This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Elon’s TeraFab. Genius Move Or Epic Nonsense?
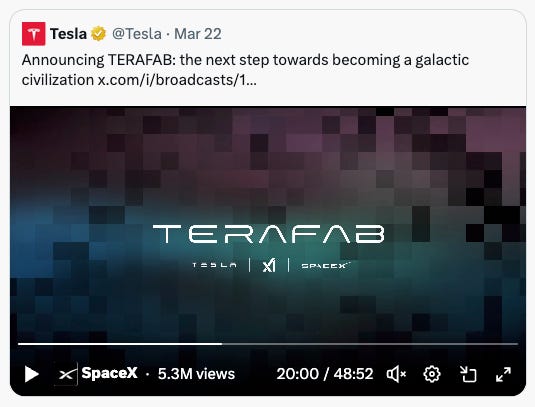
- Elon Musk announced his intention to build a leading edge, so-called TeraFab, in Austin Texas because TSMC & Samsung are unwilling to expand capacity quickly enough
- He intends to produce terrestrial chips for his Tesla cars and Optimus robots and space chips so that he can offer free flights to Saturn when the time comes
- No timeline, no process technology, no experience, no employees no worries. He’s got new physics & will do a bunch of wild and crazy things along the way. For sure…
2. SNPS, CDNS. Babies Out With SaaSpocalypse Bathwater Or Fair Game?
- SNPS & CDNS currently trade at the same levels they were at three years and two years ago respectively.
- Both companies were namechecked twice by Jensen Huang last week as example of companies whose products are needed now more than ever. NVIDIA recently invested $2 billion in SNPS
- The WSJ is now reporting that Elliott has taken a multi-billion dollar stake in SNPS. We all know what that means!
3. Arm Just Blew Up Its Business Model & Wall Street Loved It.
- Arm has formally entered the chip-making business with the Arm AGI CPU, for agentic AI infrastructure, delivering more than 2x performance per rack compared with x86 platforms
- Developed with lead partner Meta, with other customers and leading ODMs committed for production, the Arm AGI CPU is backed by strong support from the global ecosystem
- Arm was up over 16% in overnight trading. There’s officially a new CPU kid on the block.
4. Pharma Foods International (2929 JP): Profit Guidance Raised
- Management has adjusted FY July 2026 guidance after 2Q results that were in line with our expectations. Sales guidance has been lowered slightly while profit guidance has been raised.
- In 2Q, sales growth accelerated, selling expenses were reduced and the company got out of the red. Profits should increase further in 2H.
- The upward revision to profit guidance has cut the projected P/E ratio for this fiscal year from 20.4x to 13.6x.
5. TechChain Insights: Himax (HIMX) Q&A — Automotive Display Dominance Meets Edge AI and Photonics
- Automotive core: ~40% global display driver IC share; automotive now 50% of revenue, with TCON growing ~50% YoY and double-digit 2H26 growth guided from new project ramps.
- Non-Driver expansion: WiseEye edge AI, LCoS microdisplays, and co-packaged optics nano-optics target AI PCs, AR glasses, and data center silicon photonics – meaningful revenue contribution expected from 2027.
- Solid financial foundation: $258M net cash, $140M operating cash flow, ~31% gross margins; structural margin upside expected as high-value non-driver mix grows over the medium term.