
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
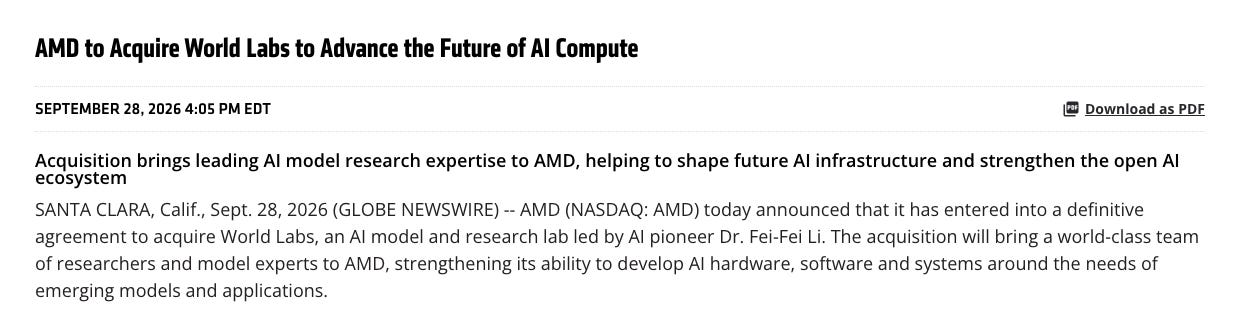
1. AMD Acquires World Labs In $8.2 Billion, All Stock, Deal. Smart Move!
- AMD today announced that it has entered into a definitive agreement to acquire World Labs, an AI model and research lab led by AI pioneer Dr. Fei-Fei Li.
- The all-stock transaction is valued at approximately $8.2 billion and is expected to close by the end of 2026, subject to regulatory approvals and other customary closing conditions.
- The move gives AMD a front row seat to monitor the evolving compute requirements as World Models replace LLMs for applications in physical AI, aka robotics.
2. Bill Gates AI Doomsday Warnings On The Ezra Klein Show. Key Takeaways & Full Transcript
- Its ability to empower a bioterrorist to kill hundreds of millions, exists today. A cyber attack ability that scrambles all bank accounts, shuts down the electric grid, that exists today.
- In the next few years, we cross over thresholds for accounting, legal work, telesales, tele-support, where 24 hours a day in every language with infinite trivia capability and no urgency.
- AI makes nuclear weapons look like nothing. We said we would engage and we crossed those thresholds and there was complete silence.
3. Ezra Klein’s Extended Interview With Jensen Huang Was Just Pure Gold. Key Takeaways, Full Transcript
- Customer service on the phone, that job is precisely the task. And so in those cases it could be automated away.
- At the beginning of this year, it was 70%, maybe higher, closed model tokens and 20% open model tokens. And now it’s running at about 70, 30 the other way
- If, when we test our models, it gets out and damages the world, then the answer is we have to shut the labs down because the damage is too great.
4. TechChain Insights Q&A: What Makes an AI Rack Hard to Build: Rails, Integration and Switches
- What makes an AI rack hard to build: a rail qualified into the tray, rack integration to an operator’s own design, and a switch engineered around a bought-in chip.
- King Slide’s monthly revenue is 3.6x January’s and runs 10.5% above what 2026 consensus needs; Accton helds its rate; Wiwynn is on pace with July low and August high.
- Inside the tray, Lotes and Elite Material told us customers keep raising high-speed data requirements and laminates must lose less signal: the spec every part is designed against.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
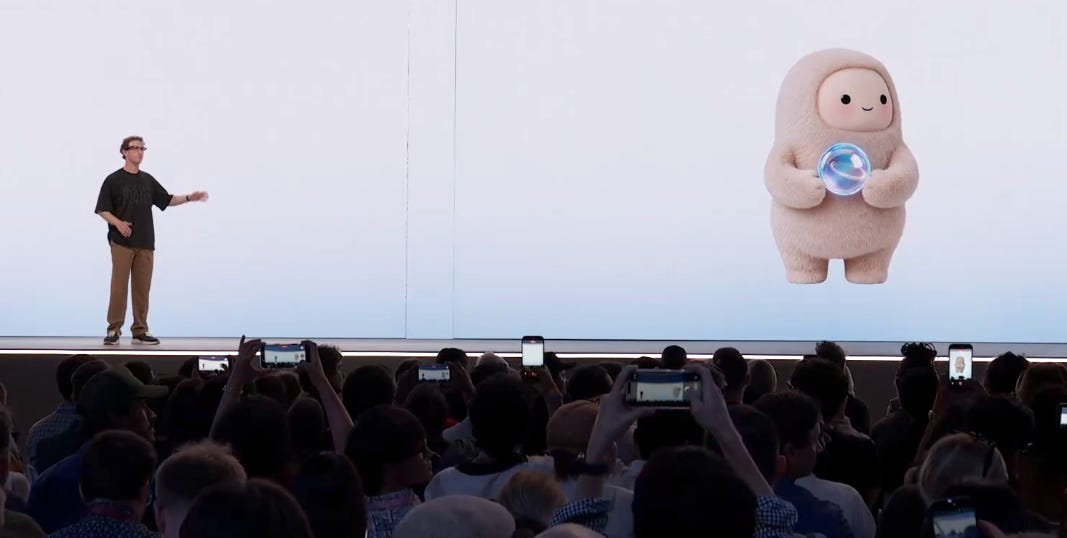
1. Meta Connect 2026 Keynote. Key Takeaways & Full Transcript
- Meta is shifting its primary focus from the Metaverse to delivering personal superintelligence, driven by its newly launched AI personal agent, Muse (and its underlying model family, MuseSpark).
- Monetization & Ecosystem: Muse is offered free with a generous token allowance; Meta plans to monetize by taking a small transaction fee from agent-led commercial actions.
- Meta showcased its next-generation Meta VR Glasses, a lightweight VR/mixed-reality device weighing just 100 grams (less than one-fifth the weight of Meta Quest 3).
2. Taiwan Dual-Listings Monitor: TSMC Premium Still Near Two-Year Lows; ChipMOS Premium Tops Its Band
- TSMC: +12.2% Premium; Below -1 SD Band; Long the ADR Spread
- ChipMOS: +3.6% Premium; Above +1 SD Band; Short the ADR Spread
- UMC: +0.2% Premium; Within Historical Range; No Active Trade Signal
3. CDNS @ Deutsche Bank 20th Annual Technology Conference. Key Takeaways & Full Transcript
- CDNS had a record $8.1 billion backlog exiting Q2, with a Current Remaining Performance Obligation coverage ratio of ~58%, providing high visibility into revenue over the next 12 months.
- CDNS launched an agentic AI flow (including ChipStack, RapidFire, Veristack, InnoStack, and AuraStack), which bridges the engineering bottleneck by automating complex tasks like RTL code generation and test bench creation.
- Due to a projected 30-40x increase in design workload over the next 5–6 years, customers indicate willingness to spend >50% of a human designer’s cost on automation, tokens, and tools
4. Google Cloud CEO Thomas Kurian @ Goldman Sachs Technology Conference. Key Takeaways, Full Transcript
- Google Cloud has 17 product lines with more than $1 billion in revenues and their customers on average exceeded their commitments by more than 50%.
- They have also seen more than 2x QoQ and YoY growth in the number and value of $100 million to $1 billion deals, >300 customers each with $100 million-plus commitments.
- The size of our TPU business is more than twice that of the next-largest hyperscaler. Our payback period on AI servers in aggregate is less than two years.
5. TechChain Insights Management Q&A: Topco Scientific Sells the Picks & Shovels Chip Fabs Use Up
- Topco says 2nm, A16 and advanced packaging raise both the amount and the value of material each wafer consumes, and it is adding adhesives, films and carriers for chip stacking.
- Topco co-owns factories with Shin-Etsu to keep that supplier selling through it, and offers smaller Taiwanese suppliers a shared route into overseas fabs.
- Materials revenue rose 22.7% in the first half while plant-building fell 0.9%, and July and August ran 39.5% above 2025. The shares trade at 18.3x 2026 earnings.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Silicon Wafers & The Looming Leading Edge Supply Crisis
- We are upgrading our existing facilities and any discussions with customers at this point are based on the capacity that we believe is possible as a result of such upgrades.
- Demand is likely to exceed supply for more than three years, because of such supply constraints. In terms of the price level, prices would need to be dramatically higher.
- We have no plans whatsoever to restart the Yoshinogari project. At current price levels, it is not viable. All costs are rising now, with Japan potentially headed for more inflation
2. AMD @ Goldman Sachs Communacopia + Technology Conference 2026. Key Takeaways & Full Transcript
- AMD raised its 2030 Server CPU Total Addressable Market (TAM) projection from $60 billion to $220 billion, targeting >50% market share as it scales multi-threaded architectures like “Venice”.
- Shifting from isolated CPU/GPU/FPGA product roadmaps to a combined Data Center Roadmap Steering Group. Hardware and software trade-offs are now evaluated holistically to deliver full rack-scale system solutions like Helios.
- AMD targets a >60% CAGR in Data Center revenue and >80% CAGR in AI Data Center revenue over its strategic timeframe, driving overall company growth above 35% annually.
3. NVIDIA @ Goldman Sachs Communacopia + Technology Conference 2026. Key Takeaways & Full Transcript
- NVIDIA reaffirmed its confidence in delivering 70% year-over-year revenue growth for the coming year, noting unconstrained demand exceeds 100%.
- While software coding remains primary high-ROI use case, Huang highlighted cybersecurity as the next massive application, with NVIDIA deploying swarms of Nemotron models for red-teaming (bug finding) and blue-teaming (patching)
- NVIDIA is actively working with the financial sector to position its high-utility GPU platforms as durable, asset-backed collateral for institutional financing. Seem like the strategy is working well, for now…
4. Jensen Huang Chats With President Trump @ The All In Summit. Key Takeaways & Full Transcript
- Frontier AI Labs: Pausing, pacing, those are all the voluntary things that they could do if they feel that their company is out of control.
- President Trump: And I’m telling you, it’s all a hoax. The data centers are great and they make people wealthy and they make states wealthy
- Jensen Huang: I’d rather help everybody succeed instead of taking a slice out. And so we would go up as far as we need to but as low as possible.
5. Satya Nadella @ The All In Summit. Key Takeaways & Full Transcript
- Nadella argues the industry must address AI risks through classic, rigorous engineering practices: transparent chain-of-thought (CoT) tracking, strict behavioural auditing and independent, third-party testing rather than “cozy arrangements”.
- Nadella wants broad industry interoperability standards (e.g., externalising memory/harnesses from specific models and creating unified KV cache standards across models) so customers can switch between models without losing their data.
- While continuing its deep strategic partnership with OpenAI, Microsoft is simultaneously building its own native AI models and adopting heterogeneous chip infrastructure (NVIDIA, AMD, internal silicon, and OpenAI’s custom silicon)
6. TechChain Insights Q&A: Kinik Automating Its Plants to Add Advanced-Node Capacity Ahead of Schedule
- Kinik says its biggest challenge is accelerating factory expansion and automating production lines against a labor shortage, so it can deliver capacity ahead of schedule into high demand.
- The capacity plan is dated: 12 inch wafer capacity goes from 330,000 pieces a month to 400,000 by the third quarter, all of the addition high grade reclaim.
- Concentration at the leading node helps a high end supplier: gross margin reached 37.6% in the first half of 2026 against 32.5% for 2025 and 31.3% for 2024.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. AMD @ Citi Global TMT Conference. Key Takeaways & Full Transcript
- On the CPU side, after a supply constraint, we have been increasing supply. We expect the second‑half CPU business to expand more than 80 % year‑over‑year,
- CPU will continue expanding more than 70 % next year though it will still remain supply‑constrained
- We just updated our TAM opportunities to more than $220 billion from $25 billion in 2025. That is how significant the expansion has been.
2. KLA Corporation (KLAC) @ Citi Global TMT Conference. Key Takeaways & Full Transcript
- KLA’s annual revenue grew 12% in 2024, 17% in 2025, and is on track for low-20% growth in 2026. Operating profits have expanded by ~400 basis points over this timeframe.
- I think growth rates into 2027 are probably in a similar range, maybe higher. Our backlog is very strong. We just disclosed our backlog of $12.6 billion in our 10-K
- KLA’s share of advanced packaging inspection/metrology market rose from ~2% in 2023 to roughly 7%–8% in 2026. This business is growing 70% YoY (~$1.1 billion), roughly 2x market growth rate.
3. TechChain Insights: Walking SEMICON 2026 Showed the Fab Is the First Buyer of Taiwan’s Robot Parts
- The fab is the first buyer of Taiwan’s robot parts: smart manufacturing was SEMICON Taiwan 2026’s largest zone, up 20% against 6% for advanced packaging.
- Labor drives the orders: TSMC has about 20 fabs under construction and calls construction workers a limiting factor, while ASE lists labor among six packaging challenges.
- TSMC will release its packaging-equipment automation specs and simulation software free in 4Q, which lowers the entry bar for local automation makers.
4. Seagate Technology (STX) & Citi Global TMT Conference. Key Takeaways & Full Transcript
- Demand-Supply Mismatch: Demand for high-capacity hard disk drives (HDDs) is outstripping supply. Rather than narrowing, the gap between supply and demand is widening.
- Seagate is focusing on increasing exabytes through technology transitions rather than manufacturing higher unit volumes. They are targeting at least a 25% exabyte CAGR over the next 2–3 years.
- Seagate plans to begin qualifying its 3rd-generation HAMR 50TB drive in roughly four quarters (mid-2027), representing a subsequent 25% capacity jump.
5. GlobalWafers Q2 2026 Earnings Review & Full Transcript
- GlobalWafers last month reported second quarter revenues of NT$15.2 billion, up 8.8% QoQ but down 5% YoY. Gross margin was 20.6%, flat sequentially but down 5.2 pp YoY
- AI infrastructure remains main growth driver, supported by higher capital spending and continued growth in agentic AI inference and cloud‑edge integration. Memory supply remains tight; LTAs provide better demand visibility.
- Our H1 gross margin was 20.7 %, -5.5 pp YoY. This mainly reflects pricing agreed during last year’s weak market, as well as higher qualification and ramp‑up costs at our new sites.
6. Taiwan Supply Chain Signals: Wistron & Quanta Drive AI Server Revenue Jump; Memory Sales Level Off
- Wistron and Quanta drove most of the chain’s August revenue growth, about 80% of the sequential increase, while notebook-heavy Inventec and Compal fell below their own seasonal pattern.
- Memory revenue held July’s level rather than extending it: the six names grew 2.7% MoM after +32% in July, and Nanya was flat against +26% last August.
- Chip designers ran well ahead of seasonal: MediaTek’s revenue grew 32% MoM against 3% last August, unexplained in its filing, and Alchip’s custom AI chip revenue grew again.
7. GlobalFoundries Q2 2026 Earnings Review & Full Transcript
- GlobalFoundries reported second quarter 2026 revenues of $1.786 billion, up 6% YoY, up 9.8% QoQ and perfectly in line with the top end of the guided range
- Gross margin came in at 29.9% (non- IFRS), handily beating guidance of 27.4% at the midpoint. GFS forecasted current quarter revenues of $1.885 billion, +5.5% QoQ and +11% YoY.
- CID accounted for ~16% of Q2 revenue. At $277 million, it was +20% QoQ and +62% YoY, the seventh consecutive quarter of double-digit YoY growth. Wow!
8. Kyndryl @ Citi 2026 Global TMT Conference. Key Takeaways & Full Transcript
- At spin-off, commercial terms mandated Kyndryl purchase $4B of IBM hardware/software content annually. Kyndryl reduced this to under $2B last fiscal year by transitioning customers to buy directly from IBM
- Revenue generated with AWS, Google Cloud, and Microsoft Azure grew from $0 at spin to over $2B last year, driven by 30,000 employee cloud credentials.
- The U.S. segment delivered 5% revenue growth for two consecutive quarters, driven by mission-critical system management, application modernization, and new customers across state government accounts (e.g., DMV digital modernisations).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
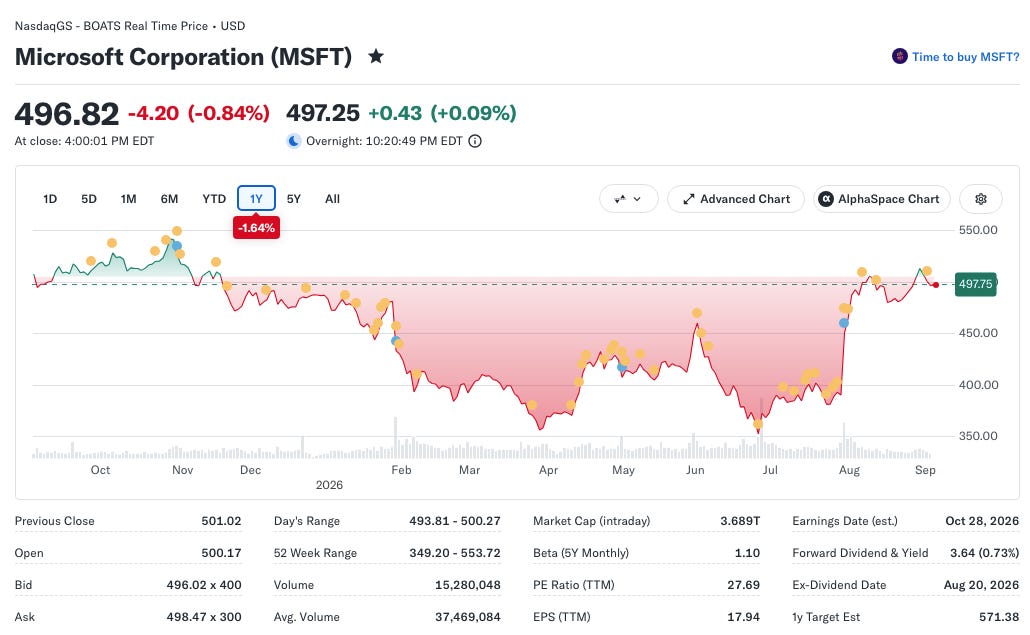
1. Microsoft @ Deutsche Bank Technology Conference. Key Takeaways & Full Transcript
- Two viral blog posts by Satya Nadella over the summer suggest a tops-down change in Microsoft’s AI deployment strategy
- Microsoft is investing $2.5 billion & deploying 6,000 engineers into a new division, Microsoft Frontier Company, to help manage its AI deployments to enterprise clients globally
- There are going to be areas where we are very complementary and partner very, very closely with AI frontier labs. Then, there might be areas of overlap competitively.
2. Intel @ Deutsche Bank Technology Conference. Key Takeaways & Full Transcript
- Intel 18A progressing past internal yield milestones and 14A defect-density yields tracking at levels unseen since Intel’s 22nm era. Not entirely sure that latter comparison is a good thing!
- Formal commitment to high-volume manufacturing (HVM) for the 14A process node in 2028, backed by the release of the 0.9 Process Design Kit (PDK) in October 2026.
- The EMIB-T Advanced packaging business is on track to generate multi-billion dollars per customer annually by 2028–2029 at 40% gross margins and 30% operating margins.
3. iEdge Singapore Next 50: Portfolio Capacity Keeps Rising
- The iEdge Singapore Next 50 comfortably supports S$50-100m index products today, and about S$171m with optimised sampling that excludes the five least liquid names.
- Strict full-replication capacity reached about S$97m as of 10 July 2026, up 75% since September 2025, as aggregate constituent turnover rose from S$134m to S$261m per day.
- The ceiling is set by a thin tail of property and hospitality names, so an ETF launch or the remaining S$2.6bn of EQDP money would lift it.
4. Salesforce Opens The AI Floodgates With Cloudforce. But Why?
- Salesforce reported Q2 FY 2027 revenue of $11.345 billion, up 11% YoY in constant currency, at the high end of the previously guided range.
- Cloudforce, a partnership between Anthropic & Salesforce, integrates Claude into Salesforce and vice versa. Basically, Claude becomes the new user interface for Salesforce, as long as you upgrade to premium
- Benioff is betting big on Cloudforce unlocking previously unheard of value from customers’s underlying Salesforce data and that they will pay handsomely for this privilege. Let’s see…
5. Taiwan Dual-Listings Monitor: TSMC Spread Now Near Multi-Year Lows
- TSMC: +9.9% Premium; Below -1 SD Band; Long the ADR Spread
- UMC: -2.9% Discount; Below -1 SD Band; Long the ADR Spread
- ASE: +2.4% Premium; Within Recent Historical Range; No Active Trade Signal
6. TechChain Insights Q&A: AI Chips Cannot Ship Until Chroma’s Machines Pass Them
- AI silicon changed what “test” is for. Larger die and stacked packages mean a late failure destroys more value, so test now decides whether parts ship.
- Chroma’s revenue doubled while gross margin fell, the signature of customers buying larger systems with more bought in content rather than more of the same instrument.
- The whole test group is priced for a multi year cycle, not a good quarter: Advantest trades at 77.0x next year’s consensus and Chroma at 44.7x.
7. Hua Hong Grace (1347.HK) Q2 2026 Earnings Report Review & Full Transcript
- Hua Hong Grace (1347.HK) reported Q2 2026 revenue of $717.5 million, up 26.8% YoY and 8.6% QoQ, a record high and easily beating the guided midpoint of $695 million
- Gross margin reached 16.5%, up 5.6 percentage points YoY and 3.5 points QoQ, clearing the top end of the 14-16% guide.
- Looking ahead, the company forecasted current quarter revenues of $775 million at the midpoint, a roughly 8% sequential increase. Gross margin is expected to be ~17%, marginally up QoQ.
8. TechChain Insights Q&A: Memory Maker Macronix Will Increase Capex by 8x on Non-DRAM Strength
- While DRAM has led the memory cycle, Macronix has budgeted NT$15.8bn for advanced capacity, roughly 8x its last four quarters of capex combined, on NOR and NAND strength.
- Second quarter revenue grew 181% with gross margin at 64.4%, earned off a written down fab that is now full. NAND supplied close to 60% of the increase.
- New capacity could carry real depreciation into a cost base that has almost none, and most tools are ds after this shortage.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. NVIDIA Capped Its Growth at 70% Because HBM Takes 3x the Silicon of Ordinary Memory
- NVIDIA guided FY28 revenue growth near 70% and Huang said demand is much greater than that. The ceiling is memory supply, not demand.
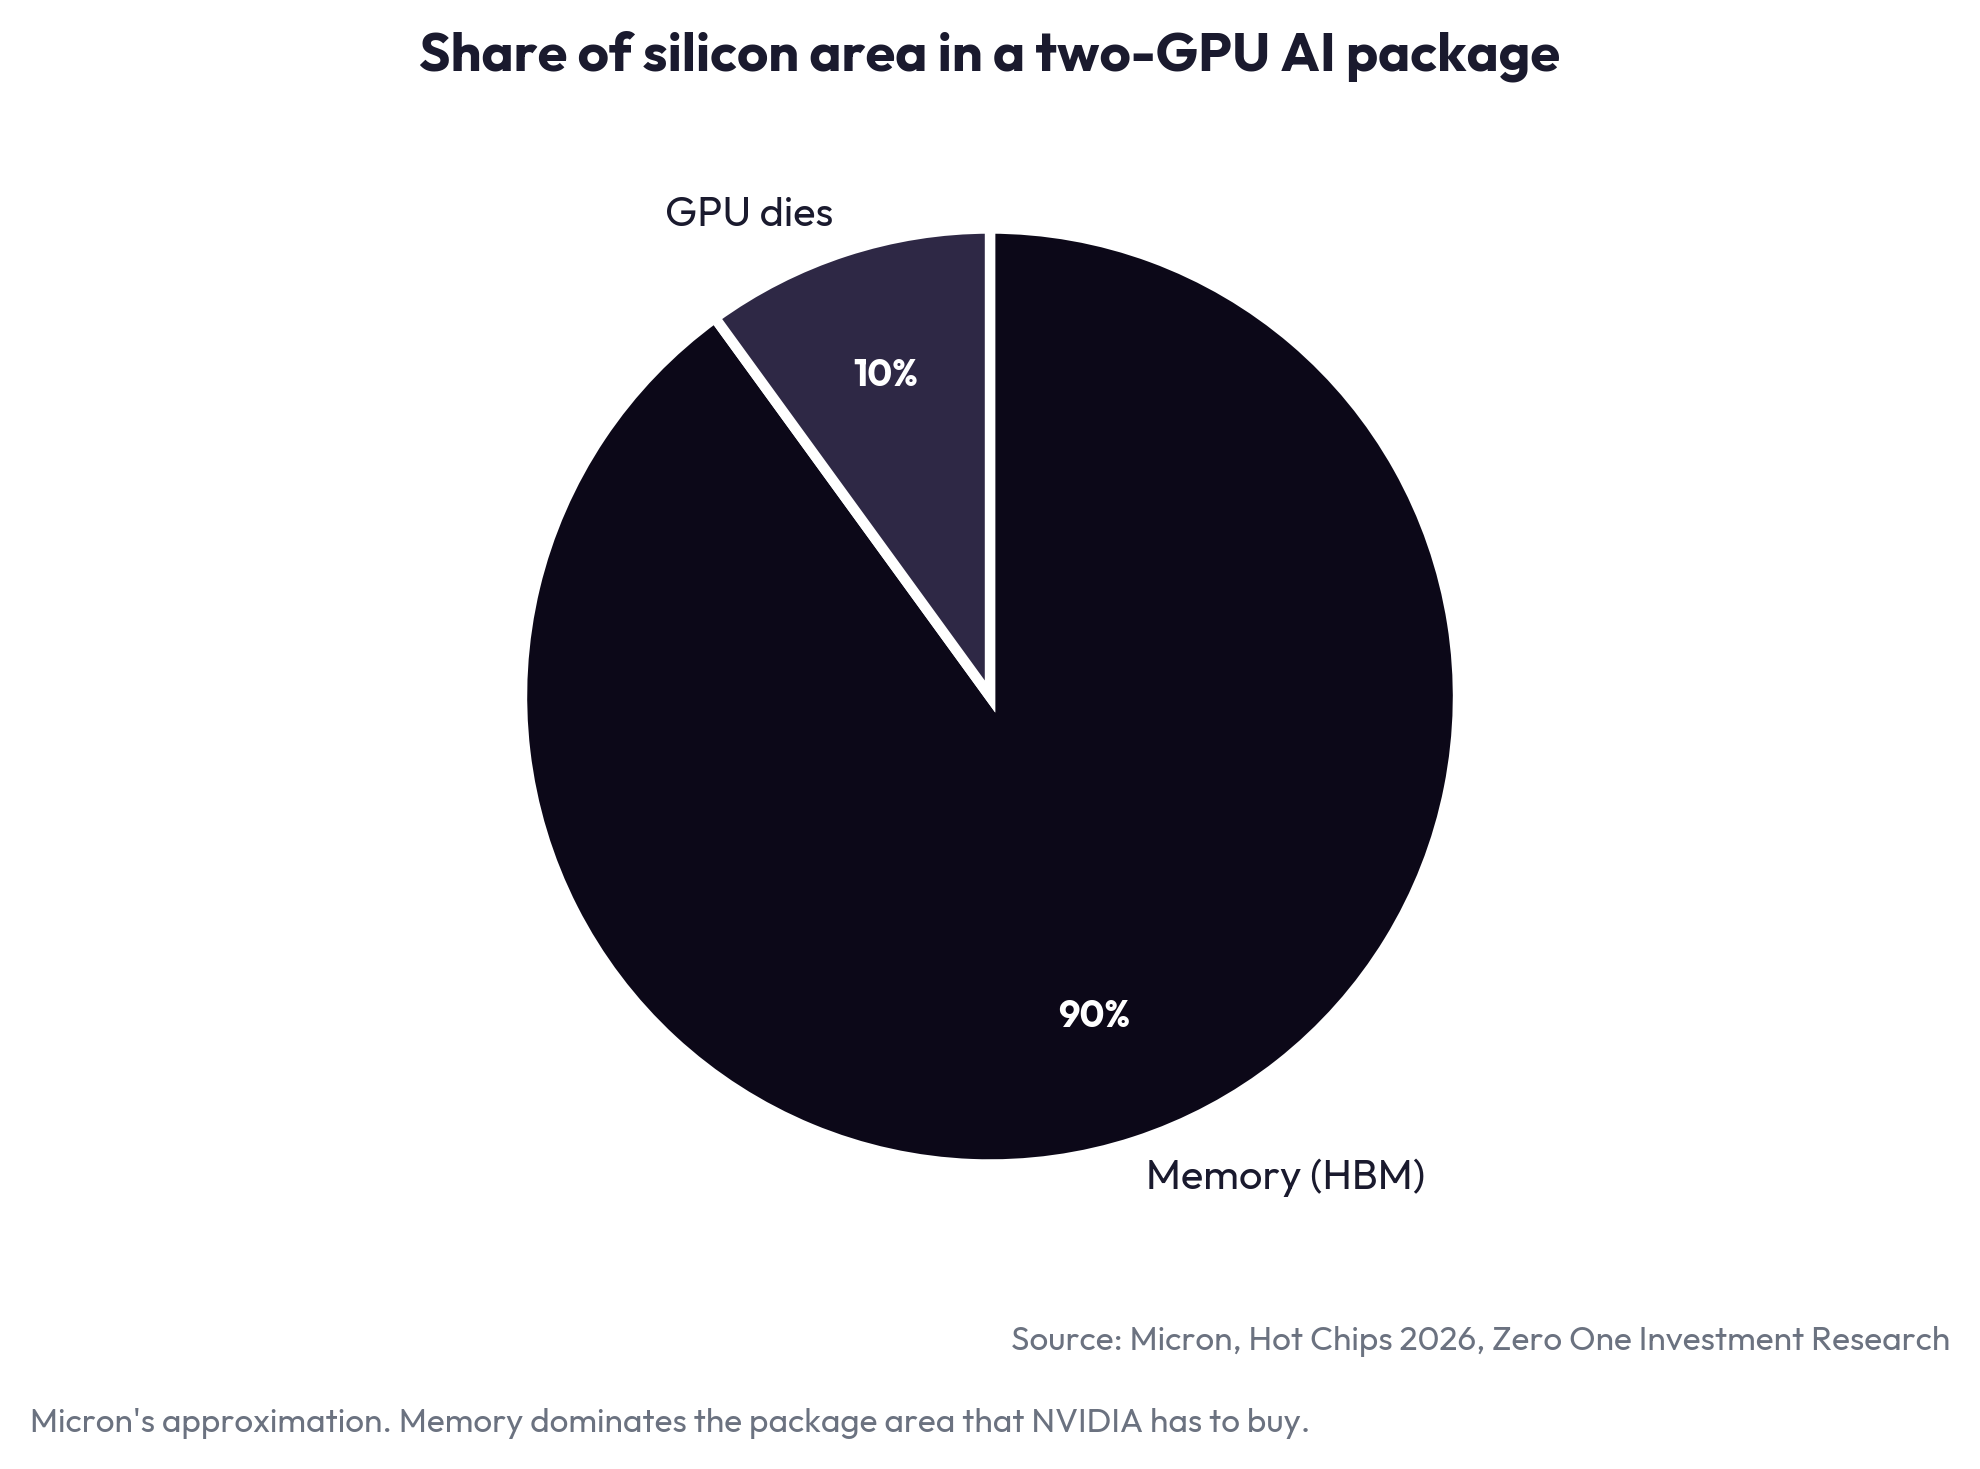
- The limit is physical. HBM needs roughly 3x the wafer area of DDR5 per gigabyte, and is about 90% of the silicon area in a two-GPU package.
- What lifts NVIDIA’s ceiling is how they allocate wafers between HBM and commodity parts, not the price print.
2. NVIDIA Q2 2027. 2028 Supply Cannot Meet The Demand Jensen Is Paying To Create
- NVIDIA reported second-quarter fiscal 2027 results, details here. Revenue was $96.2 billion, up 18% sequentially and up 106% year over year, also blowing past the $91.0 billion guided midpoint.
- Q327 revenue forecast $108.0 billion, plus or minus 2%, +12% QoQ, +89% YoY. The company also threw in forecast for fiscal 2028 growth of 70% YoY.
- Recent announcements by NVIDIA, built around guaranteeing and backstopping investment in data centres that exclusively use their compute, suggest that much of their future demand is actually being self funded.
3. Terra Drone (278A JP): Ukrainian Subsidiaries in the Line of Fire
- Terra Drone has invested in its two Ukrainian partners, turning them into consolidated subsidiaries. It can now be regarded as an active participant in the Ukraine war.
- The company remains in the red, but the bonds with warrants issue made in July should cover capital spending through January 2030. By then, it should break even.
- At ¥14,050, the shares are approaching their May high. As a result of the financing, the PBR has dropped from 29X to 7X,
4. Silergy (6415.TT): 3Q26 Outlook: Management Remains Bullish
- Management believes Data Center revenue could exceed 20% of total company revenue in 2027.
- The discussion around Smart Power Stage (SPS) products was one of the most encouraging aspects of the call.
- Automotive Business Entering a New Growth Phase: Growth is being supported by a combination of new customers, new product categories, and geographic expansion.
5. Taiwan Supply Chain Signals: Memory Revenue Re-Accelerates While Custom AI Chip Revenue Ramps
- Memory revenue re-accelerated well ahead of its seasonal pace: the six memory names grew revenue +32% MoM after about +4% in June, roughly twice their pace in July last year.
- Taiwan’s assemblers look weaker than they are: nine of thirteen ODM, EMS and PC-brand names saw revenue fall sequentially, yet the group beat its own July 2025 decline.
- Alchip Technologies (3661 TT)‘s revenue nearly quadrupled in two months and its filing reversed: after three months reporting mass-production declines, it reported growth, the only commentary change in our universe.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Applied Materials Q3FY26. Greater & Greater Growth.
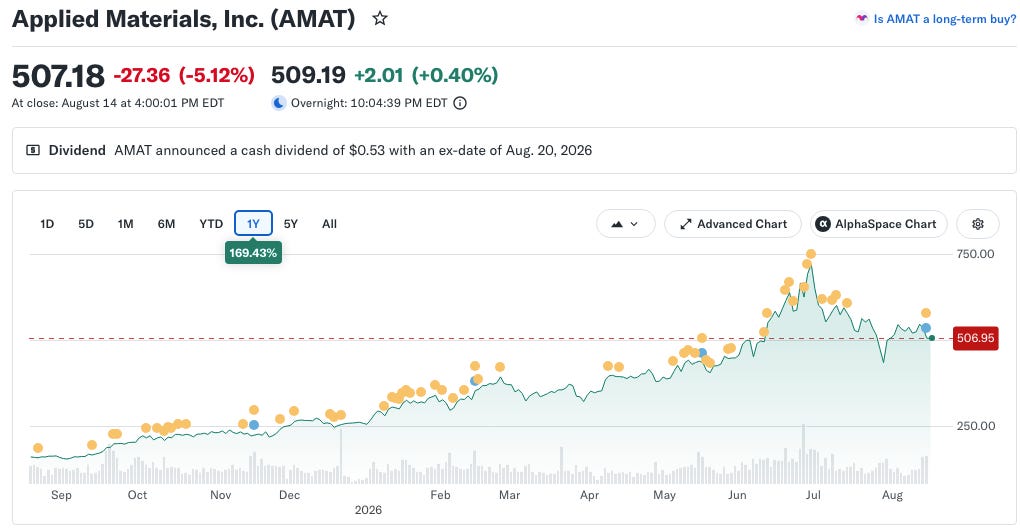
- AMAT reported record Q326 revenues of $9.1 billion, +15% QoQ (the highest QoQ growth in the company’s history), +25% YoY, all while handily beating the guided midpoint of $8.95 billion.
- Non-GAAP GM increased to 50.4%, +40 basis points QoQ and +150 basis points YoY. Operating income was a record $3.10 billion, with EPS of $3.50, also a record.
- The >30 YoY growth that we highlighted last quarter – we’re saying now that it’s greater than that but we don’t want to guide our Q1 at this point
2. SMIC Q2 2026. Record Quarter & “AI Companion Chip” Demand Is Enormous
- SMIC last week reported second quarter revenues of just over $3 billion, up 19.7% QoQ, up 36% YoY and handily beating the forecasted 15% growth at the midpoint.
- Gross margin was 25.3%, up 5.2 percentage points QoQ and up 4.9 points YoY. The significant improvement here was also attributed to both ASP increases a more favourable product mix.
- SMIC’s AI companion chip demand is enormous, we pulled forward shipments and increased this significantly. In this report we said the increase, on a comparable basis, should be around 40%.
3. IBM Q2 2026. Was The Revenue Miss Destruction Or Deferral?
- IBM’s earnings preannouncement last month sent the company’s share price into a tailspin that wiped out more than $68 billion in market capitalization, their largest single-day percentage decline since 1968
- Rather bizarrely, the revenue miss was in their software segment, under the transaction processing umbrella, which is traditionally seen as their strongest, most resilient revenue stream
- After much valiant explaining in the prepared remarks and during the Q&A session, our instinct is to accept management’s view that the miss was revenue deferral and not revenue destruction.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Cerebras Q2 2026. Messy Numbers But What Did You Expect?
- Core revenue was $209.8 million, up 103% year over year. Core cloud and other services revenue was $127.7 million, +287% YoY. Core hardware revenue was $82.1 million, +17% YoY
- Year over year, core gross margins improved substantially. Q2 core gross margin was 40.6%, approximately 940 basis points higher than Q2 2025.
- Core operating margin was negative 16% compared to negative 42% a year ago, an improvement of approximately 2,600 basis points year over year.
2. Micron @ KeyBanc Technology Leadership Forum. Key Takeaways & Full Transcript
- Micron has far broader & deeper levels of engagement with key customers than ever before. This will continue to develop, especially with the advent of custom HBM4E
- Strategic customer agreements (SCAs) ,of which there are now sixteen, come with $22 billion of cash and cash-like commitments, of which $18 billion was just cash alone
- Aggregate memory demand continues to increase. There’s no sign of any letup in the supply-demand mismatch for DRAM, the current situation will persist through calendar year 2027, at least
3. Lenovo Q1 FY26/27. Key Takeaways & Full Earnings Call Transcript
- Lenovo (HKSE: 992) reported first-quarter fiscal 2026/27 results with revenues reaching an all-time quarterly high of US$26.9 billion, up 43% YoY, and up 25% QoQ
- Adjusted net income, jumped 176% YoY to US$1.075 billion, crossing the US$1 billion milestone for the first time ever.
- Earlier, the company communicated that they want to achieve $100 billion yearly revenue in two years. With the strong momentum in Q1, they are now ahead of that schedule.
4. AMD @ KeyBanc Technology Leadership Summit. Key Takeaways & Full Transcript
- Server business grew more than 50% in Q126, grew more than 70% in Q226. Expect 80% growth in Q3 and Q4, and then at least 70% growth next year.
- AMD’s data center business, inclusive of AI, forecasted to grow “much more” than 100% next year
- AMD’s ambition is to get to >50% share of a server CPU TAM which they estimate will amount to $220 billion by 2030
5. Monday Q2 2026. The SaaSpocalypse Continues…
- Monday.com reported Q2 2036 revenue of $364.6 million, up 22% year over year and about $9 million above the high end of the guided range issued back in May.
- Non-GAAP operating income was $61.1 million, representing a 17% margin, versus the 13 to 14% guide. This compares to 15% in the year ago quarter
- For the full year 2026, Monday projected total revenue of $1.47 billion, +20% YoY, but a far cry from the 50% CAGR of the previous five years.
6. TechChain Insights Q&A: What Server Rack Specialist Chenbro Sees in the AI Buildout
- The unit of sale in AI infrastructure is moving from the server box to the rack; Chenbro targets rack and cooling products above 10% of revenue within five years.
- AI rack assembly is heading to Southeast Asia: Chenbro’s newly approved Vietnam plant takes volume, while a Dallas site near-shores sensitive US cloud provider programs from 2H27.
- AI capex is lifting general purpose servers too, and the industry’s main constraint to higher revenue is capacity, not demand, right now.
7. Atlassian Q426. A Phoenix Rising From The SaaSpocalypse Ashes?
- Atlassian reported Q4 2026 revenue of $1,766 million, up 28% YoY, flat sequentially but up roughly 6% above the high end of the guided range from back in April.
- Quarterly cloud revenue accelerated to $1,213 million, up 31% YoY, and a full 5.5 points above the ~25.5% cloud growth management had guided for the quarter.
- Despite posting a 2027 forecast that has revenue growth decelerating from 26% to 13%, the company’s share price soared 35% post earnings. Is the SaaSpocalypse over already?
8. TechChain Insights Q&A: Chip Designer Ambiq Seeing New Processor Paradigm Emerging in Wearables
- The ultra-low-power chip is moving from co-processor to main processor in wearables; Ambiq says customers already adopt Apollo5 as the primary system processor.
- Voice is the first generative AI workload that fits within a wearable’s power budget, and on-device video analysis is a full silicon generation behind it.
- Chips are now chosen on total system power including software and AI models, which is why edge silicon vendors increasingly ship their own developer stacks.
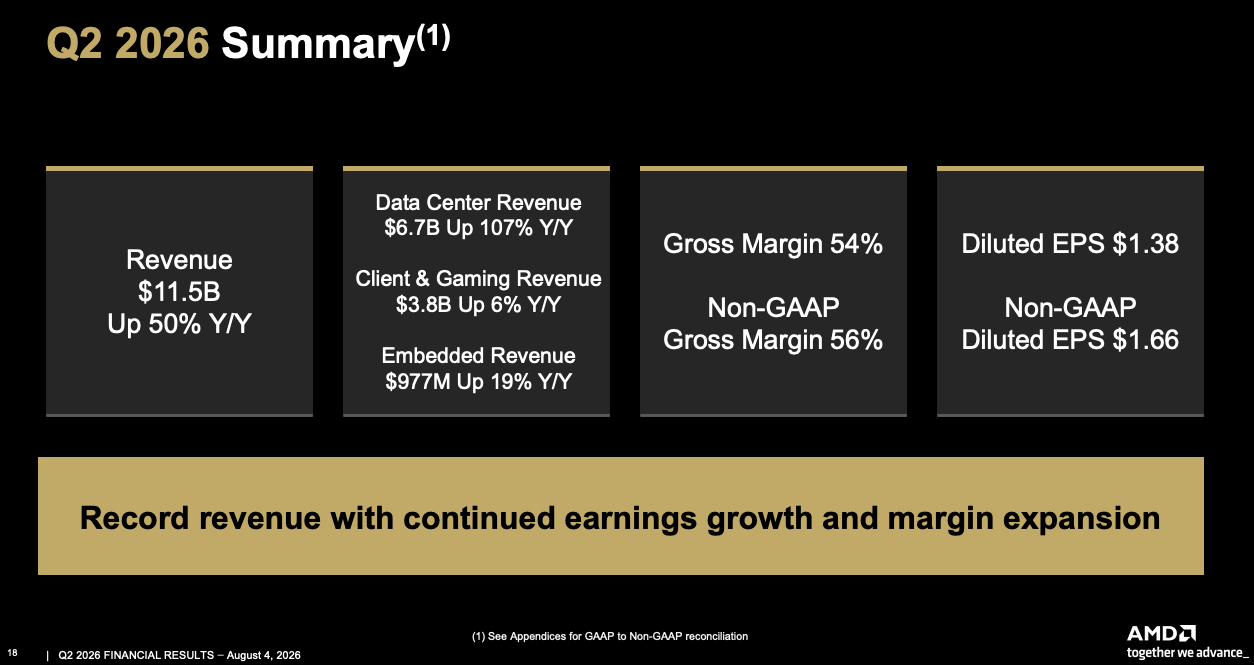
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. AMD Q2 2026. Onwards & Upwards With Beats, Raises, Data Centre Doublings & TAM Expansions
- AMD reported Q2 2026 revenues of $11.5 billion, up 50% YoY, up 13% QoQ and marginally ($36 million) beating the high end of the guided midpoint.
- Looking ahead, AMD forecasted current quarter revenues of $13 billion at the midpoint, up 12.7% QoQ and up 41% YoY.
- Revenue growth now expected to “substantially exceed” the prior long-term target of more than 35%, and EPS expected to “significantly exceed” the prior $20 annual target within the strategic timeframe.
2. Figma Q2 2026. Is The Writing On The Wall?
- Figma reported Q2 2026 revenues of $370.1 million, up 48% YoY and up 11.0% sequentially from $333.4 million in Q1 2026.
- Gross margin expanded 250 basis points sequentially to 85% non-GAAP, which management attributed directly to the first full quarter of AI credit revenue.
- Despite the beat-and-raise report, Figma’s share price fell ~15% on the news. Investors still remain to be convinced that their AI monetization strategy can really succeed in the long term.
3. Taiwan Tech Weekly: DRAM Strands US$1bn of Apple Chips; Customers Now Book 2030 Capacity
- TSMC is holding about US$1bn of finished Apple processors it cannot package for want of DRAM, and first-half smartphone processor shipments fell 15% year over year.
- Memory revenue rose 305% in the first half against 45% for logic; WSTS raised its 2026 industry forecast to US$1.655tn, growth of 108%.
- Winbond’s customers are pressing for supply contracts running into 2030, SanDisk has sold about two-thirds of its fiscal 2028 output, and Nan Ya PCB approved its largest ever plant.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
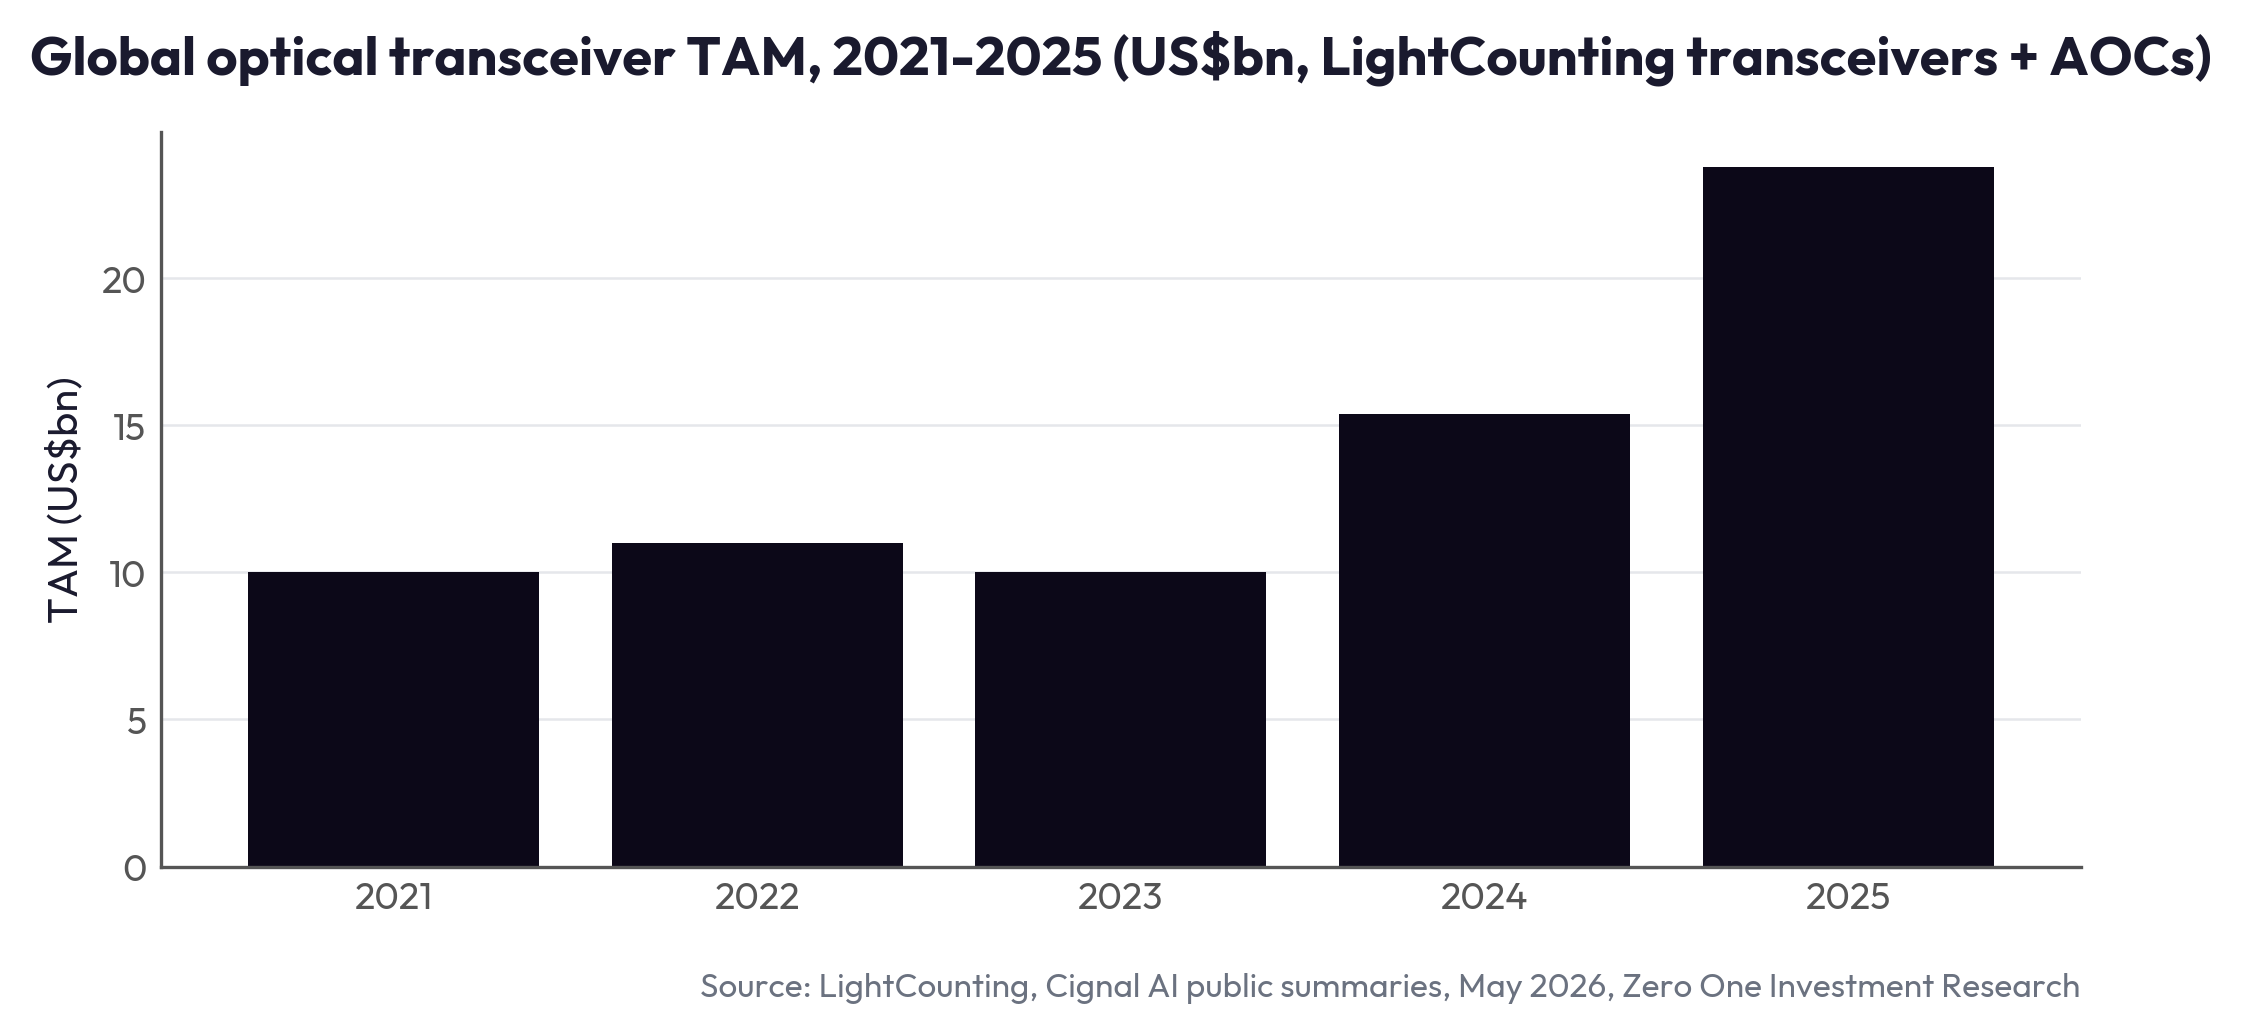
1. China Optoelectronics: Powering AI’s Voracious Bandwidth Needs
- A-Share optoelectronics names hold the largest single-country share of merchant optical transceivers; Innolight leads globally at CNY38.24bn FY25 revenue, with Eoptolink next at CNY24.84bn.
- AI has multiplied demand: Big-5 hyperscaler capex reached US$353bn in 2025, 2026 plans sum to roughly US$790bn, and the market is in year one of the 1.6T generation.
- The module leaders trade at roughly 27x forward earnings, the cheapest layer of their own supply chain; upstream chip, DSP, and EMS peers run 29-52x.
2. Intel Q2 2026. Doubling Down On 14A, But Is It Too Little, Too Late?
- Intel last week reported second quarter revenues of $16.1 billion, up 25% YoY and up $1.8 billion above the guided midpoint.
- Non-GAAP gross margin was 41.8 percent, approximately 280 basis points better than guidance and up 12.1 point YoY.
- Intel now fully committed to high volume ramps of 14A in 2028, one year after threatening to pull the plug entirely without paying external customers, which they still don’t have..
3. Taiwan Tech Weekly: NVIDIA Guarantees Its AI Landlords; Quanta Raises Asia’s Biggest GDR
- NVIDIA lined up US$625bn of AI financing in one week, from OpenAI’s Ohio lease to Hut 8’s Texas campus; the cost of insuring its debt rose the most on record.
- Macronix’s gross margin reached 64.4% and CXMT raised US$8.6bn, evidence memory pricing power kept climbing even as Korea’s chip stocks swung double digits in both directions.
- Quanta raised US$2.2bn in Asia’s largest tech GDR, ASE lifted 2026 capex to US$10.5bn, and MediaTek raised its 2027 AI ASIC share target to 15-20%.
4. Keyence (6861 JP): Not Threatened by AI
- A rebound in demand from China and the weak yen supported June quarter sales and profit growth. But further yen weakness seems cannot be assumed.
- AI contributes to factory automation, but cannot replace the granular knowledge of the company’s sales-engineers.
- The shares have rebounded to within 4% of their early May high. At 35X our EPS estimate for FY Mar-28, they look reasonably valued.