
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
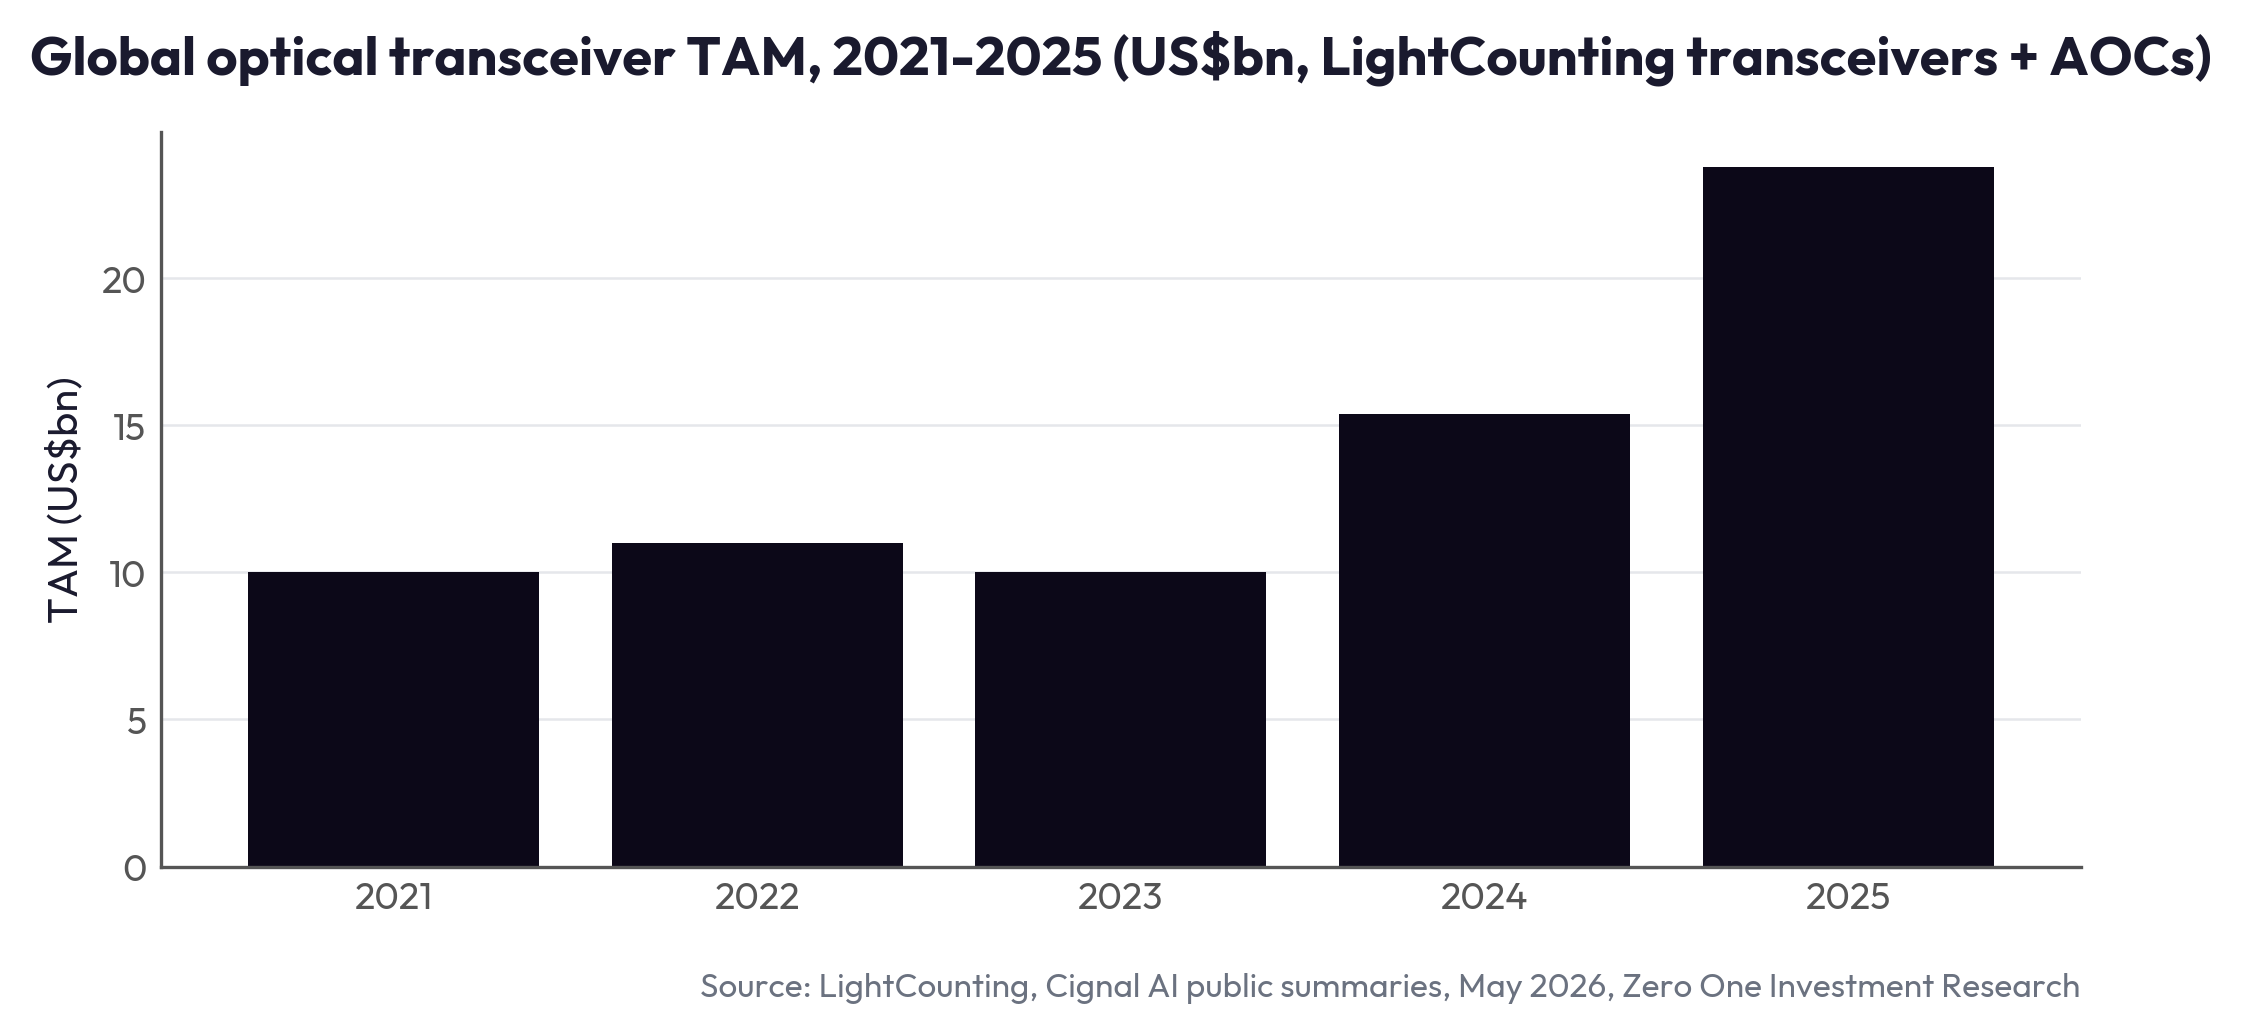
1. China Optoelectronics: Powering AI’s Voracious Bandwidth Needs
- A-Share optoelectronics names hold the largest single-country share of merchant optical transceivers; Innolight leads globally at CNY38.24bn FY25 revenue, with Eoptolink next at CNY24.84bn.
- AI has multiplied demand: Big-5 hyperscaler capex reached US$353bn in 2025, 2026 plans sum to roughly US$790bn, and the market is in year one of the 1.6T generation.
- The module leaders trade at roughly 27x forward earnings, the cheapest layer of their own supply chain; upstream chip, DSP, and EMS peers run 29-52x.
2. Intel Q2 2026. Doubling Down On 14A, But Is It Too Little, Too Late?
- Intel last week reported second quarter revenues of $16.1 billion, up 25% YoY and up $1.8 billion above the guided midpoint.
- Non-GAAP gross margin was 41.8 percent, approximately 280 basis points better than guidance and up 12.1 point YoY.
- Intel now fully committed to high volume ramps of 14A in 2028, one year after threatening to pull the plug entirely without paying external customers, which they still don’t have..
3. Taiwan Tech Weekly: NVIDIA Guarantees Its AI Landlords; Quanta Raises Asia’s Biggest GDR
- NVIDIA lined up US$625bn of AI financing in one week, from OpenAI’s Ohio lease to Hut 8’s Texas campus; the cost of insuring its debt rose the most on record.
- Macronix’s gross margin reached 64.4% and CXMT raised US$8.6bn, evidence memory pricing power kept climbing even as Korea’s chip stocks swung double digits in both directions.
- Quanta raised US$2.2bn in Asia’s largest tech GDR, ASE lifted 2026 capex to US$10.5bn, and MediaTek raised its 2027 AI ASIC share target to 15-20%.
4. Keyence (6861 JP): Not Threatened by AI
- A rebound in demand from China and the weak yen supported June quarter sales and profit growth. But further yen weakness seems cannot be assumed.
- AI contributes to factory automation, but cannot replace the granular knowledge of the company’s sales-engineers.
- The shares have rebounded to within 4% of their early May high. At 35X our EPS estimate for FY Mar-28, they look reasonably valued.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. TSMC Q226. You Put All The Truth Together, It’s Not The Truth
- In US dollar terms, TSMC’s second quarter revenue was $40.20 billion, which increased 33.7% year-over-year and increased 12.0% from the previous quarter.
- Current quarter guidance for revenues between US$44.6 billion and US$45.8 billion. At 1 US$ to 32 NT$, gross profit margin is expected to be between 65% and 67%
- Supported by their robust technology differentiation and the broad customer base, TSMC now expects full-year 2026 revenue growth of slightly above 40% YoY in US dollar terms. Yikes!
2. AI Supply Chain Revenue Signals: The Memory Surge Settles While AI Server Demand Broadens
- AI’s compute build re-accelerated broadly in June: chain revenue growth stepped up to +61% YoY across server ODMs and infrastructure, with even ASUS’s rebound crediting AI servers rather than PCs.
- Memory’s price surge settled to an ordinary pace: sequential revenue growth cooled to +7% MoM from April’s +32%, though company commentary says prices keep rising and cycle has not turned.
- AI demand is now tightening component supply at the consumer end: a casing maker blamed shortages for weak notebook shipments, and consumer PCs still lag the AI cohort.
3. Taiwan Tech Weekly: Intel Pulls Chip Orders Back From TSMC to Its Own Leading-Edge Fab
- Intel last week moved most of its Nova Lake compute tiles back to its own 18A process from TSMC, and won packaging designs at Google and AWS.
- TSMC last week raised its full-year revenue growth guide past 40% for the second time this year, while guiding near-term margin lower as its 2nm ramp scales.
- In memory, HBM4 shipments, record wafer price hikes and multi-year contracts pointed to a still-tight supply side across the DRAM stack.
4. Taiwan Dual-Listings Monitor: Multiple ADR Spreads Due for a Bounce
- TSMC: +12.0% Premium; Below -1 SD Band; Long the ADR Spread
- ASE: +0.0% Premium (ADR at Parity); Long the ADR Spread
- CHT: -1.3% Discount; Below -1 SD Band; Long the ADR Spread
5. ASML Q2 2026. Massive Capacity Expansion Plans Leave Markets Unmoved. But Why?
- ASML Q226 net sales were €9.3 billion, up 6.4% from the €8.7 billion ASML booked in Q126 and up 21.2% from the €7.7 billion it reported a year earlier.
- ASML expects Q3 2026 total net sales between €11.0 billion and €12.0 billion, and a gross margin between 55% and 57%
- ASML announced 30% capacity increases for both low-NA EUV and DUV immersion tools for delivery in 2027. They are investigating a further 30% increase for both for 2028. Yikes!
6. Taiwan Tech Weekly: AMD Wins First Training Chip Order Outside NVIDIA; NVDA Prepays Amkor’s Capex
- AMD committed up to US$5bn to Anthropic against an order for up to 2 gigawatts of MI450 accelerators, the first training-scale commitment to a rack that is not NVIDIA’s.
- NVIDIA prepaid Amkor US$1.5bn to expand Arizona packaging and planned US$5bn to US$10bn of dark fiber, paying cash upfront for what it does not manufacture.
- Korea’s supply answer to a 2027 shortage is dated 2030: Samsung plans four new fabs, and SK Hynix reapproved a 7.1 trillion won expansion.
7. TechChain Insights Q&A: How Lotes’s Value Drivers Have Transformed Due to AI Demand
- Server has gone from about a quarter of Lotes’s revenue in 2023 to 55% in Q2 2026, a shift management attributes mostly to AI demand.
- AI servers add more sockets and connectors per box and push each interface faster; Lotes says a PCIe Gen6 connector sells at least 15% above Gen5.
- Bloomberg consensus sees revenue near-doubling to NT$59bn by 2028E; at ~21x forward earnings falling to ~13x, the AI ramp is largely in the price.
8. TechChain Insights Q&A: Taiwan’s Elite Material, Global Laminate Leader Behind the AI Server Boom
- Elite Material (2383 TT) is the world’s leading maker of high-speed copper clad laminate, the low-loss material inside AI server boards; AI infrastructure is now roughly 75-80% of revenue.
- The mix is climbing to higher M8 and M9 grades for NVIDIA Corp (NVDA US)‘s GB200 and GB300 systems, lifting price and margin; consensus sees revenue near-doubling in 2026.
- At about 49 times 2026 earnings versus Taiwan peers ITEQ and TUC at 34 to 37 times, the leader’s premium prices execution: M9 timing, pricing, and holding share.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Tech Weekly: Micron, Apple and AMD Start Funding Their Suppliers
- Micron, Apple and AMD committed a combined US$43bn-plus to the suppliers they depend on, moving the industry from ordering capacity to financing it and shifting build risk onto the buyers.
- Memory economics reached record levels: Samsung’s operating profit rose 19x, and Nanya’s gross margin hit 79.5% on flat shipments, with prices doing all the work.
- SK Hynix raised US$26.5bn for ADRs in the largest US listing by a foreign company, and the week’s selloff reversed in two sessions as money returned to memory and compute.
2. TSMC 2Q26 Preview: A Record June Lands 2Q Revenue at the Upper End of the Guide
- A record June (NT$442.68bn, +67.9% YoY) puts fully-reported 2Q26 revenue at NT$1,270.4bn, about US$40.1bn, at the upper end of the US$39.0-40.2bn guide. Revenue is settled pre-print.
- The question is now the full-year guide. First-half revenvue is up 35.6% YoY, past the “above 30%” bar; the street implies +37%, so a guide raise is partially baked in.
- Also watch whether management repeats the 2-3pp N2 margin dilution and how it frames FY27 capex. At 24.4x forward, TSMC remains relatively inexpensive.
3. TSMC (2330.TT; TSM.US): All Good News Doesn’t Mean A Good Stock Price.
- Third Quarter Revenue: US$44.6 billion – US$45.8 billion, At the midpoint: Quarter-over-quarter; (QoQ): +12% Year-over-year (YoY): +37%;
- In other words, the increase in CAPEX is fundamentally driven by AI demand.
- The shortage is mainly in AI-related mature technologies, especially: PMIC (Power Management IC)
4. Nanya Tech Signals Memory Shortage Extends Through the Second Half
- Nanya’s second quarter set a record on price, not volume: revenue rose 68% QoQ as ASP climbed more than 60% and bit shipments stayed flat, at a 79.5% gross margin.
- Management guided the third quarter to improve further and called results sustainable for several quarters, so the sequential second-half decline consensus had modelled did not survive the print.
- Nanya’s capacity response is now funded: full-year capex is guided to about NT$52bn, four times last year, and a NT$78.7bn placement lifted net cash to NT$198bn.
5. KHI (7012 JP): Production Upgrades & Drone Deal with Airbus
- KHI’s new share and CB issues will fund production upgrades while strengthening the balance sheet. Potential dilution should be in the price.
- The share price has been declining since March as overbought defense contractors were sold off. That is coming to an end. MHI has started to recover.
- Collaboration with Airbus and Eurodrone is another reminder that Japan’s defense build-up is not driven by the wars in Ukraine or the Persian Gulf.
6. Vanguard (5347.TT): June Revenue Reached a Record High.
- Vanguard June Revenue Reached a Record High, Representing the Most Significant Positive Signal.
- Q2 Revenue Was in Line with Expectations, but Not Significantly Above Expectations — This Is Consistent with the Company’s Historical Guidance Approach
- AI Applications and the Tight Supply of 8-inch Foundry Capacity Provide the Largest Upside Potential for the Stock.
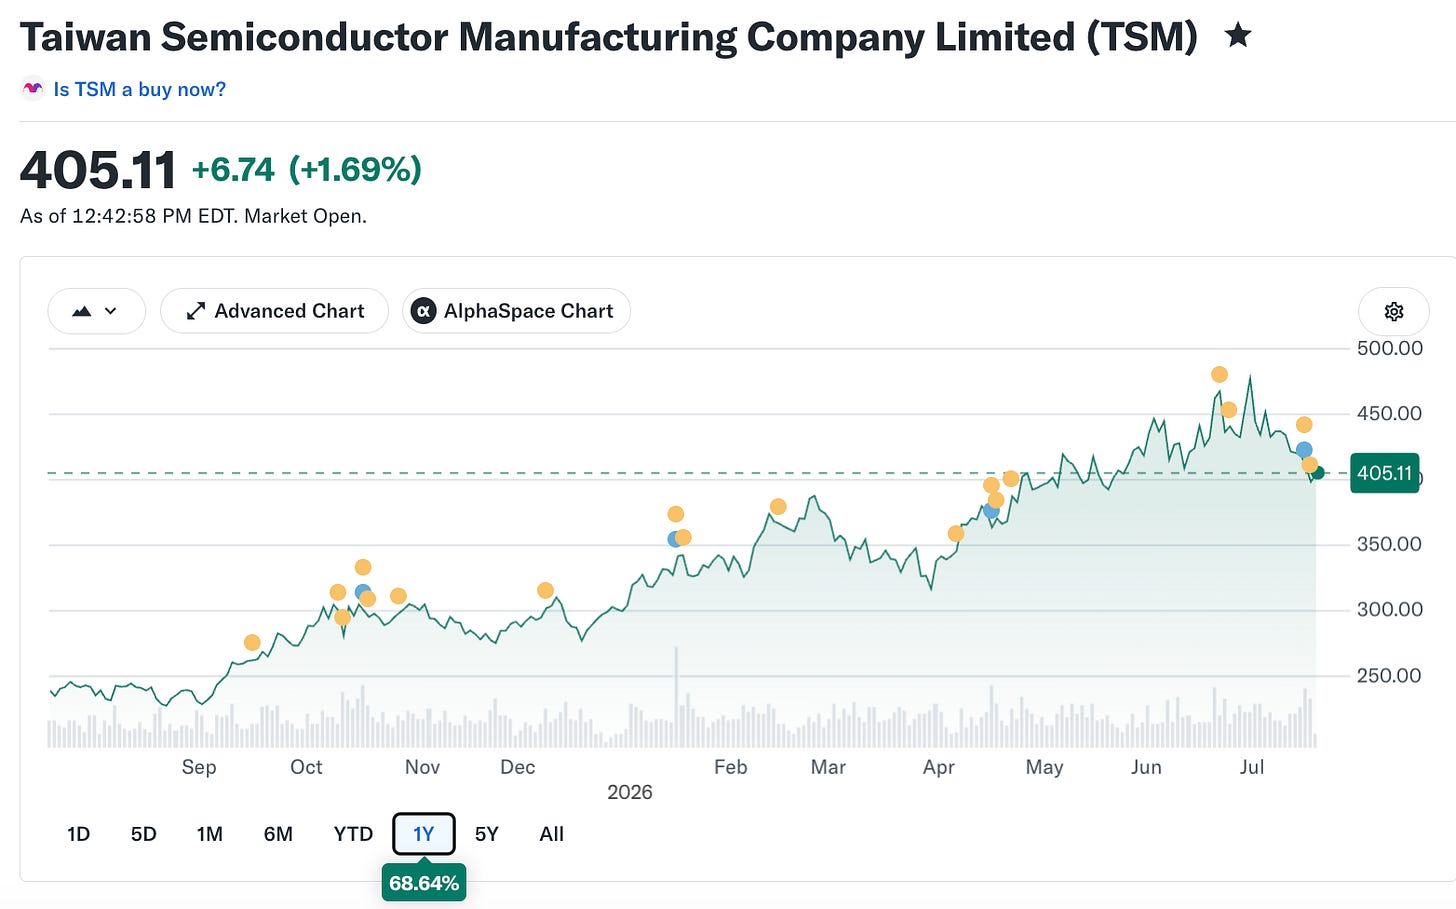
7. TSMC (2330.TT; TSM.US): Stock Prices Had Already Priced in Excessively Optimistic Expectations.
- Before the Peak, Few People Realized They Were at the Top of a Bubble.
- The recent sharp decline can be summarized by the following observations: AI is real, but the next challenge may be valuation compression.
- When evaluating the current market correction, the first step is to acknowledge a simple fact. Investors may consider waiting until pessimism has become widespread.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
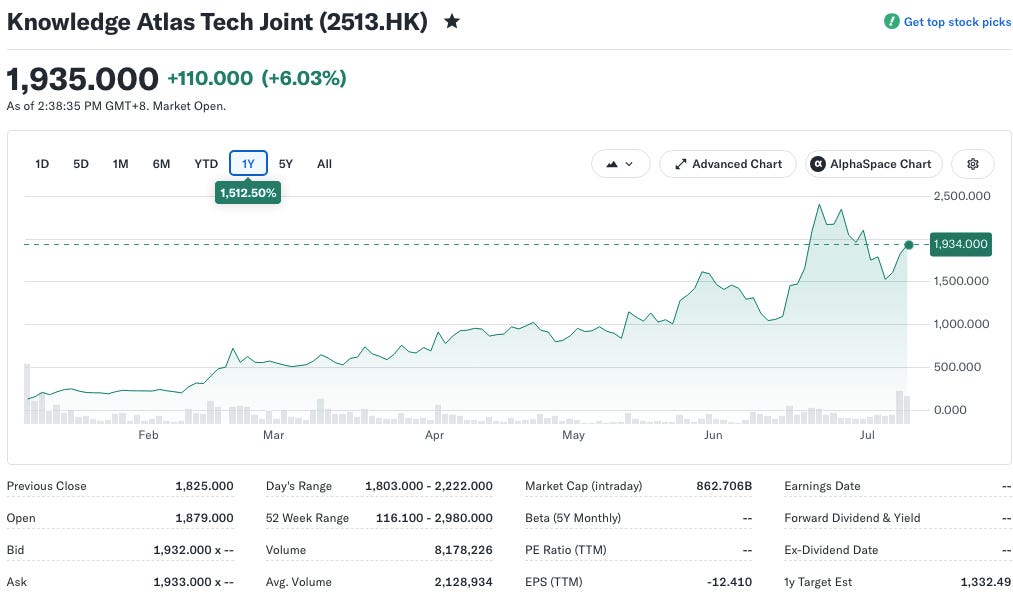
1. Zhipu & MiniMax. Six Months Into Their HK Listings, China’s AI Tiger Cubs Are Yin & Yang
- Zhipu & MiniMax both IPO’d on the Hang Seng within a single day of each other back in January & both exited their lockup expiry dates earlier this week
- Zhipu (Knowledge Atlas 2513.HK) now trades at HK$1,884 compared to its IPO price of HK$116 while MiniMax now trades at HK$259 as compared to its IPO price of HK$165
- Zhipu placed up to 19,780,000 new H shares at HK$1,588 (~13% discount) each on July 9, raising an expected gross proceeds of approximately HK$31.41 billion. Smart move.
2. Taiwan Dual-Listings Monitor: TSMC and UMC and ASE Below -1 SD Band; Long Opportunities
- TSMC: +13.5% Premium; Below -1 SD Band; Long the ADR Spread
- UMC: -8.0% Discount; Below -1 SD Band; Long the ADR Spread
- ASE: -1.9% Discount; Below -1 SD Band; Long the ADR Spread
3. Taiwan Tech Weekly: Memory’s Big Run Wobbles, But Other Supply Chain Shortages Keep Broadening
- Taiwan’s memory leaders tumbled after China’s GigaDevice warned prices had peaked, and a US class action accused Samsung, SK Hynix and Micron of colluding to inflate DRAM prices.
- A report that Meta will resell spare AI compute sparked a global chip selloff, with the Philadelphia Semiconductor Index down 6.27%, though Nomura called the shortage far from over.
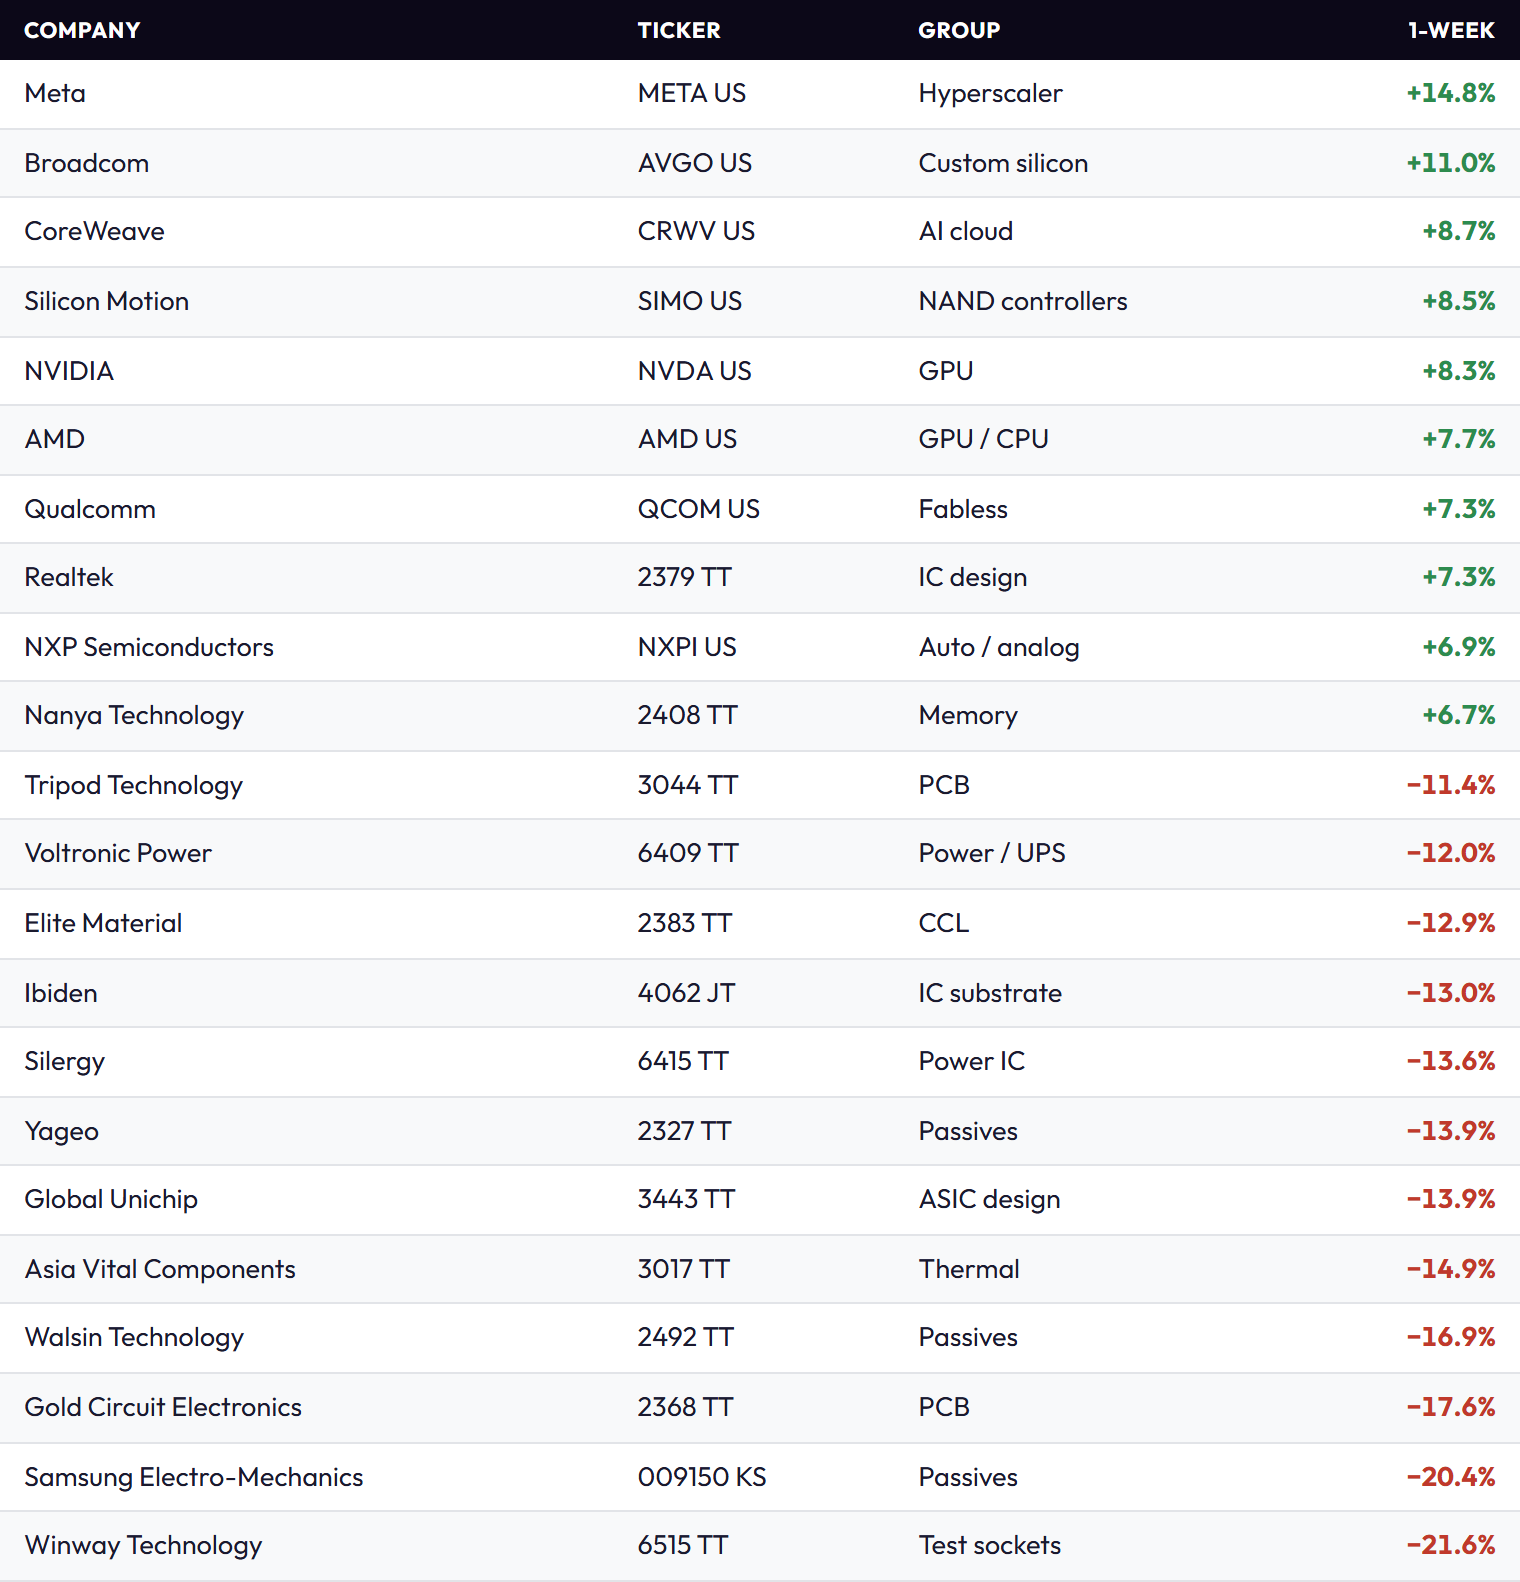
- Even so, pricing power spread to passives and timing chips, silicon-wafer and component makers led Taiwan’s gainers, and Korea pledged another US$290bn into memory fabs.
4. Sergey Brin On Model Convergence, Prompt Engineering & Transformer Evolution
- Model Convergence: capabilities that once required specialized models are increasingly handled by the main Gemini LLMs, which can now be state of the art for math and other scientific questions
- Brin admitted he is “always kind of confused as to how to prompt the models” and even the Gemini team does not know exactly where the models’ capability edges are!
- He cited chain-of-thought (”think step by step”) as an example of a technique that seemed trivial or “the dumbest thing ever” yet drove a significant jump in AI capability.
5. Silergy (6415.TT): Announced June Month Revenue Showed
- Silergy-KY (6415) announced its June 2026 revenue after market close on July 10. The nearly 38% YoY growth significantly outperformed the same period last year
- Second-Quarter revenue growth remains on track. The market’s focus will now shift from revenue growth to gross margin (GM) improvement and the company’s third-quarter outlook during the earnings conference call.
- Will EPS improve simultaneously? We believe there is a good possibility, with a relatively high probability.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Palantir CEO Alex Karp Declares War On Anthropic, OpenAI
- The Trust Deficit: Alex Karp reveals that enterprise and battlefield clients are furious with frontier AI labs over severe data caching, intellectual property theft, and a total loss of trust.
- The Sovereign Solution: Palantir’s new partnership with NVIDIA focuses on giving technical customers absolute control over their own compute, data stacks, model weights, and business alpha.
- The Application Layer Moat: Karp argues that open-source models paired with Palantir’s safe “ontology” application layer match closed-frontier performance without risking the transfer of proprietary corporate secrets.
2. Evaluating Open-Weight LLMs For Our Structured Equity & Financial Research Agent
- A field report on substituting Ollama-hosted models (GLM-5.2, DeepSeek-V4-pro, gpt-oss:120b) for Claude Opus
- The candidate open models were not usable as the agent’s main reasoning loop, and were not safe as substitutes for the verification gates, when judged against Claude Opus.
- For autonomous, gated, numerically rigorous pipeline, model selection cannot be judged on fluency or headline benchmarks. It must be judged on procedural reliability and format discipline under sustained real workloads.
3. Figma Analyst Day. No Mention Of The Claude Design Debacle.
- Last week, Figma held their annual Config together with an Analyst Day. Zero reference to the Claude Design debacle, Krieger’s board resignation or the activist letter critiques. Very disappointing
- The Config event keynote featured a slew of new product launches organized around “new creative materials” plus “intelligent tools”, an attempt to seamlessly blend design and coding
- This quarter will test whether they can transition their new AI-credit consumption model into a durable, high-margin revenue stream without cannibalizing the seat business or blowing out costs. Let’s see.
4. From Token Maxxing To Token Rationing In Just Three Months. What’s Going On?
- So if you’re not actually able to draw a direct line to how much useful features and functionality you’re shipping to your users, that trade becomes harder to justify.
- It’s actually not our engineers that are driving the token consumption. It’s a lot of the non-engineers that are doing some of those behaviors like converting PDFs into PowerPoint slides
- Microsoft Has reportedly begun canceling most of its direct Claude Code licenses, according to The Verge, instead moving engineers toward using GitHub Copilot CLI.
5. Taiwan Tech Weekly: Micron Guides Memory to US$50bn, Korea’s US$1.3tn Bet Sends Memory Shares Lower
- Micron last week reported an 84.9% gross margin and guided next-quarter revenue near US$50bn, and foreign brokers raised targets across Taiwan’s memory makers as the shortage runs past 2027.
- Foreign investors net sold a record NT$177.4bn of Taiwan stocks on June 24, even as Taiwan’s May export orders rose 47% year on year for a 16th straight month.
- Korea unveiled a combined US$1.3tn, decade-long chip plan, and Samsung and SK Hynix shares fell on June 29 as investors weighed heavy capex against near-term cash returns.
6. TechChain Insights: Silicon Motion’s Enterprise SSD Ramp Begins, Five Hyperscalers Queued
- AI servers need 8-10x the storage of standard servers, and with nearline hard-drive lead times past 52 weeks, hyperscalers are shifting to enterprise SSDs, the storage market’s fastest-growing segment.
- Silicon Motion’s MonTitan platform — the SM8366 Gen5 flagship and Gen6 SM8466 — sells controllers, reference designs, and licensable firmware to NAND makers and drive builders, a merchant model.
- Quarterly revenue has more than doubled in a year, from US$166.5m in 1Q25 to US$342.1m in 1Q26, with two customers ramping and five tier-one hyperscalers queued for 2H26.
7. Astroscale (186A JP): New Capital, New Phase of Growth
- ¥30.6 billion in new capital raised through stock and CB issues, equivalent to 3.8x equity, 95% of total assets, and 3X this year’s projected net loss.
- Gross margin has turned positive. Order backlog 2.6X midpoint of this fiscal year’s project income guidance. Outlook for new orders improving with Japan’s defense build-up.
- The share price has dropped back more than 60% from its recent peak to where it was in early April, presenting a new long-term investment opportunity.
8. UMC (2303.TT, UMC.US): The 2nd Round Wafer Price Increase Within 2026.
- The Second time Price Increase Scheduled for September in 2026.
- On the 12-inch side, United Microelectron Sp Adr (UMC US) is collaborating with Intel to develop 12nm manufacturing capacity. This joint project is expected to enter pilot production in 2027.
- We believe United Microelectron Sp Adr (UMC US)’s share price still has room to move higher.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
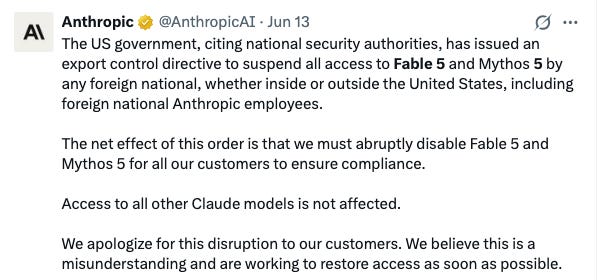
1. Anthropic’s Latest Misstep Is A Game Changer For Sovereign & Open Source AI
- Amazon’s discovery of a Fable 5 jailbreak led to swift U.S. export bans on foreign nationals, forcing Anthropic to pull its flagship models entirely offline.
- The severe federal intervention highlights the immense risk of relying on centralized U.S. cloud providers, pushing foreign governments to rapidly fund domestic, sovereign AI infrastructure
- Heavy-Handed software export controls will likely backfire on the administration by driving global enterprises and developers toward resilient, unrestricted open-source alternatives, such as those from China
2. Cerebras Q1 2026. Solid Opening Quarter, But Margins Are A Puzzle
- GAAP quarterly revenue of $193.4 million; record core revenue of $191.3 million, up 92% from a year ago
- Announced a multi-year deal with OpenAI for 750MW valued at more than $20 billion and launched multi-year partnership with Amazon to bring Cerebras’ fast inference to AWS
- Temporarily renting their own systems back from an existing customer (G42?) which will depress core cloud and other services margin temporarily by 10 to 15 margin points. Interesting move…
3. Micron Q326 Earnings. Margin Paradise
- Micron reported Q3 2026 revenues of $41.5 billion, up 74% sequentially and up 346% year over year, representing their fifth consecutive quarterly revenue record.
- Consolidated gross margin was 84.9%, a company record, doubled YoY and up 10 pp sequentially, driven primarily by higher pricing as well as continuing strong execution and favorable mix.
- FQ4 revenue forecasted at a record $50.0 billion, plus or minus $1.0 billion; gross margin to be approximately 86.0% and EPS to be a record $31.00 per share +/- $1.00.
4. Taiwan Tech Weekly: Packaging Scarcity Locks In to 2030, Intel Builds New Capacity to Compete
- Advanced packaging scarcity hardened from lead times into contracts: TSMC signed its first publicly disclosed 10-year deal, while tool makers Grand Process and Scientech booked orders to 2030.
- Intel responded late in the week, hiring SK Hynix’s former chief executive to build its own packaging-focused foundry and reportedly teaming with UMC on advanced processes.
- Memory and passives led Taiwan and Korea higher, with Winbond, Nanya, Murata and Yageo up 29% to 40% as memory and MLCC prices climbed.
5. Accenture Et Al. Welcome To The ConsultAgeddon!
- Accenture reported Q326 revenue of $18.7 billion, +3% YoY. Operating margin +20 basis points to 17.0%, diluted EPS of $3.80, a +9%. FCF $3.6 billion
- Share price dropped 18% the following day and is now ~60% from its 52-week high. Its publicly listed peer group companies have also experienced similar drawdowns, acting like SaaSpocalypse companies
- Introducing ConsultAgeddeon: the moniker for companies whose consulting work is teaching their customers how to leverage AI so that they won’t need them in the future..
6. TechChain Insights Q&A: GUC’s AI Boom Is Now a CPU Story, Testing the Next Bottleneck
- Global Unichip (3443 TT) is Taiwan’s leading ASIC (application-specific integrated circuit) design-service company, with TSMC (2330 TT) as its largest shareholder.
- GUC has become a leveraged play on US hyperscaler custom silicon. Cloud is now 81% of sales and the US 68%,
- Management did not name its CPU customers, but the public record points firmly at Google.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Is Anthropic Eating Figma’s Lunch?
- Mike Krieger, Instagram co-founder & now Anthropic’s Chief Product Officer, “building at Anthropic Labs”, resigned from the Board of Figma on 4/14/26.
- According to an open letter from activist Findell, on 4/17/26, Anthropic released Claude Design, a product which directly competes with Figma. This pattern of events raises serious corporate governance concerns.
- The Information claims that Figma was originally partnering with Anthropic on Claude Design, but pulled the plug at the last minute as the extent of the competitive threat became clearer
2. The Figma SaaSpocalypse. Are We There Yet?
- In Q1 2026, revenue grew 46% year-over-year to $333 million, accelerating from 40% last quarter and 38% in Q3.
- Net dollar retention rate also increased to 139%, our highest rate in over 2 years. This is up 3 percentage points from last quarter.
- In Q226, we expect revenue of $349 million, implying 40% YoY growth. For FY2026, we expect revenue of $1.425 billion, implying 35% growth YoY, up $55 million from prior forecast
3. Silergy (6415.TT): Price Increase Effective July 1st.
- Following the recent IC price increases implemented by Texas Instruments (TXN US), Silergy Corp (6415 TT) has also begun raising prices for its IC products.
- Based on our understanding, automotive PMICs (Power Management ICs) and server-related products are likely the primary drivers behind this latest round of price increases.
- Silergy’s products typically require approximately two years to complete the qualification process, including both system-level validation and product transition procedures.
4. TechChain Insights Q&A: Himax’s Silicon Photonics Powering Nvidia’s Next Generation Chips
- Himax’s CPO entry is a manufacturing story: it supplies the precision optics — lenses, prisms, V-grooves — inside the fiber array unit, built on 15 years of nanoimprint wafer-level optics.
- Third-Party research (Hunterbrook, Ming-Chi Kuo) ties those optics to TSMC’s COUPE engine behind NVIDIA’s CPO switches, but Himax, TSMC, and NVIDIA have not confirmed it.
- Gen 1 (1.6/3.2 Tbps) ships in small quantities from 2H26 and Gen 2 (6.4 Tbps) nears validation; lower volume, higher value than displays, funded by automotive.
5. Realtek (2379.TT): Five Layers for Investment Logic.
- The Investment Logic Behind Realtek Semiconductor (2379 TT)’s Share Price Strength has several layers.
- As a result, capital has begun rotating from expensive AI-related stocks into mid- and large-cap IC design companies. Realtek fits several of the market’s favored investment themes.
- As a result, capital has begun rotating from expensive AI-related stocks into mid- and large-cap IC design companies. Realtek fits several of the market’s favored investment themes.
6. Silergy (6415.TT): Our Preferred Pick Among 8-Inch Foundries and Silicon Wafer Manufacturers.
- The Reasons Behind U.S. Weakness Are Not Necessarily the Reasons for Taiwan Weakness
- Taiwan Has Its Own Industry-Specific Catalysts and The companies we have been following closely: Silergy Corp (6415 TT), Vanguard Intl Semiconductor (5347 TT) and Globalwafers (6488 TT).
- This Is Actually a Positive Signal for Silergy if we observe: The broader Taiwan market remains positive, U.S. equities close lower but Taiwan doesn’t follow, Capital continues flowing into AI-sectors.
7. MHI (7011): Autonomous AI Via Preferred Networks
- Development of AI with Preferred Networks provides a Japanese alternative to the unreliable USA., which has just cut off foreign access to advanced Anthropic models.
- Successful H3 rocket launch reduces uncertainty. Positive spin on Global Combat Air Programme kicks that dented can down the road.
- Share price down 32% from early March peak to 31x FY Mar-27 EPS guidance as of June 13 close. Time to have another look.
8. Vanguard (5347.TT): The 2nd Wave of 8″ Wafer Price Increase for 2H26~1Q27
- The AI boom has attracted a portion of wafer capacity, driving a significant increase in overall wafer demand.
- In comparison, Vanguard’s share price likely still has considerable upside potential.
- Vanguard Intl Semiconductor (5347 TT) is focusing on the specialty market, with new products initially being shipped in relatively small volumes within specialty applications.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
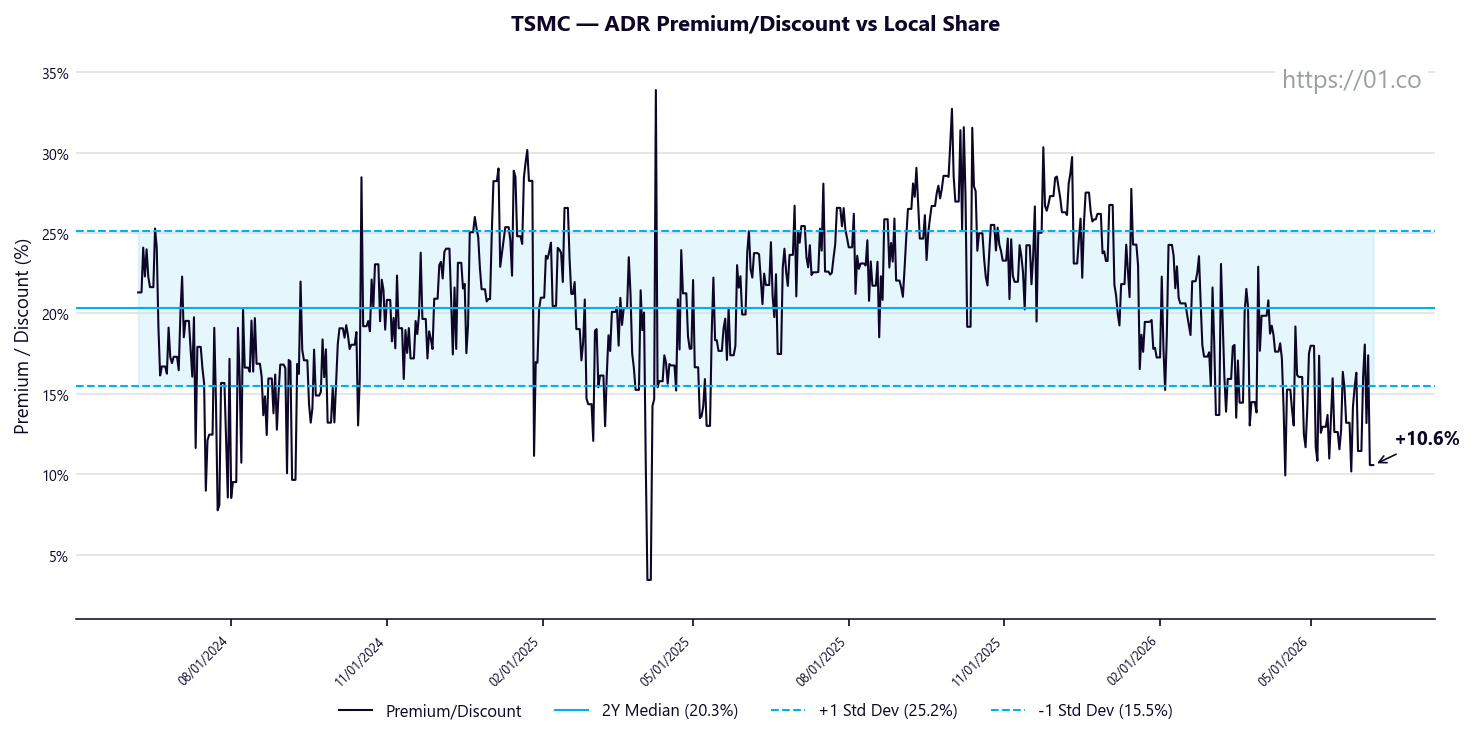
1. Taiwan Dual-Listings Monitor: Deep ADR Discounts Unlikely to Persist
- TSMC: +10.6% Premium; Fell Further on Market Weakness; But Likely to Remain Key Foundry Play for U.S. Investors
- UMC: -5.6% Discount; Below -1 SD Band; Deep ADR Discount Unlikely to Persist
- ASE: -7.1% Discount; Below -1 SD; Another Deep ADR Discount Unlikely to Persist
2. NVIDIA @ BofA Global Technology Conference 2026. Key Takeaways & Full Transcript
- Accelerated Vera Rubin Timeline: NVIDIA confirmed its next-generation Vera Rubin architecture is in full production and scheduled to stand up ahead of schedule in Q3 2026
- Standalone Vera CPU Strategy: The proprietary, custom-core Vera CPU delivers 2x the performance of competitors and will be sold standalone to direct distributed agentic workflows
- Massive Supply Chain Commitments: To secure future growth through 2027, NVIDIA has locked in $124 billion in long-term purchase commitments with its manufacturing ecosystem
3. Bill Ackman on All-In: The Next Berkshire? Executive Summary & Full Transcript
- The Berkshire Hathaway Playbook: Ackman plans to transform Howard Hughes into a Berkshire-style compounding machine, using real estate cash flows to fund and scale a high-return insurance arm.
- Shift to Digital Activism: Moving away from aggressive corporate brawling, Ackman now utilizes X (formerly Twitter) as his primary medium to drive narrative, public sentiment, and market influence.
- Venture Tech Valuations: Ackman evaluates high-multiple private megacaps like SpaceX and OpenAI as venture investments, focusing strictly on team, long-term opportunity, and structural market dominance
4. Taiwan Tech Weekly: COMPUTEX Drives TSMC to Records, Then a US$1.3tn AI Selloff
- COMPUTEX and GTC Taipei drove TSMC and the TAIEX to records, before a US$1.3tn AI selloff in the U.S. sent Taiwan index futures down a record 6.65%.
- The trigger was expectations, not fundamentals: Broadcom beat but held rather than raised its long-term AI target, and a hot US jobs report killed Fed rate-cut hopes.
- Yet demand kept accelerating through the rout: Winbond, Foxconn and Aspeed posted record sales, and Apollo and Blackstone closed US$35bn to buy AI chips for Anthropic.
5. Oracle Q426. The Records Are Real, So Is The Cash Burn
- Record Financial Growth: Oracle achieved record Q4 total revenues of $19.2 billion (up 21%) and full-year fiscal 2026 revenues of $67.4 billion, driven by explosive cloud demand.
- Surging Cloud and AI Demand: Driven by massive AI training and inferencing contracts, quarterly cloud revenues soared 47% to $9.9 billion, led by a 93% spike in infrastructure revenue
- Unprecedented Backlog Expansion: Remaining Performance Obligations (RPO) skyrocketed 363% year-over-year to $638 billion, heavily boosted by $75 billion in prepaid or customer-supplied AI hardware contracts.
6. Taiwan Revenue Signals — Memory Growth Stalls While AI Servers Remain Robust
- Memory’s price surge stalled month-over-month. The median memory name’s sequential revenue growth fell from +32% in April to +4% in May, back at its no-cycle baseline.
- The PC pull-forward could be unwinding a quarter early. Acer’s and ASUS’s revenue both fell roughly 16% month-over-month, against positive seasonality, with neither company commenting.
- AI server demand is so far untouched, and it is not lifting everything. A fifth straight month of ramp, Hon Hai re-accelerating, a record TSMC month.
7. Sarah Friar OpenAI CFO. All-In Podcast Executive Summary & Full Transcript
- Record-Breaking Private Fundraising: OpenAI raised $122 billion in March 2026 to maximize strategic flexibility and fund massive future infrastructure needs, completely eclipsing historical IPO scales.
- Massive Michigan Data Center: OpenAI CEO Sam Altman broke ground on a one-gigawatt data center in Michigan, injecting $1 billion in taxes and 2,500 union jobs into the community
- Deflationary Compute Costs: Despite rising power and memory prices, rapid chip depreciation slashed token serving costs by 97% over a two-year span from GPT-4 to GPT-5.
8. Coatue @ All-In Summit: Executive Summary & Full Transcript
- The Rebalanced Unicorn Economy: Driven by AI, the unicorn economy is healthier and more balanced, shifting toward fewer companies that are each raising significantly larger amounts of funding.
- The “Magnificent Eight” Private Index: A highly diverse group of private megacaps—including SpaceX, OpenAI, and Stripe—is delivering unprecedented growth and aggressively outperforming the public market’s “Mag 7”.
- The Scale Power Law: Counterintuitively, companies worth over $100 billion have a 31% chance of a 10x return, proving that top winners are compounding faster than ever before.
9. Apple WWDC 2026 Keynote. Executive Summary & Full Transcript
- Google Gemini Collaboration: Apple partnered with Google to build its next-generation foundation models, combining Gemini’s reasoning capabilities with Apple’s Private Cloud Compute architecture.
- Major International Exclusions: Due to regulatory and privacy complexities, Apple’s flagship “Siri AI” platform will be entirely excluded from the EU and China at launch.
- Liquid Glass Interface Refinement: Addressing legibility concerns from the prior interface redesign, Apple introduced a personalization slider to let users adjust transparency from ultra-clear to tinted
10. Nvidia GTC Taipei 2026 Financial Analyst Q&A. Executive Summary & Full Transcript.
- Strategic Shift to Agentic Computing: NVIDIA announced a major transition from legacy applications to distributed AI agents that autonomously perceive, reason, plan, and act across data center nodes.
- Next-Generation Vera Rubin Architecture: With the Vera CPU built on a custom 10-IPC ARM core, the new Vera Rubin platform is engineered specifically to run massive, disaggregated multi-agent workloads efficiently.
- Robust Capital Return Commitment: Jensen Huang formalized a framework to return 50% or more of free cash flow to shareholders via buybacks and dividends indefinitely.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Intel @ BOFA Global Tech Conference 2026. Executive Summary & Full Transcript
- We had 12 layers of management; he collapsed it into six. We had over 400 vice presidents; he collapsed that to 200. We had >100,000 employees; he collapsed that <80,000.
- If you just stamped something and called it a CPU right now, it would sell. In the near term, it’s all about supply, we are ramping supply as we speak
- Our ramp in general has been quite good, mainly because 18A is making really good progress on yields month-to-month. And we’re ramping in two facilities now, Oregon and Arizona
2. NVIDIA Keynote Computex 2026. Key Takeaways & Full Transcript
- In 2023, the number of Github commits was 300 million. 2024, 400 million. 2025, 500 million. In the first few months of 2026, it has nearly tripled.”
- It used to take two hours to assemble one Grace Blackwell rack, Vera Rubin now only takes five minutes. VR supply chain twice the size of Grace Blackwell
- Launched RTX Spark, a Microsoft-NVIDIA reimagined PC, built on the N1X SoC in partnership with MediaTek. Three SKUs: laptop (RTX Spark), desktop, and the DGX Station
3. Intel Computex 2026 Keynote. Key Takeaways & Full Transcript
- It has been a year since I stepped into the role of Intel CEO. To be more precise, 14 months. I may be the first CEO who can speak Mandarin.
- We support an ample number of ports for all of your connectivity needs, unlike some of our competitors who only have one USB-C interface…
- We are excited to have Intel Xeon 6 Plus introduced at Computex. It has 288 E-cores, massive 576 megabytes of L3 cache, and is built with our Intel 18A technology
4. AMD @ BOFA Global Tech Conference 2026. Executive Summary & Full Transcript
- AMD’s data-center CPU business grew >50% YoY in Q1, and management guided Q2 CPU revenue up >70% YoY, with roughly two-thirds coming from unit expansion rather than ASP.
- TSMC supply remains tight (notably 3nm), but Ramsey suggested AMD secured more allocation from TSMC earlier than investors appreciate, while warning the “starting point” of investor expectations was too low
- On x86 versus ARM, management emphasised TCO, platform breadth (5 generations from 8-core to 256-core), the entrenched x86 code base, and a decade of RAS and security validation with hyperscalers
5. Marvell Computex 2026 Keynote. Key Takeaways & Full Transcript
- Marvell Vision: build a best-in-class, world-class, pure-play company focused on semiconductor solutions for data infrastructure that is required to move, store, process, and secure the world’s data.
- The next major wave of innovation and scale will come from the underlying connectivity of systems. As those connections move from copper to optical, they will unlock new architectural possibilities.
- Over the last decade Marvell invested roughly $22.5 billion through acquisitions. They spent $18 billion organically inside the company to develop the platform. They divested ~$4.5 billion worth of assets.
6. Qualcomm Computex 2026. Key Takeaways & Full Transcript
- AI agents becoming the true center of the digital experience. Diverse devices, including 6 billion phones, 2 billion wearables, 2 billion PCs and 500 million vehicles, will act as endpoints
- Demonstrations proved that routing tasks dynamically between the device and the cloud via a hybrid orchestrator saves up to 30%–60% in tokens and cuts costs by 4x.
- Because agents operate independently and continuously carry context forward, they demand entirely new hardware architectures. This puts a heavy premium on high-efficiency CPUs for system orchestration
7. Broadcom Q2 FY2026. The $100 Billion AI Trajectory Remains On Track.
- Massive AI Revenue Growth: Total revenue reached a record $22.2 billion, up 48% year-on-year, driven by insatiable demand for AI semiconductors which hit a record $10.8 billion.
- Long-Term Customer Commitments: Broadcom secured major AI compute and XPU partnerships with Google, Meta, OpenAI, and Anthropic, firmly underpinning their guidance of over $100 billion AI revenue for fiscal 2027.
- The AI XPU Platform Launch: Broadcom is partnering with Apollo and Blackstone to deploy a 20-gigawatt AI platform through 2028, with Apollo currently launching the first $35 billion tranche.
8. KLAC @ JPM 54th Annual TMC 2026. Key Takeaways & Full Transcript
- We talked about an environment of spending for wafer fab equipment that was roughly $140 billion plus for this year. Now it feels like there’s additional momentum there.
- Advanced packaging feels like it’s accelerating. Initially we thought the packaging market might have been somewhere in the plus 20% overall. Now I think it’s in excess of 30%.
- 2027 visibility is very good. I’ve been CFO here since 2013. I can’t recall this level of visibility into the next year in the early May timeframe.
9. Salesforce @ BOFA Global Tech Conference 2026. Executive Summary & Full Transcript
- Upgrading existing seats to our higher-end SKUs, which we call Agentforce — Agentforce for Sales, Agentforce for Service. Every time we do that upgrade, we see on average 60–80% uplift.
- Contrary to the fear that AI shrinks seat counts, seven of the top 10 deals last quarter involved customers adding new human users, i.e. licenses are increasing, not contracting
- Agentforce wins against ~10,000 competing agentic platforms because it has native access to customers’ codified workflows, CRM context, governance/permissioning built over 27 years, human handoff, and a model-agnostic backend
10. Microsoft Build 2026. Satya Nadella Keynote Executive Summary & Full Transcript
- Surface RTX Spark DevBox: A “dream machine” for local development boasting one petaflop of AI compute and 128 gigabytes of unified memory.
- The MAI Model Family: Microsoft’s new internally developed frontier models, highlighted by the 35-billion-parameter reasoning model MAI Thinking 1.
- Majorana 2 Qubit: A massive quantum computing leap delivering a qubit mean lifetime of 20 seconds to a minute—1,000 times higher than Majorana 1.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
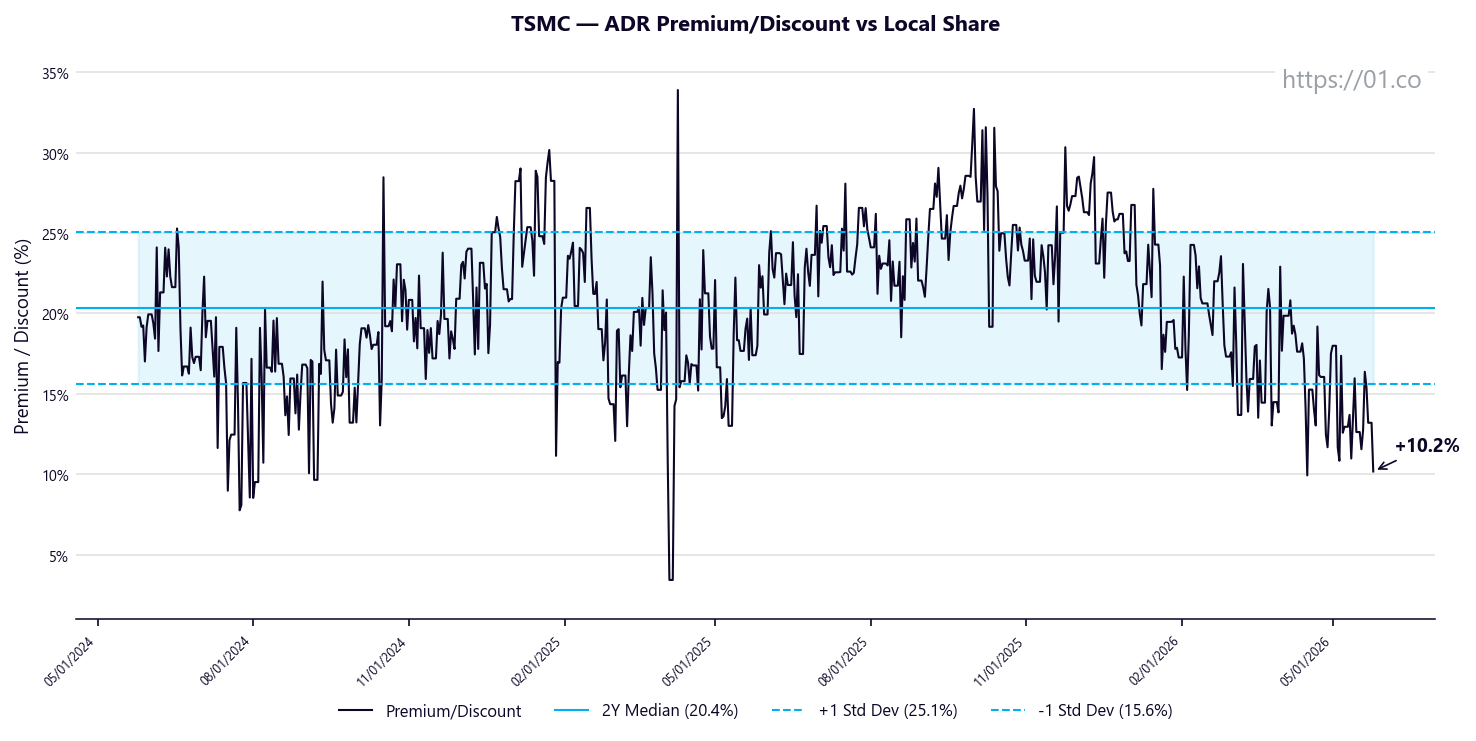
1. Taiwan Dual-Listings Monitor: TSMC, UMC, ASE and ChipMOS All Signal Long the ADR Spread
- TSMC: +10.2% Premium; Below -1 SD Band; Long the ADR Spread
- UMC: -8.3% Discount; Below -1 SD Band; Long the ADR Spread
- ASE: -11.3% Discount; Below -1 SD Band; Long the ADR Spread
2. Huawei’s “Tau Scaling Law” and “LogicFolding”. Desperation, A Genuine Breakthrough Or Both?
- Huawei introduced the “Tau Scaling Law” under which chip designers optimise for the time taken for elements of a chip to communicate, rather than for the space between transistors.
- Huawei’s next-generation Kirin SoC, due autumn 2026, will be the first commercial chip to fully adopt the resulting architecture, which Huawei is calling “LogicFolding.”
- Huawei chips designed under this framework will deliver transistor density equivalent to a 1.4nm process by 2031, three years after TSMC’s publicly stated 2028 timeline for its A14 (1.4nm) node.
3. Micron. Beware The Wrath Of YMTC
- YMTC currently has patent infringement lawsuits filed against Micron in California, Texas, Beijing, Shanghai, London, Dusseldorf & Munich.
- YMTC has also filed a complaint against Micron for false advertising, product disparagement, and unfair competition. They claim that anti-YMTC content on the chinatechthreat.com website was funded by Micron
- The US patent litigation is currently in a stalemate. The UK and German litigation could proceed much faster compared to the US, and be much more problematic for Micron…
4. Taiwan Dual-Listings Monitor: Taiwan Domestic Investors’ Relative Bullishness Is an Opportunity
- TSMC: +11.5% Premium; Taiwan Relative Bullishness is Opportunity to Long the ADR Spread
- UMC: -3.7% Discount; Persisting Discount = Opportunity to Long the ADR Spread
- ASE: -1.6% Discount; Persisting Below Zero… Another Opportunity Long the ADR Spread
5. KHI (7012 JP): Progress with Physical AI
- KHI has opened a Physical AI Center in Silicon Valley, where it will collaborate with Nvidia, Analog Devices, Microsoft and Fujitsu
- The Kawasaki Physical AI Center will first work on robotic surgery and hospital process management, then move on to semiconductors, mobility and other applications.
- This should high standards of accuracy and reliability for all KHI robotics and other AI-enabled products.
6. Salesforce Q1 FY2027. Raising Debt For Massive Buybacks: Confidence Or Delusion?
- First quarter revenue of $11.1 billion, up 13% Y/Y and 12% in CC, including $444 million Informatica contribution
- Second quarter FY27 revenue guidance of $11.27 billion to $11.35 billion, up 10% – 11% Y/Y and 10% in CC, including slightly above 4pts Informatica contribution
- Announced $25 billion accelerated share repurchase (“ASR”), with upfront share delivery of 103 million shares representing approximately 80% of total shares expected to be repurchased, final settlement in Q3 FY27
7. SanDisk @ JPM 54th Annual TMT. Key Takeaways & Full Transcript
- Three KPIs run the business, Get a fair return on the technology, dampen cyclicality via NBMs with financial guarantees, limiting to mid-to-high-teens bit growth
- First three NBM agreements (signed March quarter): $42 billion total lifetime contracted value. Five NBM agreements now signed
- SanDisk’s February 2025 Analyst Day call was that NAND would inflect in 2H25 and remain undersupplied through end 2026. Goeckeler is now extending the same conviction level through end 2027.
8. Dell’s Q127. Soaring After Hours On Massive AI Server Driven Beat & Raise
- Dell reported Q1 FY27 revenue of $43.84 billion, +88% YoY, -31% QoQ, in line with normal Q4-to-Q1 seasonality. Oh and it was also $8.6 billion above Dell’s guided midpoint
- Q2FY27 revenue guided for $44.5 billion at the midpoint, +49% YoY. Full-year FY27 revenue expected midpoint of $167.0 billion, +47% YoY
- Full-Year AI-Optimized Servers revenue expected to be roughly $60 billion, up 144% year over year
9. TechChain Insights Q&A: Where Mediatek Partner Neuralspike Sees Edge AI Demand Right Now
- NeuralSpike, an independent edge-AI partner whose optimization tools are chip-agnostic, still defaults to MediaTek’s Genio because of its edge AI ecosystem partnership and faster Mediatek engineer access shortens development.
- MediaTek investing in its ecosystem: NeuralSpike built Genio reference work for MediaTek itself, including 80+ FPS visual data segmentation on Genio 500 and a barcode-free checkout PoC on AIoT i500.
- MediaTek’s Smart Edge segment — which houses Genio — its fastest-growing in 1Q26 (+23% QoQ). Expect edge-to-cloud agentic AI headlines for Mediatek at Computex in Taipei next week.
10. Lenovo’s Q4 FY25/26. Record Quarter, Record Year, ISG Inflection Point
- Lenovo (0992.HK) reported full-year FY2025/26 revenues of a record US$83.1 billion, up 20% YoY, with net profit attributable to shareholders of US$1.9 billion, up 38%.
- Lenovo reported Q4 revenues of US$21.6 billion, +27% YoY, its fastest growth in five years. AI-related revenue hit 38% of group revenue in the quarter and grew 84% YoY.
- Lenovo’s Infrastructure Solutions Group turned full-year profitable, delivering record revenue of US$19.2 billion, up 32%, and an operating profit of US$73 million, a roughly US$140 million year-on-year swing