
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SpaceX Just Filed Their S-1 & It’s A Doozy
- On May 20, 2026, SpaceX filed an S-1 registration statement with the SEC. Ticker: SPCX. Listing venue: Nasdaq plus the brand-new Nasdaq Texas, headquartered at 1 Rocket Road, Starbase, Texas
- Two share classes. Class A = 1 vote. Class B = 10 votes. Class B shareholders separately elect a majority of the board as a class. Elon taking no chances.
- SpaceX key plans include a permanent human colony on Mars with at least one million inhabitants and launching orbital data centers capable of delivering 100 terawatts of compute per year.
2. Intel @JPM 54th Annual TMT. Key Takeaways & Full Transcript
- This is easily the most consequential interview LBT has given since taking over the CEO role at Intel. It’s essential material for both existing and would-be investors
- 18A is in volume; 14A is the foundry pitch. Panther Lake on 18A has 200 design wins and now finally has wafer supply. 14A
- Advanced packaging is a quiet upside lever. Customers are willing to prepay substrate commitments in the billions of dollars to lock in Intel’s EMIB-T capacity
3. NVIDIA Q1 FY27. Stellar Beat & Raise With Vera CPU Adding A Further $200 Billion TAM
- NVIDIA reported record Q1 FY27 revenue of $81.6 billion, +85% from a year ago and +20% sequentially, well ahead of their guided $78 billion, as has now become their SOP
- DC compute revenue was a record $60.4 billion, +77% YoY, +18% QoQ. DC networking revenue was a record $14.8 billion, +199% YoY and +35% QoQ
- Current quarter revenue pegged at $91.0 billion, with no China DC compute revenue included.
4. Qualcomm @JPM 54th Annual TMT. Key Takeaways & Full Transcript
- Qualcomm is entering data center with a three-product attack: custom silicon (revenue starting this year), data center CPU, and an AI inference accelerator (AI 200 / AI 250).
- Robotics framed as the next ADAS. Same content range starting point as Auto ($300-$2,000 per platform), 3-5 year horizon to material revenue. Multiple named partners plus many undisclosed China partners
- Smartphones. June quarter is the trough. Two quarters of channel drawdown have run their course. Confidence anchored on actual channel data plus Sep/Dec device launches
5. Micron @ JPM 54th Annual TMT Conference: Key Takeaways & Full Transcript
- Our financial outlook has strengthened since our last earnings call. We’re on track for another substantial record free cash flow in fiscal Q3. Our balance sheet has never been stronger
- Greenfield expansion is now mandatory. The industry needs new clean-room space, not just new tools, and clean-room construction is measured in years, not quarters.
- Multi-Year EUV supply agreement with ASML has been concluded covering 1-delta and subsequent generations. EUV deployment will increase materially at 1-delta versus 1-gamma.
6. Seagate @JPM 54th Annual TMT: Key Takeaways & Full Transcript
- Millions of HAMR drives shipped. Mosaic 3 is qualified at all planned CSPs. Mosaic 4 (4 TB/platter) is qualified at two large CSPs. High confidence to reach 5 TB/platter.
- Painful multi-year initial Mosaic 3 qualification was one-time learning-curve event. Mosaic 4 ran through two large CSPs at traditional qualification timelines. Expectation set: Mosaic 5 and 6 should look similar.
- Capacity expansion is happening through technology, not floor space. Seagate is targeting mid-20s percent exabyte growth and explicitly not adding new factories. We all know that that means, right?
7. Intel @JPM 54th Annual TMT. Full Transcript Attached.
- Millions of HAMR drives shipped. Mosaic 3 is qualified at all planned CSPs. Mosaic 4 (4 TB/platter) is qualified at two large CSPs. High confidence to reach 5 TB/platter.
- Painful multi-year initial Mosaic 3 qualification was one-time learning-curve event. Mosaic 4 ran through two large CSPs at traditional qualification timelines. Expectation set: Mosaic 5 and 6 should look similar
- Capacity expansion is happening through technology, not floor space. Seagate is targeting mid-20s percent exabyte growth and explicitly not adding new factories. We all know that that means, right?
8. Tower Semiconductor Q1 2026. It’s All About Silicon Photonics Now!
- Tower Reported Q1 2026 revenue of $413.6 million, +15.5% YoY but -6.0% QoQ from Q4 2025’s record $440.2 million. This was marginally ahead of the forecasted midpoint of $412 million.
- Tower guided for a record current quarter with revenues of $455 million, while flagging that we should expect QoQ growth for both revenue and gross margin throughout the year
- Tower reported $1.3 billion of contracted silicon photonics revenue for 2027 from their largest SiPho customers, backed by approximately $290 million in prepayments already received. Oh my!
9. SMIC Q1 2026. Dumping The Dividend To Maintain The CapEx Cadence
- SMIC reported Q1 2026 revenues of $2,505 million, up 0.7% QoQ and up 11.5% YoY. Gross margin was 20.1%, up 0.9 pp QoQ but down 2.4 pp YoY.
- For the second quarter 2026, SMIC expects revenue to increase by 14% to 16% sequentially and growth margin is expected to be in the range of 20% to 22%
- CapEx is expected to remain similar to CY2025 at ~$8 billion. Depreciation expenses are expected to increase 30% YoY. Bye bye dividend!
10. Amkor Expands Its Arizona Investment, For the Third Time.
- As part of its long-term growth strategy, Amkor has now secured an additional 67-acre parcel adjacent to the existing campus, providing strategic flexibility to support future expansion and evolving customer demand.
- Back in Nov 2023, Amkor Technology, announced a $2 billion, 500k square foot cleanroom space, 2000 employee investment in Arizona, yet ground breaking didn’t begin until two years later
- In November 2025, Amkor expanded their Arizona investment to $7 billion, 750k square foot clean room space and 3,000 employees, yet production still won’t start until early 2028
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Sumco Soars But Their Downturn Recovery Still Remains Very Much A Work In Progress
- SUMCO soared 18% on May 8. Their share price is +260% over the past year and +149% YTD. Siltronic & GlobalWafers have shown a similar, albeit less dramatic, trend.
- The silicon wafer recovery from a protracted post-pandemic downturn remains a work in progress. Inventory levels are still at historic highs, current year forecasts are ho-hum at best
- Many semi names are presently re-rating based on record breaking revenue growth. That kinda makes sense. The silicon wafer manufacturers are rallying on sentiment. That may become problematic. Let’s see.
2. ASE Q1 2026. CapEx Struggling To Keep Pace With Surging Demand
- On Wednesday 29 April 2026, ASE Technology reported Q1 2026 revenues of NT$173.66 billion, down 2.4% QoQ but up 17.2% YoY and at the high end of the guided range.
- Current quarter revenue expected to grow by 7 to 9% QoQ; Gross margin should increase by 20 to 100 basis points QoQ
- ASE raised 2026 capex by roughly US$1.5 billion, a 20% increase on the $7 billion number that was communicated in February. 2026 CapEx will now reach $8.5 billion
3. Taiwan April Sales Signals: AI Server Ramp Sustains & Memory Cycle Bleeds Into PC OEMs
- Memory signals — Memory revenue +309% YoY, still climbing month-to-month. Acer (+68%) cites memory price hikes inducing PC pull-forward demand; Q2 PC revenue inflated, Q3 unwind risk.
- AI server signals — Demand sustained for four straight months at dedicated server assemblers. Quanta +121%, Wistron +112%, Inventec +37%, Hon Hai +30%; 4-month YTD revenue growth +52%.
- Bifurcation signals — AI server vs. non-AI server performance bifurcation widens… Display/Optics subsector revenue −2.7% YoY (first chain-level negative).
4. Amkor Q1 2026. Money For Nothing & Your Shares For Free
- Amkor, the largest US-headquartered outsourced semiconductor packaging and test (OSAT) provider, delivered record first quarter revenue of $1.68 billion, increasing 27% YoY, while being seasonally down 10.7% QoQ
- 2026 CapEx was reaffirmed at $2.5 billion to $3 billion. 65% to 70% is projected for facility expansion, including Phase 1 of their Arizona campus.
- Amkor has offered $1 billion in convertible senior notes. It’s basically a $1 billion interest free loan, with the lenders hoping for windfall return in the form of Amkor shares.
5. GlobalWafers Q1 2026. May Be Viewed As A Relatively Low Point In The Current Cycle !
- On May 5, 2026, GlobalWafers (6488.TW) reported Q1 2026 revenue of NT$13.98 billion, down 3.6% quarter-on-quarter from Q4 2025’s NT$14.50 billion, and down 10.3% year-on-year from Q1 2025’s NT$15.60 billion.
- Gross margin was 20.8%, a 4.9 percentage point sequential decline from Q4 2025’s 25.7%, driven by three distinct and largely non-recurring factors
- GlobalWafers now provides simulated financials to show what the numbers would be if they hadn’t gone ahead with their expansion plans. Go figure!
6. Cerebras Explodes Into A New Era Of Silicon Exuberance
- CBRS opened at $350, an 89.2% pop on the offer price. It traded as high as $386.34 intraday, a 108.8% gain. It closed at $311.07, +68.1% from the $185 offer.
- At the $311 close, the market is pricing Cerebras as if the OpenAI deal converts, the AWS channel scales, the performance lead over NVIDIA holds, and the historical concentration moderates.
- OpenAI’s equity stake in Cerebras, disclosed in the related-party section of the prospectus, has just become worth substantially more. Nice one Sam!
7. Rohm (6963 JP): Profit Rebound in the Price
- After rising by 76% since the beginning of the year, Rohm is selling at 20x our EPS forecast for FY Mar-29. This should discount a reasonably optimistic recovery scenario.
- A ¥193.6 billion impairment charge and the withdrawal of Denso’s acquisition proposal has opened the way for management to rebuild the business.
- Shortages of and high prices for materials, and other economic disruption caused by the war on Iran, have largely been ignored.
8. TSMC (2330.TT; TSM.US): 2026 Symposium Held on May 14
- Global Expansion & Operations : A total of 18 fabs are currently under construction or expansion worldwide, including 5 advanced packaging facilities.
- Advanced Process Roadmap (N2 / A14 / A12): N2 Performance: First-year output is expected to exceed N3’s first year by 45%.
- Next-Gen Technology: CFET-based SRAM cell area is 30% smaller than nanosheet designs.
9. Silergy (6415.TT): Management Is Confident that Exceeding 20% Is Highly Feasible.
- Key growth is driven by the rapid increase in power requirements for AI servers and the ubiquitous demand for battery management systems (BMS) across automotive, energy storage, and robotics.
- The company maintains its 20–30% annual growth target, with management expressing increased confidence that achieving over 20% is highly feasible.
- That while upstream costs have risen, the company is passing these costs through to customers. Due to tight capacity, customers are generally accepting of price adjustments to ensure supply security.
10. Ulvac (6728 JP): Opportunities in Rare Earth Magnets and AI
- ULVAC regained its May 2024 price peak last Tuesday, when it announced 3Q results showing a big increase in new orders, which rose 29% from 2Q and 109% YoY.
- Orders growth was led by strong demand for vacuum equipment used in the AI semiconductor boom, rare earth magnet production, and OLED displays. The 3Q Book-to-Bill ratio was 1.46X.
- Sales and profits lagged as the end of the EV power device downturn passed through the income statement, but should rebound in 1H of FY Jun-27.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Samsung Q1 2026. The Sleeping Giant Awakens
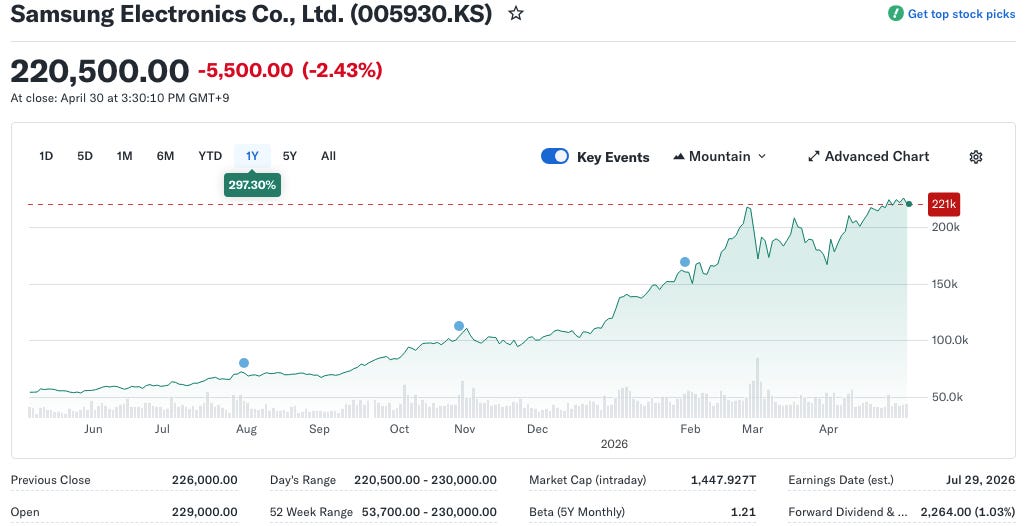
- Samsung Electronics reported record Q1 2026 revenues of ₩134 trillion, record operating profit of ₩57.1 trillion, and an operating margin of 43%.
- Revenue up 43% quarter-on-quarter. Operating profit up 185% QoQ. Net profit of ₩47 trillion, 2.4x the prior quarter. Earnings per share of ₩7,123 per common share
- Long term agreements: “Unlike existing supply contracts based on mutual trust, these multi-year contracts represent a higher level of binding commitment.” Oh boy!
2. Taiwan Dual-Listings Monitor: Rare Opportunities Open Up in TSMC & UMC
- TSMC: +13.6% Premium; Strong Opportunity to Long the ADR Spread
- UMC: +4.3% Premium; Above +1 SD Band; Opportunity to Short the ADR Spread
- ASE: +1.5% Premium; Within Historical Range; No Active Trade Signal
3. Cerebras IPO Incoming Mid-May 2026
- Cerebras is offering 28 million Class A shares at $115-$125 per share, implying gross proceeds of $3.22-$3.50 billion before underwriting discounts.
- For valuation context: at the midpoint of $120 per share, the offering structure implies a fully diluted market capitalisation in the range of $26-$27 billion.
- With just three customers, there’s a likelihood that Cerebras’s quarterly revenue streams will be lumpy for the foreseeable future. Not ideal, in a world that craves perfection. Let’s see..
4. AMD Q1 2026. EPYC Numbers Are Insane
- AMD reported Q126 revenue of $10.253 billion, up 38% year-over-year, with non-GAAP EPS of $1.37, up 43% year-over-year
- Guidance for Q2 was set at approximately $11.2 billion, up 46% year-over-year at the midpoint. Free cash flow tripled to a record $2.6 billion, which is 25% of revenue.
- During the November 2025 Financial Analyst Day, Lisa Su pegged server CPU TAM at $60 billion by 2030. Now it has jumped to $120 billion by 2030. That’s insane.
5. Palantir Q1 2026. Rewriting The Rule Of 40
- Palantir reported Q1 2026 revenue growth of 85% year-over-year to $1.633 billion. U.S. revenue crossed $1 billion for the first time and grew 104% year-over-year.
- New FY 2026 guidance: $7.650-$7.662 billion, or 71% growth. That is 10 percentage points above what they guided just one quarter ago.
- Palantir’s Rule of 40 score has soared to 145%. We have shattered the metric, a feat matched only by other fellow AI infrastructure companies: NVIDIA, Micron and SK Hynix
6. TechChain Insights Q&A: Inside TSMC, Intel and SMIC’s Advanced-Node Pipeline – M31 (6643 TT)
- Sub-8nm foundry license mix surged from 47.6% to 79% in 1Q26, a real-time read on advanced-node platform demand across TSMC, Samsung, and the leading-edge foundry stack.
- A Tier-1 US foundry engagement (likely Intel Foundry or TSMC Arizona in our view) could be confirmed 2Q26, a leading indicator of which US fab attracts external fabless customers first.
- First 3nm royalties landed in 4Q25; sub-16nm royalty +~700% YoY in 1Q26, confirming the AI accelerator supply chain’s transition to leading-edge nodes is now live.
7. Meta Q1 2026. The AI Plan Is On Track But What Exactly Is It ?
- Meta reported Q1 2026 revenues of $56.3 billion, +33% year-over-year (29% constant currency), comfortably above the $55.5-$55.6 billion FactSet/Bloomberg consensus. Non-GAAP EPS was $7.31, adjusted for a one-time tax benefit
- Meta guided current quarter revenues at $59.5 billion, up 5.6% QoQ and up 24% YoY. Oh and they also guided FY2026 capex at $125-$145 billion, up from $115-$135 billion previously
- Meta’s add business is doing just great but when it comes to their AI plans, the narrative around how their CapEx translates into meaningful ROIC is as clear as mud.
8. Apple Q2 FY2026. Ternus Takes The Reins As Memory Pricing, Geopolitical & AI Strategy Headwinds Loom
- Apple reported Q2 FY2026 revenue of $111.2 billion, +17% YoY, a March quarter record and above the high end of Apple’s own guidance range. Diluted EPS hit $2.01, +22% YoY
- IPhone grew 22% to $57 billion. Services grew 16% to $31 billion, an all-time record. Every geographic segment set a March quarter record. China grew 28% YoY
- Ternus takes the helm with three looming headwinds, memory pricing, geopolitical risk associated with their structural China dependency and an Apple Intelligence strategy that’s been MIA for two years…
9. Applied Materials Buys ASMPT’s NEXX Problem Child For $120M
- On April 30, 2026, Applied Materials and ASMPT signed a stock purchase agreement for AMAT to acquire their NEXX division for US$120 million in cash.
- AMAT already has digital lithography, PVD, CVD, etch, and eBeam metrology for advanced packaging. The missing piece was ECD. Not any more
- ASMPT is not divesting a crown jewel. It is divesting a cash drain, at roughly book value, to a buyer willing to pay up because NEXX fits a strategic gap..
10. GlobalFoundries Q1 2026. Pivoting To The AI Networking Bottleneck
- GlobalFoundries reported Q126 revenue of $1.634 billion, up 3% YoY, but down 11% sequentially, which is the normal seasonal pattern for the business
- Non-IFRS gross margin hit 29.0%, a record for a first quarter, beating guidance by around 200 basis points and topping the prior-year period by 510 basis points
- SiGe capacity is oversubscribed through well into 2027. Silicon photonics revenue is on track to roughly double in 2026..
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
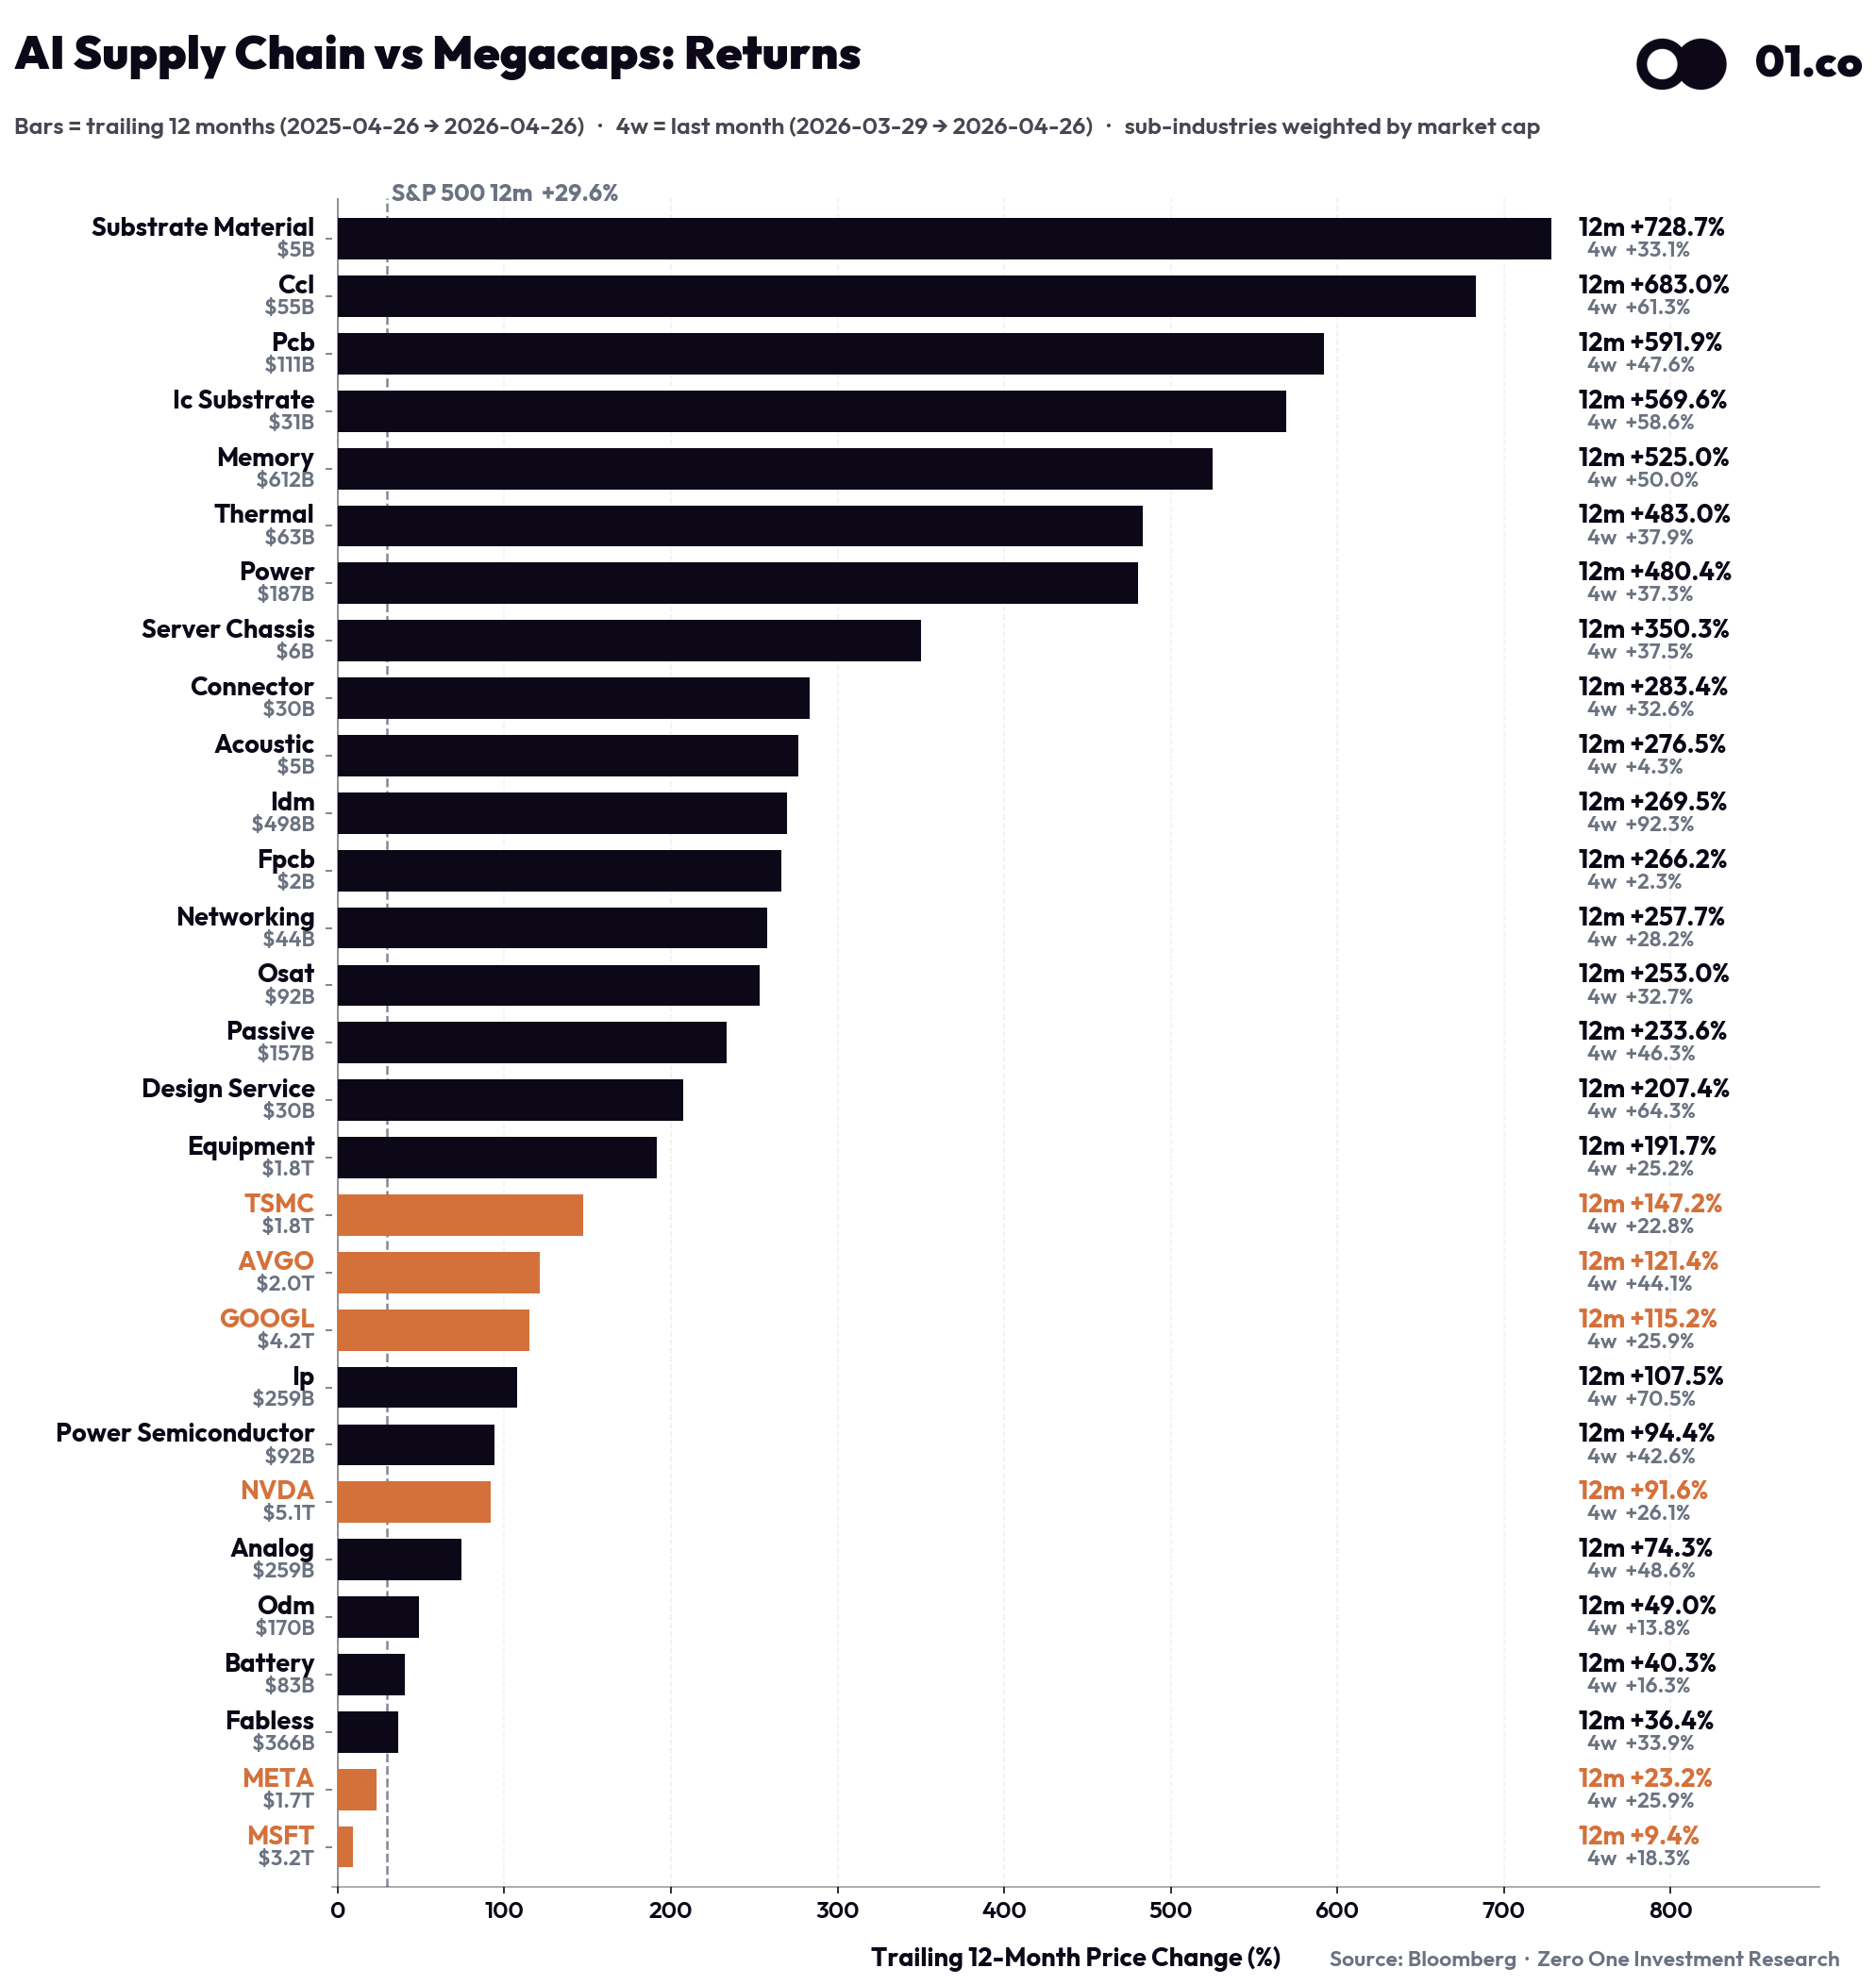
1. AI’s Biggest Winners Aren’t NVDA and TSMC — They’re the Suppliers
- Over the trailing 12 months and the last month, the suppliers feeding the AI buildout have run multiples of NVDA and TSMC themselves.
- I pulled fresh price performance across Zero One’s broad coverage universe — 190 AI and semiconductor names tracked daily across Taiwan, Korea, Japan, and the US.
- We explore five key themes that arise from the data and recent events.
2. Microsoft Q3 FY2026. The $190 Billion CapEx Bombshell
- Revenue: $82.9B, +18% YoY, +2% QoQ, and a beat against the ~$81.4B consensus estimate. Microsoft guided to a Q3 midpoint of $81.2B on the Q2 call; they cleared it comfortably.
- Azure grew: 40% year-over-year, 39% in constant currency. The Q2 call guided 37-38% constant currency for Q3. A year ago it was 35%. The re-acceleration is real.
- Hood’s FY2026 full-year capex guidance: $190 billion. The prior consensus was around $154.6 billion. The guidance represented a 23% upward revision in a single quarter. Oh my!
3. TechChain Insights Q&A: ARM’s Only Listed Rival – Powering Meta and Taiwan’s AI Cycle – Andes (6533 TT)
- Last independent RISC-V IP vendor standing. With MIPS, Codasip, and Nuclei exiting and ARM competing with its own licensees, Andes is the primary “flight-to-stability” beneficiary, anchored by ACE customer lock-in.
- Operating breakeven is an explicit 2026 objective. Management is targeting a 10% OPEX cut to NT$1.7B and a 20% revenue ramp from the FY2025 base of NT$1.478B.
- Cuzco announcement within a month is the next catalyst. Business arrangements and development schedule for the Neoverse-class core will be officially disclosed separately, alongside ramping AX46MPV and automotive design wins.
4. Microsoft and OpenAI Relationship Transitions From Next Chapter To Next Phase
- On April 27, 2026, Microsoft & OpenAI jointly announcing what they are calling the next phase of their partnership.
- Under the terms of the deal, Microsoft no longer pay a revenue share to OpenAI, while the latter continues to pay its a revenue share to Microsoft through 2030
- Microsoft also loses its exclusivity agreement on hosting OpenAI’s APIs. That’s a big deal, albeit it was the inevitable outcome as OpenAI spreads it wings and embraces other infrastructure partners…
5. Seagate Q326. Soaring On Beat & Raise While HAMR Marches On
- Seagate reported fiscal Q3 2026 revenue of $3.11 billion, above the high end of its own guidance range of $2.9B-$3.1B, and well ahead of Street consensus near $3.0 billion.
- For Q4 FY2026, management guided revenue of $3.45 billion ±$100M (+41% YoY at midpoint), non-GAAP operating margin in the lower 40% range for the first time in company history,
- Seagate surged >17% in after hours trading. The stock has now appreciated over 600% over the course of the past year. The humble HDD is back…
6. Qualcomm Q2 FY2026. Handsets Hit A Wall But AI Data Centre Beckons Alluringly
- Qualcomm reported Q226 revenues of $10.6 billion, -3% YoY from $11.0 billion and down ~14% sequentially from Q1’s record $12.3 billion, roughly in line with the $10.59 billion FactSet consensus.
- QCT segment revenue: $9.1B: down 4% YoY, with handsets down 13% YoY. However, CEO Cristiano Amon told Reuters post earnings interview: “We can now call the bottom”. Hmm
- We have engagement on custom ASIC, which is what we wanted to do when we bought AlphaWave. We have a lot of connectivity IP that enables us to do that.
7. Salesforce Goes Headless. That’s A Big Deal.
- On April 15, 2026, Salesforce co-founder Parker Harris posed a question at the company’s annual TDX developer conference “why should you ever log into Salesforce again?”
- This question marked the launch of Salesforce Headless 360, arguably the most significant architectural announcement the company has made in its 27-year history
- Headless 360 makes Salesforce agnostic as to how work happens, charging for the work being done rather than the seats doing it. It’s a bold move. Let’s see…
8. KYEC (2449.TT): 2026 Growth Forecast Cut to 38–40% from 47%, Still Far Above 2025.
- We revise down King Yuan Electronics Co, Ltd. (2449 TT)’s full-year 2026 revenue growth forecast revised down from original 47% to 38–40%, still far exceeding last year’s 30% growth.
- King Yuan Electronics Co, Ltd. (2449 TT)’s 1Q26 revenue YoY +2–3%, better than original expectations (previously feared a 1–2% decline)
- King Yuan Electronics Co, Ltd. (2449 TT)’s 2026 capex reaches NT$50 billion, with cash dividend only NT$1 + 0.5 shares, lowering yield
9. Medallia. Canary In The Coal Mine?
- On April 22, 2026, Thoma Bravo reached an agreement to hand software firm Medallia to its lenders, wiping out $5.1 billion in equity on a $6.4 billion 2021 take-private.
- Lender syndicate (Blackstone at $1.5B, KKR, Apollo Global, and Antares Capital) will take control in a debt-for-equity swap. For Thoma Bravo, it is the largest equity write-off in their history
- Being stress-tested right now, is the question as to which of the 1,900+ PE-owned software companies can generate enough cash to service $440B in debt at current rates. Let’s see
10. Amazon Q1 2026. FCF Disappearing As CapEx Soars But Otherwise Things Are Going Great
- Amazon reported Q126 revenues of $181.5 billion, up 17% year-over-year from $155.7 billion (15% excluding a $2.9 billion FX tailwind), beating the LSEG consensus of $177.1 billion.
- EPS of $2.78 demolished the $1.63 street estimate, though that gap is heavily inflated by $16.8 billion in pre-tax Anthropic investment gains booked in non-operating income this quarter.
- Anthropic is becoming Amazon’s most important strategic asset in AI: $33B invested, $100B+ in committed AWS spend coming back over a decade, and $16.8B already-realized investment gains this quarter alone.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SK Hynix Q126 Earnings Call Transcript
- SK Hynix reported Q1 2026 revenue of ₩52.58 trillion, operating profit of ₩37.61 trillion, and net profit of ₩40.35 trillion.
- Revenue cleared ₩50 trillion for the first time. Operating margin hit 72%, an all time record high
- Shares were already up 88% year-to-date heading into the print, closing at ₩1,224,000 on April 21. The stock has been on a tear all year. Now you know why!
2. NEC (6701 JP): Key Supplier for Mogami Frigates
- Contract with Australia to supply sonar, communications and navigation equipment for Mogami frigates points to long-term growth for NEC’s defense business.
- Three frigates to be built for the Australian Navy by MHI in Nagasaki, followed by eight more to be built in Australia. NEC likely to supply all of them.
- Shares rebounding from their February low, but still more than 25% below their 52-week high. Selling at 23 times EPS guidance as of April 21.
3. Intel Q126. Soaring On Multiple Tailwinds
- Intel reported Q126 revenue of $13.6 billion, $1.4 billion above the midpoint of guidance, and $1.3 billion above Street consensus of $12.3 billion. Non-GAAP EPS was $0.29, versus break-even guidance.
- The company is experiencing multiple tailwinds from insatiable CPU demand, slowly rising 18A yields, progress on 14A and a new phenomenon, LTAs with strategic customers like Google. That’s new!
- Intel’s share price is soaring in after hours trading, currently up ~22%. Is this a turning point for Intel’s resurgence? Let’s see…
4. ServiceNow Q126. Tanking On Not Very Much
- ServiceNow reported Q126 revenues of $3.67 billion, +3% QoQ and +22% YoY. Subscription revenue grew 19%, beating guidance. RPO came in at +21% CC, 100 basis points above guide.
- Looking ahead, the company forecasted current quarter revenues marginally up QoQ to $3.8 billion, and up 22.5% YoY.
- The share price tanked >17% post-earnings. It’s now down 48% over the past twelve months and trading roughly where it was at the trough of the 2022 rout. Interesting..
5. ASMPT Q126. Exploding On AI Demand
- ASMPT Q126 revenue was up 32% YoY to HK$3.97 billion (US$508 million). Bookings up 72% YoY to HK$5.67 billion (US$727 million), the highest in four years.
- The Group’s Photonics solutions achieved a five-fold increase in YoY revenue growth, propelled by strong demand from high-speed transceivers of 800G and beyond.
- Planned NEXX divestiture, potential (lower margin) SMT divestiture, new CEO incoming, BESI M&A premium and soaring AI demand all drove a >100% share price increase YTD. More to come?
6. SK Hynix Q126. Margins On Steroids
- SK Hynix reported Q1 2026 revenue of ₩52.58 trillion, operating profit of ₩37.61 trillion, and net profit of ₩40.35 trillion.
- Revenue cleared ₩50 trillion for the first time. Operating margin hit 72%, an all time record high
- Shares were already up 88% year-to-date heading into the print, closing at ₩1,224,000 on April 21. The stock has been on a tear all year. Now you know why!
7. IBM Q1 2026. Solid Beats But Prudent Guidance Gets Punished.
- IBM Q126 revenue came in at $15.92B, up 9% year-on-year from $14.54B in Q1 2025, and above the Street consensus of $15.62B, a beat of $300M.
- Software growing 8% on a $7 billion quarterly base. Infrastructure growing 12% behind the strongest mainframe cycle in a decade. Data revenue growing 16% behind AI tailwinds. FCF growing 13%
- Given where we are in the year, we believe it prudent to maintain our guidance, even as the underlying performance and execution are off to an encouraging start. Stock tanks!
8. The Token Maxxing Delusion
- Earlier this month, Fortune reported that Meta’s 85,000 employees were competing on an internal AI leaderboard called “Claudeonomics”. Welcome to the world of Token Maxxing.
- Now that the door is closing on Agentic AI being able to sneak in under the cover of a monthly subscription, Token Optimisation should become front & center for every enterprise
- Treat your agentic sessions like sprints. Define a clear objective for each session. Work to completion or a meaningful checkpoint. Then summarise and reset. You will save a fortune…
9. Cerebras. The IPO Returns But The Middle East Concentration Remains
- On April 17 last, Cerebras once again filed to go public, having withdrawn their first attempt back in October 2025, thirteen months after having first filed
- One of the concerns in the original filing was was the extreme customer/revenue concentration with G42. That’s greatly reduced, but overall revenue concentration in the region remains >80%
- The recently announced OpenAI partnership is a game changer for this latest Cerebras IPO; the AWS announcement less so, as it’s still in Term Sheet status. Let’s see…
10. LRCX Q326 Earnings Call Transcript
- LRCX Q326 revenue of $5.84 billion, +9% QoQ, +23.8% YoY. GAAP diluted EPS $1.45; non-GAAP diluted EPS was $1.47. It was the company’s third record revenue quarter in a row.
- LRCX guided Q4 FY2026 revenue to $6.60 billion, ±$400 million, up 13% QoQ. Non-GAAP EPS of $1.65, ± $0.15. Gross margin 50.5%- first time over 50%
- LRCX gross margin trajectory already well ahead of the February 2025 Investor Day target, the company will have to do a reset at the next investor day later this year..
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
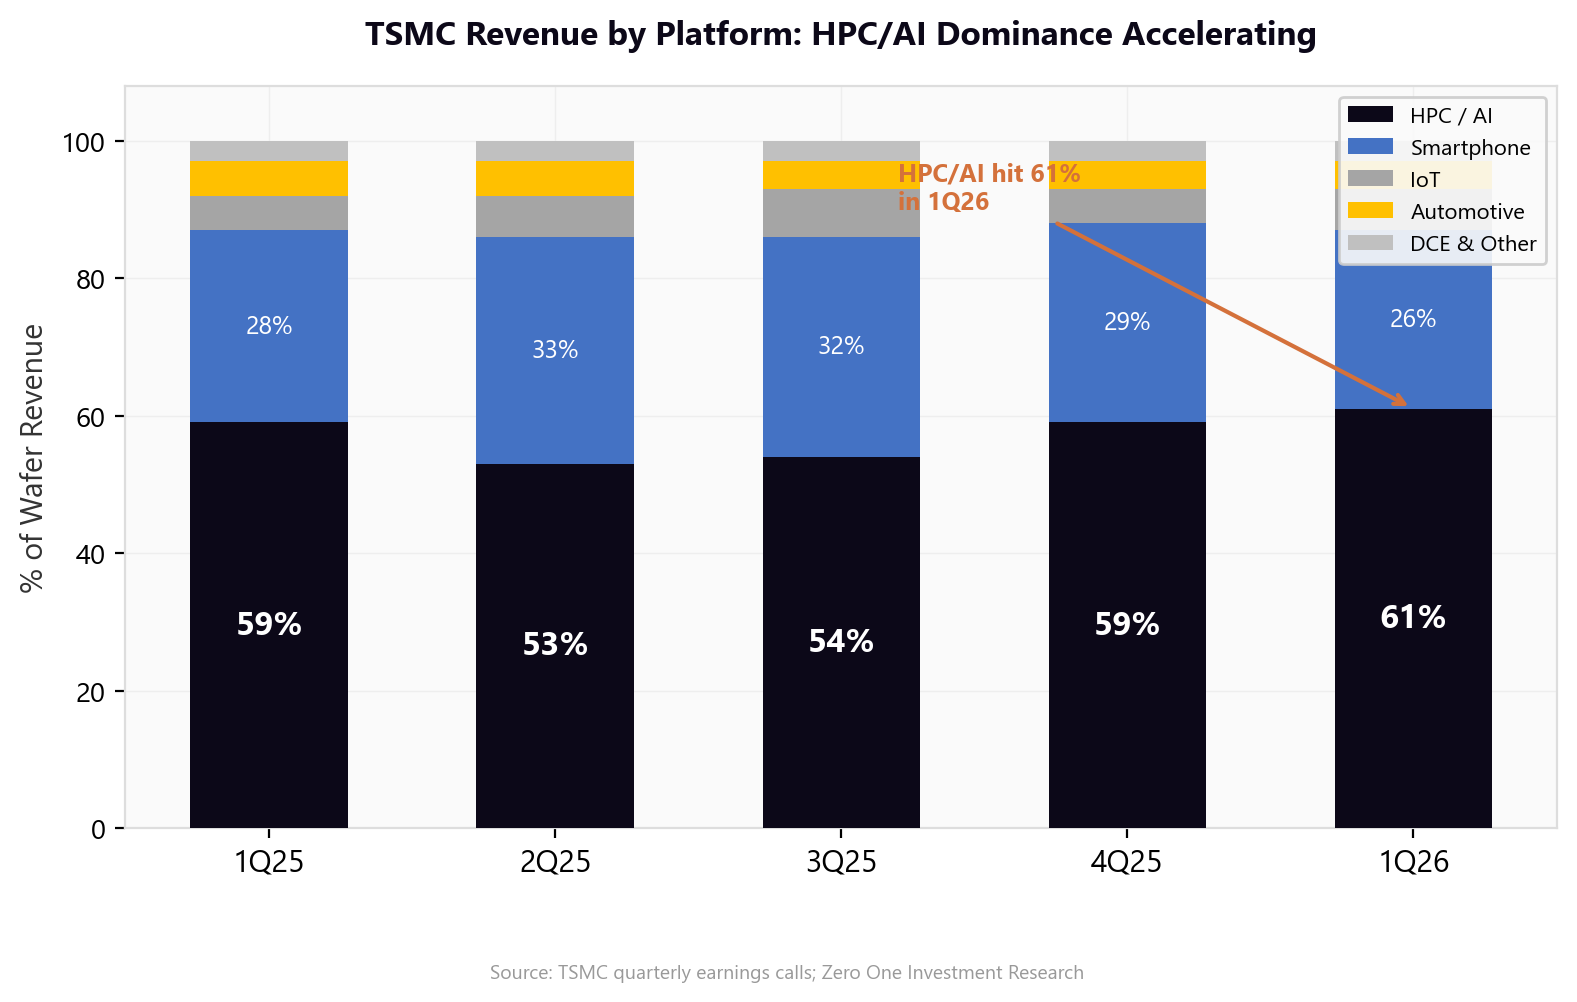
1. TSMC 1Q26: 66% Gross Margin Beat — What It Means for ASML, NVIDIA, MediaTek & 7 More
- Record 66.2% gross margin beat guidance by 120bps; management raised full-year revenue growth to “above 30%” and capex to high end of $52-56B on insatiable AI demand.
- Supply constraints persist through 2027 as TSMC builds three new N3 fabs globally. AI accelerator revenue CAGR reaffirmed at “higher-50s” through 2029.
- Supply chain scorecard: strongly positive for ASML, SK Hynix, ASE; mixed for MediaTek and Apple; negative for Intel and Samsung foundry competitiveness.
2. Taiwan Dual-Listings Monitor: TSMC Recovers from Lows; ChipMOS Spike
- TSMC: +17.6% Premium; Recovered from Lows, Still Just Within Long Level
- ASE: +0.3% Premium; Recovered from Discount; Remains a Long Opportunity
- ChipMOS: +5.7% Premium; Surged Through +1 SD; Consider Shorting the Spread
3. Why Nanya Results and Placement Mean Memory Tightness to Last Much Longer; Close SK Hynix/Nanya Pair
- Management Addresses Recently Closed US$2.5B Strategic Placement. SanDisk, Kioxia, SK Hynix’s Solidigm, and Cisco took 10.19% of Nanya Technology (2408 TT) to lock in legacy DRAM supply.
- FY1Q26 Confirms Supply-Driven Tightness That Will Persist. Nanya reported 67.9% gross margin with ASPs +>70% QoQ on falling bit shipments; management cannot satisfy market demand this year.
- Close Our Long SK Hynix (000660 KS) / Short Nanya Technology (2408 TT) Pair. SK has rallied to new highs while Nanya has retraced from its peak.
4. OpenClaw’s GTC 2026 Moment
- OpenClaw is the #1 most popular open source project in the history of humanity, and it did so in just a few weeks, exceeding what Linux did in 30 years.”
- NVIDIA’s NemoClaw builds on OpenClaw by addressing the security concerns that would otherwise make enterprise-wide adoption impossible
- Jensen coined at new acronym at GTC 2026, GaaS, or Agents as a Service. GaaS is what could very well drive explosive demand for good, old-fashioned CPU compute. Let’s see..
5. Where the AI & Semi Supply Chain Is Actually Flowing: Bottom-Up Read From Taiwan’s March Sales Data
- Taiwan’s March 2026 monthly sales, covering our universe of about 150 supply-chain names, show revenue up +46% aggegate sales growth YoY, one of the strongest months of the current cycle.
- The strongest pockets are where AI hardware buildout flows: Memory +196%, AI Server ODMs +57%, Electronic Components +60%, TSMC +45%, successive layers of the same AI-capex wave.
- The chain is bifurcated. Display, Analog, and PC names are flat; ASIC design-service names are down. One cannot treat the AI supply chain as one block.
6. TSMC Q1 2026. TeraFab? There Are No Shortcuts!
- TSMC reported Q1 2026 revenues of NT$1,134.10 billion (~$35.90B), at the high end of management’s guided range of $34.6–$35.8B and essentially in line with the NT$1,137B consensus.
- Gross margin came in at 66.2%, up 390 basis points from Q4 2025’s 62.3%. That’s a record Q1 print, and it confirms that Q4’s margin expansion was no one-off
- When asked if he was concerned about competition from Elon Musk’s TeraFab, he response was basically to stay that there are no shortcuts. I guess that’s a no, then.
7. Anthropic’s Dario Amodei. Liar With A God Complex Or AI Safety Hero? Part II
- After receiving it’s official supply chain risk designation letter on March 4, the company filed a lawsuit against the DoD on March 9
- OpenAI saw a dramatic rise in unsubscriptions following their Pentagon contract signing, Anthropic benefitted from a surge in subscriptions that boosted them to #1 downloaded App on the App Store
- Following a groundswell of support from the likes of Microsoft, Amazon, Google & Apple, as well as multiple individual AI researchers, Anthropic was granted an injunction against the DoD’s designation
8. Anthropic’s Dario Amodei. Liar With A God Complex Or AI Safety Hero? Part I
- Anthropic’s meltdown with the Pentagon has faded from the limelight, but the issues this episode surfaced remain very much unresolved, a ticking time bomb as the military further embraces AI
- Amodei engaged with the Pentagon via a loosey-goosey “other” type of contract and put operational control of their integration in the hands of Palantir. What could possibly go wrong?
- OpenAI’s rush to fill the Anthropic gap was ill judged, as was Amodei’s intemperate internal memo and the US Administrations Supply Chain Risk designation. Plenty of blame to go around.
9. TSMC (2330.TT; TSM.US): 1Q26 with EPS of NT$22.1, with Full-Year USD Revenue Growth Over 30%.
- TSMC (2330) Sets New Record in 1Q26 with EPS of NT$22.08, Upgrading Full-Year USD Revenue Growth to Over 30%.
- From a product mix perspective, advanced processes continue to drive this quarter’s growth and profitability.
- Chairman stated that with sustained strong demand for advanced processes and robust AI momentum, even amid macroeconomic and geopolitical uncertainties.
10. ASML Q1 2026. Revenue Beat, Guidance Raised. What’s Not To Like?
- ASML reported Q126 revenues of €8.8 billion, above the midpoint of the guided range of €8.2 to €8.9 billion and comfortably ahead of street consensus of around €8.6 billion
- Guided Q2 2026 net sales to €8.4 – €8.8 billion, and raised FY 2026 revenue outlook to €36- €40 billion, up from the previous range of €34 to €39 billion
- The stock has had a remarkable run, up around 40% year to date, and the market’s initial reaction has been muted. At 40x forward earnings, that’s hardly a surprise.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Intel Scraps Apollo SCIP With Ireland’s Fab34. Proof Of Intel Resurgence? Not Necessarily.
- On April 1, Intel and Apollo issued a joint press release announcing the scrapping of the SCIP the companies had signed less than two years ago back in June 2024
- Apollo got a 49% stake in Intel’s Fab 34 for $11 billion less than two years ago. In unwinding the deal, Intel will have to pay Apollo $14.2 billion
- Intel consistently failed to meet key milestones agreed with Apollo, triggering penalties to date of ~$1.5 billion. Next up, Brookfield? Let’s see..
2. TechChain Insights Q&A: Ambiq Micro (AMBQ US) — Ultra-Low-Power Pioneer Betting Big on Edge AI
- Ambiq Micro (AMBQ US) guides >$100M revenue in 2026 (~40% growth), driven by existing customer expansion, a new major wearables customer ramping to mass production.
- New Atomiq AI SoC (built w/ 12nm TSMC production) targets 2027 production, expanding Ambiq’s addressable market into smart glasses, medical devices, and advanced edge AI.
- Patented SPOT platform powers 290M+ devices; no competitor has yet replicated Ambiq’s unique subthreshold low-power operations for semiconductors, creating deep moat reinforced by software ecosystem switching costs.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
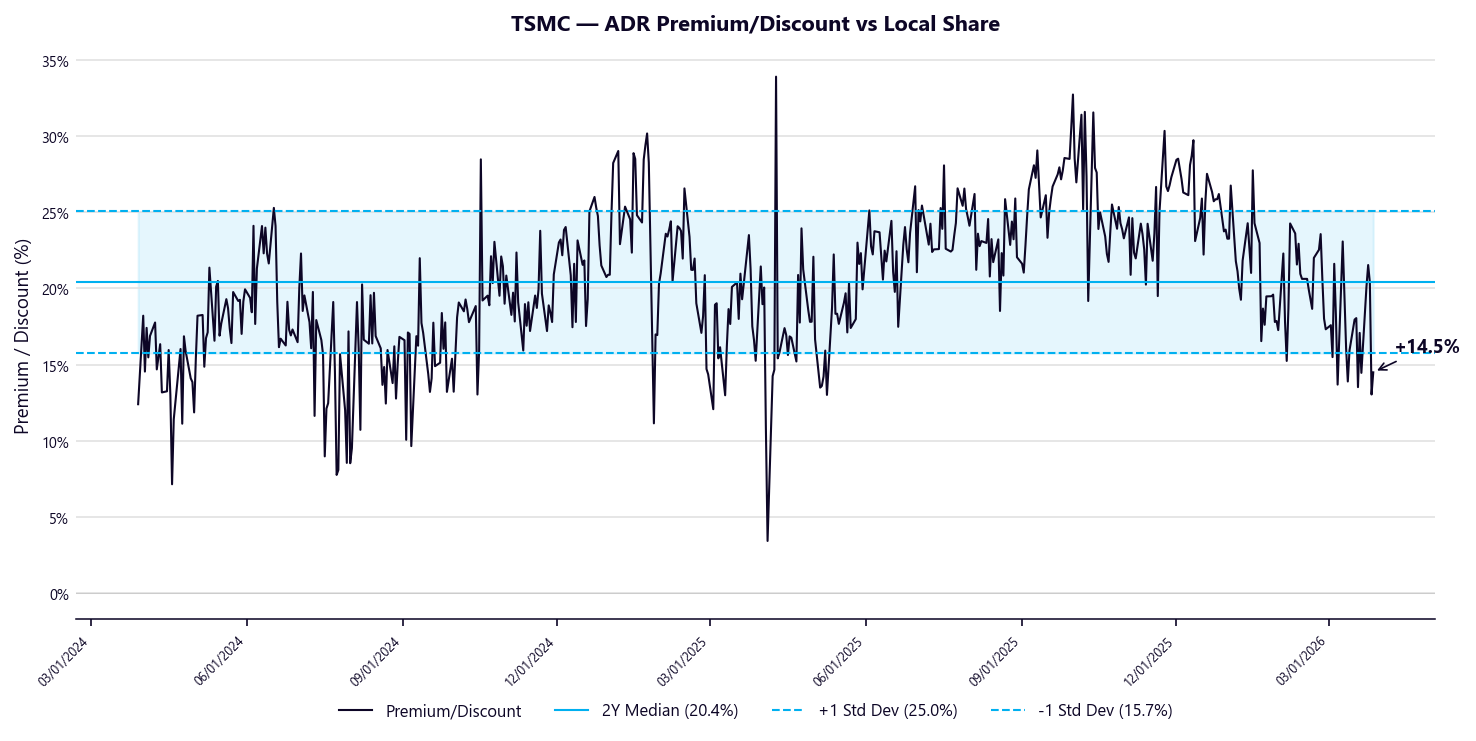
1. Taiwan Dual-Listings Monitor: TSMC Premium Compresses; ASE and UMC Flip to Discount
- TSMC ADR premium compressed to +14.5%, nearly 6pts below its 2-year median of +20.4%, signalling a potential trade in the ADR relative to the local.
- ASE and UMC both trade at discounts to local shares (-3.0% and -2.0%), with ASE ADR short interest dropping 20% even as Taiwan short interest climbs.
- ChipMOS ADR short interest surged 141% to 37,452 shares, though on thin volume.
2. TechChain Insights Q&A: Legacy DRAM Squeeze — How AI’s Capacity Grab Is Reshaping the Memory Market
- Legacy DRAM has shifted to a truly sellers’ market, with buyers unable to secure full order quantities as lead times extend to months.
- HBM and DDR5 capacity reallocation by Samsung, SK Hynix, and Micron is squeezing legacy supply, creating openings for Taiwanese specialty producers.
- IoT demand is accelerating, while large buyers actively dual-source amid geopolitical uncertainty and Chinese capacity expansion.
3. TSMC: Arm’s Foundry Exclusivity Reinforces Advanced Node Dominance & Margins Stronger for Longer
- Arm’s AGI CPU deepens TSMC’s advanced-node monopoly; every leading chip architecture now manufactures exclusively at TSMC.
- We forecast TSMC gross margins 200-400bps above consensus through FY2029E, implying 10-12% EPS upside not priced in.
- Accumulate on weakness: ~20x FY2026E earnings after a 14% pullback; we rate TSMC a Structural Long.
4. Fujitsu (6702 JP): Targeting AI Inference at 1.4nm
- With its stock price down 30% from its January peak, Fujitsu deserves another look.
- Management is setting long-term target with development of a Neural Processing Unit for AI inferencing to be produced by Rapidus at 1.4-nm.
- Sales and profits are now threatened by the economic disruption caused by the war on Iran, but restructuring and demand for AI-driven corporate service solutions should support long-term margin expansion.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Elon’s TeraFab. Genius Move Or Epic Nonsense?
- Elon Musk announced his intention to build a leading edge, so-called TeraFab, in Austin Texas because TSMC & Samsung are unwilling to expand capacity quickly enough
- He intends to produce terrestrial chips for his Tesla cars and Optimus robots and space chips so that he can offer free flights to Saturn when the time comes
- No timeline, no process technology, no experience, no employees no worries. He’s got new physics & will do a bunch of wild and crazy things along the way. For sure…
2. SNPS, CDNS. Babies Out With SaaSpocalypse Bathwater Or Fair Game?
- SNPS & CDNS currently trade at the same levels they were at three years and two years ago respectively.
- Both companies were namechecked twice by Jensen Huang last week as example of companies whose products are needed now more than ever. NVIDIA recently invested $2 billion in SNPS
- The WSJ is now reporting that Elliott has taken a multi-billion dollar stake in SNPS. We all know what that means!
3. Arm Just Blew Up Its Business Model & Wall Street Loved It.
- Arm has formally entered the chip-making business with the Arm AGI CPU, for agentic AI infrastructure, delivering more than 2x performance per rack compared with x86 platforms
- Developed with lead partner Meta, with other customers and leading ODMs committed for production, the Arm AGI CPU is backed by strong support from the global ecosystem
- Arm was up over 16% in overnight trading. There’s officially a new CPU kid on the block.
4. Pharma Foods International (2929 JP): Profit Guidance Raised
- Management has adjusted FY July 2026 guidance after 2Q results that were in line with our expectations. Sales guidance has been lowered slightly while profit guidance has been raised.
- In 2Q, sales growth accelerated, selling expenses were reduced and the company got out of the red. Profits should increase further in 2H.
- The upward revision to profit guidance has cut the projected P/E ratio for this fiscal year from 20.4x to 13.6x.
5. TechChain Insights: Himax (HIMX) Q&A — Automotive Display Dominance Meets Edge AI and Photonics
- Automotive core: ~40% global display driver IC share; automotive now 50% of revenue, with TCON growing ~50% YoY and double-digit 2H26 growth guided from new project ramps.
- Non-Driver expansion: WiseEye edge AI, LCoS microdisplays, and co-packaged optics nano-optics target AI PCs, AR glasses, and data center silicon photonics – meaningful revenue contribution expected from 2027.
- Solid financial foundation: $258M net cash, $140M operating cash flow, ~31% gross margins; structural margin upside expected as high-value non-driver mix grows over the medium term.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Micron. Don’t Sweat The Dip, Focus On The Five Year SCA!
- Micron delivered an exceptional fiscal Q2, with stellar records in revenue, gross margin, EPS and free cash flow. Quarterly revenue nearly tripled versus one year ago.
- Micron’s fiscal Q3 single quarter revenue guidance exceeds the full year revenue for every year in the company’s history through fiscal 2024.
- Strategic Customer Agreements now replace the useless LTAs of the past. One customer has signed up for five years. Likely includes volume guarantees and pricing at prevailing rates. That’s nice!