
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SaaSpocalypse Now. Are We Done Already?
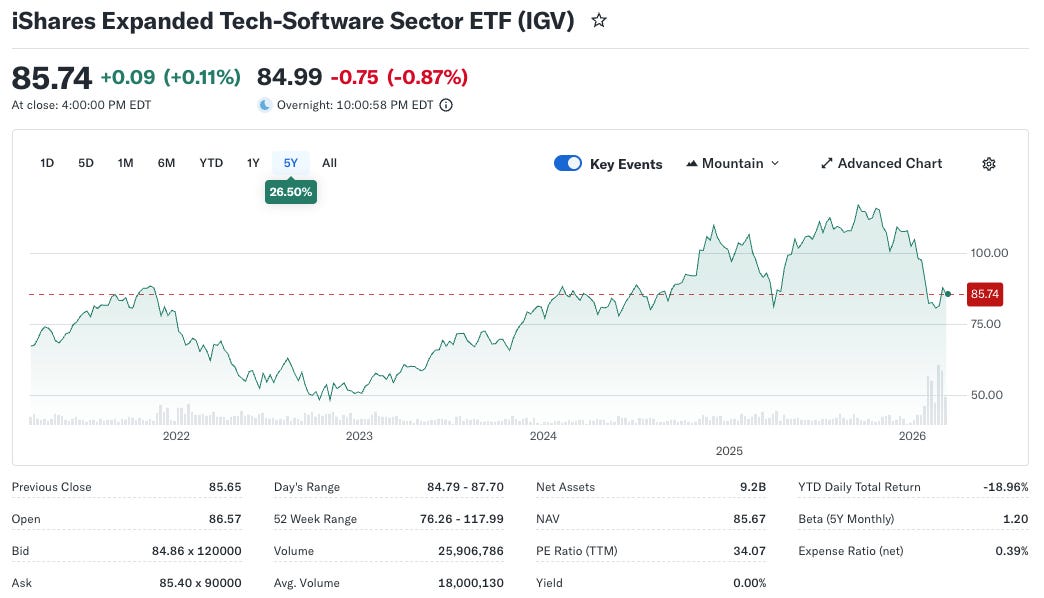
- From its all time high of ~$118 back in September 2025, IGV, the iShares Expanded Tech-Software Sector ETF, is currently down ~26%
- Despite the Saaspocalypse, SaaS earnings and outlook have rarely looked better.
- The issue isn’t that AI can replace SaaS, it’s the risk that SaaS per seat pricing models will fall apart in an agent-centric world.
2. TechChain Insights: Drone World Expo Warsaw 2026 — Vendor Q&A
- Non-China supply chain premium is real and growing: European buyers are willing to pay 30–50% more for Taiwanese drone components, with mandates for zero China-sourced content increasingly common for sensitive applications.
- Batteries are the critical bottleneck: Chinese battery cells remain far ahead on price and energy density; this is the single largest obstacle to building a fully non-Chinese drone supply chain.
- Low barriers to drone assembly, high barriers to differentiation: A striking number of firms offered complete drone solutions built from off-the-shelf components. Value is shifting toward batteries, software, and edge AI.
3. Rohm (6963): Takeover Discounted
- Rohm has backed off its March 9 spike high, but is still up 45% year-to-date. Denso’s proposed takeover has been discounted.
- Rohm is reportedly talking with Toshiba about combining their power device businesses. This could delay an attempted takeover and make it more expensive.
- The Japanese government favors semiconductor industry consolidation, but the three companies could collaborate in automotive power devices without a takeover.
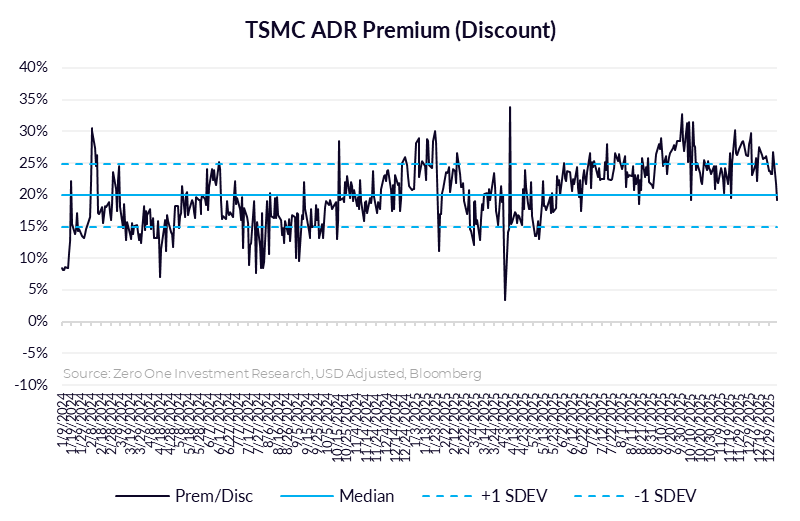
4. Taiwan Dual-Listings Monitor: Broad Spread Collapse Across the Board; TSMC Below Long Entry Level
- TSMC: +15.9% Premium; Spread Has Crashed Through Our Long Entry Level at 19%; Consider Going Long
- UMC: -0.5% Discount; Significant ADR Conversion (+28.8M Units); Spread Fully Unwound
- ASE: -0.5% Discount; Spread Collapsed from +4.5% Premium; Consider Going Long
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Claude Is Gunning For COBOL. IBM Strikes Back
- Announcements from Anthropic during the month of February 2026 roiled multiple segments of an already battered Software industry
- One of those announcements targeted COBOL, highlighting an opportunity to have Claude “modernize” the “legacy” platform that runs 95% of ATM transactions in the US
- IBM disagrees. COBOL is not their secret sauce, it’s their purpose-built architecture from silicon through the operating system that delivers unmatched transactional resilience, security, performance, and efficiency at scale
2. CTW Cayman: Global Anime Demand Surging; Legacy IP’s “Late Bloomer” Effect
- International revenue comprises the majority of revenue for the anime industry, accounting for 56.5% of total sales ($14.1 billion) and is expanding at a 26% YoY rate.
- With international revenue now driving the industry, CTW’s web-based architecture allows the company to circumvent regional app store restrictions and directly reach international audiences across borders.
- The late bloomer phenomenon: Titles that achieve modest viewership during their initial Japanese broadcast frequently experience a viral resurgence across Western social media much later. CTW US – Structural Long.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: Key Spreads After Long CNY Closure in Taiwan
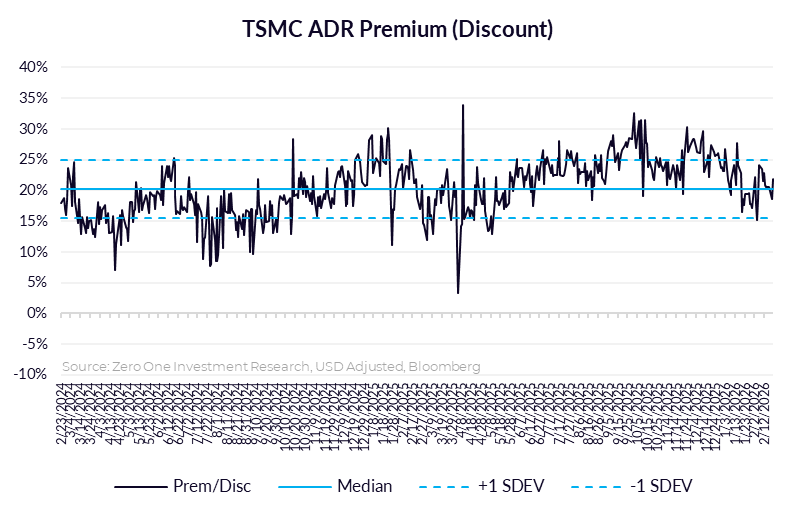
- TSMC: +21.9% Premium; Spread Rebounded from Previous Lows; Maintain Key Long/Short Levels
- UMC: +4.4% Premium; Good Level to Short the Spread Despite Recent Premium Resilience
- ASE: +4.5% Premium; Rebounded from Near-Parity, Near Level to Short the Spread
2. Giving Yourself Away: AMD’s Defensive AI Playbook Expands To Include Meta
- AMD announced a long term, strategic partnership with Meta to power their AI infrastructure with up to 6GW of GPUs “to align our product roadmaps across hardware, software, and systems
- The deal is almost identical to the one AMD inked with OpenAI, with the key difference being that Meta likely has the cash to actually see it through
- An important element of the deal is that it also spans both AMD’s EPYC server CPU processors and their forthcoming Helios rack-scale solution.
3. TechChain Insights: Protect Animal Health (7850 TT) — Management Q&A
- First-In-Class veterinary biologics targeting the US market: Developing the world’s first canine gene therapy (heart disease) and dual-checkpoint immunotherapy (cancer) — the two leading causes of pet death.
- 2025 MountainVet acquisition provides revenue base and clinical infrastructure: ~60% Taiwan diagnostics market share, 900+ vet hospital network, and a built-in distribution channel for therapeutic pipeline launches.
- Multiple 2026 catalysts ahead: PT001 cancer trial efficacy readout, PT401 gene therapy indication expansion, and new antibody candidates from proprietary AIDE discovery platform.
4. TechChain Insights: Gus Technology – Management Q&A
- Taiwan’s first battery gigafactory at 10% utilization — built ahead of demand to win contracts. Breakeven requires 35-45%; management prioritizes capital-efficient, customer-backed expansion.
- Defense is the nearest catalyst — drone cells in qualification with 4-5 mass production discussions active. Meaningful military revenue from 2027, not 2026.
- Non-China supply chain positioning is the structural bet — 100% Taiwan manufacturing, multi-geography sourcing. Converting geopolitical tailwinds into contracts before cash runs thin is the key risk.
5. Macronix (2337 TT): NOR Flash Shortage Intensifies as AI Racks Drive New Type of Demand
- Building on our Jan 28 analysis of the NOR flash cycle trough, Macronix January revenue of NT$3.2bn, +35%YoY (+40% for NOR) and recent industry developments, signal strength amid tightening supply.
- AI’s memory narrative often spotlights HBM and advanced NAND, but NOR memory is the quiet enabler in the datacenter’s backbone—storing boot code, servers firmware, BMCs, and configuration data for networking.
- Macronix International (2337 TT) and Winbond Electronics (2344 TT) together control the majority of global NOR supply. We’ve increased our model forecasts for Macrionix, see further upside for the stock.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SMC (6273 JP): Share Price Chasing Orders Up
- Results for the nine months through December were not impressive, but semiconductor and other electronics industry orders jumped nearly 40% in December-January.
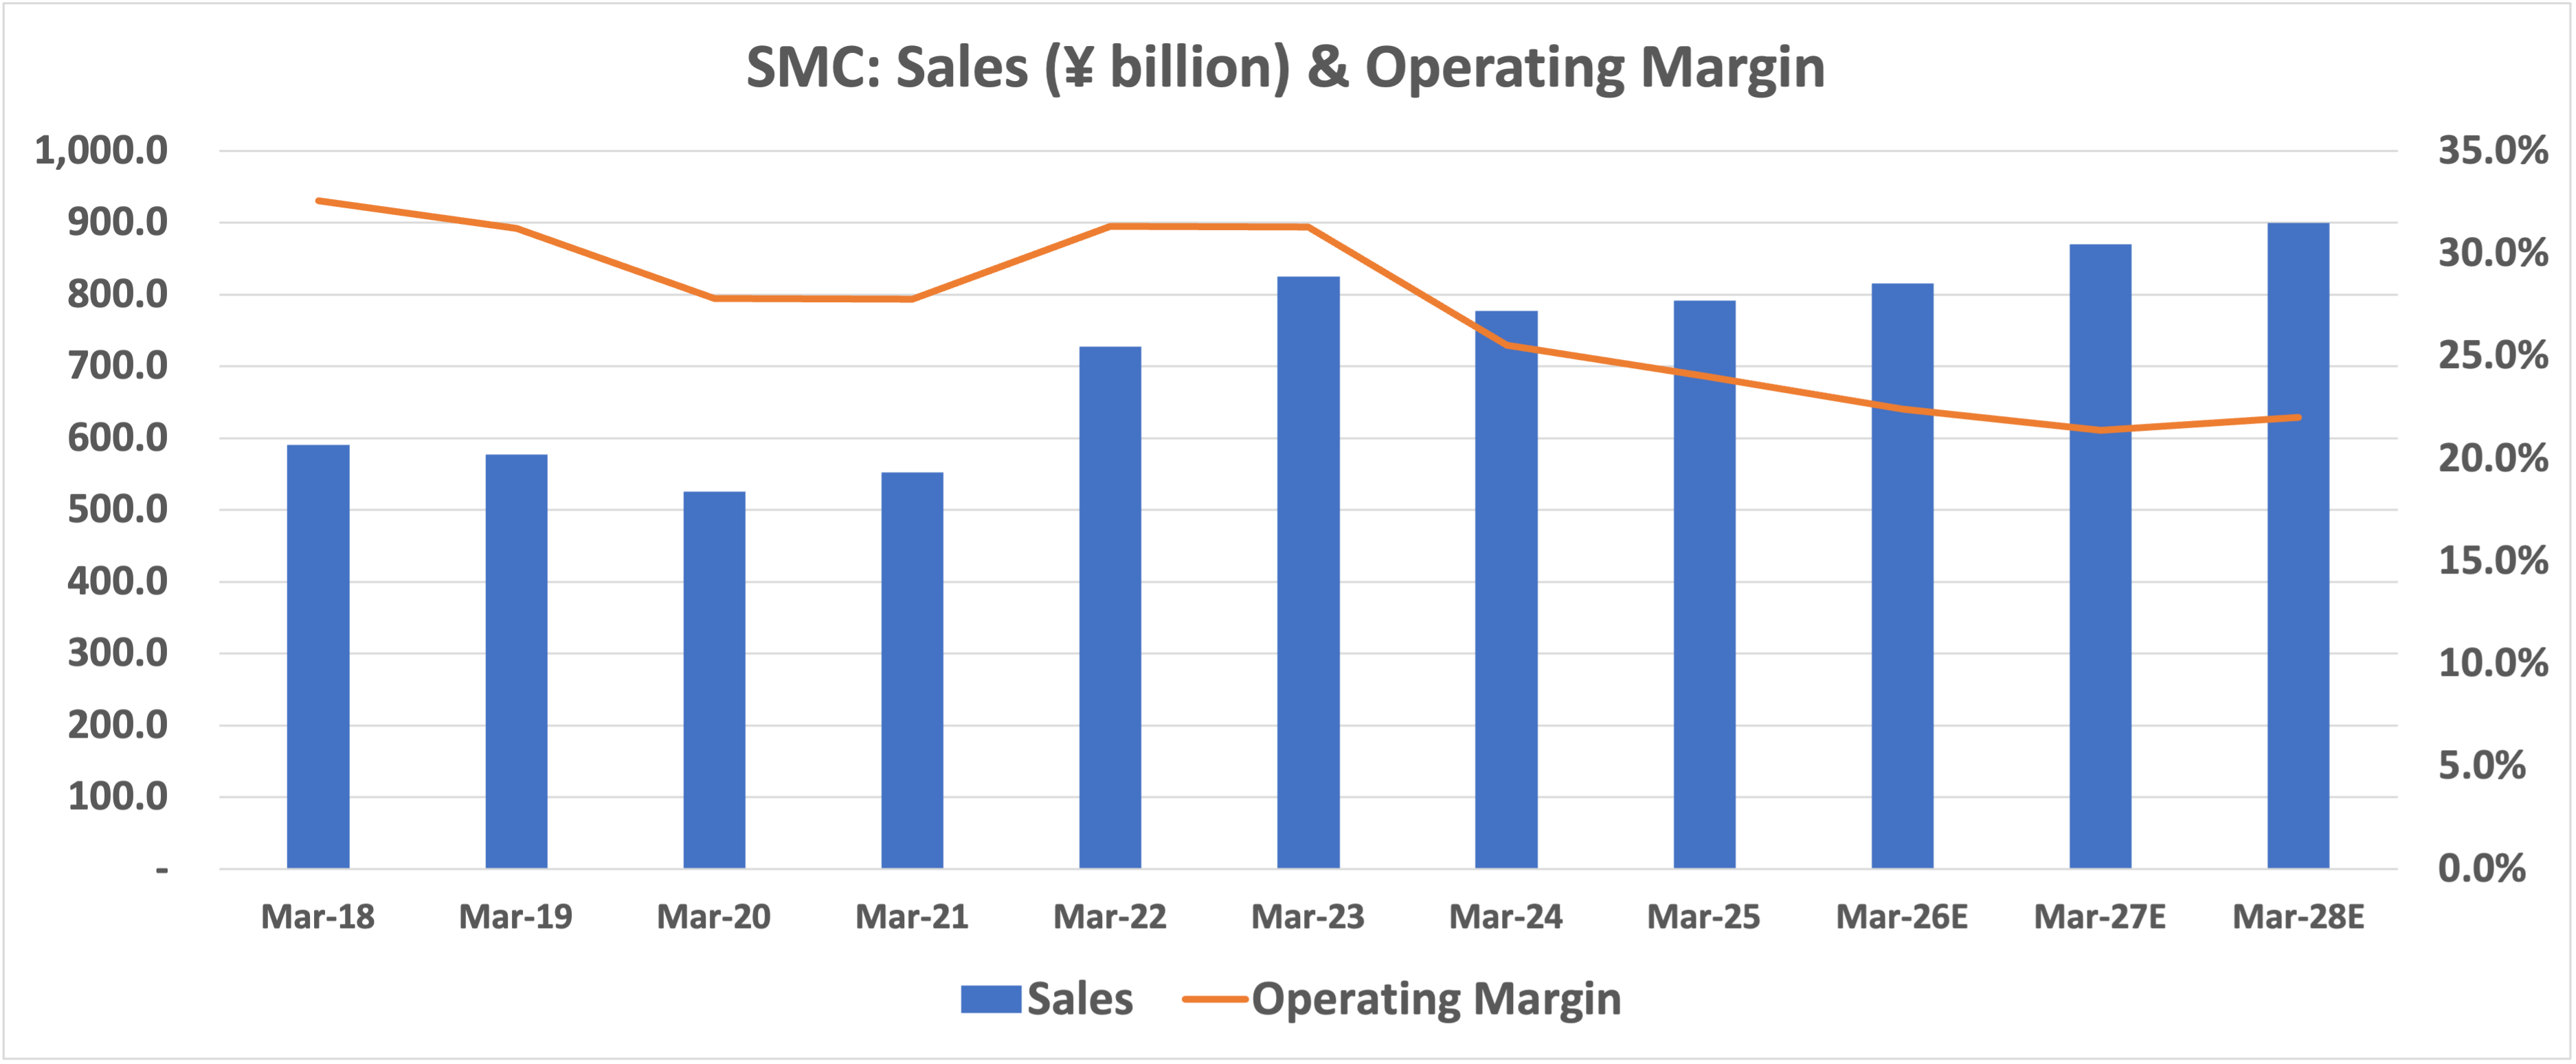
- FY Mar-26 guidance was unchanged with operating profit dropping 3.8% on a sales growth of only 3.0%, but sales should grow more rapidly and margins rise starting next fiscal year
- At the February 18 close, SMC’s share price was up 24% year-to-date and up 53% in the past six months, largely discounting the upturn in orders.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UMC (2303.TT; UMC.US)/ Vanguard (547.TT): The Wafer Prices of Second-Tier Foundries Are Rising.
- Recently, there’s a rumor: Are 8-inch wafers currently negotiating Q2 prices? Is there a chance for a price increase after the Lunar New Year?
- We’ve heard that TSMC and Samsung are exiting the 8” foundry market.
- Vanguard’s 12” wafer output won’t hit the market until early 2027, so there’s no need to consider price increases for now.
2. Nikon (7731 JP): New Defense Business Beyond the Write-Down
- The market has discounted and moved beyond Nikon’s write-down of the value of its additive manufacturing subsidiary Nikon SLM Solutions.
- Orders for 3D metal printers for HII’s Newport News naval shipyard signal a new growth opportunity for Nikon’s Digital Manufacturing business.
- The investment in Trener Robotics is the next step in the development of Nikon’s Digital Manufacturing business.
3. SMIC (981.HK): Expect a Flat QoQ Results in 1Q26, but 2026 Could Still Be a Growth Year.
- 4Q25 results: revenue was $2,489 million Up 4.5% QoQ and Up 12.8% YoY, gross margin was 19.2% and profit from operations was $299 million.
- The 1Q26 guidance: Revenue to be flat and Gross margin to range from 18% to 20%. A typically seasonal softness can be expected, but 2026 still a stable growing trend.
- However, SMIC’s stock price has risen only 0.28% since December 31, 2025—underperforming TSMC (+15%) and UMC (+12%).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Mediatek: Emerging as the Picks-And-Shovels Play on Edge AI Infrastructure
- FY2025 revenue record, profit in-line with consensus. Connectivity business exceeded US$3bn as Wi-Fi 7 tripled and 5G modem doubled, signaling infrastructure buildout for edge AI.
- GB10 partnership with NVIDIA positions MediaTek in the emerging personal AI hardware category as DGX Spark ships to developers and enterprises.
- For investors, MediaTek offers diversified exposure to AI infrastructure buildout across edge and cloud, though near-term share price spike warrants patience.
2. Taiwan Dual-Listings Monitor: Market Volatility Opens Up Multiple Historical Range Breakouts
- TSMC: +19.7% Premium; Rebounds from Near-Term Lows, Latest View on Levels
- UMC: +4.2% Premium; Opportunity to Short the ADR Price Premium
- ChipMOS: +2.7% Premium; Opportunity to Short the ADR Price Premium
3. Keyence (6861 JP): Sliding Down a Mountain of Cash
- Sales are up but profits are lagging, with the gross, operating and net margins all declining in the first nine months of FY Mar-26.
- Overseas sales have risen to two-thirds of total sales, with growth led by Asia and America. This trend seems likely to continue.
- Keyence continues to pile up cash, but for what purpose? With no obvious gearing to AI, its stock price has been underperforming.
4. Microsoft Down ~10% Despite Earnings Beat, Raises & CapEx Growth. What Gives?
- Microsoft delivered a robust Q2FY26 earnings report with revenues of $81.3 billion, up 4.7% QoQ, up 17% YoY and handily beating the high end of the guided range
- It was an excellent quarter with solid beats and raises, yet the share price slumped 10% in after hours trading and has remained at that depressed level ever since
- CapEx ROI concerns & deepening OpenAI exposure may explain some of the decline, but the real issue may actually be what’s happening with the number of Tokens being processed.
5. AMD Q126 Down Guide Sinks The Stock, Yet Their Q1s Are Almost Exclusively Down Sequentially!
- AMD reported Q425 revenues of $10.27 billion, up 34% YoY, up 11% YoY and well ahead of the $9.6 billion guided midpoint. Full year revenues grew by 34% YoY.
- Q126 outlook of $9.8 billion, down ~5% sequentially, albeit up 32% YoY, sent the share price down more than 7% in after hours trading.
- Over the past twenty years, AMD has only recorded four sequentially up Q1 revenues. Q122 was a COVID anomaly & Q118 was a bitcoin mining anomaly. Go figure!
6. ASEH (3711.TT; ASX.US): Both ATM and EMS Better than past Seasonality in 1Q26.
- 1Q26 Outlook Both ATM and EMS better than past seasonality; overall revenue -5~-7% QoQ, GM down 0.5-1pts QoQ. ATM revenue down mid-single digits.
- Expect ATM to outgrow EMS in 2026. ATM revenue/profit share to rise further. ATM 2026 LEAP at least doubles YoY (to $3.2B USD), demand far exceeds supply.
- Foundries have wafer-level priority, but as volumes scale, customers need second sources.
7. Kyivstar: Operational Resilience & The Hidden Digital Alpha
- Kyivstar reported preliminary 2025 results, with full results to be released in March.
- Revenue and EBITDA growth for 2025 has come in at 25%, roughly in-line with our forecasts.
- KYIV trades at a deep discount to peers despite 25% 2025 revenue growth and the embedded value of its rapidly growing digital platforms. Maintain Structural Long rating.
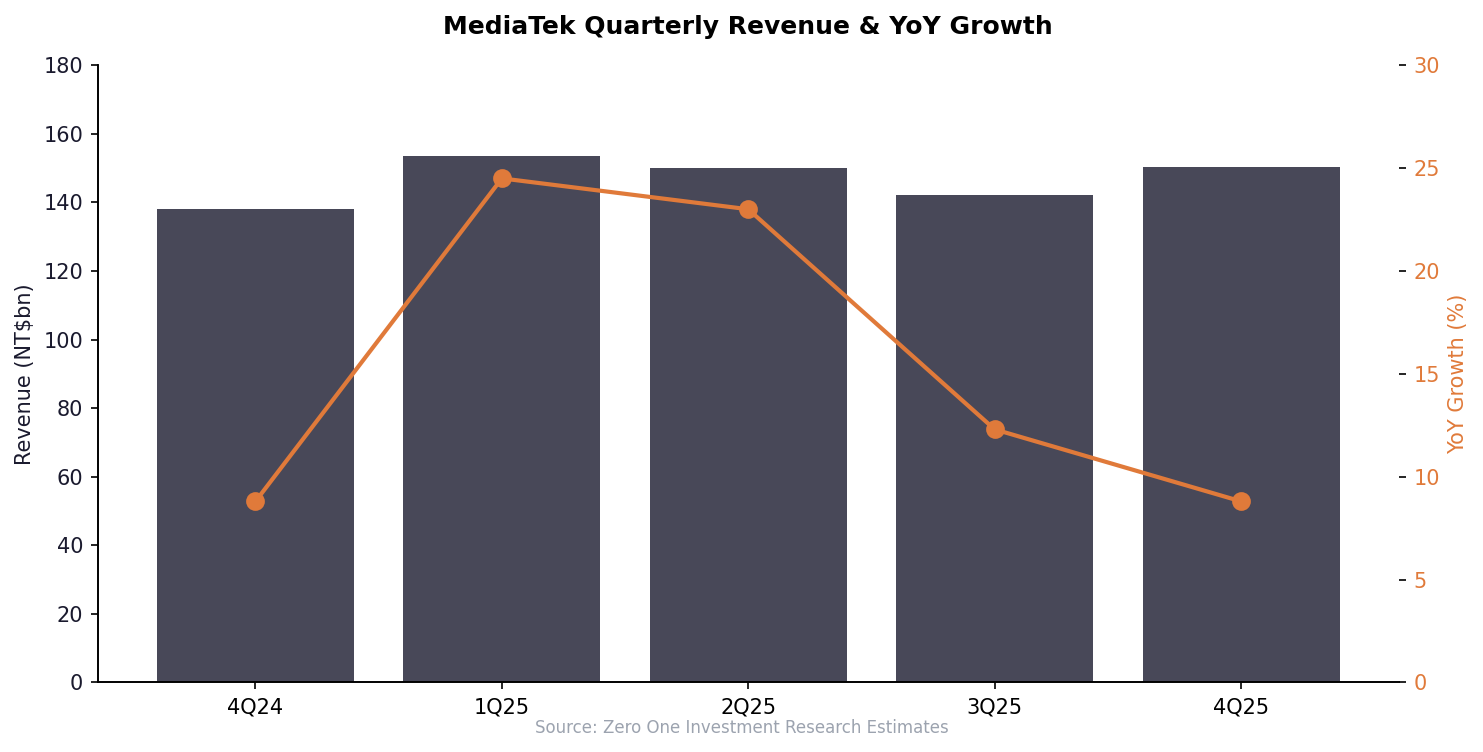
8. MediaTek (2454.TT): 1Q26 Rev Flat To -6% QoQ; Flagship Share Gains.
- 1Q26 Revenue: NT$141.2-150.2bn, flat to -6% QoQ, -2% to -8% YoY; Gross Margin: 46% ±1.5%; OpEx Ratio: 31% ±2%.
- Flagship market share will continue to gain. Blended ASP increasing generation after generation. Overall shipment under pressure from memory situation, but balanced by share/ASP gains.
- 2026 is tough/cyclical, but demand will come back in force (next year or 1.5 years). MediaTek position much stronger than previous cycles (6th year of 5G).
9. Vanguard (5347.TT): 1Q26 Met Expectations, Kicking off a Strong Growth Year.
- 1Q26 & 2026 Guidance: 1Q26 (FX 31.3); Wafer +1-3% q/q; ASP decline by 3-5% q/q; GM 28%-30%.
- In 2026, AI investment wave drives broad semiconductor demand, plus healthy inventory adjustments; mature process capacity squeezed by AI, leading to supply shortages.
- Achievable at 30% GM if capacity fully loaded and ASP appropriately reflects cost increases.
10. Vanguard (5347.TT): Stock Price Rose and Fell Sharply Short-Term; 1Q26 QoQ Expected At -5% to +2%.
- Stock price has surged and declined too quickly in a short time—worth checking if it needs a breather.
- 1Q26 is currently expected to see QoQ around -5% to +2%, hoping to outperform past seasonal performance.
- Consumer demand might partially pull in from 2H26 to 1H26, especially TVs for H2 events or memory influences.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. ASML Q425. Employees Asking For Headcount Reductions? Give Me A Break!
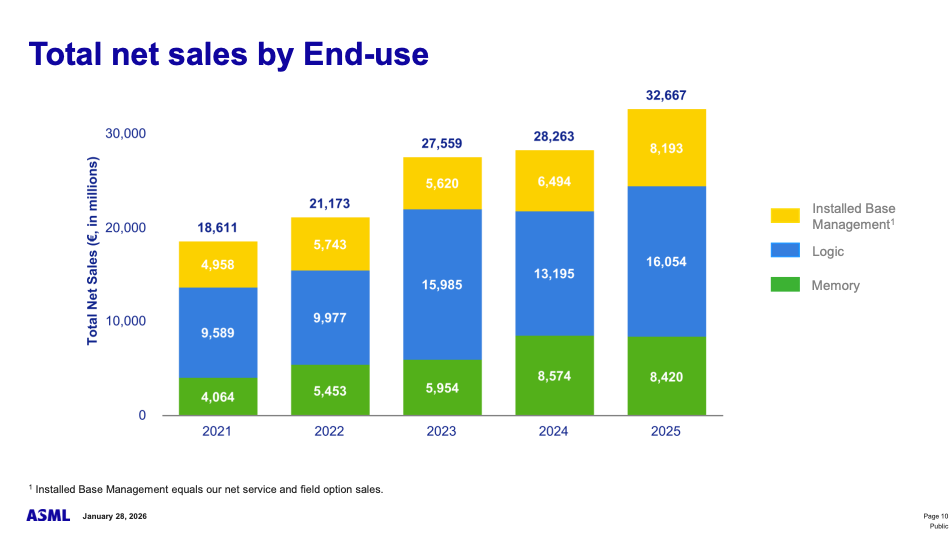
- ASML reported Q425 revenues of €9.7 billion, €200 million above the guided midpoint, up 30% QoQ and up 5% YoY, their highest ever quarterly revenue
- The company guided current quarter revenues of €8.55 billion at the midpoint. For FY2026, they forecasted revenues of €36.5 billion at the midpoint, representing an 11.6% YoY growth
- Out of the blue headcount reductions will see 3,000 out of 4,500 leadership roles eliminated from their Technology Organization, with 1,400 new engineering positions created. Something’s got them spooked…
2. Taiwan Tech Weekly: TSMC’s Affiliate Shows Hyperscalers’ Shift to Reduce Nvidia Dependence
- GUC’s 3nm Breakout Quarter Reveals How Taiwan’s ASIC Leaders Are Capturing AI Chip Demand
- Macronix Shows NOR Flash Cycle Turning as AI Infrastructure Reshapes Memory Demand
- UMC (2303.TT; UMC.US): 1Q26 Revenue Flat, but GM Downside; AI Will Drive Foundry Market Growth.
3. Taiwan Dual-Listings Monitor: Massive TSMC Spread Breakdown
- TSMC: +17.2% Premium; Massive Spread Breakdown; Opens New Long Opportunity
- UMC: +2.7% Premium; Historically Extreme Premium a Good Level to Short
- ChipMOS: -3.0% Discount; Opportunity to Go Long the ADR Spread
4. GUC’s 3nm Breakout Quarter Reveals How Taiwan’s ASIC Leaders Are Capturing AI Chip Demand
- 3nm and below now accounts for 48% of total revenue, up from near-zero two years ago, as TSMC affiliate GUC becomes the go-to partner for hyperscaler custom silicon
- Full-Year revenue grew 36% to NT$34.1bn, outpacing the broader semiconductor industry as custom AI chip demand accelerates
- Companies like Amazon, Google, Microsoft, and Meta have publicly discussed or deployed custom chips for AI inference and training, and GUC’s results suggest these programs are reaching meaningful volume.
5. Fanuc (6954 JP): Sales Strong, Margins Slipping
- With Fanuc’s stock price down 12% in the past two weeks, short-term profit taking may have run its course. .
- Management has lowered FY Mar-26 profit guidance while raising sales guidance – not a good sign.
- Not cheap at 36x new EPS guidance, particularly since AI, which management touts as one of the company’s strengths, is becoming an industry standard.
6. UMC (2303.TT; UMC.US): 1Q26 Revenue Flat, but GM Downside; AI Will Drive Foundry Market Growth.
- 1Q26 guidance: Wafer shipments flat; ASP stable; gross margin in high 20% (QoQ downside); capacity utilization in mid-70% range.
- Foundry market, driven by AI, estimated to reach low-20% growth. UMC’s serviceable market expected in low-single-digit growth.
- 1Q26 gross margin in high 20s mainly due to rising depreciation. 2026 full-year depreciation expected up low-teens YoY, plus raw material and cost inflation.
7. Macronix Shows NOR Flash Cycle Turning as AI Infrastructure Reshapes Memory Demand
- Macronix International (2337 TT)‘s 11pt gross margin recovery shows the NOR Flash downcycle that began in 2022 has rebounded. Good news for Winbond Electronics (2344 TT), GigaDevice Semiconductor (3986 HK).
- AI infrastructure demand is reshaping specialty memory, with server and networking driving NOR growth while NAND supply tightens as fabs prioritize capacity
- Product mix transformation and capex discipline have turned free cash flow positive, signaling improved health across the specialty memory sector. After a long downturn, profitability has rebounded significantly.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. TSMC Q425. CEO “Very Nervous” About An AI Bubble? Yes But…
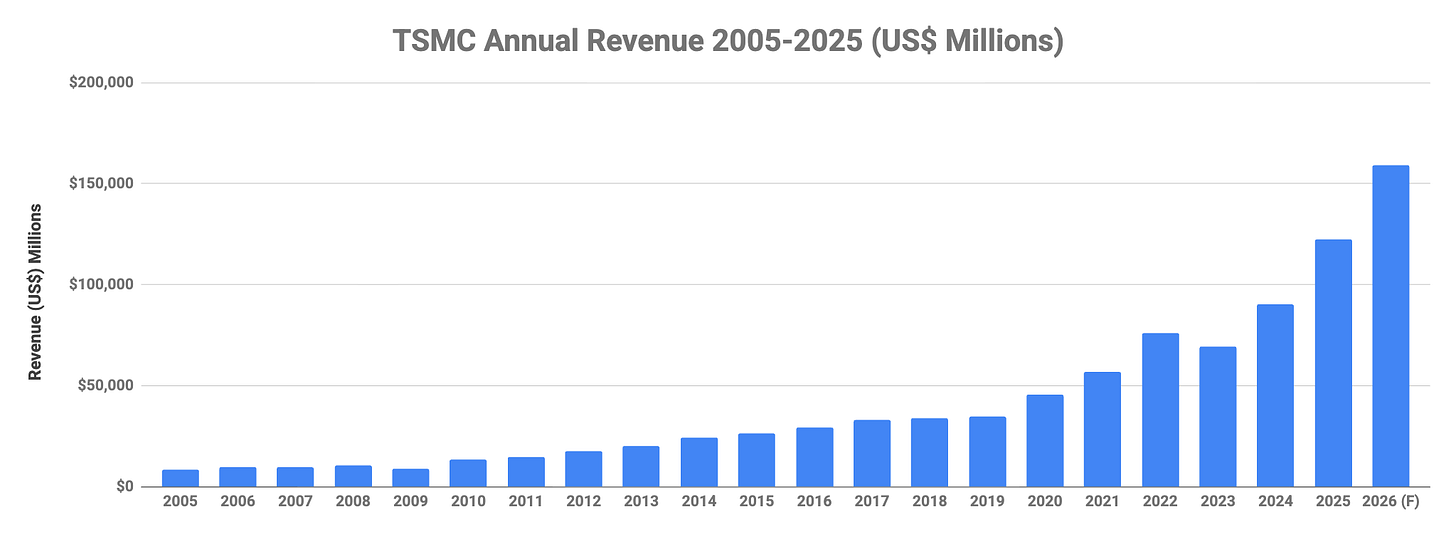
- TSMC last week announced Q425 revenues of $33.7 billion, modestly beating the high end of the forecasted range. Current quarter outlook $35.2 billion, +4% QoQ, +38% YoY
- 2026 CapEx of $54 billion, up 31.7% YoY. This is actually conservative compared to the 74% YoY increase back in 2021, but that didn’t end well. Lessons learned
- Current year growth pegged at ~30 %YoY, long term growth CAGR through 2029 increased from 20% to 25%. Onward and upward!
2. CES 2026. The Finnish Brothers Taking The Technology World By Storm
- CES 2025: Donut Lab announces their revolutionary, in wheel, electric motor, with performance claims blowing the competition out of the water
- CES 2026: Donut Lab announces their revolutionary solid state battery, also with with performance claims blowing the competition out of the water
- Mid 2025: ASILAB, same co-founder as Donut Lab, announces the Asinoid “superintelligence”, built on the architecture of the human brain, designed to think, learn, evolve autonomously like a living organism.
3. Taiwan Tech Weekly: US-Taiwan Trade Deal Cognitive Warfare; HonPrecision Listing; TSMC Upgrades
- Taiwan-U.S. Trade Deal: What Was Agreed — and Why the Noise Around It Matters
- HonPrecision (7769 TT): TWSE Listing & Stock Run-Up Leads to Double Index Inclusion
- TSMC Results: Leading-Edge Nodes Push Margins and Growth Above 2026E Market Assumptions
4. Intel. Between A Rock & A Hard Place
- Q425 revenues of $13.7 billion, flat sequentially, down 4% YoY but $400 million above guided midpoint. Gross margin was 37.9%, 1.4 points above outlook, but down 4.2 points YoY.
- Forecasted Q126 of $12.2 billion, down 11% sequentially and down $500 million YoY. GM to fall 3.4 points QoQ, and EPS will be, well basically there won’t be any EPS
- 18A challenge is switching from yield to reliability. This limits their ability to volume ramp without tanking GM completely, putting the company between a rock and a hard place.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Beat Drives Spread Surge; UMC Sharp Headroom Decline
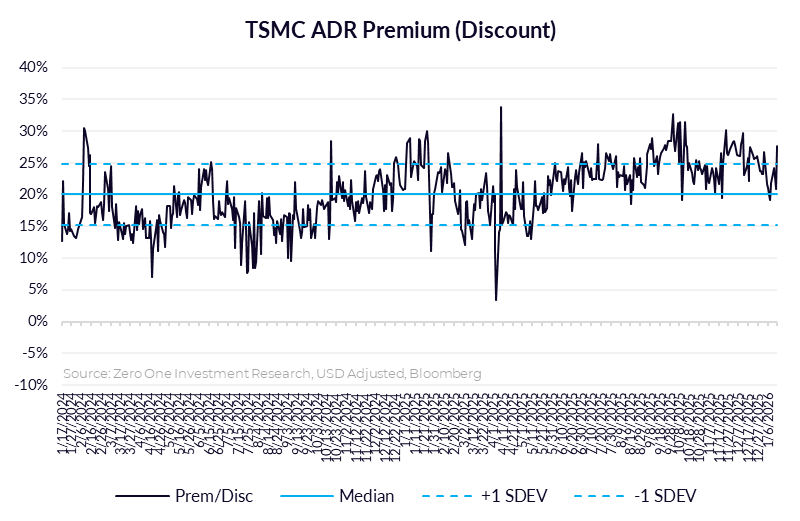
- TSMC: +27.7% Premium; Short the ADR Spread Anywhere Above 24%
- UMC: +1.3% Premium; Large Change in ADR Headroom, Premium Biased to Rise?
- ASE: +1.5% Premium; Consider Going Long the Spread Given Semiconductor Rally
2. TSMC Results: Leading-Edge Nodes Push Margins and Growth Above 2026E Market Assumptions
- TSMC: 4Q25 Results and Guidance Point to 2026E Margins and Revenue Ahead of Consensus
- Management expects AI accelerator revenue to remain strong and compound at a mid-to-high-50% CAGR through 2029E. This growth is complemented by resilient demand for high-end smartphone chips.
- Structural Long: We estimate that TSMC’s guidance implies roughly a 10% uplift required for current 2026E consensus earnings and an all-time high margins outlook.
3. CES 26. NVIDIA Reboots Its AD Stack With Alpamayo But Mercedes-Benz Stays Stumm. Hang On A Momenta!
- NVIDIA launched an all-new AI inspired autonomous driving solution stack at CES last week. Known as Alpamayo, it will make its debut on the Mercedes-Benz flagship 2025 CLA
- Yet, Mercedes-Benz wasn’t mentioned in the press release and wasn’t invited on stage to celebrate with Jensen Huang. Why?
- Mercedes-Benz has a new ADAS partner, China’s Momenta. They are jointly developing an ADAS system for the Chinese market plus a luxury robotaxi fleet for the Abu Dhabi market. Ouch!
4. TSMC (2330.TT; TSM.US): 2026: ~30% YoY Growth Amid Geopolitical & Demand Risks
- 1Q26 Outlook: A. Revenue: 34.6-35.8B (+4% QoQ / +38% YoY) B. FX: 31.6 C. GM: 63-65% D. OPM: 54-56%
- Overall UTR to increase slightly; N3 GM to exceed company average at some point this year. 2nm to start diluting GM in 2H26.
- Don’t know if semiconductor cycle can sustain 3-5 years, but AI will continue for several years.
5. SMIC (981.HK): The EUV Issue Remains, Forcing China to Develop Its Own Technology Now?
- Due to U.S. export restrictions on chip technology to China, mainland China’s semiconductor industry has been significantly impacted.
- Currently, in terms of chip manufacturing technology, ASML Holding NV (ASML NA) advancements in lithography machine-related technology represent a formidable barrier that’s extremely difficult to overcome.
- China must gradually build an upstream supply chain for chips to develop independent chip production technology.
6. CES 2026: Humanoid Robots Are Here & Getting Better. One Day, They May Even Be Useful For Something.
- According to ChatGPT, there was a significant uptick in the scale and scope of humanoid robots on display at CES 2026
- While AMD & NVIDIA humanoid robot keynote segments were terrible, Boston Dynamics impressed and Unitree should really have had a keynote not just an exhibition booth
- Unitree remains on track to IPO later this year at at a $7 billion valuation. When it comes to China’s future role in humanoid robots, think EV, robotaxi, solar power!
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Major Spread Breakdown; ASE & ChipMOS Opportunities
- TSMC: +19.1% Premium; Opportunity to Close Shorts, Set Up New Long
- ASE: -1.6% Discount; Rare Opportunity to Long the Spread at a Discount
- ChipMOS: -7.8% Discount; Short Term Fluke Creates Long the ADR Opportunity
2. TSMC (2330.TT; TSM.US): 2026 Growth >20%; N3/N2 Capacity & Yield; Main Clients’ Focus.
- TSMC (Taiwan Semiconductor Manufacturing) – ADR (TSM US) annual growth rate for 2026 is expected to reach 20%+.
- N3, N4, and N5 processes are currently cross-fabricating to Taichung Fab 15 for metal layer production.
- NVIDIA Corp (NVDA US) is anticipated to be a key customer driving significant growth in 2026, fueled by demand of AI.
3. Taiwan Tech Weekly: TSMC’s Capacity Crunch; Latest Intel on Leading Edge Yield
- Inside TSMC’s Fight to Balance H200 Wafers and CoWoS Packaging
- TSMC (2330.TT; TSM.US): 2026 Growth >20%; N3/N2 Capacity & Yield; Main Clients’ Focus.
- Taiwan Dual-Listings Monitor: TSMC Major Spread Breakdown; ASE & ChipMOS Opportunities
4. SMC (6273 JP): Investing for the Long Term
- Capex is scheduled to rise by 67% this fiscal year, then drop by nearly half. Record investment going into in logistics, technical centers, domestic and overseas production and sales.
- Depreciation likely to increase by about 90% this fiscal year and next before starting to decline. Operating profit down this year and next, before starting to recover in FY Mar-28.
- Chillers for the semiconductor industry and other applications projected to rise from 7% of sales this fiscal year to 11% year after next.