This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. ASML Q425. Employees Asking For Headcount Reductions? Give Me A Break!
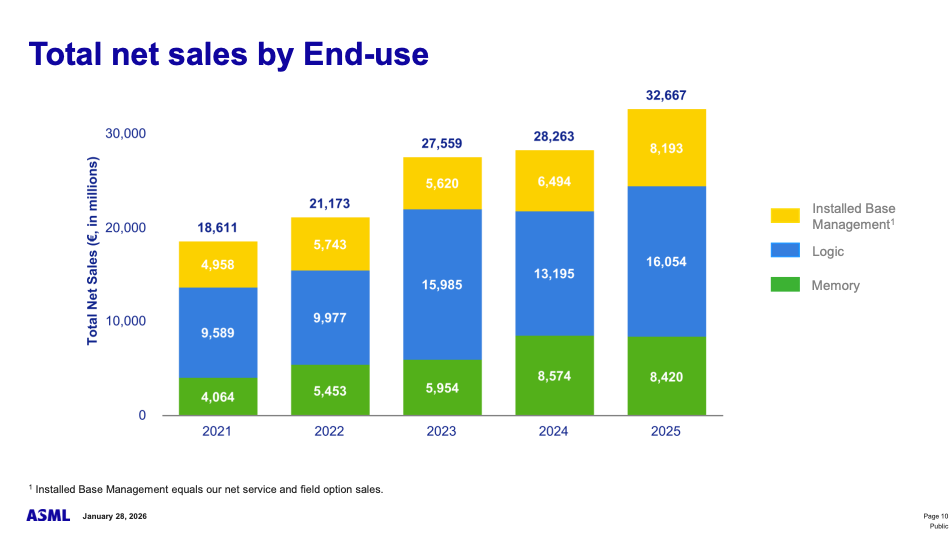
- ASML reported Q425 revenues of €9.7 billion, €200 million above the guided midpoint, up 30% QoQ and up 5% YoY, their highest ever quarterly revenue
- The company guided current quarter revenues of €8.55 billion at the midpoint. For FY2026, they forecasted revenues of €36.5 billion at the midpoint, representing an 11.6% YoY growth
- Out of the blue headcount reductions will see 3,000 out of 4,500 leadership roles eliminated from their Technology Organization, with 1,400 new engineering positions created. Something’s got them spooked…
2. Taiwan Tech Weekly: TSMC’s Affiliate Shows Hyperscalers’ Shift to Reduce Nvidia Dependence
- GUC’s 3nm Breakout Quarter Reveals How Taiwan’s ASIC Leaders Are Capturing AI Chip Demand
- Macronix Shows NOR Flash Cycle Turning as AI Infrastructure Reshapes Memory Demand
- UMC (2303.TT; UMC.US): 1Q26 Revenue Flat, but GM Downside; AI Will Drive Foundry Market Growth.
3. Taiwan Dual-Listings Monitor: Massive TSMC Spread Breakdown
- TSMC: +17.2% Premium; Massive Spread Breakdown; Opens New Long Opportunity
- UMC: +2.7% Premium; Historically Extreme Premium a Good Level to Short
- ChipMOS: -3.0% Discount; Opportunity to Go Long the ADR Spread
4. GUC’s 3nm Breakout Quarter Reveals How Taiwan’s ASIC Leaders Are Capturing AI Chip Demand
- 3nm and below now accounts for 48% of total revenue, up from near-zero two years ago, as TSMC affiliate GUC becomes the go-to partner for hyperscaler custom silicon
- Full-Year revenue grew 36% to NT$34.1bn, outpacing the broader semiconductor industry as custom AI chip demand accelerates
- Companies like Amazon, Google, Microsoft, and Meta have publicly discussed or deployed custom chips for AI inference and training, and GUC’s results suggest these programs are reaching meaningful volume.
5. Fanuc (6954 JP): Sales Strong, Margins Slipping
- With Fanuc’s stock price down 12% in the past two weeks, short-term profit taking may have run its course. .
- Management has lowered FY Mar-26 profit guidance while raising sales guidance – not a good sign.
- Not cheap at 36x new EPS guidance, particularly since AI, which management touts as one of the company’s strengths, is becoming an industry standard.
6. UMC (2303.TT; UMC.US): 1Q26 Revenue Flat, but GM Downside; AI Will Drive Foundry Market Growth.
- 1Q26 guidance: Wafer shipments flat; ASP stable; gross margin in high 20% (QoQ downside); capacity utilization in mid-70% range.
- Foundry market, driven by AI, estimated to reach low-20% growth. UMC’s serviceable market expected in low-single-digit growth.
- 1Q26 gross margin in high 20s mainly due to rising depreciation. 2026 full-year depreciation expected up low-teens YoY, plus raw material and cost inflation.
7. Macronix Shows NOR Flash Cycle Turning as AI Infrastructure Reshapes Memory Demand
- Macronix International (2337 TT)‘s 11pt gross margin recovery shows the NOR Flash downcycle that began in 2022 has rebounded. Good news for Winbond Electronics (2344 TT), GigaDevice Semiconductor (3986 HK).
- AI infrastructure demand is reshaping specialty memory, with server and networking driving NOR growth while NAND supply tightens as fabs prioritize capacity
- Product mix transformation and capex discipline have turned free cash flow positive, signaling improved health across the specialty memory sector. After a long downturn, profitability has rebounded significantly.