This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. TSMC Q425. CEO “Very Nervous” About An AI Bubble? Yes But…
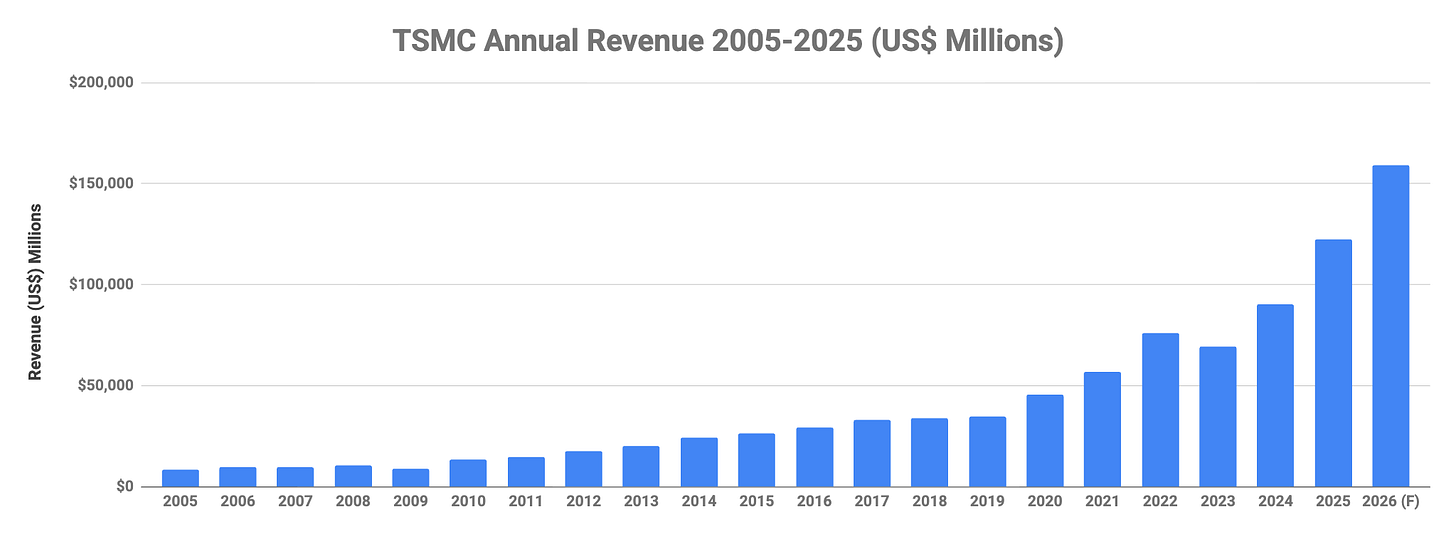
- TSMC last week announced Q425 revenues of $33.7 billion, modestly beating the high end of the forecasted range. Current quarter outlook $35.2 billion, +4% QoQ, +38% YoY
- 2026 CapEx of $54 billion, up 31.7% YoY. This is actually conservative compared to the 74% YoY increase back in 2021, but that didn’t end well. Lessons learned
- Current year growth pegged at ~30 %YoY, long term growth CAGR through 2029 increased from 20% to 25%. Onward and upward!
2. CES 2026. The Finnish Brothers Taking The Technology World By Storm
- CES 2025: Donut Lab announces their revolutionary, in wheel, electric motor, with performance claims blowing the competition out of the water
- CES 2026: Donut Lab announces their revolutionary solid state battery, also with with performance claims blowing the competition out of the water
- Mid 2025: ASILAB, same co-founder as Donut Lab, announces the Asinoid “superintelligence”, built on the architecture of the human brain, designed to think, learn, evolve autonomously like a living organism.
3. Taiwan Tech Weekly: US-Taiwan Trade Deal Cognitive Warfare; HonPrecision Listing; TSMC Upgrades
- Taiwan-U.S. Trade Deal: What Was Agreed — and Why the Noise Around It Matters
- HonPrecision (7769 TT): TWSE Listing & Stock Run-Up Leads to Double Index Inclusion
- TSMC Results: Leading-Edge Nodes Push Margins and Growth Above 2026E Market Assumptions
4. Intel. Between A Rock & A Hard Place
- Q425 revenues of $13.7 billion, flat sequentially, down 4% YoY but $400 million above guided midpoint. Gross margin was 37.9%, 1.4 points above outlook, but down 4.2 points YoY.
- Forecasted Q126 of $12.2 billion, down 11% sequentially and down $500 million YoY. GM to fall 3.4 points QoQ, and EPS will be, well basically there won’t be any EPS
- 18A challenge is switching from yield to reliability. This limits their ability to volume ramp without tanking GM completely, putting the company between a rock and a hard place.