This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
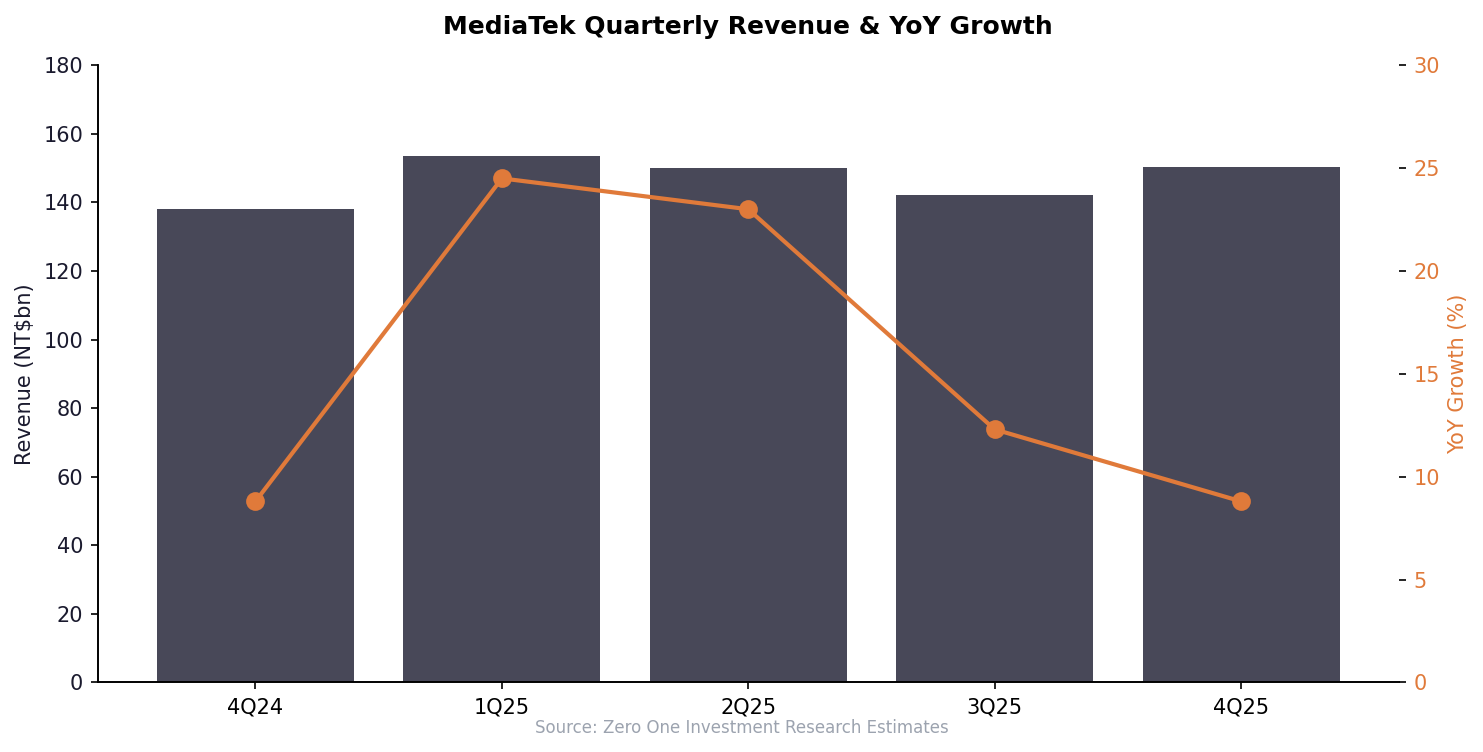
1. Mediatek: Emerging as the Picks-And-Shovels Play on Edge AI Infrastructure
- FY2025 revenue record, profit in-line with consensus. Connectivity business exceeded US$3bn as Wi-Fi 7 tripled and 5G modem doubled, signaling infrastructure buildout for edge AI.
- GB10 partnership with NVIDIA positions MediaTek in the emerging personal AI hardware category as DGX Spark ships to developers and enterprises.
- For investors, MediaTek offers diversified exposure to AI infrastructure buildout across edge and cloud, though near-term share price spike warrants patience.
2. Taiwan Dual-Listings Monitor: Market Volatility Opens Up Multiple Historical Range Breakouts
- TSMC: +19.7% Premium; Rebounds from Near-Term Lows, Latest View on Levels
- UMC: +4.2% Premium; Opportunity to Short the ADR Price Premium
- ChipMOS: +2.7% Premium; Opportunity to Short the ADR Price Premium
3. Keyence (6861 JP): Sliding Down a Mountain of Cash
- Sales are up but profits are lagging, with the gross, operating and net margins all declining in the first nine months of FY Mar-26.
- Overseas sales have risen to two-thirds of total sales, with growth led by Asia and America. This trend seems likely to continue.
- Keyence continues to pile up cash, but for what purpose? With no obvious gearing to AI, its stock price has been underperforming.
4. Microsoft Down ~10% Despite Earnings Beat, Raises & CapEx Growth. What Gives?
- Microsoft delivered a robust Q2FY26 earnings report with revenues of $81.3 billion, up 4.7% QoQ, up 17% YoY and handily beating the high end of the guided range
- It was an excellent quarter with solid beats and raises, yet the share price slumped 10% in after hours trading and has remained at that depressed level ever since
- CapEx ROI concerns & deepening OpenAI exposure may explain some of the decline, but the real issue may actually be what’s happening with the number of Tokens being processed.
5. AMD Q126 Down Guide Sinks The Stock, Yet Their Q1s Are Almost Exclusively Down Sequentially!
- AMD reported Q425 revenues of $10.27 billion, up 34% YoY, up 11% YoY and well ahead of the $9.6 billion guided midpoint. Full year revenues grew by 34% YoY.
- Q126 outlook of $9.8 billion, down ~5% sequentially, albeit up 32% YoY, sent the share price down more than 7% in after hours trading.
- Over the past twenty years, AMD has only recorded four sequentially up Q1 revenues. Q122 was a COVID anomaly & Q118 was a bitcoin mining anomaly. Go figure!
6. ASEH (3711.TT; ASX.US): Both ATM and EMS Better than past Seasonality in 1Q26.
- 1Q26 Outlook Both ATM and EMS better than past seasonality; overall revenue -5~-7% QoQ, GM down 0.5-1pts QoQ. ATM revenue down mid-single digits.
- Expect ATM to outgrow EMS in 2026. ATM revenue/profit share to rise further. ATM 2026 LEAP at least doubles YoY (to $3.2B USD), demand far exceeds supply.
- Foundries have wafer-level priority, but as volumes scale, customers need second sources.
7. Kyivstar: Operational Resilience & The Hidden Digital Alpha
- Kyivstar reported preliminary 2025 results, with full results to be released in March.
- Revenue and EBITDA growth for 2025 has come in at 25%, roughly in-line with our forecasts.
- KYIV trades at a deep discount to peers despite 25% 2025 revenue growth and the embedded value of its rapidly growing digital platforms. Maintain Structural Long rating.
8. MediaTek (2454.TT): 1Q26 Rev Flat To -6% QoQ; Flagship Share Gains.
- 1Q26 Revenue: NT$141.2-150.2bn, flat to -6% QoQ, -2% to -8% YoY; Gross Margin: 46% ±1.5%; OpEx Ratio: 31% ±2%.
- Flagship market share will continue to gain. Blended ASP increasing generation after generation. Overall shipment under pressure from memory situation, but balanced by share/ASP gains.
- 2026 is tough/cyclical, but demand will come back in force (next year or 1.5 years). MediaTek position much stronger than previous cycles (6th year of 5G).
9. Vanguard (5347.TT): 1Q26 Met Expectations, Kicking off a Strong Growth Year.
- 1Q26 & 2026 Guidance: 1Q26 (FX 31.3); Wafer +1-3% q/q; ASP decline by 3-5% q/q; GM 28%-30%.
- In 2026, AI investment wave drives broad semiconductor demand, plus healthy inventory adjustments; mature process capacity squeezed by AI, leading to supply shortages.
- Achievable at 30% GM if capacity fully loaded and ASP appropriately reflects cost increases.
10. Vanguard (5347.TT): Stock Price Rose and Fell Sharply Short-Term; 1Q26 QoQ Expected At -5% to +2%.
- Stock price has surged and declined too quickly in a short time—worth checking if it needs a breather.
- 1Q26 is currently expected to see QoQ around -5% to +2%, hoping to outperform past seasonal performance.
- Consumer demand might partially pull in from 2H26 to 1H26, especially TVs for H2 events or memory influences.