
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
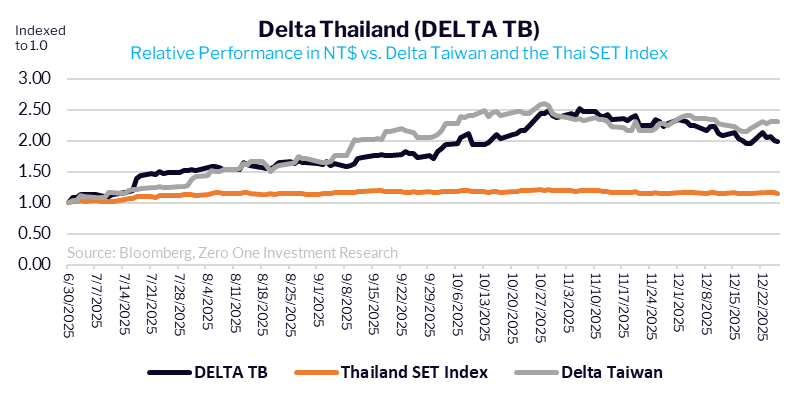
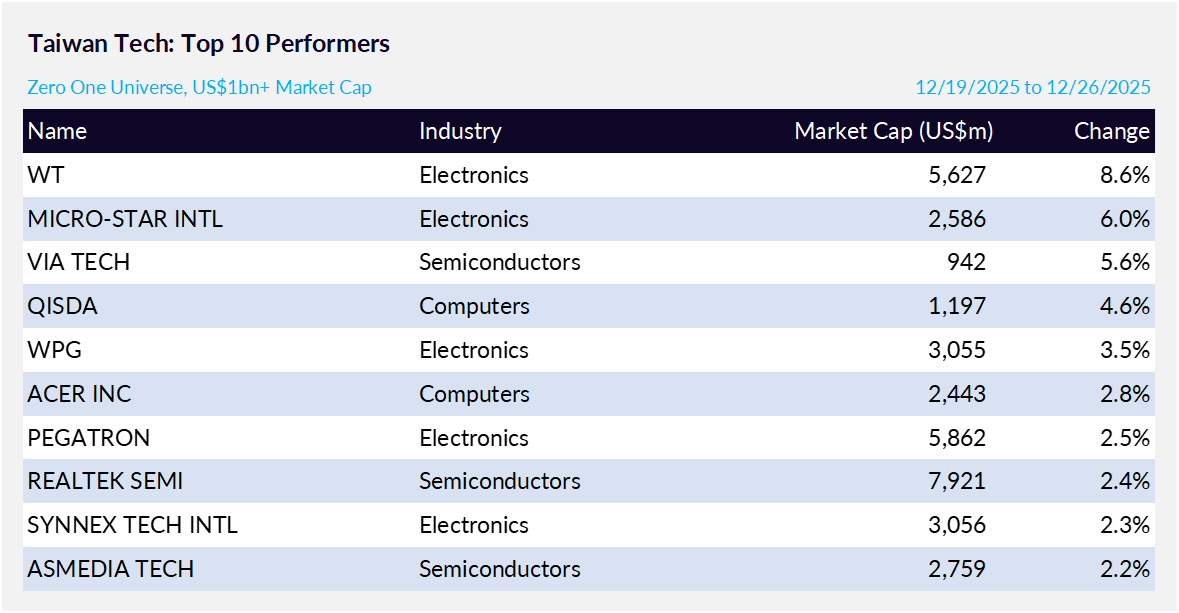
1. Delta Taiwan Vs. Delta Thailand: Valuation Extreme Persists as Growth Leadership Shifts to Parent
- Valuation gap remains extreme and unsupported by fundamentals. Delta Electronics (2308 TT) trades at 28.5x 2025E PER, while Delta Electronics Thailand (DELTA TB) trades at 66.8x.
- LONG Delta Electronics (2308 TT) vs. SHORT Delta Electronics Thailand (DELTA TB). Delta Taiwan delivering materially higher revenue and net income growth 2025E–2026E with a dramatically lower valuation.
- Thailand SET50 Index capping introduces a market structure headwind for Delta Thailand into 2026E; Delta Taiwan expected to outperform Delta Thailand in the new year.
2. NVIDIA’s Shocking $20 Billion Volte-Face On ASIC For Inference
- After year of telling us that NVIDIA GPUs were the only game in town for both Training & Inference, Jensen Huang just dropped $20 billion on licensing Groq’s IP
- Groq’s top talent are also moving to NVIDIA as part of the deal. Their two most senior folks have already updated their LinkedIn profiles to reflect their new roles.
- Whatever lies behind the deal, NVIDIA has surgically removed a potential threat from their inference wheelhouse. How they integrate LPUs without cannibalizing their GPUs will be fascinating to see…
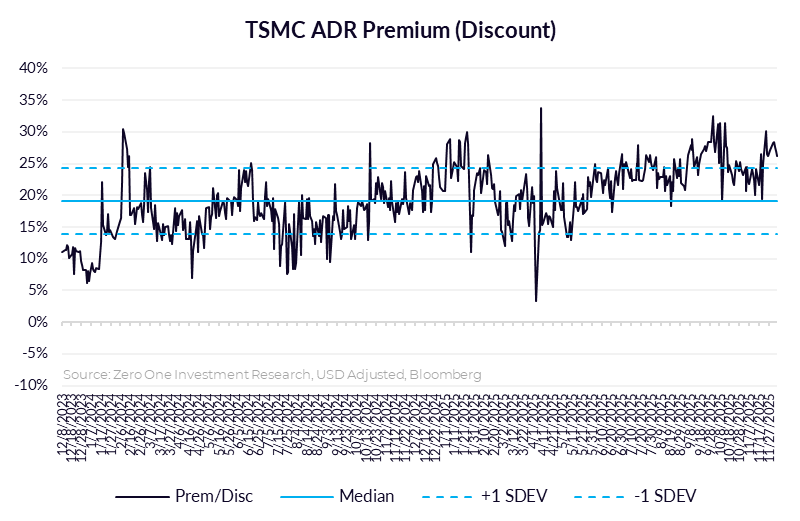
3. Taiwan Dual-Listings Monitor: TSMC Premium Breaks Down Again; ASE Rare Near-Parity Level
- TSMC: +23% Premium; Spread Falls Again from Previous Short Level; Could See Increased Volatility on Taiwan Market Open
- ASE: +0.3% Premium; Great Level to Open a Fresh Long of the Spread
- UMC: +0.4% Premium; Wait for More Extreme Levels Before Going Long or Short
4. Micron’s Monster Quarter Triggers Santa Claus Rally For Beleaguered AI Names
- Micron reported fiscal Q126 revenue of $13.6 billion, up 21% sequentially and up 57% year over year — setting a quarterly record for the third consecutive quarter.
- Micron guided Q226 at $18.70 billion, up 37% sequentially, with gross margin surging to 68% at the midpoint. This quarterly revenue forecast exceeds Micron’s entire revenue for their FY23.
- Memory demand far exceeds available supply right now and prices are soaring. That’s a situation that’s not going to change any time soon. Yikes!
5. Long TSMC / Short UMC: Invest in a Structural Monopoly Vs. A Crowded Recovery
- Recent 3-month performance has been similar for TSMC and UMC despite dramatically different fundamentals for the two companies. TSMC’s outlook is much more resilient into 2026E.
- Technology Nodes Comparison: TSMC dominates leading-edge manufacturing while UMC remains legacy-bound. TSMC higher multiples are justified and less likely to de-rate.
- TSMC ADR vs. Local Shares Consideration: Fundamentally cheaper long side of the trade? TSMC ADR likely the best Long, avoids stock market fund flow differences between US and Taiwan.
6. Taiwan Tech Weekly: Samsung Planning to Leapfrog TSMC 2nm in the U.S.; Why Long TSMC Vs. Short UMC
- Samsung Accelerates 2nm Plan for Immediate Push in U.S. to Take Advantage of TSMC Timing Gap
- Long TSMC / Short UMC: Invest in a Structural Monopoly Vs. A Crowded Recovery
- Delta Taiwan Vs. Delta Thailand: Valuation Extreme Persists as Growth Leadership Shifts to Parent
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Tech Weekly: TSMC a Hidden Capacity Risk for Apple; Memory Pair Long/Short Opportunity
- Hidden Risk for Apple? — TSMC’s Potential 2nm Capacity Bottlneck
- Long/Short SK Vs. Nanya: AI Memory Leadership to Outperform Legacy DRAM’s Final Cyclical Peak
- Himax (HIMX US, Long): Management Call Confirms 2026 Mass-Production Readiness; Increasing Forecasts
2. Taiwan Dual-Listings Monitor: TSMC Spread Rebounds into Short Territory; ChipMOS & CHT Opportunities
- TSMC: +26.3% Premium; Rebounded Back to a Level One Can Short the Spread
- ChipMOS: -2.6% Discount; Opportunity to Go Long the ADR Spread
- CHT: -0.9% Discount; Opportunity to Go Long the ADR Spread
3. Himax (HIMX US, Long): Management Call Confirms 2026 Mass-Production Readiness; Increasing Forecasts
- Management Call — Increased Clarity on Co-Packaged Optics Rollout with Nvidia
- Positioning Inside the TSMC CoWoS / CPO Supply Chain — Margin Accretive Mix Effects; Low Capital Intensity.
- HIMX — Increasing Our Long-Term Forecasts, Reiterate Structural Long Rating
4. Long/Short SK Vs. Nanya: AI Memory Leadership to Outperform Legacy DRAM’s Final Cyclical Peak
- LONG SK Hynix (000660 KS) — Positioned for earnings growth durability through 2026E-2027E, anchored by high bandwidth memory (HBM), high-performance DDR5, and AI server memory content expansion.
- SHORT Nanya Technology (2408 TT) — Rallied sharply as older DDR4 memory prices spiked, driven by end-of-life supply behavior and panic-buying dynamics, which will normalize as the supply side responds.
- Large divergence in product mix quality and of consensus growth forecasts’ resilience to potential market swings favors a Long SK Hynix (000660 KS) vs. Short Nanya Technology (2408 TT) position.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Fermi America’s Unfathomable Progress
- On October 1, Texas-based startup Fermi raised $682.5 million through the sale of 32.5 million shares at $21/share in a remarkable dual listing on both the NASDAQ and LSE
- The company claimed to have a prospective first tenant who had already “put down” a $150 million prepayment
- On December 12, Fermi issued a SEC filing clarifying that no money had been drawn down and the the prospective tenant had terminated their agreement. Currently trading @ ~$9/share
2. TSMC: A Resilient Long Holding Insulated From an AI Slowdown
- Strong Signals TSMC’s 2nm Node Will Take the Company to New Heights
- Apple Anchors 2nm Volumes — Insulates from Potential AI Capex Slowdown
- TSMC Inexpensive and Resilient to Any Potential AI Capex Slowdown
3. Hamamatsu Photonics (6965 JP): The Opportunity in Lasers
- Demand from the semiconductor, medical, quantum computing and defense industries is turning the Laser segment into Hamamatsu Photonics’s new growth driver.
- The acquisition of NKT Photonics brings defense and other technologies, Rheinmetall as a customer in Europe, and potential for greater defense-related sales in Japan.
- Selling at 20x net profit guidance for FY Sep-28, near the bottom of its 10-year P/E range.
4. Taiwan Tech Weekly: TSMC’s Next Node Already Sold Out Before Any Mass Production
- TSMC’s 2nm Node Is Already Sold Out Through 2026E… And Hasn’t Even Started Production Yet
- Taiwan Dual-Listings Monitor: TSMC Historically High Premium Cracks; ChipMOS & CHT Opportunities
- Micron: Nov-25 Beat by 30%, Feb-26 Guidance 80% Above Consensus
5. Pharma Foods International (2929 JP): 1Q Loss from Up-Front Advertising Expenses
- After dropping to a 52-week low on operating and net 1Q losses, the share price has recovered to 20x EPS guidance for FY July 2026.
- The gross margin remains near 80%, but a large increase in advertising expenses put the company into the red. It also boosted sales as planned.
- Management plans to cut back on advertising, aiming for break-even in 2Q and profits in 2H. The dividend yield is now 3.6%. The long-term investment story remains intact.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC & UMC Spreads at Historically Rare Levels
- TSMC: +26.1% Premium; Remains at Level Rarely Maintained for More Than a Week; Good Level to Short the Spread
- UMC: +2.5% Premium; Historically Rare Level is a Short Opportunity
- ASE: +2.9% Premium; Wait Better Short Opportunity at Higher Levels
2. Alphabet. More Of The AI, Less Of The Drama
- Marc Benioff on Gemini 3: I’ve used ChatGPT every day for 3 years. Just spent 2 hours on Gemini 3. I’m not going back. The leap is insane
- Anthropic on expansion of Google Cloud TPU: The expansion is worth tens of billions of dollars and is expected to bring well over a gigawatt of capacity online in 2026.
- DeepMind is Alphabet’s dark horse. AlphaFold is one of the most significant AI-related accomplishments ever. What will they turn their attention to next? Let’s see…
3. Taiwan Tech Weekly: Industry Moves Show Silicon Photonics Becoming Must-Have for Next Gen Compute
- Himax (HIMX US): Silicon Photonics Becomes Strategic Imperative for Foundries, Reinforcing Long View
- Silicon Motion (SIMO US): Multiple Growth Drivers Converging Into 2026E
- Taiwan Dual-Listings Monitor: TSMC & UMC Spreads at Historically Rare Levels
4. Taiwan Dual-Listings Monitor: TSMC Historically High Premium Cracks; ChipMOS & CHT Opportunities
- TSMC: +23% Premium; Has Broken Down from Historically High Level
- ChipMOS: -3.0% Discount; Good Level to Go Long the ADR Spread
- CHT: -1.1% Discount; Good Level to Go Long the ADR Spread
5. Himax (HIMX US): Silicon Photonics Becomes Strategic Imperative for Foundries, Reinforcing Long View
- Latest industry developments show silicon photonics becoming a must-have capability for leading foundries as AI bandwidth needs push the limits of traditional chip interconnect technology.
- Himax is well positioned as a key upstream supplier of CPO optical engines and nano-optics used in TSMC’s silicon-photonics packaging for next-generation NVIDIA platforms.
- Himax’s validated CPO roadmap, proprietary WLO nano-optics platform, and a 2026E-2028E commercialization timeline position the company well. We reiterate our Structural Long rating for Himax into 2026E.
6. Rohm (6963 JP): Renewed Growth, Conservative Guidance & Reasonable Valuation
- Sales are growing again and the company has turned profitable with capacity utilization up and costs down. Guidance for 2H of FY Mar-26 looks conservative.
- Sales of power devices is rising after a long period of weakness, supported by auto, industrial and data center related demand.
- Projected valuations are once again reasonable. The share price should continue to trend upwards.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
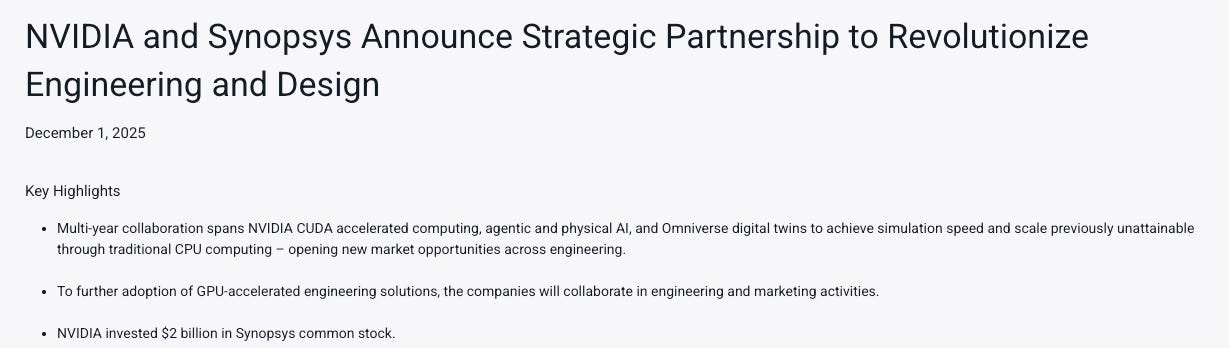
1. NVIDIA Invests $2 Billion In Synopsys. But Why?
- NVIDIA & Synopsys announced a new strategic partnership on Dec 1, mostly covering topics they were already strategically partnering on, with one exception, Cloud-Ready Solutions
- The partnership sees NVIDIA purchase $2 billion worth of Synopsys stock in a private placement. Other, recent, similar strategic partnerships e.g. Siemens & GM, involved no such investment
- They plan to start enabling cloud access for GPU-accelerated engineering solutions. Could this be where that $2 billion finds a home? Is this a new Neocloud in disguise? Let’s see
2. Intel (INTC.US): Apple M-Series in 2027; Intel 18A Is the Key.
- Apple (AAPL US) may outsource iPad CPU production to Intel in 2027.
- U.S. semiconductor reshoring faces fundamental structural barriers, and Trump is trying to blame this by pushing TSMC to move advanced manufacturing technology to the U.S.
- The key variable remains Intel’s 18A execution. However, Intel’s current CEO, Lip-Bu Tan, has not demonstrated an aggressive stance so far.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. NVIDIA. Burry’s Claims Miss The Forest For The Trees. The Real Issues Are Structural, Not Legal
- After taking short positions against Palantir & NVIDIA, Michael Burry has closed his hedge fund and taken to substack to continue his assault on the AI bubble
- While he makes some valid points, these are mainly things everybody already knows and in the end he’s missing the forest for the trees
- There are key structural issues surrounding the AI Infrastructure build out (grid, foundry, memory capacity to mention a few). These will drive course corrections, all by themselves.
2. TSMC (2330.TT; TSM.US): Retired Sr. VP Joins Intel; U.S. Fab Impact; Arizona Earnings Decline.
- TSMC (Taiwan Semiconductor Manufacturing) – ADR (TSM US)’s retired Senior Vice President Dr. Wei-Jen Lo has taken a position at Intel.
- Trump has been in power for less than a year, and the U.S.’s measures have fully revealed its purpose of confrontation between China and the United States.
- TSMC’s Arizona fab profit dropped from NT$4.32 billion in 2Q25 to NT$410 million in 3Q25.
3. Did The Elon & Jensen Clown Show Just Crater The AI Narrative?
- Maybe it’s 10, 20 years something like that. For me that’s long term. Um my prediction is that work will be optional.
- The evidence speaks for itself uh but but but AI and humanoid robots will actually eliminate poverty and Tesla won’t be the only one that makes them.
- There will still be constraints on power like electricity. The fundamental physics elements will still be constraints. Um but um I think at some point uh currency becomes irrelevant.
4. Taiwan Dual-Listings Monitor: TSMC Spread Back in Extreme Range, UMC Discount
- TSMC: +25.8% Premium; Rebounded to High End of Range, Good Level to Open a Short of the ADR Spread
- UMC: -2.2% Discount; Good Level to Open a Short of the ADR Spread
- ASE: +3.2% Premium; Wait for More Extreme Level Before Going Long or Short
5. PC Monitor: Dell/HP Results Support PC Up-Cycle Into 2026E
- AI PCs turning the PC refresh into a gradual, extended up-cycle
- Memory inflation is one of the major margin risks for PC makers in 2026
- Dell’s server business indicates AI factory build-outs becoming a multi-year investment cycle. Remain long Dell, Asustek, Acer.
6. Taiwan Tech Weekly: Rapidus Making Progress… TSMC Impact; Latest PC Results Support 2026E Up-Cycle
- Japan’s Rapidus Moves Ahead With 1.4nm Plans… TSMC Impact? — Latest and Past Analysis
- PC Monitor: Latest Dell/HP Results Support PC Up-Cycle Into 2026E
- TechChain Insights: Factory Visit with One of Taiwan’s Critical Battery Suppliers
7. TechChain Insights: Visit with Taiwan’s Critical Battery Supplier
- Factory visit to GUS Technology reveals Taiwan’s strategic position as a non-China battery supplier for defense and critical infrastructure applications.
- Proprietary pouch cell technology with patents in Taiwan and Japan addresses weight-sensitive applications including drones, underwater vehicles, and data center UPS systems.
- Dual product strategy (safety-focused Mettle Series and energy-dense Hyper Series) targets both commercial reliability and mission-critical performance markets.
8. Taiwan Dual-Listings Monitor: TSMC ADR Spread Deeper in Historically Rare Zone
- TSMC: +27.1% Premium; Increased to More Historically Extreme Level; Deeper in Short Range
- UMC: +2.3% Premium; Good Level to Open a Short of The Spread
- ASE: +2.3% Premium; Wait Better Long Opportunity Near Parity or Below
9. TSMC (2330.TT; TSM.US): Rapidus Plans to Build a Second Fab to Begin 1.4nm Volume Production in 2029
- Rapidus is currently moving in parallel with TSMC (Taiwan Semiconductor Manufacturing) – ADR (TSM US) in targeting the 2nm, and is regarded as Japan’s core force in the advanced-process arena.
- Rapidus plans to build a second fab in Hokkaido in FY2027. The facility is scheduled to begin 1.4nm volume production in 2029 to accelerate the catch-up with global leader TSMC.
- During its mid-October earnings briefing, TSMC stated that 2nm will enter volume production as scheduled in 4Q this year, and that it will begin 1.4nm mass production in 2028.
10. Silicon Motion (SIMO US): Multiple Growth Drivers Converging Into 2026E
- Four growth drivers ramping simultaneously: PCIe5 targeting 40% market share, NAND makers increased outsourcing of controller design, automotive segment approaching 10% of revenue, and datacenter products approaching 5-10% of revenue.
- Near-Term catalysts compelling as memory supply tightness drives controller outsourcing and gross margins approach 49-50%.
- 19x 2026E PER represents good value if company hits targets. While stock carries market pullback risk, we nevertheless maintain our Structural Long rating due to multi-year growth in view.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. OpenAI. Is The Narrative Slowly Disintegrating ?
- Fresh on the heels of his podcast meltdown, Mr. Altman has had to scramble to walk back his CFO’s assertion that a potential federal bailout was on her agenda.
- One of Mr. Altman’s revenue generating ideas is to lease AI compute directly to others. Of course, that’s compute capacity he can’t afford to purchase in the first place.
- Mr. Altman wants OpenAI to be all things to all people all at once. That’s a strategy that rarely ends well. Let’s see..
2. Microsoft. Acting Like There’s An AI Bubble Without Saying There’s An AI Bubble
- Microsoft has significantly course corrected on their compute capacity build out, demurred on their right of first refusal for OpenAI compute demand and adopted a risk off “fungible” compute strategy
- Mr. Nadella thinks AGI as more hype than substance, “jagged” intelligence will remain problematic for a longer, and the true measure of AI success will be measured by GDP growth
- Microsoft stopped reporting AI-driven ARR when the number hit $13 billion six months ago, but why? Broadly deploying AI into productivity tools is a marathon not a sprint.
3. NVIDIA Results: Taiwan Take-Aways — Demand Visibility Implies Strength for Key Suppliers
- NVIDIA’s AI Factory Buildout Signals Multi-Year Demand for Taiwan’s Supply Chain
- TSMC’s Growth Outlook De-Risked by NVIDIA’s Smooth Transition to GB300
- NVIDIA’s Networking Segment Surge Expands System-Level Product Integration Opportunity for Taiwan Ecosystem
4. Taiwan Tech Weekly: NVDA Results- Taiwan Supplier Winners; Silicon Valley’s Substrate- TSMC Slayer?
- NVIDIA Results: Taiwan Take-Aways — Demand Visibility Implies Strength for Key Suppliers
- NVDA Strong Quarter, Strong Guidance, Consensus ~20% Too Low, Stock Is Not Expensive
- Silicon Valley’s Substrate — ASML, TSMC Slayer Or Ideological Pipe Dream?
5. Taiwan Dual-Listings Monitor: TSMC and ASE Premiums Near Spead Short Levels
- TSMC: 24.5% Premium; Near Level to Open Fresh Short of ADR Spread
- ASE: +5.7% Premium; Good Level to Short the ADR Spread
- ChipMOS: -1.7% Discount; Near Discount Level to Go Long the ADR Spread
6. IHI (7013 JP): Orders and Profits Headed Up, Share Price Down
- Sales and operating profit declined YoY in 1H, but new orders were up 17.5% and the book-to-bill ratio rose from 1.00 to 1.25. anagement has raised full-year guidance.
- Aerospace & Defense continue to lead growth, with nuclear energy and Asian EPC making significant contributions to new orders and the restructuring of Industrial Systems & Machinery boosting operating profit.
- Share price down 15% in two weeks to 23x FY Mar-26 EPS guidance. Once again a reasonably valued investment in Japan’s rising defense budget and corporate restructuring.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Tech Weekly: Nvidia Asking TSMC for More Capacity; Apple to Disintermediate Telcos?
- Nvidia Pushes TSMC for More Capacity as AI Chip Demand Surges
- Apple Expands Its Satellite Ambitions for iPhones Beyond Just Emergencies — A Step Towards Disintermediating Telcos?
- Nvidia’s International HQ in Taipei Deal Clears Final Hurdle — Boost for Taiwan 2026E-2027E
2. Substrate. ASML, TSMC Slayer Or Ideological Pipe Dream?
- Silicon valley startup Substrate made waves two weeks ago when they emerged from stealth mode to announce a revolutionary new tool they claim will rival ASML’s EUV lithography capability
- Substrate simultaneously plans to build next-generation semiconductor fabs to return America to dominance in semiconductor production and will use their technology—a new form of advanced X-ray lithography—to power them.
- For a three year old startup, whos CEO has zero documented experience of semiconductors or lithography, these are bold claims indeed. This should be interesting!
3. Humanoid Robots Won’t Take Your Job, We’ve Just Decided Not To Give You The Job In The First Place.
- Jensen Huang claims that the world is running out of workers & there will be a shortage of 50 million workers by the end of the decade. Enter humanoid robots.
- Elon Musk claims that AI and robots will take all our jobs, working will be optional and we can grow vegetables while he’s on his way to becoming a trillionaire
- Technology and society are rapidly approaching a critical decision point. Jobs for robots or for humans?
4. SMIC (981.HK): Although GM May Decline Slightly, Revenue Is Expected to Continue Growing in 4Q25.
- Revenue in 3Q25 was 7.8% higher than in 2Q25, in line with stronger seasonal demand. GM: 22.0% in 3Q25, compared with 20.4% in 2Q25 and 20.5% in 3Q24.
- The Company expects: Revenue Flat to up 2% quarter-over-quarter (QoQ). Gross Margin: Between 18% and 20%.
- SMIC’s stock price has risen 160.7% year-to-date in 2025, outperforming Taiwan Semiconductor (TSMC) – ADR (TSM US) at 44.2% and United Microelectron Sp Adr (UMC US) at 10.8%.
5. Hamamatsu Photonics (6965 JP): Capex Peaking, Profits to Rebound
- Announced last Friday, FY Sep-25 sales and net profit were in line with guidance, but operating profit fell short. On Monday, the shares dropped 4.5%, wiping out a month’s gains.
- Looking ahead, management expects three years of sales and profit growth as capex declines, depreciation and R&D level off, and the NKT Photonics acquisition approaches breakeven.
- In this scenario, semiconductor, bio-medical, defense and quantum computing applications should drive 3-year sales growth of 24% and a 71% increase in net profit, bringing the P/E down to 20X.
6. Silergy (6415.TT): 4Q25 Flat or Slightly Upside; Early Gen4 Yields Remain Non-Comparable.
- 4Q25 seasonal outlook? Silergy expects flat to slightly up QoQ, similar to past years.
- Silergy does see consolidation, and given its stronger financials, product breadth, and R&D capabilities, the company remains a top supplier and will continue to gain share.
- Will 1H next year be better than 2H this year?Hard to say because of Chinese New Year seasonality.We expect YoY growth, but not strong yet.
7. TechChain Insights: ChipMOS Indicates Memory Industry Surge into 2026E; Smartphones Currently Soft
- This assembly and testing leader provides fresh insight into the state of display, memory, consumer, enterprise, and industrial end markets.
- ChipMOS: Memory Industry Strength Offsets Display Industry Weakness. Memory strength seen into 2026E. Company noted soft smartphone industry panel demand currently.
- Management signals sustained memory upcycle; disciplined capex to serve multi-year AI and datacenter growth. We rate ChipMOS shares as a Structural Long.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Microsoft’s OpenAI Conundrum
- In Q126, Microsoft recorded $4.1 billion in net losses from investments in OpenAI, up from $688 million in the year ago quarter.
- The newly updated partnership between Microsoft and OpenAI has many clauses contingent on when (not if) AGI gets declared. Since AGI has no actual definition, an expert panel will decide.
- Sam Altman dreams of an OpenAI IPO so that detractors can be lured into shorting the stock and getting burned in the process. Revenue growth is a touchy subject, apparently
2. Taiwan Tech Weekly: Mediatek’s Power Move for 2nm Chips; Yet More TSMC Pricing Power
- TSMC Sets Sights on 3-10% Price Rises for Advanced Nodes
- MediaTek’s Leap Into the 2nm Era — Leading Edge Node Signals Market Leadership Ambitions
- Mediatek 3Q25: Good News (ASIC Revenue) But Weak Margins Getting Weaker. Stock Not Attractive.
3. NEC (6701 JP): Tie-Up with Siemens Adds to Growth Potential
- NEC and Siemens plan to develop an automated robot teaching system for faster set-up and more efficient operation of production lines incorporating multiple robots.
- NEC’s FY Mar-26 guidance raised on strong 1H results. BluStellar, which includes digital twins for robot teaching, grew faster than expected.
- Aerospace/Defense led sales growth and followed BluStellar in operating profit. Improving product mix and rising Japanese defense budget point to growing long-term potential.
4. Novatek (3034.TT): 4Q25 Decline; AI-Integrated Products Currently ~20% of SoC Revenue and Growing.
- 4Q25 Guidance: Revenue NT$22–23bn (declined 4.9% QQ); Entering traditional low season. Gross Margin: 35–38%; Operating Margin: 14.5–17.5%.
- AI-Integrated products currently ~20% of SoC revenue and growing. Image SoC / New Camera Trends: New AI Vlog cameras seeing positive demand.
- Key 2026 factors: FX, gold price, raw materials (KGD, substrate) supply.
5. Yageo 3Q25 Take-Aways: Passive Components Leader Benefitting from AI Applications Demand
- Strong AI Demand Sustains Revenue Growth Despite the Seasonal Headwinds
- Recent Shibaura Acquisition Enhances Yageo’s Strategic Positioning in Specialty Components
- We rate Yageo as a Structural Long – AI Content Cycle Should Drive Sustainable Mix Improvement
6. Vanguard (5347.TT): 3Q25 EPS Missed Expectations; 4Q25 and 1Q26 Decline Milder Than Seasonal Trend
- Management expects 4Q25 wafer shipments to decline 6–8% QoQ, while ASP should rise 4–6% QoQ, mainly due to lower DDI shipments.
- The AI revenue share has risen from a low-single-digit percentage in 2024 to a high-single-digit level in 2025.
- The worst phase of mature-node overcapacity has passed, and pricing pressure should ease entering 2026.
7. Taiwan Dual-Listings Monitor: TSMC Premium Eases Down; UMC & CHT Opportunity Levels
- TSMC: +21.8% Premium; Wait for Lower Premium Before Fresh Long
- UMC: +2.2% Premium; Good Level to Short the ADR Premium
- CHT: -2.0% Discount; Near Level to Go Long the ADR Spread

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Near Fresh Spread Short Level; ChipMOS Rare Discount
- TSMC: +23.4% Premium; Near Levels to Open Fresh ADR Spread Short
- ASE: +0.3% Premium; Good Level to Long the ADR Spread
- ChipMOS: -7.5% Discount; Local Shares Rally Makes ADR Deeply Discounted
2. Taiwan Tech Weekly: Apple’s Macbook Windfall; Yageo’s Rally; TSMC’s Massive Rare Earth Stockpile
- Windows 10’s End-of-Life Becomes Apple’s Windfall as Second Fastest Growing Computer Brand
- Eyes on Yageo Results Coming October 30 After 35% 1-Week Surge
- China Tightens Rare Earth Grip: TSMC Says It’s Prepared with Inventory
3. SK Hynix Q325. HBM, DRAM, NAND All Sold Out Through 2026
- SK Hynix reported Q325 revenues of ₩34.45 trillion, up +10% QoQ and up 39% YoY representing an all time quarterly revenue record
- Now given the customers demand and the company’s capacity for next year not only HBM but DRAM and NAND capacity has essentially been sold out.
- DRAM margin could rise closer to HBM but the company does not plan to immediately adjust the capacity mix based on what can be a short-lived change in profitability
4. MediaTek (2454.TT): 4Q25 GM Eases on Mix; 2025 Record Revenue; 2026 AI Upswing Begins
- 4Q25 Guidance: Revenue is NT$142.1 – 150.1 bn (+0 – 6% QoQ, +3 – 9% YoY); Gross margin is 46% ± 1.5ppt; Opex ratio is 31% ± 2ppt.
- Cloud ASIC TAM: Raised from US$40bn → ≥ US$50bn by 2028; MediaTek targeting ≥ 10–15% share; Gross Margin: 4Q dip from mix; 2026 to benefit from repricing + high-value allocation
- MediaTek continues to execute on a dual-engine AI strategy. Despite near-term margin pressure from mix and FX, the company is building a foundation for sustainable profit growth.
5. Realtek Results Readthrough: Normalization Marks Pause Before Next PC Wave
- PC upgrade mini-cycle front-loaded: Realtek 3Q25 results reflected normalization after Windows 10-related demand pulled forward into 1H25, with revenue and margins easing sequentially but remaining solid.
- Diversification offsets softness: Communications infrastructure and automotive Ethernet continued to expand, with stronger growth outside China and resilient contribution from next-gen connectivity and Wi-Fi 7 adoption.
- Cautious near term, constructive on 2026E: Inventory build and tariff uncertainty temper 4Q outlook, but management expects a strong 1Q26 rebound as PC inventories normalize and AI-driven peripherals lift ASPs.
6. UMC (UMC US / 2303 TT): Adeptly Navigating Foundry Industry Transition From Scale to Specialization
- UMC’s 3Q25 results reaffirm its strategic shift toward specialty foundry leadership.
- Revenue was stable at NT$59.13bn with improving utilization and 22nm technology now contributing over 10% of sales. Gross margins remain robust.
- UMC’s growing 22/28nm portfolio, Intel partnership in Arizona, and focus on power-efficient packaging highlight how the maturing foundry sector is moving away from pure node competition and towards application-specific differentiation.
7. ASEH (3711.TT; ASX.US): 3Q25 ATM Record High; 4Q25 Modest Growth; 2025 ATM Revenue +20% YoY (USD)
- 4Q25 Outlook: Revenue is expected to grow by 1% to 2% QoQ. Both of GM and OPM are projected to increase by 0.70 to 1 percent QoQ.
- Growth continues to be driven by AI and HPC demand, with testing revenue exceeding expectations and offsetting minor shortfalls in packaging due to geopolitical uncertainties.
- With 2025 test revenue expected to grow at roughly twice the pace of packaging revenue. Investment priorities are focused on wafer probing capacity for both AI and non-AI devices
8. UMC (2303.TT; UMC.US): 4Q25 Upbeat; 1Q26 May Be a Challenging Quarter Due to Expected Seasonality.
- 4Q25 Guidance: Wafer shipment will remain flat. ASP in US dollars will remain firm. Gross margin will be approximately in the high 20% range.
- Expect interposer technology capabilities to serve the market when volume comes in late 2026 or sometime in 2027.
- 12nm PDK is expected to be ready for the first wave of customers in January 2026. Customer product takeout is expected at the beginning of 2027.