This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
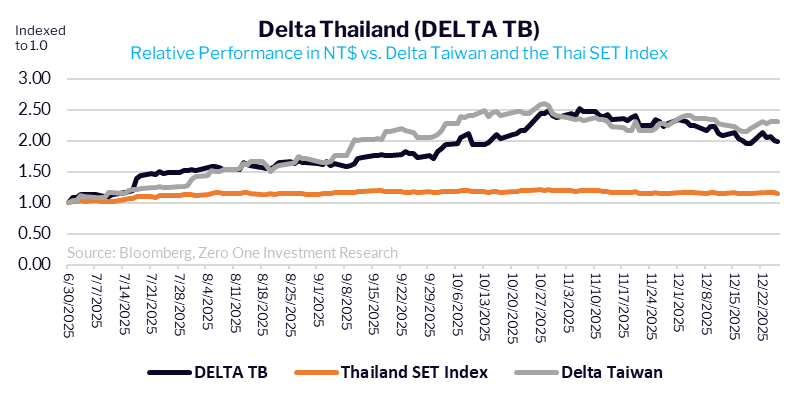
1. Delta Taiwan Vs. Delta Thailand: Valuation Extreme Persists as Growth Leadership Shifts to Parent
- Valuation gap remains extreme and unsupported by fundamentals. Delta Electronics (2308 TT) trades at 28.5x 2025E PER, while Delta Electronics Thailand (DELTA TB) trades at 66.8x.
- LONG Delta Electronics (2308 TT) vs. SHORT Delta Electronics Thailand (DELTA TB). Delta Taiwan delivering materially higher revenue and net income growth 2025E–2026E with a dramatically lower valuation.
- Thailand SET50 Index capping introduces a market structure headwind for Delta Thailand into 2026E; Delta Taiwan expected to outperform Delta Thailand in the new year.
2. NVIDIA’s Shocking $20 Billion Volte-Face On ASIC For Inference
- After year of telling us that NVIDIA GPUs were the only game in town for both Training & Inference, Jensen Huang just dropped $20 billion on licensing Groq’s IP
- Groq’s top talent are also moving to NVIDIA as part of the deal. Their two most senior folks have already updated their LinkedIn profiles to reflect their new roles.
- Whatever lies behind the deal, NVIDIA has surgically removed a potential threat from their inference wheelhouse. How they integrate LPUs without cannibalizing their GPUs will be fascinating to see…
3. Taiwan Dual-Listings Monitor: TSMC Premium Breaks Down Again; ASE Rare Near-Parity Level
- TSMC: +23% Premium; Spread Falls Again from Previous Short Level; Could See Increased Volatility on Taiwan Market Open
- ASE: +0.3% Premium; Great Level to Open a Fresh Long of the Spread
- UMC: +0.4% Premium; Wait for More Extreme Levels Before Going Long or Short
4. Micron’s Monster Quarter Triggers Santa Claus Rally For Beleaguered AI Names
- Micron reported fiscal Q126 revenue of $13.6 billion, up 21% sequentially and up 57% year over year — setting a quarterly record for the third consecutive quarter.
- Micron guided Q226 at $18.70 billion, up 37% sequentially, with gross margin surging to 68% at the midpoint. This quarterly revenue forecast exceeds Micron’s entire revenue for their FY23.
- Memory demand far exceeds available supply right now and prices are soaring. That’s a situation that’s not going to change any time soon. Yikes!
5. Long TSMC / Short UMC: Invest in a Structural Monopoly Vs. A Crowded Recovery
- Recent 3-month performance has been similar for TSMC and UMC despite dramatically different fundamentals for the two companies. TSMC’s outlook is much more resilient into 2026E.
- Technology Nodes Comparison: TSMC dominates leading-edge manufacturing while UMC remains legacy-bound. TSMC higher multiples are justified and less likely to de-rate.
- TSMC ADR vs. Local Shares Consideration: Fundamentally cheaper long side of the trade? TSMC ADR likely the best Long, avoids stock market fund flow differences between US and Taiwan.
6. Taiwan Tech Weekly: Samsung Planning to Leapfrog TSMC 2nm in the U.S.; Why Long TSMC Vs. Short UMC
- Samsung Accelerates 2nm Plan for Immediate Push in U.S. to Take Advantage of TSMC Timing Gap
- Long TSMC / Short UMC: Invest in a Structural Monopoly Vs. A Crowded Recovery
- Delta Taiwan Vs. Delta Thailand: Valuation Extreme Persists as Growth Leadership Shifts to Parent