This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SpaceX Just Filed Their S-1 & It’s A Doozy
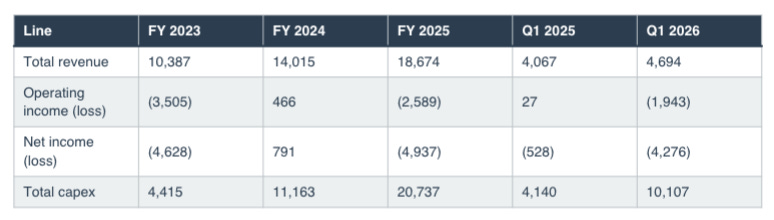
- On May 20, 2026, SpaceX filed an S-1 registration statement with the SEC. Ticker: SPCX. Listing venue: Nasdaq plus the brand-new Nasdaq Texas, headquartered at 1 Rocket Road, Starbase, Texas
- Two share classes. Class A = 1 vote. Class B = 10 votes. Class B shareholders separately elect a majority of the board as a class. Elon taking no chances.
- SpaceX key plans include a permanent human colony on Mars with at least one million inhabitants and launching orbital data centers capable of delivering 100 terawatts of compute per year.
2. Intel @JPM 54th Annual TMT. Key Takeaways & Full Transcript
- This is easily the most consequential interview LBT has given since taking over the CEO role at Intel. It’s essential material for both existing and would-be investors
- 18A is in volume; 14A is the foundry pitch. Panther Lake on 18A has 200 design wins and now finally has wafer supply. 14A
- Advanced packaging is a quiet upside lever. Customers are willing to prepay substrate commitments in the billions of dollars to lock in Intel’s EMIB-T capacity
3. NVIDIA Q1 FY27. Stellar Beat & Raise With Vera CPU Adding A Further $200 Billion TAM
- NVIDIA reported record Q1 FY27 revenue of $81.6 billion, +85% from a year ago and +20% sequentially, well ahead of their guided $78 billion, as has now become their SOP
- DC compute revenue was a record $60.4 billion, +77% YoY, +18% QoQ. DC networking revenue was a record $14.8 billion, +199% YoY and +35% QoQ
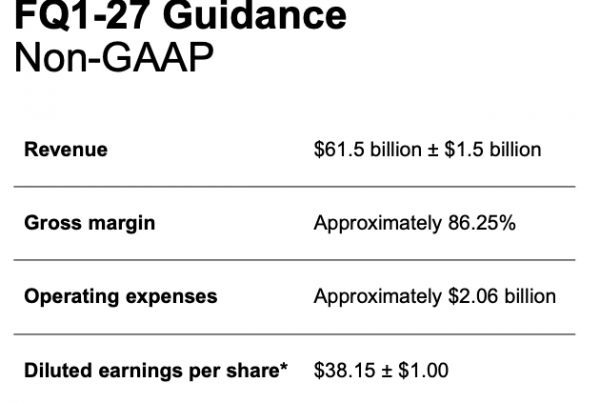
- Current quarter revenue pegged at $91.0 billion, with no China DC compute revenue included.
4. Qualcomm @JPM 54th Annual TMT. Key Takeaways & Full Transcript
- Qualcomm is entering data center with a three-product attack: custom silicon (revenue starting this year), data center CPU, and an AI inference accelerator (AI 200 / AI 250).
- Robotics framed as the next ADAS. Same content range starting point as Auto ($300-$2,000 per platform), 3-5 year horizon to material revenue. Multiple named partners plus many undisclosed China partners
- Smartphones. June quarter is the trough. Two quarters of channel drawdown have run their course. Confidence anchored on actual channel data plus Sep/Dec device launches
5. Micron @ JPM 54th Annual TMT Conference: Key Takeaways & Full Transcript
- Our financial outlook has strengthened since our last earnings call. We’re on track for another substantial record free cash flow in fiscal Q3. Our balance sheet has never been stronger
- Greenfield expansion is now mandatory. The industry needs new clean-room space, not just new tools, and clean-room construction is measured in years, not quarters.
- Multi-Year EUV supply agreement with ASML has been concluded covering 1-delta and subsequent generations. EUV deployment will increase materially at 1-delta versus 1-gamma.
6. Seagate @JPM 54th Annual TMT: Key Takeaways & Full Transcript
- Millions of HAMR drives shipped. Mosaic 3 is qualified at all planned CSPs. Mosaic 4 (4 TB/platter) is qualified at two large CSPs. High confidence to reach 5 TB/platter.
- Painful multi-year initial Mosaic 3 qualification was one-time learning-curve event. Mosaic 4 ran through two large CSPs at traditional qualification timelines. Expectation set: Mosaic 5 and 6 should look similar.
- Capacity expansion is happening through technology, not floor space. Seagate is targeting mid-20s percent exabyte growth and explicitly not adding new factories. We all know that that means, right?
7. Intel @JPM 54th Annual TMT. Full Transcript Attached.
- Millions of HAMR drives shipped. Mosaic 3 is qualified at all planned CSPs. Mosaic 4 (4 TB/platter) is qualified at two large CSPs. High confidence to reach 5 TB/platter.
- Painful multi-year initial Mosaic 3 qualification was one-time learning-curve event. Mosaic 4 ran through two large CSPs at traditional qualification timelines. Expectation set: Mosaic 5 and 6 should look similar
- Capacity expansion is happening through technology, not floor space. Seagate is targeting mid-20s percent exabyte growth and explicitly not adding new factories. We all know that that means, right?
8. Tower Semiconductor Q1 2026. It’s All About Silicon Photonics Now!
- Tower Reported Q1 2026 revenue of $413.6 million, +15.5% YoY but -6.0% QoQ from Q4 2025’s record $440.2 million. This was marginally ahead of the forecasted midpoint of $412 million.
- Tower guided for a record current quarter with revenues of $455 million, while flagging that we should expect QoQ growth for both revenue and gross margin throughout the year
- Tower reported $1.3 billion of contracted silicon photonics revenue for 2027 from their largest SiPho customers, backed by approximately $290 million in prepayments already received. Oh my!
9. SMIC Q1 2026. Dumping The Dividend To Maintain The CapEx Cadence
- SMIC reported Q1 2026 revenues of $2,505 million, up 0.7% QoQ and up 11.5% YoY. Gross margin was 20.1%, up 0.9 pp QoQ but down 2.4 pp YoY.
- For the second quarter 2026, SMIC expects revenue to increase by 14% to 16% sequentially and growth margin is expected to be in the range of 20% to 22%
- CapEx is expected to remain similar to CY2025 at ~$8 billion. Depreciation expenses are expected to increase 30% YoY. Bye bye dividend!
10. Amkor Expands Its Arizona Investment, For the Third Time.
- As part of its long-term growth strategy, Amkor has now secured an additional 67-acre parcel adjacent to the existing campus, providing strategic flexibility to support future expansion and evolving customer demand.
- Back in Nov 2023, Amkor Technology, announced a $2 billion, 500k square foot cleanroom space, 2000 employee investment in Arizona, yet ground breaking didn’t begin until two years later
- In November 2025, Amkor expanded their Arizona investment to $7 billion, 750k square foot clean room space and 3,000 employees, yet production still won’t start until early 2028