This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
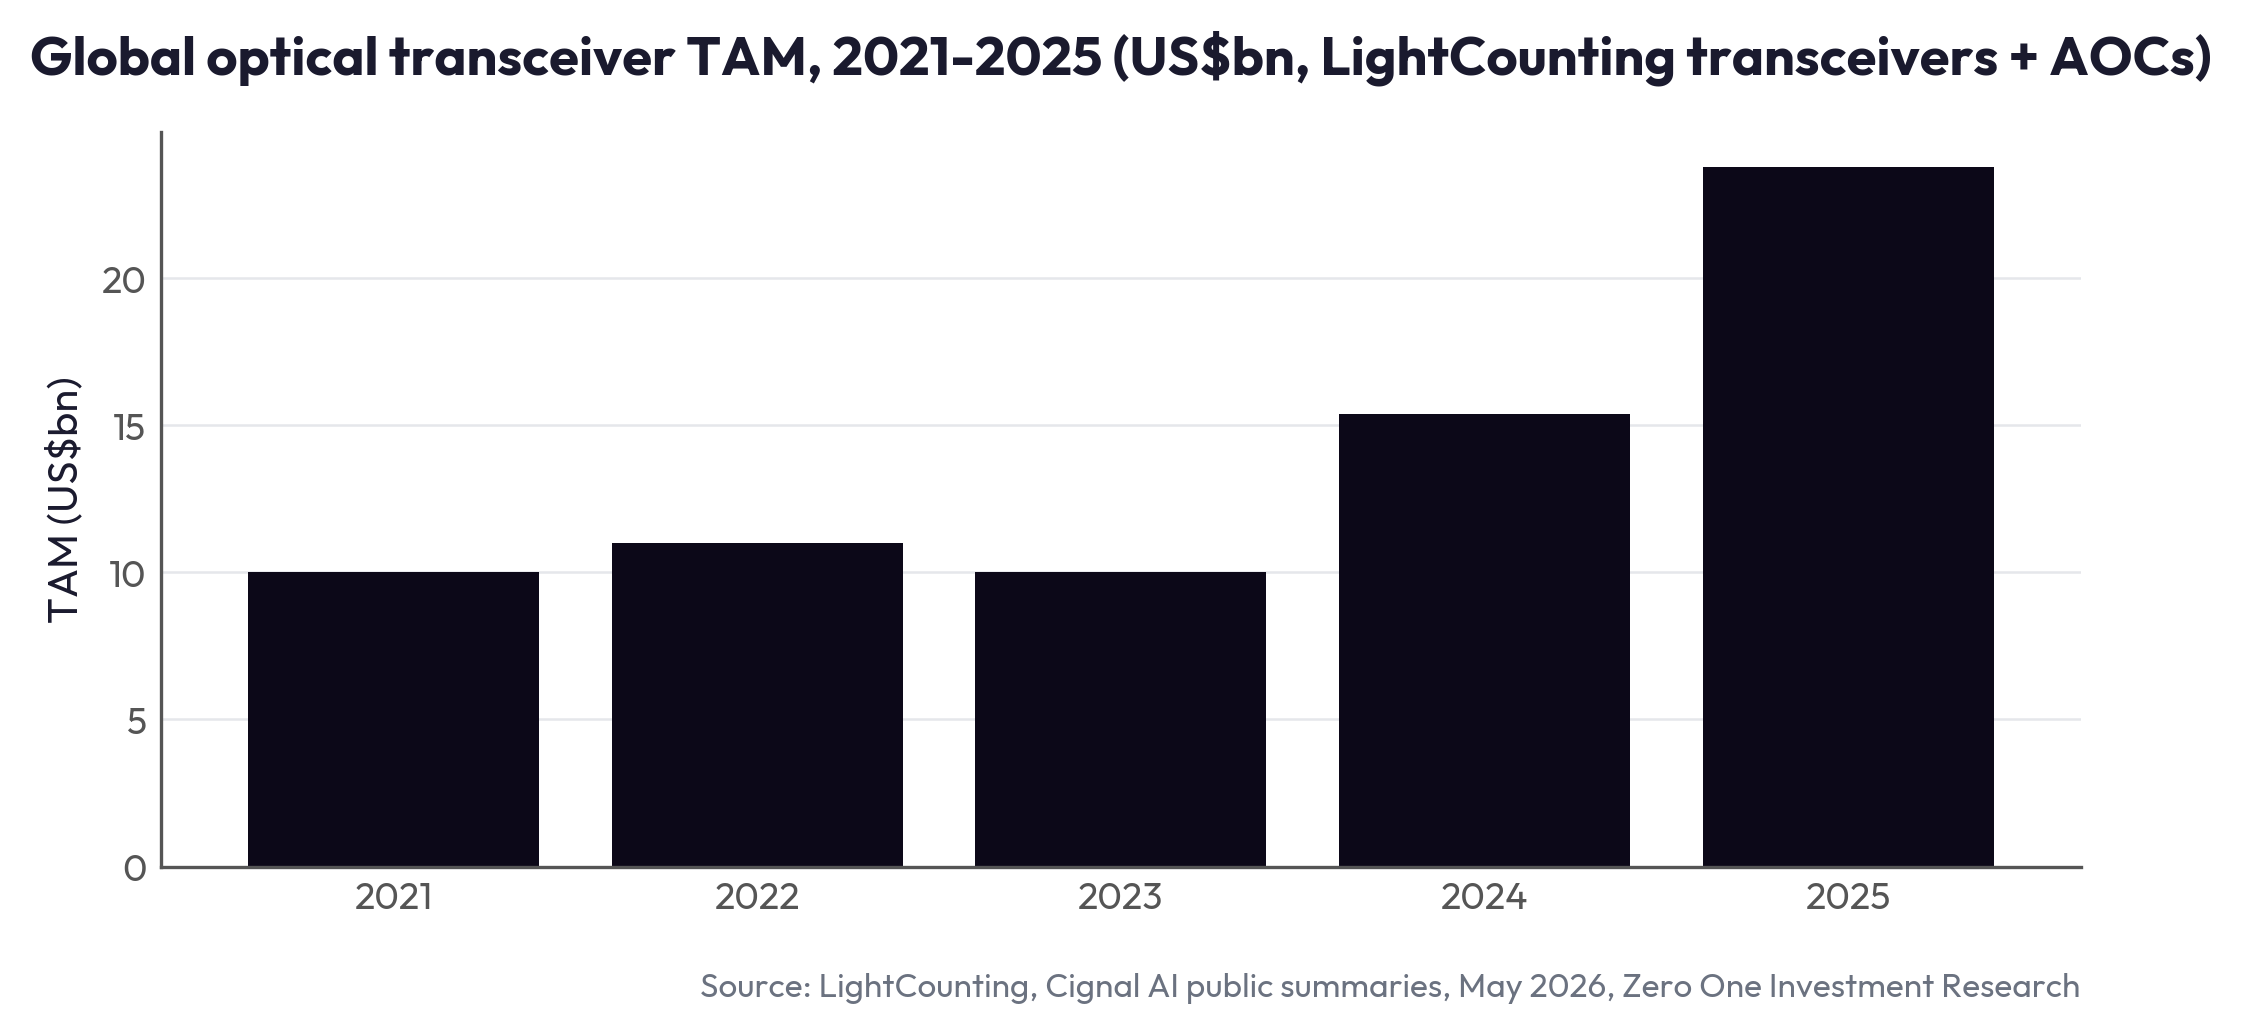
1. China Optoelectronics: Powering AI’s Voracious Bandwidth Needs
- A-Share optoelectronics names hold the largest single-country share of merchant optical transceivers; Innolight leads globally at CNY38.24bn FY25 revenue, with Eoptolink next at CNY24.84bn.
- AI has multiplied demand: Big-5 hyperscaler capex reached US$353bn in 2025, 2026 plans sum to roughly US$790bn, and the market is in year one of the 1.6T generation.
- The module leaders trade at roughly 27x forward earnings, the cheapest layer of their own supply chain; upstream chip, DSP, and EMS peers run 29-52x.
2. Intel Q2 2026. Doubling Down On 14A, But Is It Too Little, Too Late?
- Intel last week reported second quarter revenues of $16.1 billion, up 25% YoY and up $1.8 billion above the guided midpoint.
- Non-GAAP gross margin was 41.8 percent, approximately 280 basis points better than guidance and up 12.1 point YoY.
- Intel now fully committed to high volume ramps of 14A in 2028, one year after threatening to pull the plug entirely without paying external customers, which they still don’t have..
3. Taiwan Tech Weekly: NVIDIA Guarantees Its AI Landlords; Quanta Raises Asia’s Biggest GDR
- NVIDIA lined up US$625bn of AI financing in one week, from OpenAI’s Ohio lease to Hut 8’s Texas campus; the cost of insuring its debt rose the most on record.
- Macronix’s gross margin reached 64.4% and CXMT raised US$8.6bn, evidence memory pricing power kept climbing even as Korea’s chip stocks swung double digits in both directions.
- Quanta raised US$2.2bn in Asia’s largest tech GDR, ASE lifted 2026 capex to US$10.5bn, and MediaTek raised its 2027 AI ASIC share target to 15-20%.
4. Keyence (6861 JP): Not Threatened by AI
- A rebound in demand from China and the weak yen supported June quarter sales and profit growth. But further yen weakness seems cannot be assumed.
- AI contributes to factory automation, but cannot replace the granular knowledge of the company’s sales-engineers.
- The shares have rebounded to within 4% of their early May high. At 35X our EPS estimate for FY Mar-28, they look reasonably valued.