This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
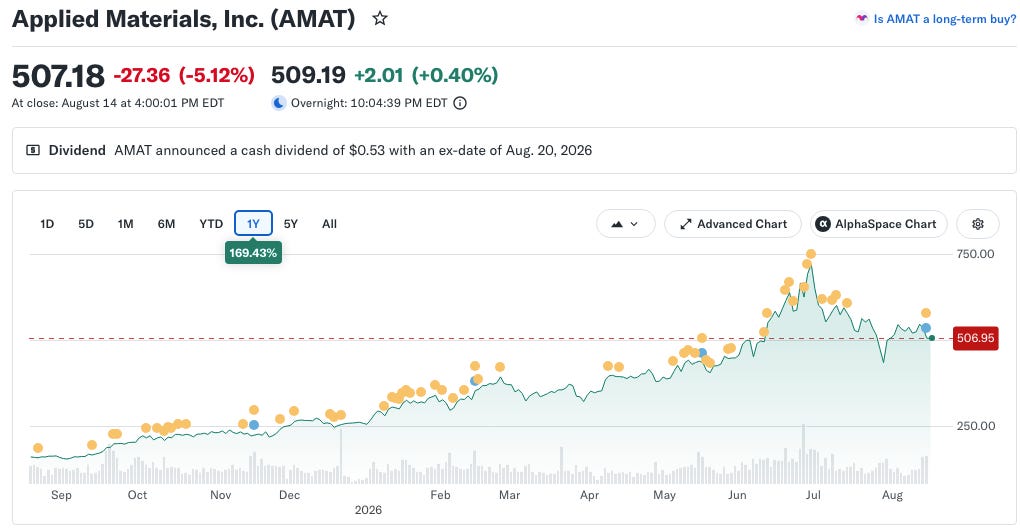
1. Applied Materials Q3FY26. Greater & Greater Growth.
- AMAT reported record Q326 revenues of $9.1 billion, +15% QoQ (the highest QoQ growth in the company’s history), +25% YoY, all while handily beating the guided midpoint of $8.95 billion.
- Non-GAAP GM increased to 50.4%, +40 basis points QoQ and +150 basis points YoY. Operating income was a record $3.10 billion, with EPS of $3.50, also a record.
- The >30 YoY growth that we highlighted last quarter – we’re saying now that it’s greater than that but we don’t want to guide our Q1 at this point
2. SMIC Q2 2026. Record Quarter & “AI Companion Chip” Demand Is Enormous
- SMIC last week reported second quarter revenues of just over $3 billion, up 19.7% QoQ, up 36% YoY and handily beating the forecasted 15% growth at the midpoint.
- Gross margin was 25.3%, up 5.2 percentage points QoQ and up 4.9 points YoY. The significant improvement here was also attributed to both ASP increases a more favourable product mix.
- SMIC’s AI companion chip demand is enormous, we pulled forward shipments and increased this significantly. In this report we said the increase, on a comparable basis, should be around 40%.
3. IBM Q2 2026. Was The Revenue Miss Destruction Or Deferral?
- IBM’s earnings preannouncement last month sent the company’s share price into a tailspin that wiped out more than $68 billion in market capitalization, their largest single-day percentage decline since 1968
- Rather bizarrely, the revenue miss was in their software segment, under the transaction processing umbrella, which is traditionally seen as their strongest, most resilient revenue stream
- After much valiant explaining in the prepared remarks and during the Q&A session, our instinct is to accept management’s view that the miss was revenue deferral and not revenue destruction.