This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
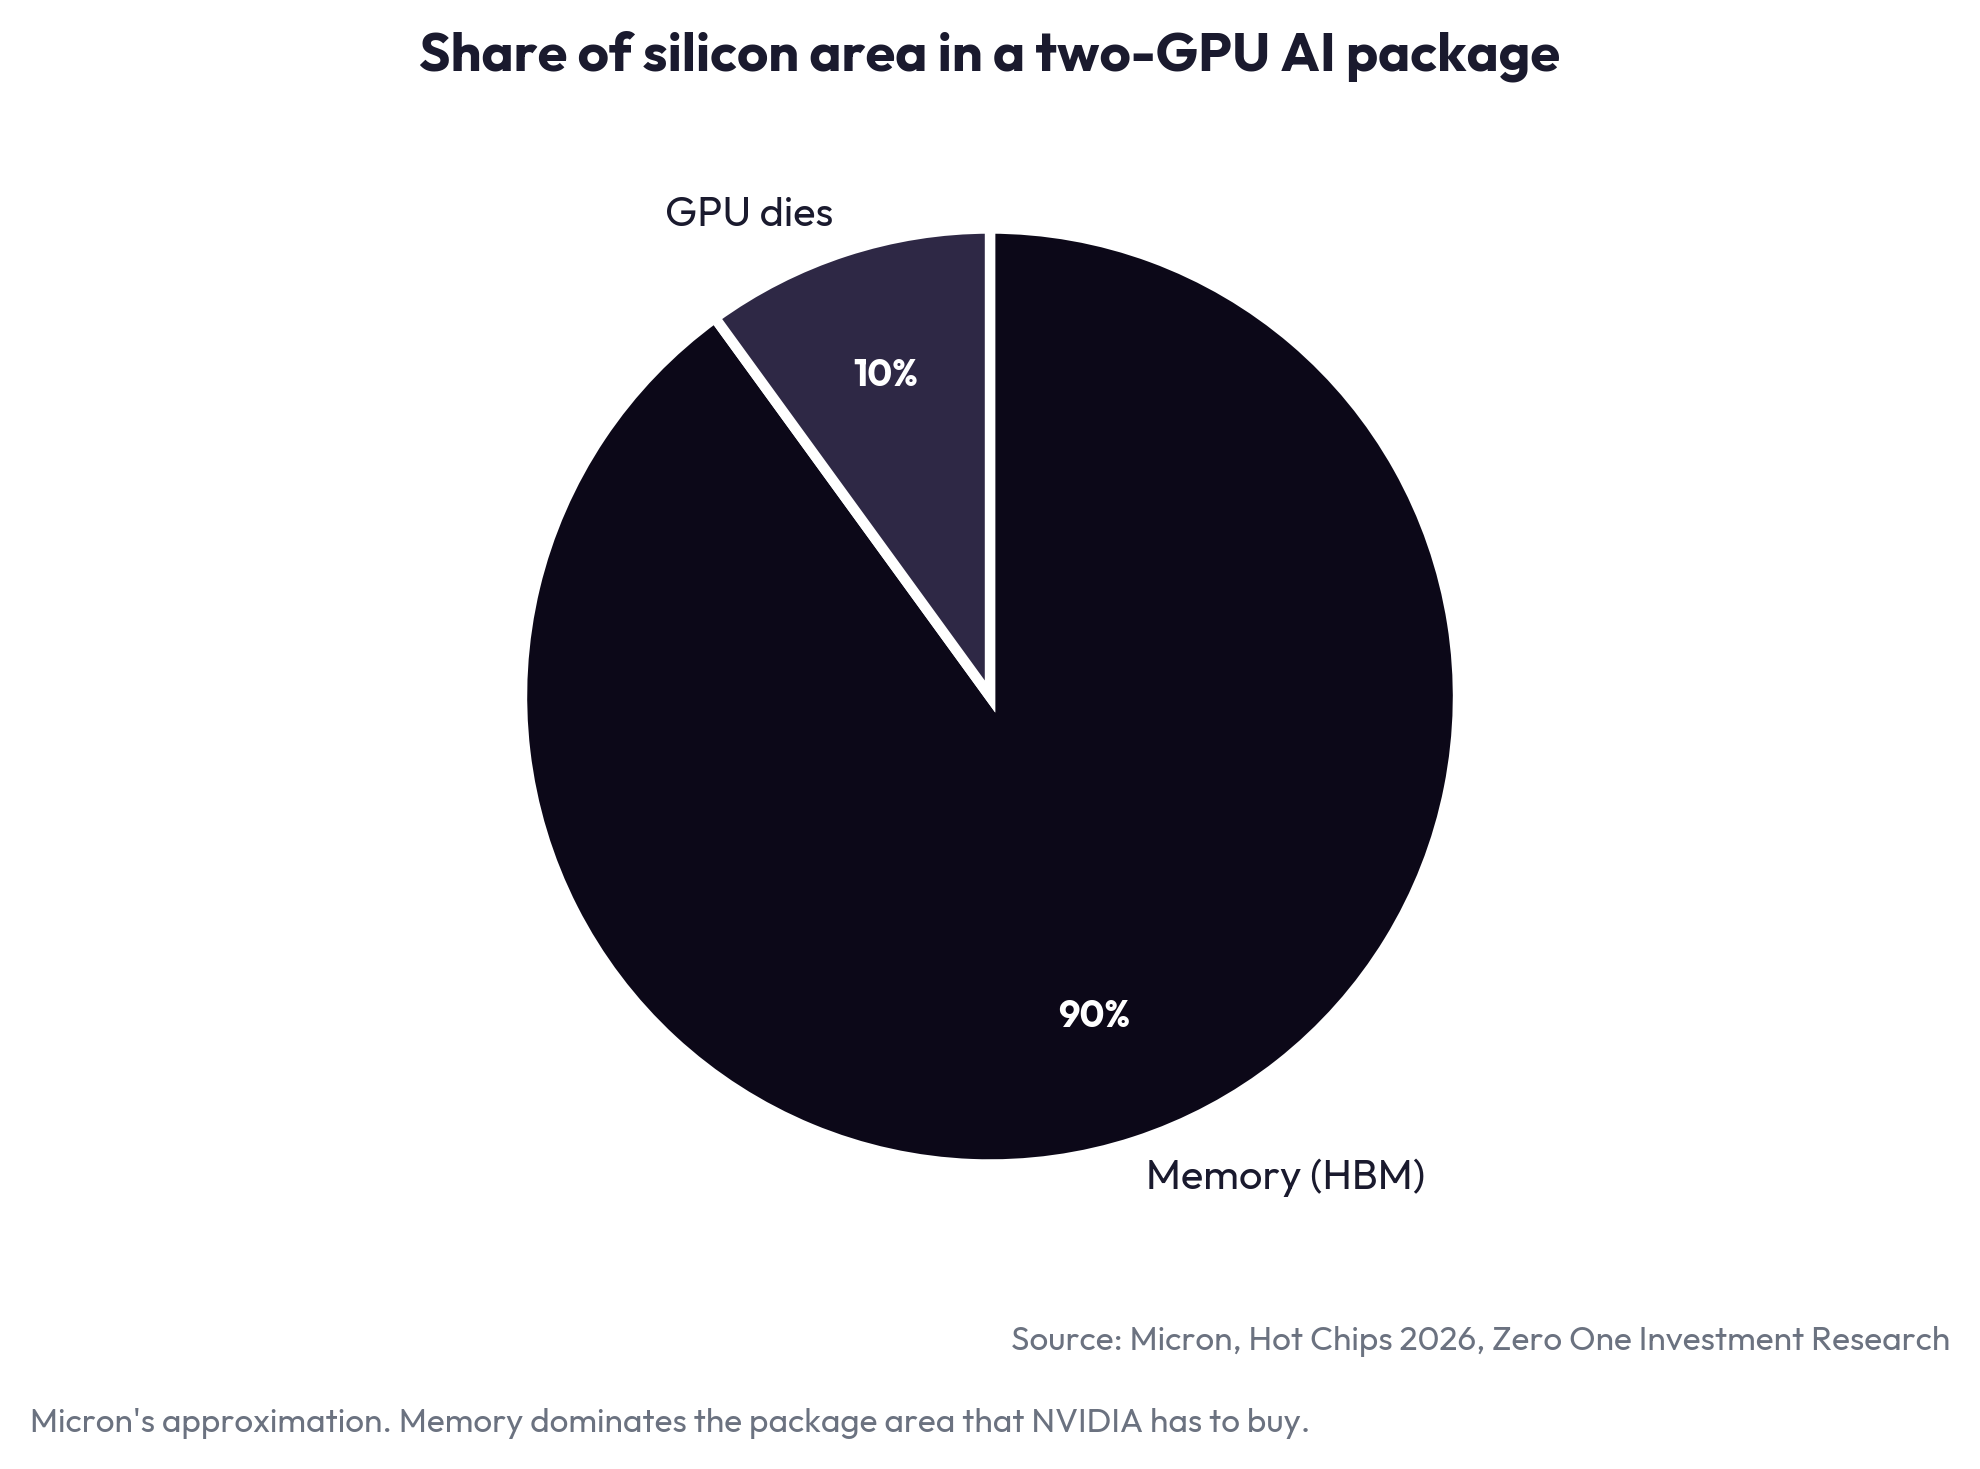
1. NVIDIA Capped Its Growth at 70% Because HBM Takes 3x the Silicon of Ordinary Memory
- NVIDIA guided FY28 revenue growth near 70% and Huang said demand is much greater than that. The ceiling is memory supply, not demand.
- The limit is physical. HBM needs roughly 3x the wafer area of DDR5 per gigabyte, and is about 90% of the silicon area in a two-GPU package.
- What lifts NVIDIA’s ceiling is how they allocate wafers between HBM and commodity parts, not the price print.
2. NVIDIA Q2 2027. 2028 Supply Cannot Meet The Demand Jensen Is Paying To Create
- NVIDIA reported second-quarter fiscal 2027 results, details here. Revenue was $96.2 billion, up 18% sequentially and up 106% year over year, also blowing past the $91.0 billion guided midpoint.
- Q327 revenue forecast $108.0 billion, plus or minus 2%, +12% QoQ, +89% YoY. The company also threw in forecast for fiscal 2028 growth of 70% YoY.
- Recent announcements by NVIDIA, built around guaranteeing and backstopping investment in data centres that exclusively use their compute, suggest that much of their future demand is actually being self funded.
3. Terra Drone (278A JP): Ukrainian Subsidiaries in the Line of Fire
- Terra Drone has invested in its two Ukrainian partners, turning them into consolidated subsidiaries. It can now be regarded as an active participant in the Ukraine war.
- The company remains in the red, but the bonds with warrants issue made in July should cover capital spending through January 2030. By then, it should break even.
- At ¥14,050, the shares are approaching their May high. As a result of the financing, the PBR has dropped from 29X to 7X,
4. Silergy (6415.TT): 3Q26 Outlook: Management Remains Bullish
- Management believes Data Center revenue could exceed 20% of total company revenue in 2027.
- The discussion around Smart Power Stage (SPS) products was one of the most encouraging aspects of the call.
- Automotive Business Entering a New Growth Phase: Growth is being supported by a combination of new customers, new product categories, and geographic expansion.
5. Taiwan Supply Chain Signals: Memory Revenue Re-Accelerates While Custom AI Chip Revenue Ramps
- Memory revenue re-accelerated well ahead of its seasonal pace: the six memory names grew revenue +32% MoM after about +4% in June, roughly twice their pace in July last year.
- Taiwan’s assemblers look weaker than they are: nine of thirteen ODM, EMS and PC-brand names saw revenue fall sequentially, yet the group beat its own July 2025 decline.
- Alchip Technologies (3661 TT)‘s revenue nearly quadrupled in two months and its filing reversed: after three months reporting mass-production declines, it reported growth, the only commentary change in our universe.