This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
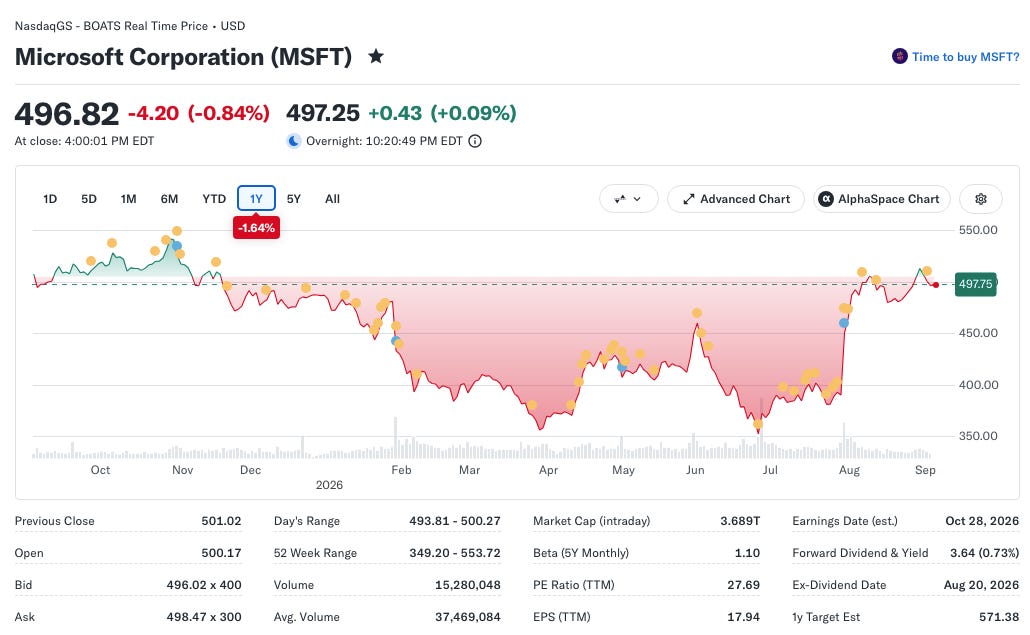
1. Microsoft @ Deutsche Bank Technology Conference. Key Takeaways & Full Transcript
- Two viral blog posts by Satya Nadella over the summer suggest a tops-down change in Microsoft’s AI deployment strategy
- Microsoft is investing $2.5 billion & deploying 6,000 engineers into a new division, Microsoft Frontier Company, to help manage its AI deployments to enterprise clients globally
- There are going to be areas where we are very complementary and partner very, very closely with AI frontier labs. Then, there might be areas of overlap competitively.
2. Intel @ Deutsche Bank Technology Conference. Key Takeaways & Full Transcript
- Intel 18A progressing past internal yield milestones and 14A defect-density yields tracking at levels unseen since Intel’s 22nm era. Not entirely sure that latter comparison is a good thing!
- Formal commitment to high-volume manufacturing (HVM) for the 14A process node in 2028, backed by the release of the 0.9 Process Design Kit (PDK) in October 2026.
- The EMIB-T Advanced packaging business is on track to generate multi-billion dollars per customer annually by 2028–2029 at 40% gross margins and 30% operating margins.
3. iEdge Singapore Next 50: Portfolio Capacity Keeps Rising
- The iEdge Singapore Next 50 comfortably supports S$50-100m index products today, and about S$171m with optimised sampling that excludes the five least liquid names.
- Strict full-replication capacity reached about S$97m as of 10 July 2026, up 75% since September 2025, as aggregate constituent turnover rose from S$134m to S$261m per day.
- The ceiling is set by a thin tail of property and hospitality names, so an ETF launch or the remaining S$2.6bn of EQDP money would lift it.
4. Salesforce Opens The AI Floodgates With Cloudforce. But Why?
- Salesforce reported Q2 FY 2027 revenue of $11.345 billion, up 11% YoY in constant currency, at the high end of the previously guided range.
- Cloudforce, a partnership between Anthropic & Salesforce, integrates Claude into Salesforce and vice versa. Basically, Claude becomes the new user interface for Salesforce, as long as you upgrade to premium
- Benioff is betting big on Cloudforce unlocking previously unheard of value from customers’s underlying Salesforce data and that they will pay handsomely for this privilege. Let’s see…
5. Taiwan Dual-Listings Monitor: TSMC Spread Now Near Multi-Year Lows
- TSMC: +9.9% Premium; Below -1 SD Band; Long the ADR Spread
- UMC: -2.9% Discount; Below -1 SD Band; Long the ADR Spread
- ASE: +2.4% Premium; Within Recent Historical Range; No Active Trade Signal
6. TechChain Insights Q&A: AI Chips Cannot Ship Until Chroma’s Machines Pass Them
- AI silicon changed what “test” is for. Larger die and stacked packages mean a late failure destroys more value, so test now decides whether parts ship.
- Chroma’s revenue doubled while gross margin fell, the signature of customers buying larger systems with more bought in content rather than more of the same instrument.
- The whole test group is priced for a multi year cycle, not a good quarter: Advantest trades at 77.0x next year’s consensus and Chroma at 44.7x.
7. Hua Hong Grace (1347.HK) Q2 2026 Earnings Report Review & Full Transcript
- Hua Hong Grace (1347.HK) reported Q2 2026 revenue of $717.5 million, up 26.8% YoY and 8.6% QoQ, a record high and easily beating the guided midpoint of $695 million
- Gross margin reached 16.5%, up 5.6 percentage points YoY and 3.5 points QoQ, clearing the top end of the 14-16% guide.
- Looking ahead, the company forecasted current quarter revenues of $775 million at the midpoint, a roughly 8% sequential increase. Gross margin is expected to be ~17%, marginally up QoQ.
8. TechChain Insights Q&A: Memory Maker Macronix Will Increase Capex by 8x on Non-DRAM Strength
- While DRAM has led the memory cycle, Macronix has budgeted NT$15.8bn for advanced capacity, roughly 8x its last four quarters of capex combined, on NOR and NAND strength.
- Second quarter revenue grew 181% with gross margin at 64.4%, earned off a written down fab that is now full. NAND supplied close to 60% of the increase.
- New capacity could carry real depreciation into a cost base that has almost none, and most tools are ds after this shortage.