This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: Tencent Investee Selldown – Start of Another US$70bn Selldown Wave
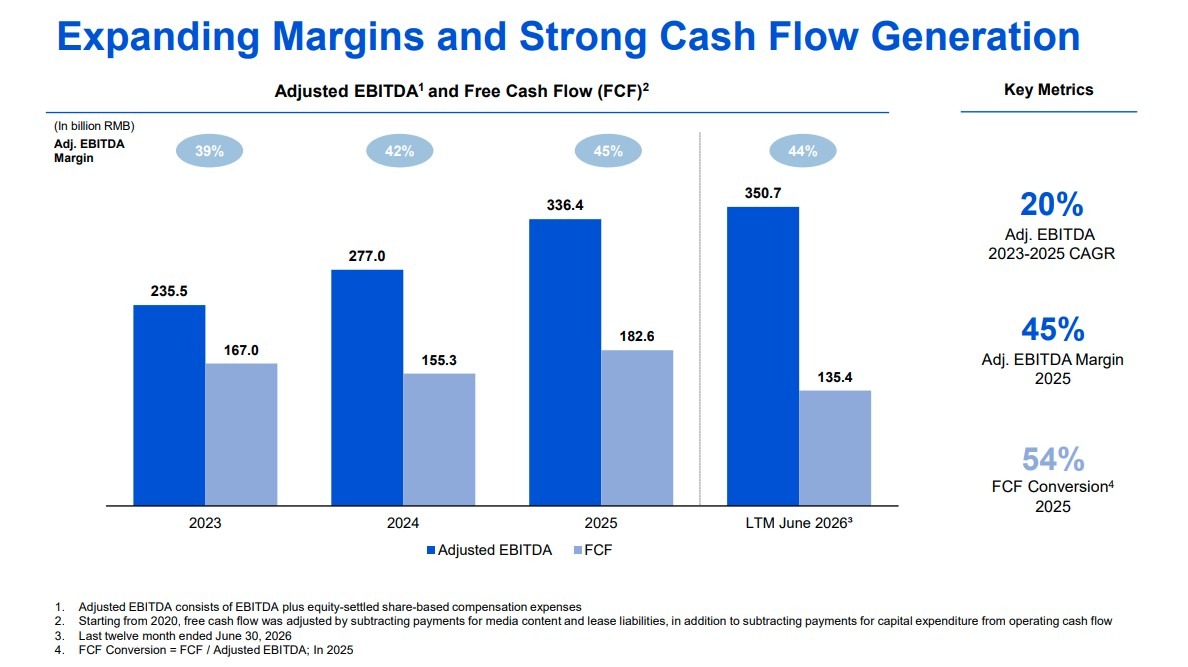
- Tencent (700 HK) has been active since the start of the year in selling down some of its stake in its investee companies to raise over US$3.3bn cash.
- Tencent did report a negative free cash flow quarter in 2Q26. Given the elevated spending, it might look to sell some more of its stakes.
- Tencent owned over US$66bn worth of shares in over 39 companies, with the bulk of it stemming from US, US-HK listed and overseas listed companies.
2. Aequitas ECM Weekly (21 September 2026)-NSE, GCash, Ligent, Kingwong, Elice, Z.AI, Kanzhun, Groww
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, National Stock Exchange (NSEIN IN) managed to garner interst from a long list of anchor investors, while GCash (Mynt) is said to be planning to launch.
- On the placement front, Tencent (700 HK) continues to trim its investment portfolio.
3. RoboTechnik (300757.SZ): The H-Share Is Cheap. The Company Is Not.
- 2026 A+H IPOs have punished day-one buyers: Luxshare, Innolight and Longsys all closed below issue despite discounts of 13–44%.
- RoboTechnik’s photonics inflection is real, but FY27E at 372x EPS leaves almost no fundamental valuation support.
- Investment positioning: bid only at ≥30% discount, size for a weak open, stop at CNY545 and exit around Southbound eligibility.
4. Oura (OURA) IPO: Three Numbers Investors Should Watch
- Oura, Inc. plans to sell 50.0 million shares at an expected price of $40.00 to $44.00 per share and list on the Nasdaq Global Select Market under the ticker OURA.
- At the $42.00 midpoint, the offering would raise approximately $2.10 billion and value the company at approximately $13.48 billion.
- Goldman Sachs, Morgan Stanley and J.P. Morgan are leading the offering.
5. National Stock Exchange of India (NSEIN IN) Updates: The 3.6% Float Matters More Than the 1.5x Book
- 126.4m of 2,475m NSE shares are being sold, 37.8m of those are anchor stock locked for 30–90 days: the tradable float on 24 Sep is ~88.6m shares, 3.6% total shares.
- The book is ~1.5x, not 50x — retail is 0.7x covered and the grey-market premium has halved from ₹310 to ~₹150 in a fortnight. Thin float meets thin demand.
- We hold BULLISH, FV ₹2,000: subscribe at ₹1,785, trim above ₹2,100, add below ₹1,800; the real float arrives on ~22 March 2027 and MSCI/FTSE weight follows it, not the IPO.
6. Kinwong Electronic H Share Listing (3228 HK): The Investment Case
- Shenzhen Kinwong Electronic (3228 HK) is a global printed circuit board (PCB) manufacturer, seeking to raise up to US$653 million at a maximum offer price of HK$69.88 per share.
- It makes rigid PCBs (RPCBs), flexible printed circuits (FPCs), and other PCBs for automotive electronics, smart devices, industrial control, telecommunications, and data infrastructure customers.
- The investment case is bearish: Kinwong is a price-taker in a fragmented, capital-intensive industry, with squeezed core margins, profits propped up by copper-scrap sales and heavy capex-driven cash burn.
7. Elice Group IPO Valuation Analysis
- My base case valuation of Elice Group is target price of 62,353 won per share. This is 11.4% lower than the low end of the IPO price range.
- Given the lack of upside, I have a Negative View of this IPO. The bankers used eight overseas companies as comps for Elice Group. I disagree.
- My base case valuation of Elice Group is based on a P/E of 34.7x my estimated net profit of 20.1 billion in 2026.
8. Aequitas: Robotechnik A/H Listing – Only Cheap on Y+2 P/E
- RoboTechnik Intelligent Technology (RBTK HK) is looking to raise up to US$662m in its upcoming Hong Kong IPO.
- It is a leading global provider of high-precision intelligent manufacturing equipment and systems specializing in photovoltaic (PV) manufacturing solutions and silicon photonics (SiPh) assembly and testing equipment.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
9. Shenzhen Kinwong (3228 HK) IPO: Marginally Attractive
- Shenzhen Kinwong Electronic (3228 HK)‘s IPO is seeking HK$4.96bn, though priced at a steep 45.9% discount to the A-share, the absolute PER is not cheap.
- The key strengths lie in its comprehensive product portfolio, strong market reputation, and strategic partnerships with global customers.
- We value it at 32.7x PER for FY26, in line with the global peer average, meaning a price of HK$80.15. But this is not without risks, given potential earnings disappointment.
10. RoboTechnik H Share Listing (3757 HK): The Investment Case
- RoboTechnik Intelligent Technology (RBTK HK) makes manufacturing equipment for the PV and silicon photonics (SiPh) industries. It is seeking to raise up to US$663 million at HK$436.00 per share.
- Its legacy PV business is collapsing, while SiPh assembly and testing equipment, acquired through ficonTEC in 2025, generated 80% of 1H26 revenue.
- The investment case is cautious: RoboTechnik leads a fast-growing SiPh niche, but is barely profitable, leveraged and goodwill-heavy, with a weak governance record.