This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Micron’s FY26 Revenue Soars 3.5x YoY. FY27 Looks Even Better, Right? Key Takeaways & Full Transcript
- Micron last week reported Q4FY26 revenues of $54.23 billion versus $41.46 billion for the prior quarter (+31%) and $11.32 billion for the same period last year (+379%)
- Consolidated gross margin for fiscal Q4 was 87.0%, up 210 basis points sequentially. This improvement was driven primarily by higher pricing and strong execution, partially offset by mix.
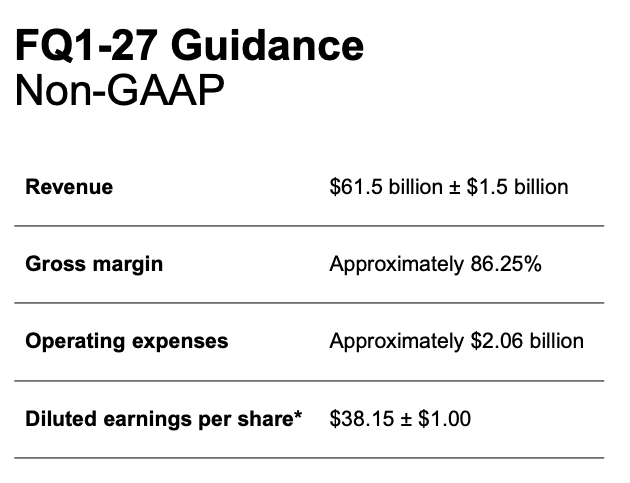
- Looking ahead, the company expects F27Q1 revenue to be a (another) record $61.5 billion, plus or minus $1.5 billion with gross margin to be approximately 86.25%;
2. Marvell Investor Day 2026. Key Takeaways & Full Transcript
- Marvell set a long-term revenue target of $70B to $90B for FY31 ($80B at the midpoint), representing a 55%–60% CAGR and a 10x expansion over FY26 ($8.2B).
- Newly installed CFO Dan Dern introduced the “30 in 30” milestone, projecting non-GAAP EPS of greater than $30 per share in calendar 2030 (FY31).
- Marvell claims it can achieve these new financial targets without needing any new home run design winds or any new sockets. Apparently, they have what they need today.
3. Accenture Soars As New Bookings Accelerate. Q426 Earnings Review, Key Takeaways & Full Transcript
- Accenture last week reported Q4 FY26 revenues of $18.7 billion, up 7% YoY in local currency and above the top end of the guided range of $18.4 billion.
- New Bookings were $22.2 billion for the quarter, a 4% increase in U.S. dollars and 5% in local currency, with an overall book-to-bill of 1.2.
- Accenture’s top 10 ecosystem partners represented >60% of their revenue in FY26. Among their eight emerging AI and data partners, bookings more than tripled and revenue more than doubled YoY.
4. The Blade Weekly: Micron Customers Post US$32bn of Deposits, Broadcom Lends Anthropic up to US$42bn
- Micron reported US$32bn of customer commitments, mostly cash deposits, with 75% of fiscal 2027 output committed and most 2027 HBM contracted above 2026 prices.
- Broadcom will lend Anthropic up to US$42bn as Anthropic’s IPO filing lists US$518bn of compute obligations against about US$4.6bn of 2025 revenue.
- Amazon bought a NT$1.59bn Gold Circuit stake, Samsung Electro-Mechanics is expanding substrates on reported NVIDIA prepayments, and phone makers cut memory demand 30% to 40%.
5. Taiwan Dual-Listings Monitor: UMC, ASE and ChipMOS Above +1 SD Band; Short the ADR Spread
- TSMC: +20.3% Premium; Rebounded from Our Long the ADR Level
- UMC: +3.4% Premium; Above +1 SD Band; Short the ADR Spread
- ASE: +5.8% Premium; Above +1 SD Band; Short the ADR Spread
6. Synopsys Investor Day 2026. Elliott’s Fingerprints Are Everywhere.
- Synopsys is expanding from its traditional “Factory 1” model (standardized IP: build once, sell many times) to a “Factory 2” model focused on Application-Optimized IP (AOIP).
- Synopsys raised its long-term revenue CAGR through 2030 to mid-teens (up from low/double-digits), targeting $9.7B in FY26 and driving toward ~$11.15B in FY27 (+15% YoY).
- Synopsys announced a $1 billion, multi-year, IP licensing agreement with Amazon as well as a multi-year agreement to collaborate with OpenAI as preferred partners to develop and deliver GPT-Synopsys
7. TSMC 3Q26 Preview: 2027 Price Increases Should Hold Margins; Further Share Upside from Here
- 3Q26 revenue is already reported at NT$1,494.2bn, about US$46.7bn, 2% above the top of the guide; the 15 October release turns on margins, the 4Q guide and 2027.
- We expect January 2027 price increases to roughly offset wider 2nm and overseas dilution, holding gross margin near 65-67%; 2027 capex is the bigger unknown.
- Target price NT$2,920 (15% upside): 26.9x 2026 EPS, reflecting what we see as a permanent re-rating since 2019; TSMC trades at 17.9x 2027 earnings versus 23.0x for big US tech.
8. The Blade Weekly: AI Chip Financings Pass US$150bn as OpenAI’s Revenue Lands US$20bn Below Reports
- Financing plans for Anthropic, SpaceX and OpenAI chip orders totaled more than US$150bn, as the FT put OpenAI’s revenue run rate at about US$50bn.
- Laminate and power chip prices rose, and Nanya told customers DRAM prices will rise up to 20% as Micron’s Taiwan union won a strike vote.
- Foxconn booked Taiwan’s first NT$1tn revenue month and TSMC beat its 3Q guidance, while Samsung reportedly plans to cut 4Q phone output by up to 30%.