This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
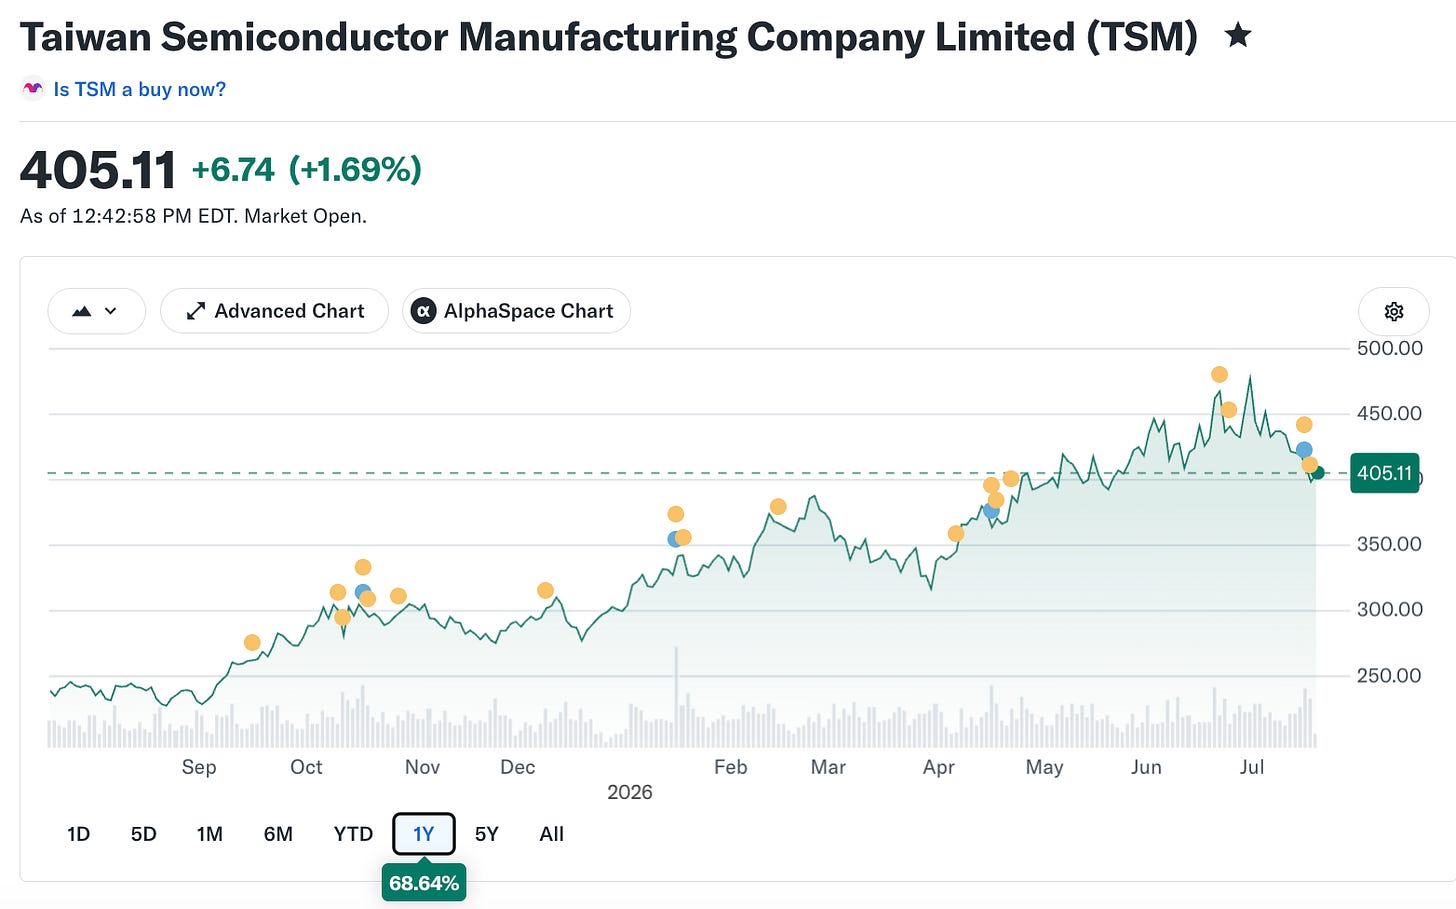
1. TSMC Q226. You Put All The Truth Together, It’s Not The Truth
- In US dollar terms, TSMC’s second quarter revenue was $40.20 billion, which increased 33.7% year-over-year and increased 12.0% from the previous quarter.
- Current quarter guidance for revenues between US$44.6 billion and US$45.8 billion. At 1 US$ to 32 NT$, gross profit margin is expected to be between 65% and 67%
- Supported by their robust technology differentiation and the broad customer base, TSMC now expects full-year 2026 revenue growth of slightly above 40% YoY in US dollar terms. Yikes!
2. AI Supply Chain Revenue Signals: The Memory Surge Settles While AI Server Demand Broadens
- AI’s compute build re-accelerated broadly in June: chain revenue growth stepped up to +61% YoY across server ODMs and infrastructure, with even ASUS’s rebound crediting AI servers rather than PCs.
- Memory’s price surge settled to an ordinary pace: sequential revenue growth cooled to +7% MoM from April’s +32%, though company commentary says prices keep rising and cycle has not turned.
- AI demand is now tightening component supply at the consumer end: a casing maker blamed shortages for weak notebook shipments, and consumer PCs still lag the AI cohort.
3. Taiwan Tech Weekly: Intel Pulls Chip Orders Back From TSMC to Its Own Leading-Edge Fab
- Intel last week moved most of its Nova Lake compute tiles back to its own 18A process from TSMC, and won packaging designs at Google and AWS.
- TSMC last week raised its full-year revenue growth guide past 40% for the second time this year, while guiding near-term margin lower as its 2nm ramp scales.
- In memory, HBM4 shipments, record wafer price hikes and multi-year contracts pointed to a still-tight supply side across the DRAM stack.
4. Taiwan Dual-Listings Monitor: Multiple ADR Spreads Due for a Bounce
- TSMC: +12.0% Premium; Below -1 SD Band; Long the ADR Spread
- ASE: +0.0% Premium (ADR at Parity); Long the ADR Spread
- CHT: -1.3% Discount; Below -1 SD Band; Long the ADR Spread
5. ASML Q2 2026. Massive Capacity Expansion Plans Leave Markets Unmoved. But Why?
- ASML Q226 net sales were €9.3 billion, up 6.4% from the €8.7 billion ASML booked in Q126 and up 21.2% from the €7.7 billion it reported a year earlier.
- ASML expects Q3 2026 total net sales between €11.0 billion and €12.0 billion, and a gross margin between 55% and 57%
- ASML announced 30% capacity increases for both low-NA EUV and DUV immersion tools for delivery in 2027. They are investigating a further 30% increase for both for 2028. Yikes!
6. Taiwan Tech Weekly: AMD Wins First Training Chip Order Outside NVIDIA; NVDA Prepays Amkor’s Capex
- AMD committed up to US$5bn to Anthropic against an order for up to 2 gigawatts of MI450 accelerators, the first training-scale commitment to a rack that is not NVIDIA’s.
- NVIDIA prepaid Amkor US$1.5bn to expand Arizona packaging and planned US$5bn to US$10bn of dark fiber, paying cash upfront for what it does not manufacture.
- Korea’s supply answer to a 2027 shortage is dated 2030: Samsung plans four new fabs, and SK Hynix reapproved a 7.1 trillion won expansion.
7. TechChain Insights Q&A: How Lotes’s Value Drivers Have Transformed Due to AI Demand
- Server has gone from about a quarter of Lotes’s revenue in 2023 to 55% in Q2 2026, a shift management attributes mostly to AI demand.
- AI servers add more sockets and connectors per box and push each interface faster; Lotes says a PCIe Gen6 connector sells at least 15% above Gen5.
- Bloomberg consensus sees revenue near-doubling to NT$59bn by 2028E; at ~21x forward earnings falling to ~13x, the AI ramp is largely in the price.
8. TechChain Insights Q&A: Taiwan’s Elite Material, Global Laminate Leader Behind the AI Server Boom
- Elite Material (2383 TT) is the world’s leading maker of high-speed copper clad laminate, the low-loss material inside AI server boards; AI infrastructure is now roughly 75-80% of revenue.
- The mix is climbing to higher M8 and M9 grades for NVIDIA Corp (NVDA US)‘s GB200 and GB300 systems, lifting price and margin; consensus sees revenue near-doubling in 2026.
- At about 49 times 2026 earnings versus Taiwan peers ITEQ and TUC at 34 to 37 times, the leader’s premium prices execution: M9 timing, pricing, and holding share.