
Receive this weekly newsletter keeping 45k+ investors in the loop
1. The Week Ahead – Is Trump Winning?
- Recent tariff announcements reflect cautious optimism on the US Dollar and inflation risks
- Tariff rates of 16-17% could lead to gradual pass through to prices, impacting inflation in the coming months
- Q2 GDP growth rebounded, but domestic final demand slowed, suggesting a gradual economic slowdown in the US, while Canada faces economic challenges and BoC takes a dovish stance
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
2. BoE Cut Proves Finely Balanced
- Four MPC members refused to back the rate cut in August, and only one favoured a 50bp cut, but he was forced to vote for a 25bp cut to break the balanced 4:4 split.
- The group favouring a slower pace of easing may have expanded from 5:4 to 6:3, raising the hurdle to another cut. Four don’t even support the prevailing level.
- Inflation forecast revisions keep trending the profile higher. Rolling resilience in the broader data should keep the BoE on hold in November and beyond, like the ECB.
3. Briefing. Massive Jobs Restatement, Rates Go Nowhere, Apple M&A?, Earnings Updates
- New newsletter format called “The Briefing” provides quick market synopsis and company information, also available in podcast form on speedwellmemos.com
- Recent market events include S&P 500 reaching all-time high before job report and new tariffs cause market to drop, Fed considering rate cut in response to softening economy
- President Trump criticizes Fed Chair Powell for not lowering rates, Powell cautious on rate cuts to avoid inflation, history of rate mistakes highlighted
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
4. Jung Chung-Rae (New Head of Ruling DPK) – Likely To Push for CGT Changes, How About Other Taxes?
- Jung Chung-Rae, a four term lawmaker, has been appointed the new head of the ruling Democratic Party of Korea (DPK) in the past week.
- His appointment as the head of the DPK party signals that there could be some changes to the 2025 Tax Reform Plan announced by MOSF last week.
- The highest probability event is that the lower threshold for major shareholders for stock capital gains tax may NOT be lowered from 5 billion won to 1 billion won.
5. EA: Resilient Retail Rebound
- Consumers need to drive activity growth as tariffs and Euro strength harm export competitiveness. Reassuringly, retail sales returned to their trend after a trimmed fall.
- Growth was broad across countries and categories, taking the annual pace 0.5pp above consensus expectations. Non-food retail is critical and the strongest of them all.
- Surveys are gloomier, especially about the future, but rarely right. Resilient real wage and employment growth can sustain brisk retail trends, preserving economic expansion.
6. HEM: One-Touch Easing
- Payrolls revisions challenge the rolling resilience seen in most other hard data releases, but seem over-weighted.
- Underlying price and wage inflation mostly track >2%, especially in the UK, which doesn’t need more rate cuts.
- Policymakers biased to ease will deliver it on a batch of bad outcomes, even if the evidence proves fleeting.
7. Separate Dividend Tax Plan in Korea: Devil Is In the Details
- A closer look at MOSF’s Tax Reform Plan for dividends suggests that it may not have a material impact on most listed companies unless the National Assembly drastically improves it.
- According to MOSF, it currently estimates that approximately 350 of the 2,500 listed companies, or 14%, could meet these requirements (two main dividend tax reduction requirements).
- We provide a list of 70 companies in the Korean stock market with 40% or higher dividend payouts (excluding companies with smaller market caps).
8. 80% Of Our 2025 Calls Are Working
- Only one of our non-consensus macro calls are not working and eight of eleven markets are moving our directions.
- Our latest business cycle indicator assessment points to a better second half.
- 2025 Investment Strategy maintained. We are overweight equities and underweight government bonds.
9. This Will Not End Well, But When?
- The U.S. stock market is undergoing a frothy advance. The intermediate trend is bullish but some technical warnings are appearing.
- We can’t predict the exact nature or timing of a possible market disruption.
- Investors may find it prudent to opportunistically take advantage of the relatively low implied volatility environment to buy cheap downside protection.
10. Rising Ringgit, Eroding Fundamentals
- BNM’s heavy reliance on FX forwards created $29 billion in off-balance sheet liabilities, masking true reserve strength and exposing future repayment risks if inflows weaken.
- This is further compounded by a narrowing current account surplus, while capital outflows and rising foreign currency deposits reflect persistent financial account weakness, undermining long-term support for the ringgit.
- While China is Malaysia’s largest trade partner, the U.S. is the main source of trade surpluses. Worryingly, the U.S. recently imposed a 19% tariff, threatening this critical surplus engine.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. The art of the turnaround: investing in companies at a crossroads
- Magellan in the Know podcast discusses consumer sector turnaround opportunities
- Definition of a successful turnaround and examples of companies that do and do not meet the criteria
- Importance of consistent investment philosophy and focus on protecting against permanent capital loss
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
2. EM Fixed Income: Summer catch-up as spreads catch-down
- EM sovereign credit markets are a key focus
- Overall risk environment for EM is being closely monitored, with a more neutral stance on EMFX rates and corporates
- Tariffs and ongoing tariff uncertainty are major drivers in the coming weeks, with markets having ground better despite potential downside risks in growth
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
3. Opec: Twist Or Stick?
- The further acceleration by ‘Opec+ eight’ in unwinding the second package of voluntary output cuts was a surprise, albeit one that left markets unmoved.
- The cartel now appears to be firmly on track to complete its unwinding in September, even though its stated justifications for increasing output remain highly questionable.
- Despite downside global growth risks, the Saudis in particular may press to start unwinding the first package, a move which may be announced as early as next week.
4. Ep. 318: Brad Setser on Trump Tariffs, China’s Surging Surplus and Dollar Policy
- Brad Setzer is an expert in global trade, capital flows, and sovereign debt restructuring
- He has been involved in various government positions related to international economic analysis
- Setzer discusses the rapid rollout of tariffs under the Trump administration and their potential impact on the economy
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
5. ECB Job Tightened By Jobs
- The EA labour market proved tighter than the ECB expected in Q2 as the unemployment rate held at a downwardly revised 6.2%. That is hawkish news to its neutral stance.
- Most countries still face falling unemployment, suggesting monetary conditions were slightly loose, and avoiding pressure to lower underlying inflation further.
- A hawkish domestic surprise should keep the ECB on hold, especially with the US trade policy risk fading. Passthrough of past cuts may mean the ECB needs to hike later.
6. EA: Sticky Summer Inflation
- The ECB’s victory party can continue for another month, as inflation proved surprisingly sticky at the target. But the hangover is disappointing, amid broad-based upside news.
- Two-thirds of national outcomes exceeded our expectations, with a slight skew higher, and pressures concentrated in services. Seasonal travel parts would be payback-prone.
- Another upside surprise to the ECB’s forecast makes the profile likely to shift higher in September. The news is the opposite of what is needed for another rate cut.
7. Activity’s Tariff Hangover In Q2
- GDP growth broadly beat expectations again in Q2 on both sides of the tariff disruption. Euro area growth slowed by less, while the US rebounded vigorously.
- Temporal distortions to demand didn’t open up slack as European supply growth stays stagnant. Surveys suggest it won’t appear in Q3 either as demand growth rebounds.
- Underlying US GDP growth may have slowed, but the extent is modest and questionable. Rolling resilience should keep delaying rate cuts, preventing them from occurring.
8. Disappointing New Korean Tax Policies (Dividends, Capital Gains, and Corporate Taxes)
- The Korean government announced disappointing new tax polices for dividends, capital gains, corporate, and higher transaction taxes on securities transactions.
- The new tax policies announced today is likely to have the biggest negative impact on the Korean financials with high dividend yields.
- They will also likely to negatively impact other high dividend yielding stocks in Korea.
9. HEW: Atlantic Jobs Divide
- Depressing revisions to US payroll data clash with the resilience seen in other data, and compare poorly with the bullish revisions to the Euro area’s labour market.
- Jobs data challenge the Fed’s patient posture, while the Euro area’s sticky inflation and tighter labour markets should encourage it to keep rolling rate cuts later.
- Thursday’s BoE decision sets unemployment’s rise against inflation persistence, leaving the outcome uncertain, yet it is likely to yield another split vote for a rate cut.
10. UK: Loans Secured Despite Tax Hike
- Credit extended its rebound far beyond expectations in June. Reformed stamp duty raises costs and housing tenure, but it hasn’t broken the housing or mortgage markets.
- Demand for loans looks more resilient than banks expected amid easing monetary conditions. Refinancing may not have much effect on cash flow anymore.
- Higher transaction costs probably won’t break expectations into a downwards spiral, but are now widely cited as a major hurdle, contributing to slower UK activity growth.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK Structurally Unemployed
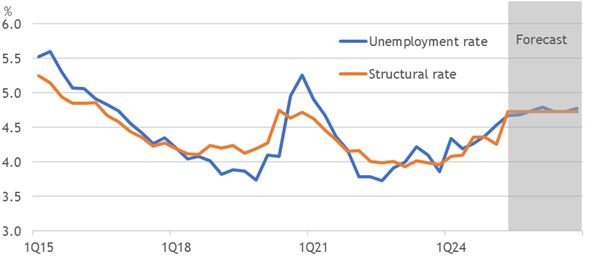
- Higher employment taxes can entirely explain the fall in payrolls as the tax wedge hits its highest since 1987, raising our structural unemployment rate estimate by 0.48pp.
- That could understate the structural shift amid a substantial drop in the threshold, rise in the minimum wage (jobs ban) and benefit rates. Some will go ‘inactive’ on disability.
- The unemployment rate must rise more than its natural rate to deliver disinflationary pressure sustainably. Our structural estimates suggest it won’t break excess inflation.
2. UK Fiscal Slippage Rules
- The UK’s de facto fiscal rule is slippage, with a £50bn to £100bn increase in borrowing between initial official forecasts and outcomes. 2025-26 made another slippery start.
- Politicians spend any space in the OBR forecasts, skewing surprises to higher spending. Yet tax hikes keep failing to raise the hoped revenue, motivating further increases.
- Investors should not be fooled by forecasts for consolidation when the failed strategy driving the fiscal slippage rule survives. Issuance may stay near £300bn in 2029-30.
3. US Politics: ‘As Ye Sow…’
- The Epstein files row has intensified deep splits in the MAGA movement and triggered persistent demands for accountability.
- Trump’s recent pivot towards supporting Ukraine and critical foreign policy shifts have fuelled further rifts among his traditional base.
- Despite controversies, the key midterm factor remains Trump’s economic agenda, as tariffs and fiscal changes may hit his core supporters hardest.
4. ECB: Watching the Good Place
- The ECB kept its description of the policy setting as in a good place, and wants to watch the news in the next few months. Lagarde refused to emphasise September’s meeting.
- Euro strength is depressing inflation below target in the near-term forecasts, but the ECB remains relaxed about this. It sees the outlook as broadly unchanged since June.
- We still see rolling resilience in the economy and doubt US trade policy will break it. More rate cuts are inappropriate without demand destruction, so we don’t expect any.
5. The Trade War Is Dead! Long Live the Trade War!
- Despite all of the dire headlines about tariffs on Canada, Mexico and the European Union, the only trade war that matters is effectively over. China has won.
- In the short run, economic policy uncertainty is receding but it’s not fully normalized. It’s time to adopt a risk-on posture.
- In the long run, equity investors should not expect the S&P 500, which trades at forward P/E of 22, to continue to outperform global stocks in the next expansion cycle.
6. New Barbarians Podcast | Episode #029 | Recap & Reset: Macro Shifts, Ethereum’s Spike, MicroStrat…
- Podcast has been running for almost seven months with recent guest episodes
- Discussion on recent global asset trends and market news, including inflation, Fed rate cuts, and Trump’s tariff threats
- Mention of interns from CUNY City Tech helping with macro database analysis and highlighting Ethereum’s strong performance in the market.
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
7. Potential Change in Capital Gains on Stocks & Securities Transaction Taxes: Impact on Korean Stocks
- The capital gains tax on stock sale gains and securities transaction taxes could be raised in 2H 2025, which could negatively impact the Korean stock market, especially small caps.
- Combination of higher securities transaction tax and capital gains on stock sales could result in local retail investors selling their shares in 4Q 2025, before these changes come into effect.
- Although many small caps in Korea have performed well this year, the potential changes on these two important taxes could put some damper on the recent excellent share price performances.
8. HEW: Trade Deals & Fiscal Slippage
- Market narratives were driven by US trade pacts, critically with Japan, the ECB watching data from a good place, and further evidence of UK fiscal problems.
- Tariff uncertainty eased slightly, but it is still fierce ahead of the 1 August deadline. PMIs remained resilient, and UK retail sales rebounded into growth again for Q2.
- Next week brings Fed, BoC and BoJ meetings (broadly on hold), US and euro-area GDP growth for Q2, US payrolls, euro-area unemployment and slower flash HICP data.
9. BUY/SELL/HOLD: Hong Kong Market Update (JULY 21)
- HSI poised to break 25k for first time since 2022. Next resistance 27100. Hong Kong market outperforming global markets by wide margin since our BUY was initiated in March 2024.
- Financial, materials and healthcare sectors leading the market higher as tech sector consolidates. China shares still offer the best valuation metrics in Asia.
- Alibaba Pictures (1060 HK) , renamed Damai Entertainment has seen increased analyst attention as the company becomes the Live Nation Entertainment, Inc (LYV US) of China.
10. Stay Overweight Japanese Equities
- Despite the Upper House election result we are overweight Japanese equities and a buyer of the yen.
- Business cycle indicators are positive; the profit and investment cycles in upswing. Companies are highly diversified – foreign sales account for 40% of sales and 37% of production is abroad.
- They are hedging their bets by expanding in the US and India while scaling back in China. These factors contribute to the resilience of corporate earnings growth.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK CPI Lifts Hawkish Case in June
- UK inflation surged 0.2pp beyond the consensus again in June, with underlying inflation measures broadly inconsistent with the target and headlines moving the wrong way.
- The consensus is failing to learn the lesson of intense underlying pressures. The CPI rate rose 0.6pp since Jan instead of falling 0.4pp and is 1.4pp higher than called a year ago.
- Policymakers seem infected with dovish fear about the labour market ahead of August’s meeting. CPI is 0.9pp higher in our year-ahead forecast, and we were right a year ago.
2. UK Jobs Data And The Muddled MPC
- UK payroll revisions removed most of May’s weakness, while wage and price inflation is too fast, yet the BoE probably won’t back down from an August cut as the UR rises.
- Fewer payroll inflows explain its downtrend, with <24yo suffering sustained pain, but the 25-64yo endure the taxation hit, structurally raising unemployment by ~0.5pp.
- Wage growth isn’t showing signs of new disinflationary demand pressures, so we expect excessive underlying wage and price trends to persist, not helped by an August BoE cut.
3. Asia Cross Asset: Liberation Day 2.0 and Asia
- Not surprised by recent events in the equity market, as it aligns with forecasted growth trends in Asia
- Transitory factors such as front loading and transshipment contributing to expected decline in H2 growth
- Expectation for central banks in the region to potentially ease rates in response to current economic conditions
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
4. US Inflation Creeps In Quietly
- Rebounding headline and core US inflation in June understated the underlying growth, with shelter rising at its slowest pace since August 2021. Tariff pain crept in belatedly.
- Commodities, less food, energy and car prices grew by 0.3% m-o-m, the fastest since Feb-23, and services (ex-shelter) hit 0.4% m-o-m, both inconsistent with the target.
- Less than half of the post-election surge in expectations has survived so far. Further rises remain likely, even if sustained avoidance smooths and reduces the full impact.
5. HEW: Inflation Persists, But Cuts Loom
- Persistent upside inflation surprises and sticky wage growth are lifting hawkish market narratives, defying central bank and consensus hopes for a quick return to target.
- UK inflation jumped well above forecast in June, strengthening the hawkish case, while US core inflation shows tariffs adding to excessive underlying price pressures.
- Next week, attention turns to the ECB decision, July flash PMIs, and UK public finances, as markets weigh central banks’ willingness to ignore resurgent inflation.
6. The Bullish Elephant in the Room
- We have been fairly cautious on equities in the past, but that’s changing. There is a bullish elephant in the room that is becoming evident and can’t be ignored.
- Market psychology had panicked and became overly concerned about left-tail risk. . Better, or less bad, news emerged and price momentum became dominant.
- Our base case scenario calls for the rally to continue into the August–September time frame.
7. Tuning Tariff Impact Estimates
- President Trump’s tariff policy seemingly follows a random walk with a drift towards deals. Path dependency raises risks and uncertainty around his volatile whims.
- Corporate avoidance measures have spared their customers from most of the pain, but Vietnam’s deal as a template could belatedly bring more of the pain to bear.
- We assume most countries stay at 10%. The impact of others rising to 20% may be smaller than the anti-avoidance hit, with the total now worth less than 0.4% to UK GDP.
8. Hong Kong Alpha Portfolio (June 2025)
- The Hong Kong Alpha portfolio has significantly outperformed the Hong Kong indexes in June and since inception. Outperformance range is 17% to 23% since inception.
- At the end of June, we sold positions in the tech sector after substantial gains. The portfolio’s exposure to the consumption sector was also trimmed, both discretionary and staples.
- The portfolio added exposure to the metals refining sector and initiated positions in conglomerates Shanghai Industrial Holdings (363 HK) and Citic Ltd (267 HK) .
9. Korea: Short Selling Data Analysis: 3Q 2025
- We are introducing a new regular series called “Korea: Short Selling Data Analysis.” We will try to provide this insight on a quarterly basis.
- Net short balance ratio for top 20 stocks in KOSPI averaged about 1.7% three months ago, much lower than current levels (3%).
- The average short interest ratio of these top 20 stocks in KOSPI with the highest short balance ratio was 2.6x as of 10 July 2025.
10. Korean Government’s New Task Force for Inclusion in a Major Global Index + IBKR Korea Trading Signal
- In this insight, we discuss Korean government’s new task force for Korea to be included in a major global index.
- Prior to this major market moving event, there will be some important signals.
- One of the most important signals could be major global securities companies (such as IBKR/TD Ameritrade) allowing trading of Korean stocks to customers world-wide.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Inconsistently Dovish Pricing
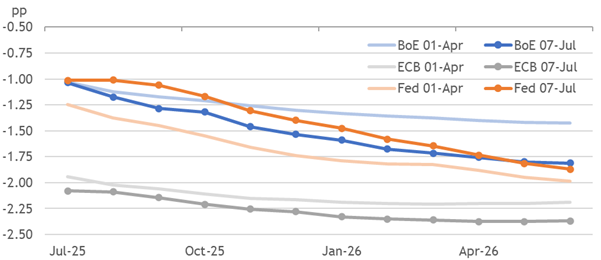
- Dovish market fears from April have unwound for the Fed, yet deepened for the BoE, despite broadly resilient data and cautious guidance from policymakers reluctant to cut.
- Equity prices have relied on this resilience to recover, yet expectations for extended rate-cutting cycles imply it breaks. Payrolls only forced half of the gap to close.
- We expect ongoing resilience to keep rolling market pricing for rate cuts later, with the unnecessary easing ultimately never being delivered by the BoE, Fed, or ECB.
2. Labour’s Collapsing Credibility
- Labour failed to campaign on a platform up to the UK’s structural problems, depriving it of the support to deliver change in its first year. Reform UK now lead most polls.
- Spending cut U-turns compound the fiscal hole exposed by the slippage of optimistic assumptions, making further tax hikes and more persistent deficits seem inevitable.
- Far-centrism has been rejected, but challenges to Labour’s right and left break its ability to triangulate back towards success. Investors may not stay so forgiving.
3. Can a New Bull Begin at a Forward P/E of 22?
- It’s official, our long-term market timing model has confirmed a buy signal at the end of June.
- The S&P 500 is trading at a forward P/E of 22. Can a new bull truly begin at such elevated valuations?
- We interpret the buy signal from our long-term market timing model as a buy signal for global equities, and not just the U.S. market.
4. HEM: Rolling Resilience
- Economic activity is robust with a tight labour market.
- Price and wage inflation are generally above 2%.
- Despite predictions of a downturn, the current economic regime remains stable.
5. Why America’s Manufacturing Dreams Might Be Economic Nightmares
- Germany’s GDP declined 0.2% in 2024, Japan’s industrial production contracted 1.1%. Meanwhile, America’s service-focused economy outperforms manufacturing-heavy competitors consistently.
- Tooling costs are 10x higher in America than China. Even 145% tariffs insufficient—need 350% tariffs to make domestic manufacturing viable.
- US services exports surpass lost manufacturing profits. Services employ 84% of private sector, pay more than manufacturing ($36 vs $35/hour).
6. De-Dollarisation Debate : Unmasking USD Over-Valuation
- Despite headlines about BRICS alternatives, gold hoarding, and China’s reduced U.S. Treasury holdings, the data shows no structural shift away from the dollar.
- A 10% decline in the DXY under six months is not an uncommon occurence from a longer term perspective.
- The dollar’s weakness is driven by a historically overvalued real effective exchange rate (REER) and falling oil prices, not a structural decline.
7. HEW: Kicked Can Lands Steady
- Trump kicked the tariff can a few weeks to 1 August, leaving other policymakers and markets in a wait-and-see mode. Pricing was little changed amid little news elsewhere.
- We thematically explored the market implications of resilience rolling cuts later, how healthy the US labour market data is, and dug into the UK’s political problems.
- Next week’s UK labour market and inflation data are critical ahead of an August BoE decision we believe remains finely balanced. US and EA inflation are other highlights.
8. US Claims Continue To Cruise Calmly
- Rising continuing claims in recent months have been heralded as a canary warning of belated suffering in the labour market. But the problem is ending before it ever began.
- US employment growth is still aligned with its long-run average, and the unemployment rate is unchanged on the year. Openings and quits are also steady with averages.
- The Fed needs excess disinflation to cut, and we believe this won’t materialise. That also avoids demand and policy pressure on the BoE and ECB, helping them hold rates.
9. Barbarians with Bandwidth: Why Christina Qi Left the Hedge Fund World to Reinvent Data
- Recap of last week’s events including good inflation news, pressure on Fed to cut interest rates, tensions between Israel and Iran escalating, and market outcomes
- Factors showing risk-on sentiment with sales growth up, EPS growth strong, volatility and quality return on equity fluctuating
- Discussion on factors influencing return on equity and quality, with insights into market trends and data analysis techniques
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
10. Systematic Global Macro: Data, AI, and Models Are Reshaping Investing | New Barbarians AI Agent #05
- The podcast episode discusses the shift towards systematic global macro investing and the advantages of using quantitative models and algorithms.
- The sources highlight the importance of technology and data in driving this shift, but also emphasize the value of human judgment in certain situations.
- Listeners are encouraged to explore the freely available Google Colab Jupyter notebook for replicating sector performance analysis discussed in the episode.
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. HEW: Payrolls Waking Up Rates Pricing
- Dovish rate pricing had been ignoring resilient data until US payrolls delivered a rude awakening. We believe rates remain too dovish relative to reality and equity prices.
- BoE surveys also revealed resilience in defiance of dovish pricing, while the rise in EA unemployment merely matched ECB forecasts and was heavily reliant on Italy.
- Next week’s deadline for US tariffs is the main risk event, as not all countries will likely get an extension. Monetary policy decisions come from the RBA, RBNZ, BNM, and BOK.
2. Mid-Year Themes Review – Part I
- How did our major investment themes do so far in 2025?
- Review of the performance of the major markets and asset classes we focus on
- We revisit our outlook for each of those asset classes for H2 25
3. BoE Surveys Sustain Resilience
- The Decision Maker Panel and Credit Conditions Surveys remained resilient. Price and wage inflation are stuck at excessive levels, and US trade policy makes little difference.
- Default rates are falling while the availability and demand for credit are rising to reveal a loosening of monetary conditions. There is no evidence of policy being too tight.
- Inflation and labour market data matched BoE forecasts from May, when most members were biased to slow easing. Resilient surveys should discourage it from cutting again.
4. Oil: Revisiting My Forecast
- Oil supply is projected to outpace demand growth through 2026, leading to rising inventories and sustained downward pressure on Brent crude to below USD60pb.
- Opec+ output increases, quota disputes (especially with the UAE), and the potential unwinding of voluntary cuts could further flood the market.
- US shale producers and international oil companies are reducing investment due to lower prices, but current Brent levels are not yet low enough to force significant cuts.
5. Korean Holdcos Vs Opcos Gap Trading Opportunities in 3Q 2025
- In this insight, we highlight the recent pricing gap divergences of the major Korean holdcos and opcos which could provide trading opportunities in 3Q 2025.
- A whopping 87% (33 out of 38) holdcos/quasi holdcos outperformed their opco counterparts in the past three months, which is one of the best ever in the past two decades.
- This appears to be one of the classic “buy the rumor, sell the news” trading opportunities.
6. Gap Trade Opportunities in Korean Prefs Vs Common Share Pairs in 3Q 2025
- In this insight, we discuss numerous gap trade opportunities involving Korean preferred and common shares in 3Q 2025.
- In particular, five pairs of common and preferred stocks have experienced more than 20% widening of their share prices in the past six months.
- These companies (Doosan Corp, Mirae Asset Securities, KIS Holdings, Daishin Securities, and LG Chem) are more likely to revert to closing their gaps in the coming weeks.
7. EA: Calm At The Inflation Target
- An unsurprising achievement of the 2% target might urge a celebration at the ECB, but it does not demand policy action. Energy price declines can’t be relied upon to repeat.
- The early consensus forecast was surprised on the upside, but raised by last week’s releases in France and Spain. So, while reassuring, this outcome is not dovish.
- We expect inflation to stay close to the target, whereas the ECB forecasts a substantial drop below it, while calling policy well-positioned. We still see no more rate cuts.
8. Calm Before the Currency War? Central Banks Go Their Separate Ways
- European central banks have embraced a more preemptive approach compared to the Fed in responding to the looming arrival of tariffs under the Trump administration.
- The Bank of Japan refuses to raise interest rates, despite rising core consumer price inflation, due to uncertainty about tariff negotiations with the US. Quantitative tightening will pared in 2026.
- The People’s Bank of China (PBoC) has only modestly lowered policy rates. The Fed’s future policy rate cuts could determine the timing and scope of future PBoC policy easing.
9. Mid-Year Themes Review – Part II
- How did our major investment themes do so far in 2025?
- Review of the performance of the major markets and asset classes we focus on
- We revisit our outlook for each of those asset classes for H2 25
10. H2 ’25 Outlook: Modest H2 After Strong H1. Themes: Trade, Consumption, Tech Spending, Yields
- In H1, Asia climbed several walls of worry. Valuations are slightly higher than long-term average. H2 could be more modest, as export driven growth moderates and trade agreements become contentious.
- Our end-2025 targets are: MXASJ 850, SHCOMP 3760, Sensex 85000, HSI 26000, KOSPI 3400, TWSE 23500, Strait Times 4200, JCI 7450, SET 1150. Overweights on Korea, HK/China, India, continue.
- Asian currencies should continue to appreciate, driving more FII flows. Benign inflation and headroom for monetary easing are key tailwinds. We expect two rate cuts by the Fed in 2025.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Defence Spending Is Not Stimulative
- NATO raised its target for defence spending to 5% of GDP, with Spain opting out. This increases pressure for tighter monetary conditions than were otherwise appropriate.
- Defence spending offers weak growth multipliers, so the policy is more likely to stoke deficits than productivity. Central banks may respond with a more hawkish stance.
- With debt levels already high, the move risks crowding out other spending and lifting sovereign risk premiums. Bond yields suffer from higher deficits and future rates.
2. Israel/Iran/US: Ten Pointers
- Recent events have highlighted the difficulty in predicting the progression of the Iran/Israel conflict.
- Despite this, the volatility caused by these headlines has not significantly impacted market perspectives.
- The supply/demand equation remains the primary influence on market thinking regarding oil.
3. Top 10 Korean Stock Picks and Key Catalysts Bi-Weekly (20 June to 4 July 2025)
- In this insight, we provide the top 10 stocks picks and key catalysts in the Korean stock market for the two weeks (20 June to 4 July 2025).
- Kakaopay was the best performing stock in KOSPI in the past two weeks. It could be a key potential beneficiary of the increased use of stablecoin based system in Korea.
- The top 10 picks in this bi-weekly include S&T Holdings, Samsung Life Insurance, Samsung SDS, Samsung Securities, Hyundai Elevator, SK Hynix, Paradise, Hanwha System, Hanwha Aerospace, and Korea Kolmar.
4. The New OS for Quant Finance: OpenBB, AI Agents & the Death of Legacy Terminals | New Barbarians …
- Isan Sarakil is the Chief Product Officer at OpenBB, a platform that provides advanced analytics to every investor.
- OpenBB is tearing down old walls of legacy market data systems and utilizing AI to change the way markets are understood and traded.
- Isan discusses OpenBB’s journey and how new tools can give investors an edge in analyzing complex financial data, such as the Fed’s communications.
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
5. Asian Equities: Absolute and Relative Valuations – Spotting Mean Reversion Opportunities
- We take a detailed look at forward PE multiples, absolute and relative to Asia, of all Asia ex Japan markets. North Asia is in line with average valuations, India expensive.
- Juxtaposing valuations in comparison to history with the earnings environment of each market, we arrive at conclusions about which market should rerate and which should derate.
- We posit continued rerating for Korea and Philippines. India should derate. HK, Taiwan, Indonesia and Singapore could rerate modestly. Malaysia and Thailand are cheap but seem destined to remain so.
6. A Sharp Increase in the Lending Balance of Korean Stock Market Suggests A Pull-Back
- In our view, the sharp increase in the lending balance is one of the signs of many investors preparing for a pull-back in the Korean stock market.
- The lending balance of the Korean stock market surged from 47.3 trillion won on 2 January 2025 to 90.4 trillion won as of 20 June 2025.
- The rising lending balance in the Korean stock market could be construed as a bearish sign.
7. India – Reasons To Overweight
- Overweight, Indian equities with a bias towards industrials, property and consumer stocks.
- Trading Post hopes you took advantage of last year’s correction to buy into India, as recommended. If not, there is time.
- Investing in India is ultimately about the domestic story. Business cycle indicators are improving, and the multi-year structural growth narrative remains compelling.
8. Steno Signals #202 – Peak WW3 Fears Return!
- Over the weekend, oil traders dusted off their Strait of Hormuz crisis playbooks—and once again, they overplayed their hand.
- Saturday’s U.S. strike inside Iran sparked a sharp wave of geopolitical anxiety, turbocharged by Iran’s retaliatory missile barrage and the familiar threat from Tehran’s Parliament to shut down the Strait.
- Add a few “Hormuz closed?” headlines and prediction markets went into meltdown, briefly treating a full blockade as the base case.
9. Global Rates: Monthly Inflation Outlook
- U.S. inflation expected to accelerate over the next few months, with core inflation forecasted to rise to 3.8% by December
- Trade policy and geopolitical risks, such as the potential for oil prices to spike, are factors supporting front end tips breakevens
- Euro area inflation data shows softening trend, with core inflation falling to 2.3% in May, impacted by factors like timing of Easter holidays
This content is sourced through publicly available sources and has been machine generated. Information displayed is for general informational purposes only.
10. Growth Broadly Back In The Black
- PMI recoveries extended in June, taking averages above 50 as manufacturing is its strongest since Sep-22, and services almost align with its averages of recent years.
- The UK survey balances suffered from bad vibes, so they are the primary beneficiary of sentiment improving. Their recovery can extend further as vibes improve.
- Broad expansion helps labour demand to keep pace with supply, denying doves proof of a disinflationary demand shock. Without that, cuts roll later and may not resume.

Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK Course-Corrected CPI Stays High
- UK inflation unsurprisingly slowed in May as a correction to vehicle excise duty knocked 0.1pp from the rate, reversing all the upside to our above-consensus April forecast.
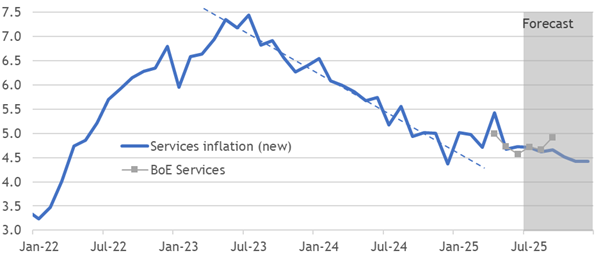
- Services inflation aligns with the BoE’s forecast from its May forecast, where MPC members were biased towards slowing their easing. Underlying rates remain too high.
- Inflation keeps trending above the consensus, cumulating a 1pp error since rate cuts began, but aligning with our forecast from 1yr and 2yrs ago. We remain hawkish.
2. BoE Still Seeking Evidence
- Guidance around an unsurprisingly unchanged BoE rate preserved the necessary uncertainty about when it might ease again, albeit with a broad bias to do more later.
- Dave Ramsden joined the dovish dissent, taking it to three for a 25bp cut, but none of them are in the MPC majority revealed in May as leaning towards a slower pace of cuts.
- We believe the August decision remains finely balanced for the majority. Ongoing data resilience, discouraging the Fed and ECB from easing, should also keep the BoE on hold.
3. US/China: Sprint vs Stamina
- The recent US/China trade talks highlighted Beijing’s superior leverage and determination.
- Beijing is in a stronger position in terms of both leverage and willingness to persist.
- Avoiding a re-escalation after the current 90-day truce relies on Washington making more concessions.
4. HEW: Playing For Time
- US diplomacy with Iran has been given two weeks, bringing it close to the reciprocal tariff deferral date. Both may roll later, while central bankers wait to see the impact.
- Unsurprising UK and EA inflation data offered little direction, nor did the BoE or Fed. Brazil and Norway delivered opposite surprises outside a flood of cautious statements.
- Next week is much quieter for data and decisions (TH and MX). The flash PMIs are the main global highlight, although some HICP and PCE data are notable on Friday.
5. Euro Area Wage Costs Closer To Target
- Non-wage labour costs rebounded in Q1, damping the overall slowdown to a surprisingly modest extent after the crash in negotiated wage growth revealed in May.
- Unit labour cost growth has encouragingly slowed below 3%, with the latest impulse only 0.6% q-o-q. Any further easing here could encourage monetary easing to resume.
- Stability at a low unemployment rate still suggests the policy setting is close to neutral, so we doubt disinflationary pressures will mount further and forecast no more rate cuts.
6. EA Inflation Predictably Near The Target
- Disinflationary news from May’s flash inflation release was confirmed in the final print, although a rebound in some underlying inflation measures damped the initial signal.
- Resurgent oil prices could rapidly reverse the dovish space expanded by past falls. Our forecast bumps around the target through 2026 and 2027, settling at 2%.
- Other forecasts are a little lower and only suffer a slight bias to be exceeded. The ECB can remain reassured by an outlook close to 2% without cuts, and not deliver any more.
7. China – Where To Invest?
- Overweight AI, high tech, robotics, renewables and bio-tech. Underweight on consumer discretionary, property and export cyclicals.
- China has become even more vital to its green transition. At the same time the shift in government mindset means that domestic innovation is advancing at a breathtaking pace.
- That said the economy is yet bottom. The profit cycle downturn is worsening; As of April 30% of manufacturing companies were loss making, up from 25% in November
8. Steno Signals #201 – The Mullahs Are Toast – Re-Inflation Is Back!
- Happy Monday from Copenhagen.
- What a comeback by JJ Spaun at Oakmont yesterday (sorry to the non-golfers), and what a comeback risk is about to make this week.
- Iran’s mullah-tocracy is on the brink, and it could be a catalyst for a big bounce in risk appetite.
9. Walker’s Weekly: Dr. Jim’s Summary of Key Global Macro Developments – 20 June 2025
-
US interest rate cuts expected soon as economic data deteriorates across sectors.
-
Indonesia delays rate cuts; Philippines eases but risks peso weakness.
-
China retail sales rise, but property sector continues to underperform.
10. Cancellation of Existing Treasury Shares in Korea – Government Likely to Provide a GRACE PERIOD
- The Korean government may not force the listed companies to suddenly cancel all their treasury shares all at once.
- Rather, a GRACE PERIOD is likely to be given for companies with existing treasury shares by which they need to cancel them.
- Going forward, the Korean government is likely to decide to allow acquisition new of treasury stocks only when the purpose is to cancel them, excluding bonus payments or stock compensation.

Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK: Some Workshy Start Looking
- A broadly softer labour market report could easily be used to overstate the fundamental significance. Unemployment’s rise was expected and only 0.2pp on the year.
- Employment is growing and redundancies are low, but when the inactive look for work, long-term unemployment rises. Yet the workshy will struggle to compete for jobs.
- Wage growth slowed despite a 0.5% m-o-m impulse. Costs are rising excessively fast, so the BoE still doesn’t have space to keep easing, and we expect no more rate cuts.
2. UK: Retreating To Trend Again
- Residual seasonality shocked the consensus again, this time on the downside, as the spurious surge is replaced with stagnation for the rest of the year in our view.
- The 0.3% m-o-m decline dragged GDP back toward its trend, wiping out the highly supportive statistical carryover effect for Q2, which we now forecast at 0.1% q-o-q.
- BoE forecasts are on track, allowing the MPC’s bias to slow easing to materialise with a pause. We expect cuts to keep being rolled later, with no more delivered in this cycle.
3. US Consumer Pricing Still Ignores Tariffs
- Another downside surprise in headline US inflation reflected the lack of pass-through from tariff increases, with headline and core rates of only 0.1% m-o-m in May.
- Commodities, less food, energy and car prices stalled as airfares and apparel fell again. But services (ex-shelter) inflation stayed too high to be consistent with the target.
- Low headline rates raise dovish political pressure and the risk of a cut, but the tight labour market should encourage the Fed to keep rolling potential cuts later.
4. HEW: Geopolitics Blow Hot And Warm
- Israel’s attack on Iran squeezes supply in an unwelcome shock that is harder for central bankers to look through post-pandemic. Warming US-China relations had less impact.
- Avoidance measures have helped mitigate the tariff shock so far, with US CPI holding steady. The importance of recent disappointing UK demand data is easy to overstate.
- The BoE is set to hold rates, probably with two dovish dissents and no commitment to August. UK inflation should slow with airfares normalising and a vehicle tax correction.
5. Why “Sell America” Isn’t Equity Bearish
- We have been fairly cautious in our U.S. equity outlook in these pages, but that doesn’t mean we are equity bearish.
- We are embracing the “Sell America” trade because of a combination of deteriorating U.S. fiscal position and the trade war policy pivot that’s contributing to falling confidence in USD assets.
- The key risk to our “Sell America” thesis is whether the U.S. can sustain its technology dominance in the next investment cycle.
6. US Treasuries: YOU BREAK IT YOU BOUGHT IT!
- The US Administration is undermining foreign demand for dollar assets at the same time, supply for US treasury debt is rapidly expanding.
- The Fed is constrained from lowering the Fed Funds rate due to rising yields in the long end of the treasury market.
- The long end of the US Treasury market is feeling the effects of Trump’s tariff policies. The US equity market will follow as risk premiums rise.
7. Asian Equities: Southbound Flows Turning to Dividends and Beaten Down Sectors
- In May, onshore Chinese investors bought US$5.85bn of HK-listed stocks, down sharply from the $19-21 bn net buying range of the past three months. The favorite stocks also changed sharply.
- The hitherto Southbound favorites, Tencent, Alibaba and Xiaomi were sold down. Onshore investors’ current favorites seem to be the high dividend yield stocks, particularly China Mobile, CNOOC, China Construction Bank.
- Competitive pressures crashed food delivery and EV share prices. But Southbound investors seem to see these share price drawdowns as buying opportunities. Meituan, Li Auto were bought in significant measure.
8. Walker’s Weekly: Dr. Jim’s Summary of Key Global Macro Developments – 13 June 2025
-
India cuts interest rates as currency pressure eases, aiming to boost private investment without triggering inflation concerns.
-
China’s exports rise overall despite a sharp drop to the US, showing strength through trade diversification.
-
Regional trade flows shift sharply, with Taiwan and Vietnam surging ahead of potential tariffs, while uncertainty clouds second-half investment outlook.
9. Inflation Concerns Overdone
- For Trading Post a global recession has never been on the cards, nor a resurgence in inflation.
- If mainstream economists continue to raise alarms about a tariff induced inflation surge, it reflects a fundamental misunderstanding of how inflation works and what drives it.
- Current trends in broad money growth, credit cycles and monetary policy settings simply don’t support the prevailing inflation narrative.
10. Trade Avoidance Easing Shocks
- China’s crashing exports to the US partly reflect avoidance measures, including rerouting through other countries and marking down import prices to subsidiaries.
- Exports to the EU and UK are only trending slightly higher, making little difference to disinflation. ASEAN countries, and especially Vietnam, are seeing trade surge again.
- The US may clamp down on avoidance measures that have eased the shock so far. It could make a painful example of one to encourage concessions from all trade partners.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. US vs EU: Mutually Assured Destruction?
- Section 899 is generally understood to be about leverage and deterrence.
- It is unlikely to be fully implemented due to the potential harm it could cause to the US.
- There are concerns about what could happen if the EU challenges this approach or if it is partially intended as a method to raise revenue.
2. Lee Jae-Myung Becomes the New South Korean President – Four Investment Themes That Could Outperform
- Now that Lee Jae-Myung has become new South Korean President, the uncertainty revolving who will lead South Korea in the next five years is now over.
- In this insight, we discuss four investment themes (related to Lee Jae-Myung becoming the new South Korean President) that could outperform the market for the remainder of 2025.
- The four investment themes include Korean Holdcos/Quasi Holdcos, Korean Cultural Contents, Securities, and SK Group Companies.
3. EA: May Be Disinflation’s Return
- Negative payback in services inflation dragged the headline EA rate down to 1.92% in the May flash. Although only 7bps low on the day, releases last week had cut 0.1pp.
- Inflation now looks set to spend a few months below the target rather than at or even above it, as had seemed likely until recently. This is not because of re-rooted imports.
- Euro appreciation and low energy prices have expanded the ECB’s room to cut rates, but we still see June as the final one amid tight labour markets and peers backing away.
4. HEW: Poorly Positioned Doves
- The ECB was even more hesitant to signal cuts than we expected, with the level after the unsurprising cut now deemed well-positioned. Cuts will require downside news.
- Disinflationary surprises across the Euro area in the May flash releases are already embedded in that assessment. Doves are poorly positioned for this reaction function.
- US inflation data may be the most crucial global release next week, although the signal may not be clear. Statistical issues affect the UK labour market and GDP data.
5. The Art of the Trade War: XI WATCHES AS TRUMP SERVES TACOS
- President Xi agreed to discuss issues including rare earths, chip design restrictions, and Chinese student visas with President Trump. China warns the US on its increased arms shipments to Taiwan.
- The auto industry is facing disruptions in production due to shortages of rare earth metals.
- The headline noise is starting to lose its luster as soft and hard data signals begin to pressure markets again.
6. HONG KONG ALPHA PORTFOLIO (May 2025)
- The Hong Kong Alpha portfolio underperformed its benchmark in May by 3%, however it has outperformed Hong Kong indexes by 3 to 19% since its launch 8 months ago.
- We continue to increase portfolio exposure to the consumption sector. We have added Alibaba Pictures (1060 HK), ZhongAn Online P&C Insurance C (6060 HK) & Sun Art Retail (6808 HK).
- At the end of May we sold positions in Kingsoft Corp (3888 HK) and Topsports International Holdings (6110 HK). We reduced Lingbao Gold Co Ltd H (3330 HK) .
7. Lee Jae-Myung’s 20 Trillion Won+ Supplementary Budget: Free Money, Don’t Worry and Be Happy
- One of the major policies that Lee Jae-Myung’s new administration is likely to push through is the 20 trillion won (US$15 billion)+ supplementary budget.
- The aim of this policy is to revive the sluggish domestic economy. It is a classic “spend first, worry later” government policy.
- The supplementary budget is basically sacrificing the balance sheet of the entire South Korea at the expense of short term economic stimulus which may have just limited impact.
8. Don’t Buy That TACO Just Yet
- The U.S. Court of International Trade unanimously ruled against the Trump Administration and struck down a whole range of tariffs by citing a lack of authority.
- In reaction, President Trump doubled down by opposing and appealing the decision. The government has workaround options in light of the court decision: The trade war will continue.
- Investors should continue to tilt toward the “Sell America” trade by avoiding USD assets. The court decision prolongs and exacerbates the uncertainty over the effects of the trade war.
9. US – Buy On Dip
- We maintain a buy. The sectoral weightings favour industrials, tech hardware, banks, traditional energy, defence and going into the second half of the year consumer discretionary and AI software companies.
- The US is neither headed for a full-blown recession nor another cost-of living crisis.
- Neither updated business cycle indicators nor broad money growth trends signal a downturn and a resurgence in inflation.
10. HEM: Better Never Than Late
- Companies are adapting to fluctuating trade policies while maintaining strong activity and tight labour markets.
- Despite these positive trends, underlying price and wage inflation remains high.
- While markets anticipate future cuts, the potential for rate hikes in 2026 is often overlooked.