This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
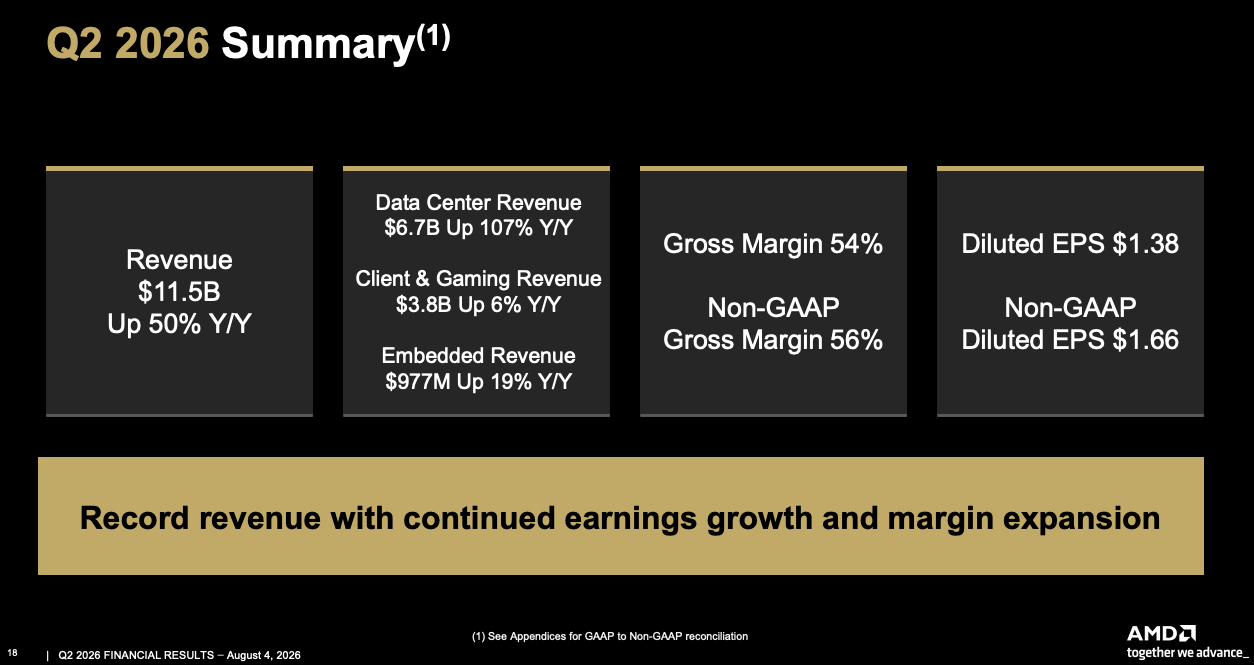
1. AMD Q2 2026. Onwards & Upwards With Beats, Raises, Data Centre Doublings & TAM Expansions
- AMD reported Q2 2026 revenues of $11.5 billion, up 50% YoY, up 13% QoQ and marginally ($36 million) beating the high end of the guided midpoint.
- Looking ahead, AMD forecasted current quarter revenues of $13 billion at the midpoint, up 12.7% QoQ and up 41% YoY.
- Revenue growth now expected to “substantially exceed” the prior long-term target of more than 35%, and EPS expected to “significantly exceed” the prior $20 annual target within the strategic timeframe.
2. Figma Q2 2026. Is The Writing On The Wall?
- Figma reported Q2 2026 revenues of $370.1 million, up 48% YoY and up 11.0% sequentially from $333.4 million in Q1 2026.
- Gross margin expanded 250 basis points sequentially to 85% non-GAAP, which management attributed directly to the first full quarter of AI credit revenue.
- Despite the beat-and-raise report, Figma’s share price fell ~15% on the news. Investors still remain to be convinced that their AI monetization strategy can really succeed in the long term.
3. Taiwan Tech Weekly: DRAM Strands US$1bn of Apple Chips; Customers Now Book 2030 Capacity
- TSMC is holding about US$1bn of finished Apple processors it cannot package for want of DRAM, and first-half smartphone processor shipments fell 15% year over year.
- Memory revenue rose 305% in the first half against 45% for logic; WSTS raised its 2026 industry forecast to US$1.655tn, growth of 108%.
- Winbond’s customers are pressing for supply contracts running into 2030, SanDisk has sold about two-thirds of its fiscal 2028 output, and Nan Ya PCB approved its largest ever plant.