This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
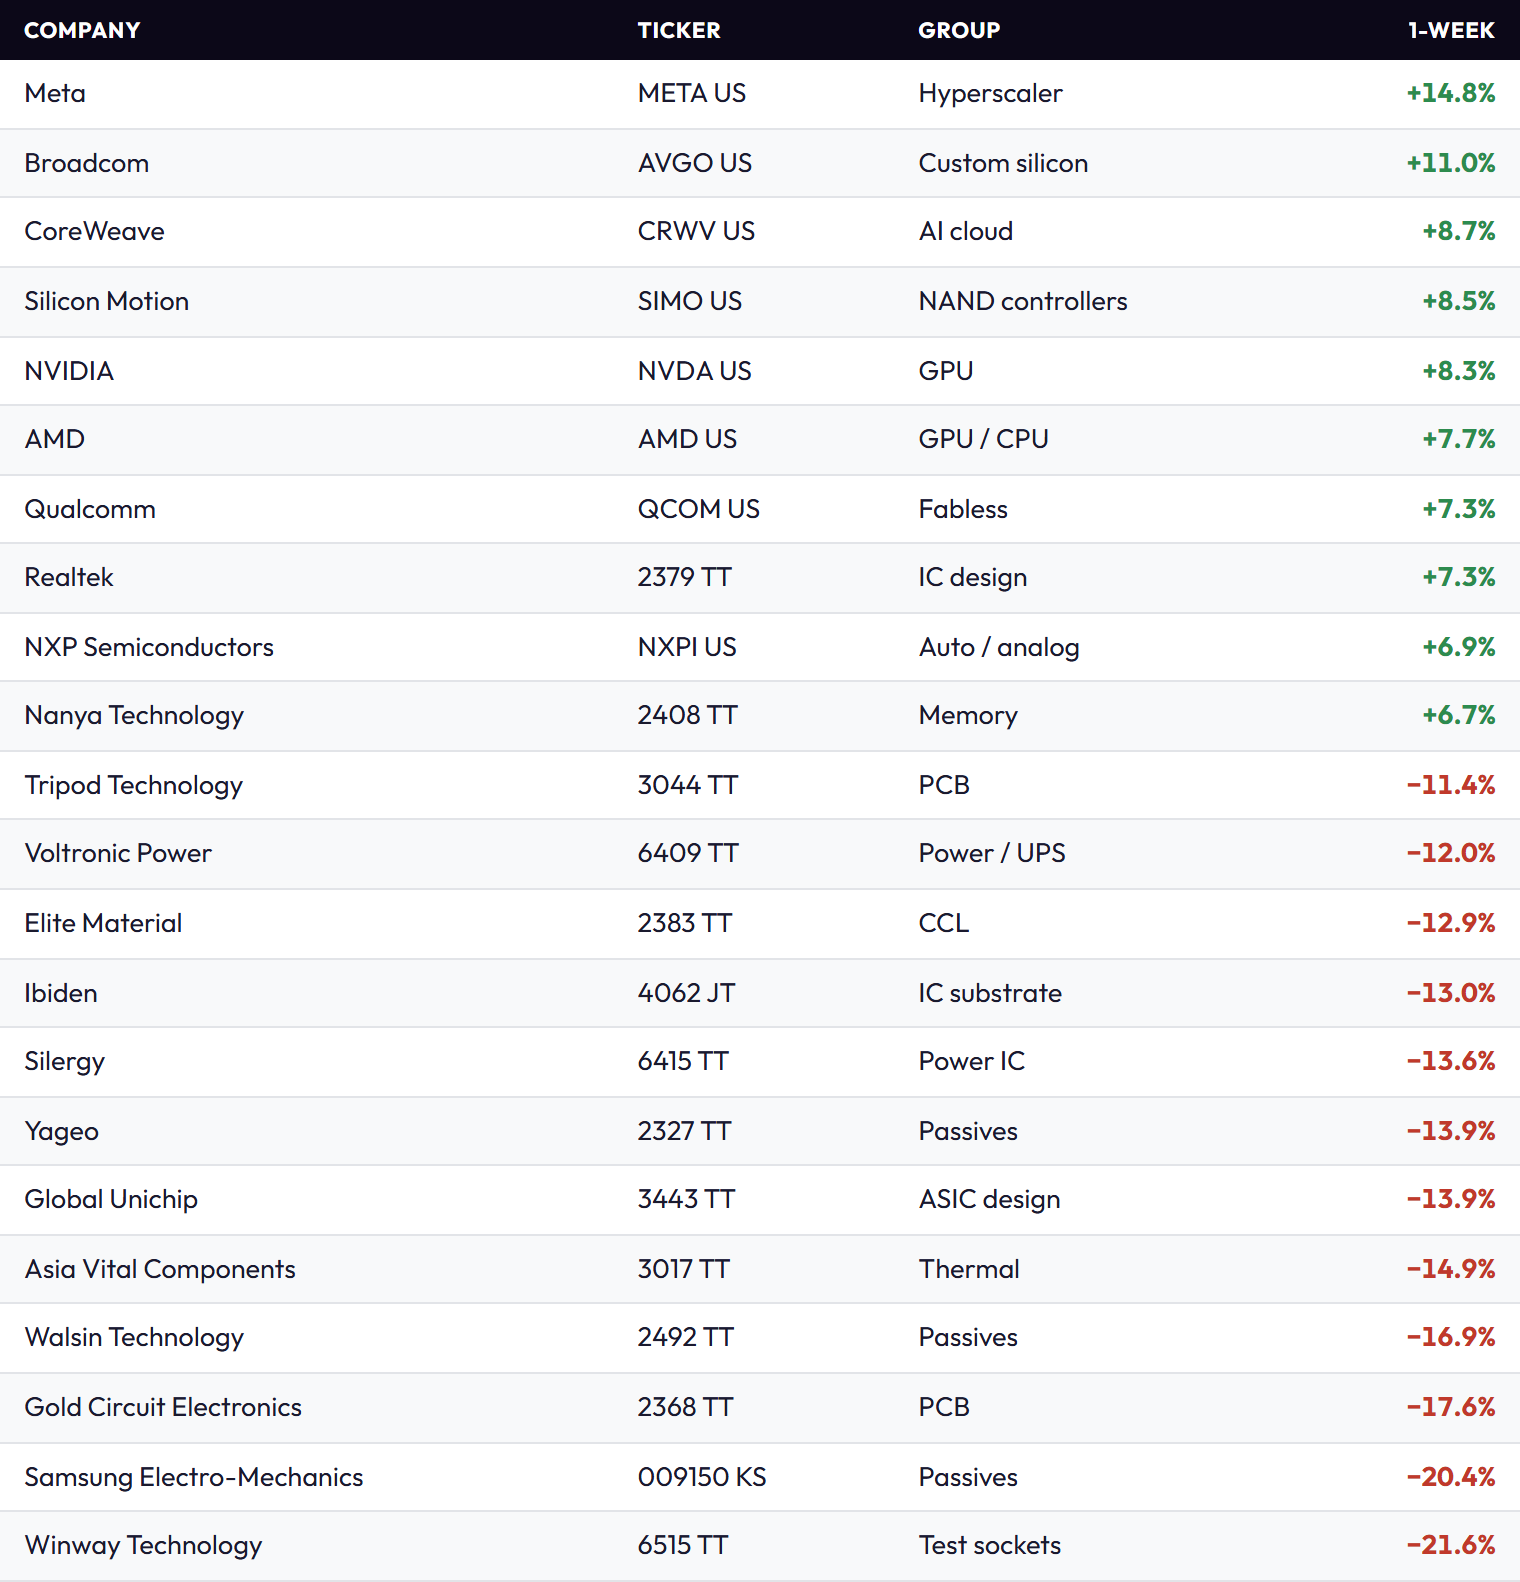
1. Taiwan Tech Weekly: Micron, Apple and AMD Start Funding Their Suppliers
- Micron, Apple and AMD committed a combined US$43bn-plus to the suppliers they depend on, moving the industry from ordering capacity to financing it and shifting build risk onto the buyers.
- Memory economics reached record levels: Samsung’s operating profit rose 19x, and Nanya’s gross margin hit 79.5% on flat shipments, with prices doing all the work.
- SK Hynix raised US$26.5bn for ADRs in the largest US listing by a foreign company, and the week’s selloff reversed in two sessions as money returned to memory and compute.
2. TSMC 2Q26 Preview: A Record June Lands 2Q Revenue at the Upper End of the Guide
- A record June (NT$442.68bn, +67.9% YoY) puts fully-reported 2Q26 revenue at NT$1,270.4bn, about US$40.1bn, at the upper end of the US$39.0-40.2bn guide. Revenue is settled pre-print.
- The question is now the full-year guide. First-half revenvue is up 35.6% YoY, past the “above 30%” bar; the street implies +37%, so a guide raise is partially baked in.
- Also watch whether management repeats the 2-3pp N2 margin dilution and how it frames FY27 capex. At 24.4x forward, TSMC remains relatively inexpensive.
3. TSMC (2330.TT; TSM.US): All Good News Doesn’t Mean A Good Stock Price.
- Third Quarter Revenue: US$44.6 billion – US$45.8 billion, At the midpoint: Quarter-over-quarter; (QoQ): +12% Year-over-year (YoY): +37%;
- In other words, the increase in CAPEX is fundamentally driven by AI demand.
- The shortage is mainly in AI-related mature technologies, especially: PMIC (Power Management IC)
4. Nanya Tech Signals Memory Shortage Extends Through the Second Half
- Nanya’s second quarter set a record on price, not volume: revenue rose 68% QoQ as ASP climbed more than 60% and bit shipments stayed flat, at a 79.5% gross margin.
- Management guided the third quarter to improve further and called results sustainable for several quarters, so the sequential second-half decline consensus had modelled did not survive the print.
- Nanya’s capacity response is now funded: full-year capex is guided to about NT$52bn, four times last year, and a NT$78.7bn placement lifted net cash to NT$198bn.
5. KHI (7012 JP): Production Upgrades & Drone Deal with Airbus
- KHI’s new share and CB issues will fund production upgrades while strengthening the balance sheet. Potential dilution should be in the price.
- The share price has been declining since March as overbought defense contractors were sold off. That is coming to an end. MHI has started to recover.
- Collaboration with Airbus and Eurodrone is another reminder that Japan’s defense build-up is not driven by the wars in Ukraine or the Persian Gulf.
6. Vanguard (5347.TT): June Revenue Reached a Record High.
- Vanguard June Revenue Reached a Record High, Representing the Most Significant Positive Signal.
- Q2 Revenue Was in Line with Expectations, but Not Significantly Above Expectations — This Is Consistent with the Company’s Historical Guidance Approach
- AI Applications and the Tight Supply of 8-inch Foundry Capacity Provide the Largest Upside Potential for the Stock.
7. TSMC (2330.TT; TSM.US): Stock Prices Had Already Priced in Excessively Optimistic Expectations.
- Before the Peak, Few People Realized They Were at the Top of a Bubble.
- The recent sharp decline can be summarized by the following observations: AI is real, but the next challenge may be valuation compression.
- When evaluating the current market correction, the first step is to acknowledge a simple fact. Investors may consider waiting until pessimism has become widespread.