This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
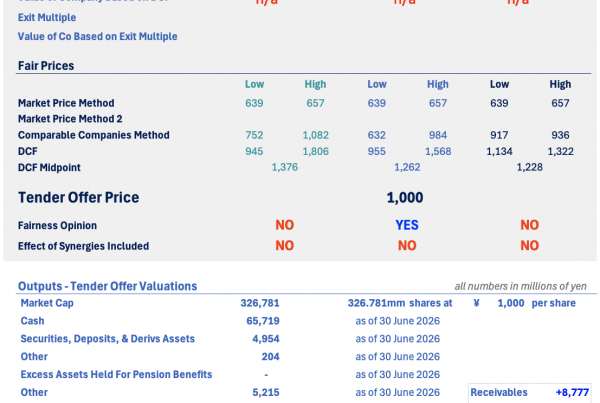
1. Toyota Industries (6201 JP): Evaluating Elliott’s Letter
- Elliott has released a letter urging shareholders to reject Toyota Fudosan’s JPY18,800 offer for Toyota Industries (6201 JP).
- Elliott’s letter makes both sensible (the offer is below 3Q book value, with limited downside risk on a deal break) and outlandish (the standalone plan is worth JPY40,000) assertions.
- There is a good chance of a further bump (to JPY21,000), as an offer below the 3Q book value (disclosed on 3 February) will give Elliott’s campaign a huge boost.
2. China ETF: Huge Outflows; National Team Unwinding?
- Over US$55bn has been redeemed from mainland China ETFs over the last 3 weeks. Headline ETFs take the largest hit while there have been inflows to sector ETFs.
- The large-scale redemptions across a variety of indices point to the National Team unwinding holdings that have been built up over the last year.
- Margin trading rules have been tightened, and this could be another way of ensuring that markets do not run-up too far in the short-term.
3. StubWorld: The Maths For A MUCH Higher Bid For Toyota Inds (6201 JP) Remains Compelling
- A double dose of StubWorld this week as I recap the latest developments in Toyota Group’s egregiously low-balled Offer for Toyota Industries (6201 JP).
- Preceding my comments on TICO are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
4. Skyworth (751 HK): A Long-Dated but Attractive Distribution and Share Buyback Scheme Proposal
- Skyworth Group Limited (751 HK) disclosed a preconditional privatisation through a share buyback scheme along with a proposed distribution and listing of Skyworth Photovoltaic shares.
- The offer comprises HK$4.03 + 0.3699779 Skyworth Photovoltaic shares per Skyworth share, for an estimated total value of HK$10.16, representing a 96.1% premium to the last close price.
- While the offer is attractive, the appraised value of Skyworth Photovoltaic is optimistic – my estimated total value is HK$8.43. Timing is the key risk.
5. [Japan M&A/Activism] The Raksul MBO Is In Danger; Bump Clearly Needed
- In [Japan M&A] CEO & Chairman Entice GS to Sponsor an MBO for Recently Lackluster Raksul (4384) I wrote that this deal was at the wrong price, and “eminently block-able.”
- Day1 it traded a lot just above terms, then it went higher, then lower. Today it’s up strongly after a Nikkei article saying Baillie Gifford is unhappy with the price.
- That’s about 14% of the register who is apparently explicitly unhappy with the price. It’s still block-able. There will likely have to be a bump here.
6. StubWorld: WuXi Biologics (2269 HK)’s Double Discounts; Melco (200 HK) Further Out Of Whack
- WuXi XDC Cayman (2268 HK)‘s Offer for BioDlink International (1875 HK) will add an additional discount layer to WuXi Biologics (2269 HK).
- Preceding my comments on WuXi stable – and Melco International Development (200 HK) – are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
7. Skyworth (751 HK): Delisting/Spin-Off Terms Are Fair. Get Involved Here
- Skyworth Group Limited (751 HK) has announced an inter-conditional Scheme and concurrent listing of 70%-held Skyworth Photovoltaic on the HKEx by way of introduction.
- Independent shareholders are offered HK$4.03/share under the Scheme, or new scrip. All shareholders will be in-specied Skyworth Photovoltaic shares with a theoretical value of HK$6.13/share. Or HK$10.16/share all-in.
- Delisting the loss-making old school ops (TVs, set top boxes), and listing the now dominant photovoltaic ops, makes sense. Now it’s just a question of timing.
8. PhonePe IPO: Limited Float & Index Inclusion Timeline
- Phonepe is looking to list on the Indian exchanges with pre-IPO investors looking to sell 50.66m shares at a valuation of US$13.1bn and raising around US$1.3bn in the IPO.
- The stock will not get Fast Entry to either of the global indices. The earliest inclusion in a global index should take place in September.
- The stock should be added to the Large Cap segment in the AMFI Classification in July and to the NSE Nifty Next 50 Index in September.
9. HK Connect SOUTHBOUND Flows (2Wks To 16 Jan 2026) – China Mobile Sold Heavily, Tech Bought Heavily
- HK$128bn+/Day of gross SOUTHBOUND activity the first two weeks of the year, and net buying of HK$43bn.
- Relatively high div low vol SOEs were net sold. Again. China Mobile shellacked with net selling every day for 10 days (actually net sold every day since 11 Dec).
- The data tables below update daily in the Tools section of Smartkarma. The Southbound Flow Monitor and AH Pairs Monitor are both there – free – for all SK readers.
10. CKH (1 HK): Trading Full Ahead Of Supreme Court Ruling
- Panama’s Supreme Court is expected to make a decision shortly on whether CK Hutchison Holdings (1 HK) (“CKH”) will retain the concessions to operate two key Panama Canal ports.
- CKH and Panama’s Comptroller hold diametrically opposite views on the legitimacy of the 2021 licence renewal and operational compliance/status of these ports. To categorise the situation political is an understatement.
- The (largely) expected Panamanian pushback appears factored in, with the market looking further afield to the sale of the remaining 41 global ports. CKH is trading full here.