
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Partial Tender] BASE (4477 JP) – Maki-San Bought, Will Buy More – Prepare For Launch
- BASE Inc (4477 JP) released a statement during the lunch break on 5 October 2026.
- It says, in short, that Maki-san, who was wary of SBI/management, had not bought during the Tender Offer Period, but once extended, started to buy.
- He bought Friday and will try to get to 30%. He bought a chunk of that Friday. He’s in today. There’s more to buy.
2. [Japan Partial Tender] BASE (4477 JP) – We Needed Bumpity We Got Bumpitrage So What Now?
- SBI Holdings (8473 JP) extended their tender on BASE Inc (4477 JP) at ¥340 despite the tender having no minimum threshold. They obviously didn’t get what they wanted. Not close.
- That opened them up to expectations of a bump. For me, those expectations were the original base case but the stock didn’t act that way. Partial tender situations are funny.
- The next day, shares traded higher but still below ¥340. On Friday, things got more exciting. A successful tender needs to be higher (but SBI could attempt a backdoor trade).
3. Clarifying the Confusion Around Chey’s SK Holdings Stake Sale Disclosure
- These are all indicative numbers. Both the per share price and the total deal value can be adjusted on the actual execution date
- The November 2 to December 1 window reflects disclosure rules, not a 30 day sell down. Given the block plus PRS structure, base case is November 2.
- November 2 is the settlement date, implying October 29 execution via pre market block trade, with October 28 close as the pricing reference.
4. Taiyo Holdings (4626 JP): Bump Pressure Builds, but KKR Holds the Cards
- Since KKR’s JPY4,750 preconditional offer was announced, Taiyo Holdings (4626 JP) shares have traded above terms on 75% of days, with the offer due to open in late October.
- Pressure for a bump: Results beat guidance, peers have rerated, the offer lacks a control premium compared to peer multiples, IFA valuations look stale and competing-offer clauses.
- However, KKR can likely close without a bump: minimum acceptance is within reach and could be lowered, no activist has emerged, an interloper looks unlikely, and the price is defensible.
5. Jardine Matheson Southeast Asia (JCNC SP) Pops On Toyota In-Specie & Special Div
- Jardine Matheson Southeast Asia (JCNC SP) (formerly known as Jardine Cycle & Carriage (JCNC SP), popped ~10% today ahead of the Toyota Motor (7203 JP) in-specie-distribution and special dividend.
- The record date for both is the 9th October, with payment on (or before) 2nd December.
- JMSEA’s implied stub value is around its highest-ever level. As is the simple ratio of JMSEA/Astra International (ASII IJ). Neither are sustainable. Borrow is (reportedly) non-existent.
6. Merger Arb Mondays (05 Oct) – Kadoya, Kakaku, Leopalace21, Taiyo, Ingenia, Peet, OFX, Cleanaway
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), OFX Group (OFX AU), Z Fin (1168 HK), Peet Ltd (PPC AU), Atlantic Lithium (A11 AU), Tourism Holdings (THL NZ).
- Lowest spreads: Kadoya Sesame Mills (2612 JP), Kakaku.com Inc (2371 JP), Accent Group (AX1 AU), Leopalace21 Corp (8848 JP), Taiyo Holdings (4626 JP), FleetPartners Group (FPR AU).
7. Mynt (GCASH PM): No Quick Index Inclusion to Absorb Float
- GCash (Mynt) (GCASH PM) is looking to raise up to US$972m by selling shares at ₱6.6/share, valuing the company at ₱442bn (US$7bn).
- The offer period runs from 6-12 October and the stock is expected to start trading on 20 October. Demand is said to be multiples of the offer size.
- The earliest global index inclusion will come in June 2027, followed by a possible Philippines Stock Exchange PSEi Index (PCOMP INDEX) inclusion in July.
8. PHC Holdings (6523 JP): Corporate Selling Tilts the Risk/Reward to the Downside
- Toho Holdings (8129 JP)‘s rumoured JPY200bn proposal for PHC Holdings (6523 JP) implies about JPY1,571. Mitsubishi Chemical and Mitsui sold 3.4m shares on-market near that level, signalling little faith.
- Their selling weakens the deal’s risk/reward: it signals lower deal certainty, and there would be a large overhang of about 20% of the shares if Toho walks away.
- My fair value range remains JPY1,800–2,030, but at the last close, JPY1,595, the risk/reward is skewed to the downside.
9. BASE (4477 JP): Maki’s Return Leaves SBI to Bump Big or Bargain
- BASE Inc (4477 JP) disclosed a “difference of views” with Maki-san, who says management ignored the cost of his trading restrictions; he would resume buying from 2 October, targeting over 30%.
- With Maki buying at JPY370+, shares trading above terms and the 25% listing floor limiting supply, SBI faces a shortfall at JPY340, and a bump looks inevitable.
- SBI likely needs about JPY420 to beat a potential Maki tender, but negotiating with Maki or accepting a small fill (SBI has no minimum) may make more sense.
10. Ingenia (INA AU) Engages With Warburg. That’s The Right Outcome
- Third time’s a charm as Ingenia Communities (INA AU) extends due diligence to Warburg Pincus on a non-exclusive basis.
- The DD access arrives after Warburg initially pitched a A$4.75/share NBIO on the 7th September (rejected); then A$5.05/share on the 21st September (also rejected), then A$5.25/share on the 28th September.
- As with the two previous bids, Warburg’s last proposal is conditional on Ingenia terminating the Peet Ltd (PPC AU) Scheme: Peet Ltd (PPC AU): Ingenia Communities (INA AU)’s Clean Scheme.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Firmus Technologies (FIRMUS AU) IPO: Lock-Up Schedule to Drive Index Inclusion, Timing & Flow
- Firmus Technologies (FIRMUS AU) has reportedly priced its IPO at A$11/share with an aim to raise A$7.1bn. There is also an overallotment option of another A$0.7bn.
- At the IPO price, Firmus Technologies (FIRMUS AU) will have a full market cap of A$43.5bn (US$30.2bn) and an enterprise value of around US$60bn.
- There could be one global index Fast Entry, with other index inclusions coming in February and March. Size and timing of the passive flows depends on the lock-up schedule.
2. Hynix Could Follow Samsung With Key Disclosure Ahead of Oct 7 MTD Reply
- For memory swing traders, October 7’s MTD reply is the key catalyst, with Hynix potentially front running it by disclosing HBM customer commitments and 2027 capacity allocation.
- Samsung’s HBM capacity messaging strengthens the supply trade off case, while Hynix could go further with customer commitments and allocation data to support an AI driven capacity reallocation narrative.
- For Hynix, hard 2027 HBM capacity numbers or incremental customer commitments would matter far more than another generic capacity update, potentially driving estimates and near term share price volatility higher.
3. Goodbaby (1086 HK): Founder’s Fair Offer
- Goodbaby International (1086 HK), a maker of juvenile products (strollers/pushchairs, child car seats), has announced an Offer, by way of a Scheme, from founder/chairman Song Zhenghuan.
- Song is Offering HK$1.50/share, a 38.9% premium to last close. And a 53.06% premium to the 10-day VWAP (possible news leakage?).
- The Offer price is final. Dividends will be netted. This transaction should be wrapped up in around four months, ahead of the 24th March 2027 long-stop.
4. NIKKON Holdings (9072 JP): Sell-Off Signals a Stalled Auction, but Downside Looks Limited
- Nikkon Holdings (9072 JP)‘s take-private auction has gone quiet. Today’s 13% share-price drop suggests a bidder has walked away or that activists are blocking the deal.
- With no publicly available news to explain the fall, the key issue may be that bidders cannot finance an offer meeting the activists’ asking price.
- Downside if the deal breaks: The base case is flat to −7% (JPY4,150–4,570) from JPY4,459. The bear case, −18% to −26%, would need an activist exit or weak results.
5. Northern Star (NST AU) Rejects Gold Fields (GFI SJ)’s Terms
- Northern Star Resources (NST AU) announced two major downgrades this year, hampered by old hardware, leading to a ~19% single-day share price fall on the second cut.
- NST made some concessions, mollifying activist Elliott (and the market). For now. I discussed this situation in Stay The Course As Northern Star (NST AU) Extends Olive Branch To Elliott.
- NST announced this morning that three days prior my note it received, and (has now) summarily rejected a cash/scrip Offer from Gold Fields (GFI SJ), or a A$27/share implied price.
6. [Japan Partial Tender] BASE (4477 JP) – SBI Extends on Zero Minimum. Bumpity Bumpity Bumpity
- When SBI Holdings (8473 JP) announced at end-August they were tendering to buy 20% of BASE Inc (4477 JP), they set a short tender (20d) and zero minimum threshold.
- That was a VERY easy target, but I thought they would need to raise the price to get the shares they wanted. The market didn’t seem to agree.
- But SBI just extended the tender. And not because it didn’t meet the minimum. Bumpity bumpity bumpity.
7. [Japan M&A] EQT Raises by ¥1 (+0.272%) To Still Below Maket, But EQT Language Could Speed Things Up
- Yesterday, Kakaku agreed to dissolve its Capital Alliance with KDDI. That was expected. KDDI agreed to sell everything. I expect it is accounting-driven.
- Today, EQT’s ¥3,680 TOB was set to expire so they raised it to ¥3,681 and extended 10 days. Interestingly, their Bidder Announcement document changed content significantly.
- The reference to negotiating with Oasis is gone. Instead, a diatribe against Bain for not being serious about things, bringing a non-feasible bid. There is vaguely threatening language.
8. More Contractor Craziness. The HKEx Needs To Open An Investigation
- In the past two months, Lotus Horizon (6063 HK), WK (2535 HK), and Superland (368 HK) have been subject to conditional/unconditional (massive) takeunders. Expect the same for KFM (3816 HK).
- Now fellow contractor/manufacturer, Trio Industrial Electronics Group (1710 HK), is suspended pursuant to the Hong Kong Code on Takeovers and Mergers. Its share price is up ~567% since June-end.
- Not a great look for the exchange. I’ve reached out to the HKEx to get their read.
9. Ingenia Communities (INA AU) Mulls Warburg’s Third Proposal
- Ingenia Communities (INA AU)‘s share price declined ~13% as shareholders didn’t take kindly to its 26th August cash/scrip Offer for real estate developer Peet Ltd (PPC AU).
- Warburg Pincus saw an opportunity, and pitched a A$4.75/share NBIO, by way of a Scheme, on the 7th September (rejected); then A$5.05/share on the 21st September (also rejected).
- A third NBIO, at A$5.25/share, was announced this morning. Ingenia is assessing terms. As with the two previous bids, Warburg’s Offer is conditional on terminating the Peet Scheme.
10. Asia-Pac M&A [Sept 2026 Wrap]: Northern Star, Kadoya Sesame, Ingenia, Leopalace21, IDP, Sharingtech
- For September 2026, 11 new transactions (firm and non-binding) were discussed on Smartkarma (by the Quiddity team) with an overall announced deal size of ~US$26bn.
- The average premium for the new transactions announced (or first discussed) in September was ~46%; and a year-to-date average of ~45%.
- The average premiums for transactions in 2025, 2024, 2023, 2022, 2021, 2020, and 2019 were 49%, 43%, 39%, 41%, 33%, 31%, and 31%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Sept 22 MTD Opposition Raises Oct 21 Survival Odds, Boosting Hynix ADR Expansion Incentive
- Sept. 22 Opposition largely recycles the CAC, but its January 2026 customer vetting logic strengthens MTD survival odds, keeping Hynix as the key litigation focus.
- The January 2026 customer vetting point makes Hynix’s need to double down on its HBM transition narrative even more critical, potentially strengthening the case for ADR expansion.
- Regulatory approval remains key, but political and strategic incentives increasingly support ADR expansion, potentially making Hynix ADR arb a key trade setup from mid October.
2. [Japan M&A/Activism] Kobayashi Pharma (4967) Gets Buyout Proposal
- Last night, news came out that Kobayashi Pharmaceutical Co (4967 JP) had received a ~¥500bn buyout proposal from a PE Fund consortium of CVC, NSSK, and the founding family.
- Kobayashi was at the center of a beni koji (red rice yeast) supplements contamination scandal revealed in 2024. The Chairman and CEO from the family resigned.
- Activist Oasis Management built a stake 2+yrs ago and have steadily increased it to 14%. They want the founding family influence out. This isn’t as easy as one likes.
3. Kobayashi Pharma (4967 JP): CVC/NSSK Buyout Rumour Faces an Oasis Hurdle
- CVC and NSSK are reportedly proposing a buyout of Kobayashi Pharmaceutical Co (4967 JP) worth over JPY500bn, possibly with the founding family. That implies JPY6,406 a share, a 9% premium.
- While the offer appears attractive relative to precedent and peer multiples, Oasis, the largest shareholder, is unlikely to back it.
- At the rumoured offer, Oasis will get a 17% return on its average cost, which is modest. The Taisho privatisation precedent suggests Oasis will push for a higher offer.
4. IDP Education (IEL AU): Blackstone’s Offer Rejection Justified, Third Approach Likely
- In response to an AFR article, IDP Education (IEL AU) disclosed that it rejected a non-binding proposal from Blackstone (BX US) at A$2.50 (received on 9 September).
- The offer is light on several metrics. Based on its weighted-average purchase price, Southeastern (which has quickly grown to be the largest shareholder) would need a A$3.00+ offer.
- Several factors suggest that Blackstone is likely to return with at least a third offer. An offer of at least A$3.00 is required to pressure the Board to engage.
5. StubWorld: Prosus Is Still A Buy
- Prosus NV (PRX NA) is still coming up “cheap” on my monitor versus Tencent (700 HK).
- Preceding my comments on Prosus/Tencent/Naspers (NPN SJ) are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
6. IDP Education (IEL AU): Blackstone’s Cheeky Offers As Pricing Touch A Decade-Plus Low
- Since its share price peaked in 4Q21, IDP Education (IEL AU), a multinational education services outfit, has fallen ~95%.
- IDP has faced pressure from immigration/student visa caps and competing English language tests for students and immigrants. Plus, IDP has never recovered from Covid.
- That share price decline was not lost on Blackstone, which has tabled two NBIOs (the last at A$2.50/share), both of which have been rightfully rejected. Definitely scope for a re-bid.
7. Global Lithium (GL1 AU): Titan’s Binding Scheme, an Uncertain MinRes Vote
- Global Lithium Resources Ltd (GL1 AU) entered into a scheme implementation deed with Titan at A$1.15 per share, a 72.9% premium to the undisturbed price.
- Regulatory approvals (FIRB, ACCC) are low-risk. Barring Mineral Resources (MIN AU), there is little doubt that the remaining substantial shareholders will be supportive.
- While MinRes will crystallise a material loss at the offer price, it is unlikely to interfere, as it recently stated that it does not want further exposure to lithium.
8. Global Lithium (GL1 AU): Trading Wide To Titan’s A$1.15/Share Scheme
- Mineral Resources (MIN AU)-backed Aussie lithium play Global Lithium Resources Ltd (GL1 AU), has entered into a Scheme with UAE-backed Titan Mining.
- Titan is offering $1.15/share, in cash, for each GL1 share, or a 73% premium to undisturbed. Titan is also providing GL1 with a loan to develop the Manna Lithium Project.
- GL1 directors, holding 12.5%, are supportive. The Scheme meeting is expected to be held in December. The Scheme requires FIRB & ACCC signing off. Expect scrutiny.
9. Merger Arb Mondays (21 Sep) – Kadoya, Leopalace21, Kakaku, Skyworth, Z Fin, OFX, Peet, Cleanaway
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), OFX Group (OFX AU), Z Fin (1168 HK), Peet Ltd (PPC AU), Atlantic Lithium (A11 AU), Tourism Holdings (THL NZ), Cleanaway Waste Management (CWY AU).
- Lowest spreads: Kadoya Sesame Mills (2612 JP), Leopalace21 Corp (8848 JP), Carnaby Resources (CNB AU), Kakaku.com Inc (2371 JP), Accent Group (AX1 AU), FleetPartners Group (FPR AU).
10. Christian Dior: Tailoring the LVMH Hedge
- Arnault family proposes a cash OPR at 95% of CDI’s look-through NAV, based on LVMH’s one-month VWAP ahead of the December EGM.
- At €425.40, CDI trades at 91.7% of current NAV, versus the proposed 95% exit level, implying 3.6% gross upside at current LVMH prices.
- Long CDI / short ~1.11 LVMH hedges most of the initial market exposure, with the short reduced progressively as the December VWAP fixes.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
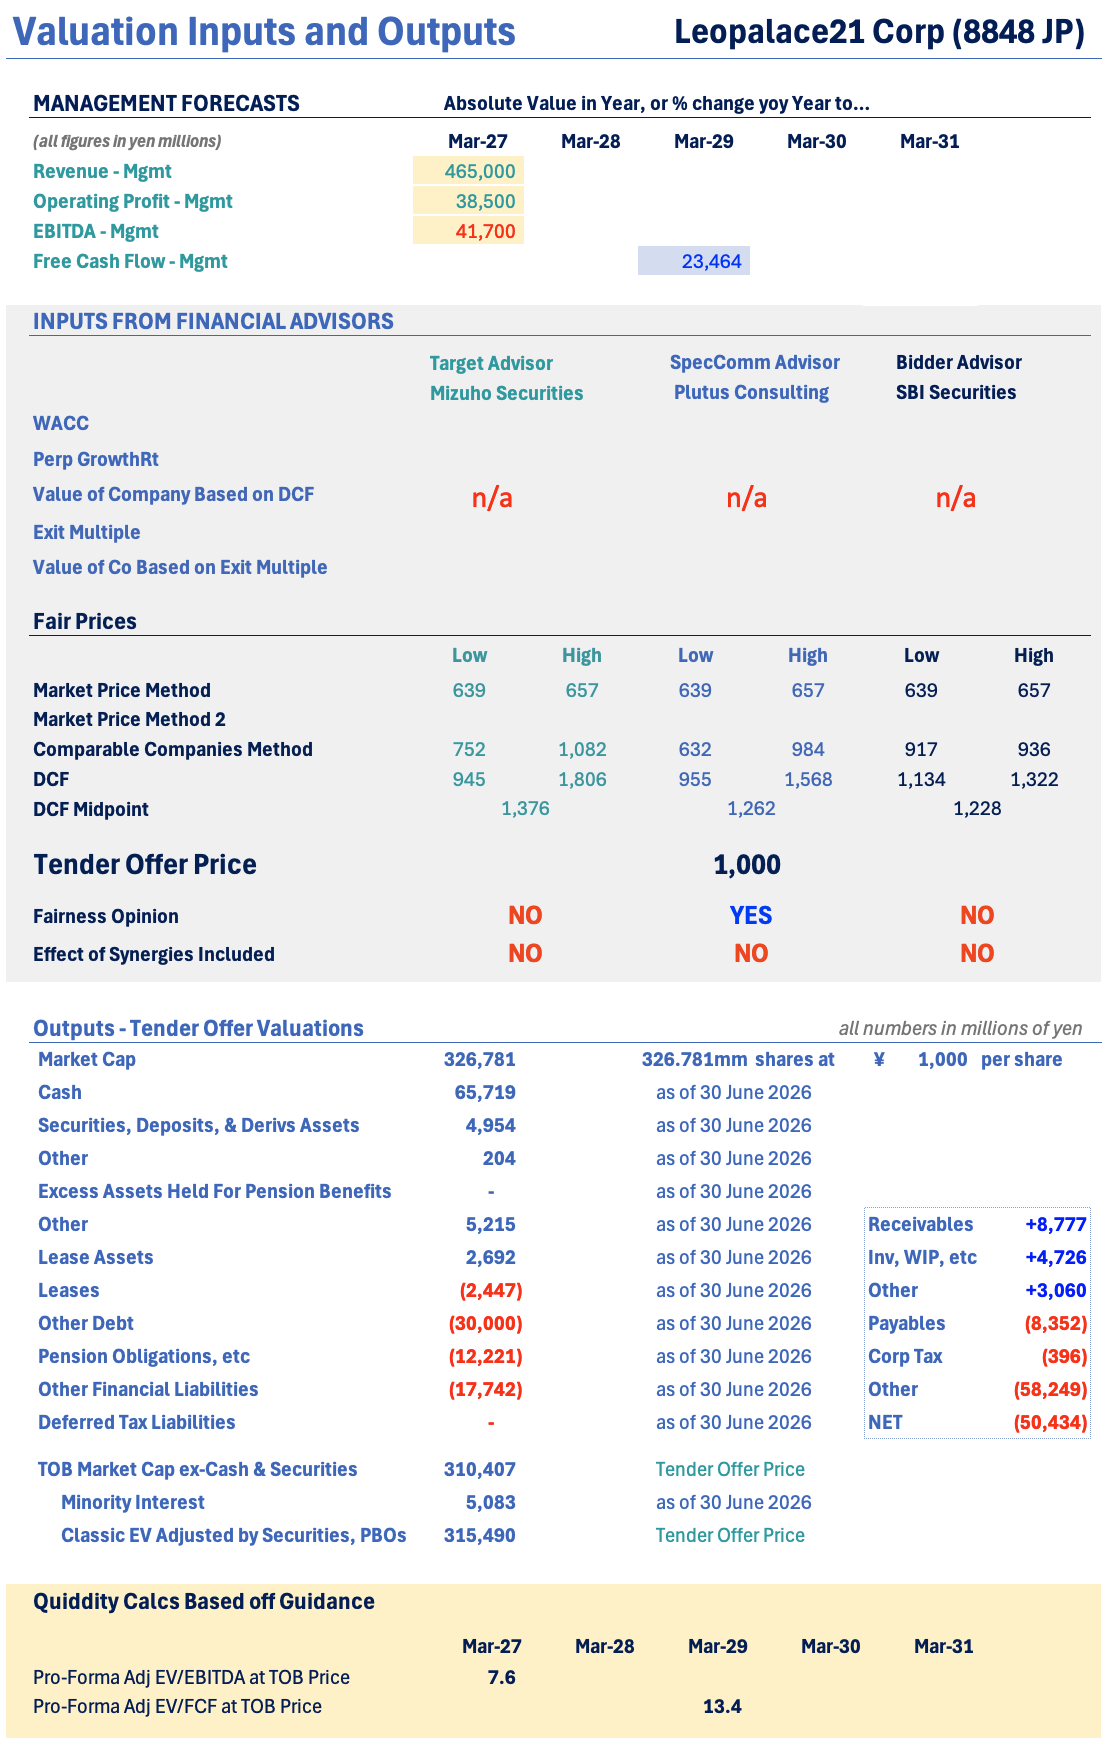
1. [Japan M&A] Hikari Tsushin + Friends to Buy Leopalace21 (8848) – Light Bid, Somewhat Open Register
- Today after the close, Hikari Tsushin (9435 JP) announced a deal to buy out Leopalace21 Corp (8848 JP) partnering with MBK and NEC Capital, taking out Fortress’ last 15%.
- Hikari Tsushin bought its large stake very low in 2022, post-scandal. Fortress did too. Murakami tried earlier, failed. Others made money on it.
- This deal offers near zero basic transparency, and comes at a sharp discount to the midpoint of the fair value DCF ranges. Very not a good look. But it’s vulnerable.
2. [Japan Partial Tender] BASE (4477 JP) Deal Update – Trading VERY Cheap
- When SBI launched its partial tender for 20% of BASE Inc (4477 JP) at the end of last month, they wanted to buy ~42.5% of the Max Real World Float.
- That was at ¥340, a small premium to where the stock was trading, and a 17% discount to where another partial tender last year got only 7-8% of MRWF.
- I think the dynamic here favours being long. Pro-ration expectations are misplaced I think.
3. Kadoya (2612 JP): Integral’s Unconventional Offer With Competing Bidders Lurking
- Kadoya Sesame Mills (2612 JP) announced a tender offer from Integral (5842 JP) at JPY2,514, a 3.9% premium to the last close and a 40.2% premium to the undisturbed price.
- The offer could increase to JPY2,760 if both Mitsubishi Corp (8058 JP) and Mitsui & Co Ltd (8031 JP) agree to share buybacks. Two competing bidders remain in the background.
- Mitsubishi and Mitsui’s deliberately deferred, non-committal stance facilitates a potentially higher competing bid, particularly as the offer is below the midpoint of the IFA DCF valuation range.
4. Setup Pointing to Hynix (And Samsung) Slowing Their Dollar Selling Pretty Soon
- Local concerns are resurfacing over Hynix and Samsung’s low utilization, with further GMR cuts potentially exposing deliberate production curbs, though KRW strength remains supportive for buybacks.
- Hynix and Samsung’s dollar selling may be slowing as FX driven GMR deterioration risks exposing low utilization, while regulators increasingly flag KRW volatility.
- Hynix ADR funding faces rising regulatory hurdles amid FX volatility, potentially delaying buyback funding and forcing slower dollar selling, creating a near term stock price pivot.
5. Cleanaway Waste (CWY AU): EQT (All But) Firms Terms. Get Involved
- On the 13th August, EQT proposed taking Australia’s largest garbage and waste disposal play Cleanaway Waste (CWY AU) private, via a Scheme, at A$3.13/share, a 32.1% premium to undisturbed.
- EQT was afforded nine weeks of exclusive DD; and announced yesterday nothing had arisen in its review that was likely to cause it not to proceed on the same terms.
- All good? Mostly. There’s some pushback in the market CWY’s management’s backing an (exclusive) Offer as the Iran war suppressed CWY’s share price. I’m not a buyer into that narrative.
6. Kakaku.com (2371 JP): Bain/LY’s Latest Offer Is Playing a Dangerous Game
- Bain/LY revised their Kakaku.com Inc (2371 JP) offer to JPY3,597 (JPY3,720 for KDDI share buyback), 2.2% premium to the previous JPY3,520 offer but a 2.3% discount to EQT/DG’s JPY3,680 offer.
- Bain/LY (4689 JP)’s latest offer underwhelms and could backfire if KDDI Corp (9433 JP) and possibly Oasis decide to end this long-running saga by accepting the marginally lower EQT/DG offer.
- While there remain arguments for continued escalation, the “winning” offer is unlikely to exceed the last close (JPY3,820). It’s time to head for the exit.
7. Korea Investment Partners – A Home Run Investment in Anthropic
- Korea Investment Partners (KIP) has made a home run investment in Anthropic. Korea Investment Holdings Co, Ltd. (071050 KS) owns a 100% stake in Korea Investment Partners
- Assuming a 50% share dilution from its original investment in August 2024 ($10 million), KIP’s stake in Anthropic would reach $555 million (if Anthropic is valued at $2 trillion).
- Korea Investment Holdings Co, Ltd. (071050 KS) has a market cap of 10.4 trillion won, so this would be 7.4% of its market cap.
8. Trading Setup from Samsung and Hynix Timing Buyback Completion Around Litigation Key Dates
- Fresh local chatter links Samsung and Hynix accelerating buyback completion to the DRAM price fixing litigation, with September 29 CMC and October 21 MTD as key binary events.
- MTD denial could shift the narrative from supply discipline to coordinated supply discipline, with Micron’s divergent stance and tight Samsung and Hynix inventories adding to legal overhang.
- The key trading window may be Sep 29 to Oct 21, as the CMC could signal discovery scope and trigger front running of the MTD outcome.
9. [Japan M&A] An Ongoing Competitive MBO-Ish Deal for Kadoya Sesame Mills (2612 JP) – Watch for More
- VERY late last night Tokyo time, Kadoya Sesame Mills (2612 JP) announced a Supported/Recommended Deal whereby local PE form Integral would buy out the company at ¥2,514-2,760 pending shareholder agreements.
- The base case is ¥2,514. ¥2,760 comes when major shareholders agree to sell at a discount, passive their tax benefits to the whole shareholder base.
- But there’s competition. A started things off last year. Integral/family joined in. Major shareholders MitCorp and Mitsui got B and C to join. A and C are still in it.
10. National Stock Exchange of India (NSE) IPO: Index Entry Timeline & Flow
- National Stock Exchange (NSEIN IN) is looking to list on the BSE by selling 126.4m shares via an OFS to raise INR 226bn (US$2.35bn) at a valuation of US$46bn.
- Anchor investors have been allotted 37.8m shares at INR 1785/share and shares will start trading from 24 September.
- The stock will not get Fast Entry to local and global indices and inclusion will start in March 2027 with the biggest buying coming in May and June.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Event] The Crasus Chemical (646A JP) Spinoff from Resonac (4004 JP)
- Back in February 2024, Resonac Holdings (4004 JP) announced it would start an assessment of a partial spinoff of its petrochemicals division, Crasus Chemical (646A JP).
- Resonac updated in July 2026. In August the Board resolved to deliver 80+% of shares to Resonac investors. Today the TSE approved. Crasus starts trading on Resonac ex-rights day 29-September.
- The “center” value should be determined in about a week to ten days. The estimate of asset distribution right now is 0.09 per Resonac share. There will be index effects.
2. [Japan M&A] Nippon Sheet Glass (5202) Done, Dusted, Arb for Money
- Nippon Sheet Glass (5202 JP) announced 21-Aug that the capital injection expected a fair bit later would be done and paid for on 31-Aug. New term loans were agreed 26-Aug.
- That made 25 Sep the last trading day. On the 31st, they confirmed the capital injection had been paid for. Cash out for remaining shareholders would be late December 2026.
- Actual dates and confirmation waits until early November but buy today and that is 4.0% annualised (though the BOJ could act twice in the interim). Worth a look for arbs.
3. Golfzon Holdings (121440 KS): This Is A Buy And Hold
- At the close of its reloaded ₩6,700/Share Tender Offer for Golfzon Holdings (121440 KS), SJ Investment received zero shares. With no margin seller at ₩6,700, it seemed illogical to reload.
- And for now, they won’t, opting not to proceed with a follow-on delisting transaction.
- ₩6,700/Share was low-balled. It’s probably worth (at least) double this. If you have the bandwidth to wait this out, stay in. Or buy and hold. Load up on weakness.
4. BASE (4477 JP): SBI’s Partial Tender Offer Needs a Price Bump
- On 28 August, BASE Inc (4477 JP) announced an offer by SBI Holdings (8473 JP) to acquire up to 23.8m shares (20.00% stake) at JPY340, a 7.6% premium to the undisturbed price.
- There is no minimum acceptance condition. The shares are trading above the offer price, either due to expectations of a bump or to the SBI alliance benefiting the back-end valuation.
- A price bump is likely as the offer is light on several metrics, the two substantial shareholders are unlikely to tender, and the Board has taken a neutral stance.
5. Public Financial Holdings (626 HK): Public Bank’s Scheme Offer at HK$2.50
- Public Financial (626 HK) announced a scheme privatisation offer from Public Bank (PBK MK) at HK$2.50 per share, a 61.3% premium to the undisturbed price. The offer is final.
- The offer is well below book value (P/B of 0.35x) and light compared to peer multiples. However, it is an attractive exit as it represents a 10-year high.
- The vote is low-risk, as the high takeover premium will appeal to minorities given the near-term cash certainty compared to remaining a minority holder in an illiquid, 73%-controlled stock.
6. Hunter Turns Hunted As Ingenia Communities (INA AU) Rejects Warburg’s NBIO
- On the 26th August, real estate developer Peet Ltd (PPC AU) entered into cash/scrip Offer by way of a Scheme with Ingenia Communities (INA AU).
- The Scheme appeared clean. Decent premium to NTA. Major shareholder (of Peet) support. However, Ingenia’s share price has fallen 13% since the transaction was announced.
- This morning, Ingenia announced it has received, and rejected, a NBIO of A$4.75/share (in cash) from Warburg Pincus. The proposal is contingent on Ingenia not proceeding with the Peet Offer.
7. Skyworth (751 HK) Gives Up Spin-Off Gains. And Then Some
- On the 20th January 2026, Skyworth (751 HK) announced an inter-conditional Scheme and concurrent listing of 70%-held Skyworth Photovoltaic (Skyworth PV) on the HKEx, by way of introduction.
- The Dongfeng (489 HK)/Voyah (7489 HK)-like structure appeared fair. The challenge was that Skyworth PV’s key comps were/are A-share listed, and Skyworth PV should trade at an H-share discount.
- Currently trading right at the Scheme cash consideration, assigning zero value for Skyworth PV. Skyworth’s share price is 22% below the pre-spin-off announcement price. I can see this trending lower.
8. Merger Arb Mondays (07 Sep) – Skyworth, Z Fin, OFX, Cleanaway, EQT, European Lit, BetMakers, Kakaku
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), European Lithium (EUR AU), Z Fin (1168 HK), OFX Group (OFX AU), Cleanaway Waste Management (CWY AU), Atlantic Lithium (A11 AU).
- Lowest spreads: Accent Group (AX1 AU), FleetPartners Group (FPR AU), Kakaku.com Inc (2371 JP), Vault Minerals Ltd (VAU AU), Ausgold Ltd (AUC AU), Japan Property Management Center (3276 JP).
9. Hong Ra-Hee Is Selling 1.9 Trillion Won of Samsung Electronics to Her Son Lee Jae-Yong
- After the market close on 9 September, it was reported that Hong Ra-hee is selling a 0.11% stake in Samsung Electronics (worth 1.94 trillion won) to her son Lee Jae-yong.
- Her decision to transfer the shares directly to Chairman Lee rather than selling them on the open market is seen as a move to minimize the impact on the market.
- After this transaction is completed, Lee Jae-yong’s stake in Samsung Electronics will rise from 1.47% to 1.58%.
10. [Japan M&A] EQT Bumps Kakaku Bid to ¥3,680 – Through Bain’s Bid – Means Bain Bid Likely Soon
- Today, on the last day of the earlier bump to ¥3,571 by EQT/DG, which was bumped from ¥3,570 (when shares were trading ¥3,700) and extended, EQT bumped/extended to ¥3,680/share.
- This is, of course, a bit more than 1% higher than the existing Bain best bid and the level Oasis had set as a minimum – ¥3,640.
- EQT tried to get Oasis to sign on but they did not agree. They are waiting for Bain’s overbid I expect. This now puts the floor at ¥3,680.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
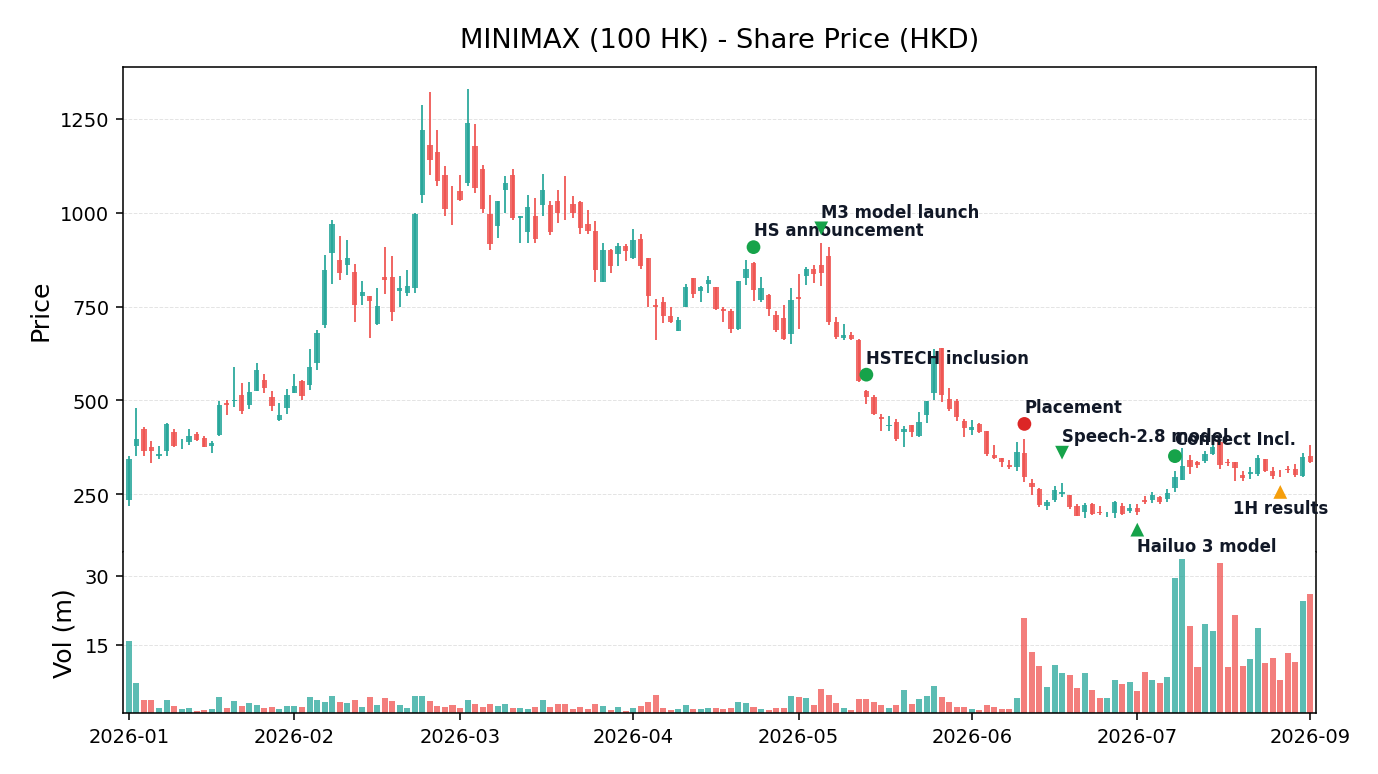
1. MINIMAX-W: Second Lock-Up Expiry and Convertible Bond Conversion Analysis
- We lay out MiniMax’s September liquidity events, from today’s Undertaking (b) unlock through the 21 Sep bond conversion window.
- We review the stock’s post-Connect inclusion trading, including southbound buying, short interest, consensus revisions.
- We assess the overhang associated with the lock up events.
2. [Japan M&A] Itochu Deal Details for Dentsu Soken (4812); ¥2,880 Is Better than Rival Bid, But…
- Deal details are much as the Nikkei and Dentsu Soken reported. ¥2,880 for the 38.2% not owned by Dentsu. Dentsu and Itochu will be partners with Dentsu consolidating.
- The price is not very high considering the growth, especially when synergies are not included. The price is below the TargetCo FA’s DCF range midpoint w/o synergies.
- But there was a rival bidder in the selection process and they had a lower bid. So it isn’t clear who or what overbidder might come out. This gets done.
3. [Japan Partial Tender] Update on SBI’s Tender for BASE (4477 JP)
- On 28 August, SBI Holdings (8473 JP) announced a Tender Offer to buy 20% of BASE Inc (4477 JP) by Tender Offer at ¥340/share. That was a very small premium.
- My comments were in [Japan Partial Tender] SBI Launches Partial Offer for 20% of BASE (4477 JP) At ¥340 – Needs More. SBI has quite often underpaid on partials.
- Top shareholder Maki-san was released from his confidentiality agreement the same day. Last night he released an updated Large Shareholder Filing Amendment. It tells you something.
4. Progress of 55 Trillion Won Share Buybacks Announced by SK Hynix and Samsung Electronics
- As of 1 September, SK Hynix and Samsung Electronics have repurchased 13.5 trillion won, representing 24.5% of total planned buyback amount.
- At the current pace, SK Hynix is expected to complete its buyback by October 2026. Samsung Electronics is also expected to complete its buyback earlier (in late September or October).
- I continue to maintain the view that Samsung Electronics will announce a much bigger buyback/cancellation program in January 2027.
5. Ichibanya (7630 JP): House Foods (2810 JP) Potentially Exiting Through a Privatisation
- The Nikkei reported that House Foods Group (2810 JP) is considering selling its 51% stake in Ichibanya (7630 JP) by selecting a suitable bidder to privatise the Company.
- The rumoured strong interest from several investment funds despite Ichibanya’s high multiples and downgraded forecasts signals deep underlying value.
- My analysis suggests that an offer price range of JPY1,170 to JPY1,317 per share, a 7.2% to 20.8% premium to the last close.
6. SBI (8473 JP) To Raise Stake in Brangista (6176 JP) In the Market Over 7 Months
- SBI Holdings (8473 JP) announced plans today to increase its stake in Brangista (6176 JP) over the next nearly 7mos.
- A year ago, SBI and Brangista signed a Capital and Business Alliance and SBI unit SBINM GK bought a third party allotment for ~8%.
- Now they are going to increase their stake. It’s a smallcap but it’s worth a look because… supply/demand dynamics…
7. NIKKON Holdings (9072 JP): Two Bidders in the Second Round with Suggestions of a Takeunder
- Bloomberg reported that Bain and Lone Star have advanced to the second round of bidding for Nikkon Holdings (9072 JP), which will commence in early September.
- Bloomberg also noted that a takeunder is possible. At first glance, the argument for a takeunder looks compelling, particularly as Nikkon shares have materially outperformed peers YTD.
- However, a takeunder is unlikely for several reasons and is largely a ruse to dampen expectations. An offer around JPY6,000 remains justifiable.
8. [Japan Buyback] Canon’s ¥200bn Buyback Is Almost Done – A Short Study
- Canon Inc (7751 JP) has been one of the most prolific executors of corporate buybacks in the past 20yrs. Up there with Toyota.
- Historically, its buybacks were finished very early in the buyback period, and were a big percentage of volume while being executed. The current one is different. Slower. Lower impact.
- This piece is a study. Our data shows Canon has underperformed during the buyback as EPS expectations have suffered vs Peers. The study shows post-buyback-end underperformance isn’t a thing.
9. Con Aero Tech (232 HK): 21st Sept SGM. “Surplus Cash” Into Focus
- On the 5th June, Continental Aerospace Technologies (232 HK) (CAT) confirmed an SPA to sell its core business, potentially leading to a cash distribution (HK$0.419-HK$0.436/share), and subsequent winding up.
- The SPA requires reg approvals and a Scheme-like vote. 46.4% of the register is supportive. Additional dividends expected from the sale of property. And any leftover funds.
- The Circular is now out. The SGM is the 21st September. With payment of the special/property dividend (on or before) the 12th October. “Surplus cash” distribution is expected shortly thereafter.
10. StubWorld: Swire Accelerates Cathay Exchange. “As” At Multi-Decade Premium To “Bs”
- Via an accelerated exchange, Swire Pacific (19 HK) is soliciting tenders from its 2027 exchangeable bond holders and, in parallel, placing Cathay (293 HK) shares to fund the bond repurchase.
- Preceding my comments on Swire, are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
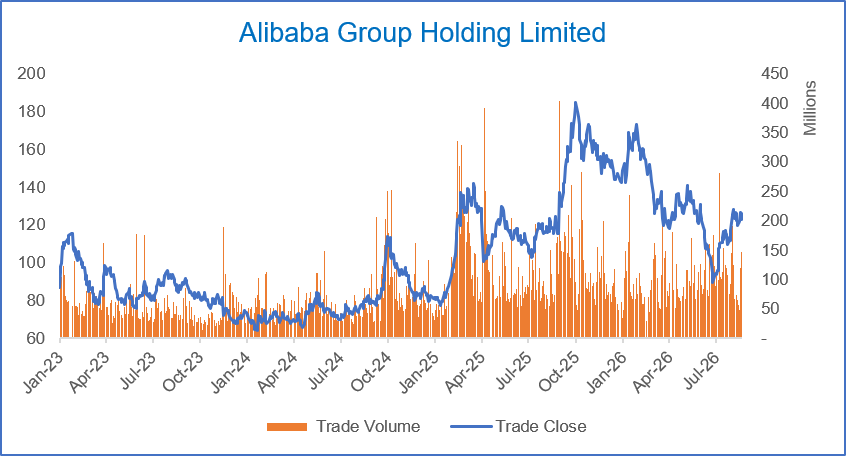
1. Alibaba (9988 HK): Index Implications for US$10bn Placement
- Alibaba (9988 HK) / Alibaba (BABA US) has announced a placement of HK$80bn (US$10.2bn) to invest in its full stack AI capabilities and to expand and enhance its AI infrastructure.
- The shares are being offered at HK$112.7/share, an 8.4% discount to the Alibaba (9988 HK) close and a 3.6% discount to the Alibaba (BABA US) close.
- There will be passive buying from trackers of one global index later this week, while trackers of the other global index will buy in November. No impact for local indices.
2. Dynamics Between Hynix’s Buyback Pace and Opening up ADR Fungibility
- Hynix has bought back 3.25mn shares, or 13.5%, in six days. At the current 650K daily pace, it should finish October 19, a month ahead of the November 19 deadline.
- The early buyback finish is not unusual, but its timing near the October 8 ADR lockup expiry revives chatter around a potential follow on ADR issuance.
- Square could sell the 68bp stake via a secondary ADR, potentially funding a special dividend for Chey’s ₩1T divorce settlement. Watch September filings for fungibility signals and ADR arb timing.
3. [Japan M&A] Bain Lets 5-Day Overbid Chance Lapse, Will Wait for EQT Tender To Finish
- On Friday after the close, Kakaku.com Inc (2371 JP) announced that Bain would not respond to EQT+DG/Kamgras1’s bid bump to ¥3,570 which meant Bain’s ¥3,640 was just 1.96% higher.
- This means Bain will simply let EQT’s current ¥3,570 bid close on 27 August. If the minimum threshold is met, EQT wins. If not, presumably Bain will launch.
- On 18 August, Oasis Management with 19.5% said it did not support a Tender Offer below ¥3,640/share. This, and the market price, may have emboldened Bain. What next?
4. SHEIN Global (625 HK): Delayed Index Inclusions; Stock Connect Next September
- SHEIN Global Holdings (625 HK) could raise up to US$2bn in its IPO if the overallotment option is exercised, valuing the company at HK$212bn (US$27bn).
- Cornerstone investors will take up between 21.7-22.6% of the base offering and those shares will be locked up for 6 months from listing date.
- Fast Entry inclusion in the HSCI is likely but Southbound Stock Connect could take over a year from listing date. Earliest global index inclusion in March.
5. India: Key CAS Test on Monday as Global Index Rebalances
- The Closing Auction Session (CAS) kicked off on 3 August for Indian stocks that are part of the Futures & Options (F&O) segment of the market.
- Daily total turnover in CAS since launch has averaged around US$128m. In comparison, global passives will need to trade around US$4bn of F&O stocks at the CAS on 31 August.
- There could be large moves in affected stocks in the lead up to the CAS on Monday, followed by more large moves at CAS, and a potential reversal on Tuesday.
6. Samsung’s Remaining Return Mix and Two Yearend Trades
- Samsung’s remaining KRW 70 to 80tn return package looks set at KRW 60tn dividends and KRW 10 to 20tn buybacks, with KRW 40tn a hard dividend floor and potential upside.
- Samsung’s KRW 10 to 20tn buyback could skew heavily toward prefs due to Samsung Life’s 10% constraint, implying potentially 6.7% prefs cancellation versus 0.7% common.
- Samsung offers two yearend trades: pref discount compression with 6.8% yield versus 5.1% common, and dividend arb with 3.3% yield, potentially higher amid continued memory sector vol.
7. Why Samsung Electronics Should Buyback and Cancel At Least 10% of Its Preferred Shares
- In this insight, I argue why Samsung Electronics should buyback and cancel at least 10% of its preferred shares.
- Clearly, many shareholders have been disappointed with lack of buybacks/cancellations with the recent 30 trillion won dividend program.
- In order to appease many disappointed investors in Samsung Electronics, the company should significantly increase the buybacks/cancellation portion of the remaining shareholder returns, especially for the preferred shares.
8. SK Innovation Announces a Merger With SK IET (Before New Regulation Kicks In)
- On 25 August, SK Innovation (096770 KS) announced a merger with SK IE Technology (361610 KS) (SK IET).
- I believe this will have a negative impact on SK Innovation and a neutral impact on SK IET.
- The biggest concern is the fact that SK IET has been generating continued net losses in the past several years and this could negatively impact SK Innovations’ financial structure.
9. Dentsu Soken (4812 JP): Oasis’s Presence Results in Itochu’s Rumoured Generous Offer
- Nikkei reported that Dentsu Inc (4324 JP) and Itochu Corp (8001 JP) will privatise Dentsu Soken (4812 JP) at a total cost of around JPY250 billion.
- The rumoured JPY250 billion valuation for the 38.12% stake not owned by Dentsu suggests an offer of JPY3,360 per share, a 22.7% premium to the last close.
- Oasis’s emergence as a substantial shareholder ensured a generous offer. The rumoured offer represents an all-time high and is attractive compared to precedent transactions and peer multiples.
10. Kakaku.com (2371 JP): Bain/LY Hold Firm as EQT/DG Face a Dilemma
- Bain/LY (4689 JP) have kept their Kakaku.com Inc (2371 JP) offer unchanged and have decided to wait for the EQT/Digital Garage (4819 JP) offer to close, convinced that it will fail.
- Minorities have a free option on the higher Bain/LY offer. In the worst case, the EQT/DG offer succeeds, and in the best-case, it fails, and minorities get the Bain/LY offer.
- The success of the EQT/DG offer relies heavily on KDDI’s support, which remains uncertain. It is very likely that EQT/DG will at least match Bain/LY’s JPY3,640 offer.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Hynix Dividend Heavy Return Likely Friday: Square Outperformance Setup in Focus
- Hynix could announce KRW 100tn shareholder returns this week, with a 60:40 dividend buyback mix. Yeouido is increasingly positioning for this outcome.
- KRW 40tn buyback matches the ADR proceeds, with Hynix repurchasing below the issuance price. The broader package also creates a timely window to upstream excess cash to SK.
- Square looks set to outperform Hynix near term as the return mix reinforces the cash upstreaming narrative. A long Square, short Hynix or market setup looks compelling into the announcement.
2. Local Intel on Timing and Structure of Samsung’s Return Package
- Local chatter now points to Samsung announcing shareholder returns as early as Friday, driven by government pressure and Hynix’s more aggressive buyback.
- Samsung is expected to split its 50% FCF return into two tranches: KRW 40-50T from late August, then roughly KRW 50T in early 2027, led by buybacks and special dividends.
- Samsung’s special dividend record date should remain September 30, with Q3 regular and special dividends likely approved together at the late October board meeting.
3. SK Hynix’s 40 Trillion Won Share Buyback and Cancellation – Trading Implications
- SK Hynix announced a major treasury shares repurchase and cancellation of about 40 trillion won ($29 billion), representing about 3.3% of outstanding shares.
- SK Hynix plans to return more than 50% of the cumulative free cash flow (FCF) generated during 2025-2027E to shareholders.
- In terms of trading implications in the next several weeks, this could positively boost SK Hynix’s share price back to about 2,200,000 won level (about 40-50% upside).
4. Curator’s Cut: Sentiment Shifts in India, Racking Up in Singapore & Gaming Across Borders
- Welcome to Curator’s Cut – a fortnightly roundup of standout themes from the 1,500+ insights shared on Smartkarma.
- In this cut, we spotlight the shifting sentiment towards Indian equities, highlight the investable universe in Singapore around data centres, and draw attention to the gaming industry across continents.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
5. M3 (2413 JP) – Building Up After the Crash: Know Your ABCs (Activist, Buyback, Cash)
- M3 Inc (2413 JP) fell 85+% from 2021 highs to spring 2026 lows. We’re not that far off that level now. Earnings a week+ ago sent shares tumbling.
- The company is now trading just above 20x earnings with 15% CAGR targeted organic revenue growth over the next five years plus inorganic growth expected from M&A.
- M3 now has its ABCs. An Activist. A Buyback. And Cash. And it has growth at lower multiples than peers.
6. [Japan M&A] Baudroie (4413 JP) Board Decides a 1% Premium to Squeeze Out Minorities Is Good Enough
- This morning, Baudroie (4413 JP) and Bain Capital announced an MBO whereby the existing major executives and shareholders sell to Bain and then reinvest.
- The deal is at a 1% premium to last. The Board recommends minorities tender. the fair value model the Board looked at is faulty.
- But the execs/directors/optionholders/crossholders combination basically gets this deal past the two-thirds hurdle without anyone active tendering. If the GPIF tenders, it’s done. Not a great example of improved Japanese governance.
7. Baudroie (4413 JP): Bain-Sponsored MBO at a Nil-Premium Will Be Tough to Force a Bump
- Baudroie (4413 JP) has recommended a Bain-sponsored MBO at JPY2,970, a 1.0% premium to the undisturbed price of JPY2,942.
- While the offer is above the midpoint of the IFA DCF valuation range and attractive relative to peer multiples, it is 7.8% below the 3-month high of JPY3,220.
- A competing offer is unlikely, as the founding shareholders did not accept a fiduciary-out clause. The deal is tough to block because of the low minimum acceptance threshold.
8. Samsung Return: ₩27.5tn Special Dividend, No Immediate Cancellations Raise Memory Pivot Concerns
- Samsung sees KRW 90tn to KRW 110tn of 2026 shareholder returns, with around KRW 30tn in 3Q dividends and the balance decided in January 2027.
- Samsung’s KRW 110tn FCF payout ceiling looks likely, while the KRW 150tn view is too aggressive. The KRW 27.5tn special dividend is more dividend heavy than expected.
- No cancellation focused buyback was announced, signaling limited confidence in memory pricing. With returns heavily dividend skewed, the near term Samsung downside looks hard to avoid.
9. Merger Arb Mondays (17 Aug) – Steadfast, Con Aero, Z Fin, Cleanaway, OFX, BetMakers, FleetPartners
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), OFX Group (OFX AU), Z Fin (1168 HK), Atlantic Lithium (A11 AU), Tourism Holdings (THL NZ), Cleanaway Waste Management (CWY AU).
- Lowest spreads: FleetPartners Group (FPR AU), Accent Group (AX1 AU), Kakaku.com Inc (2371 JP), Taiyo Holdings (4626 JP), Digital Hearts Holdings (3676 JP), Japan Property Management Center (3276 JP).
10. OceanaGold (OGC CN) Claims Ausgold (AUC AU). Clean Deal
- Gold fever continues Down Under as Ausgold Ltd (AUC AU) enters into a Scheme with OceanaGold Corp (OGC CN).
- OceanaGold is offering 0.03365 new shares for each Ausgold share, or an indicative Offer price of A$1.36/share, a 28% premium. A capped cash option is afforded, also at A$1.36/share.
- Post merger, Ausgold shareholders would hold ~7.9% (if 100% scrip consideration). A key shareholder and directors (collectively holding 9.1%) are supportive. December completion expected. Clean deal. Interlopers possible.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Latest Read on Hynix Shareholder Return and Solidigm Since Last Friday’s Filings
- Street sees end-August print with Solidigm tie in; total around 70 trillion won, mix buyback plus special dividend, staged from 4Q with multi year buyback and FCF linked quarterly payouts.
- Near term narrative weak; immediate shareholder return signal unlikely. Faster Solidigm timeline could signal urgency on peak out risk and reinforce concerns rather than remove them.
- Tactical setup; if stock catches a bid, play the pop, monetize relief, and rotate out rather than chase strength.
2. Guotai Junan (1788 HK): Get Involved Here
- After broker/investment bank Guotai Junan (1788 HK) (GJI) was suspended last month pursuant to the Takeover’s Code, an Offer from its state-backed parent Guotai Haitong (601211 CH) (GHS) was expected.
- That unfolded last Friday evening (7th July), with GHS pitching a pre-conditional (SASAC/NDRC) Scheme at HK$3/share, a 44.2% premium to last close, bang in-line with my estimate. Terms are final.
- The pre-con long stop date is the 31st October. That’s uncommonly quick. This could (should) be wrapped up before year-end. Plus there are some quirky Scheme vote-blocking %s.
3. [Japan M&A] EQT+DG Up Kakaku.com (2371 JP) Bid by 3.478261% to ¥3570; Bain Needs To Bump, Again
- In what is rapidly becoming tedious, EQT+DG have raised their bid on Kakaku.com by 3.48% to thwart Bain’s bid, which is now just 1.96% above EQT’s bid.
- If Bain wants to “win”, it has to come over the top. They can raise by ¥2/share and that refreshes everything but that would just allow EQT to raise ¥2/share.
- Kakaku.com should probably sit both down and say “Final round. We have spoken to KDDI. Put in your best bid and we will support/recommend. No crying at the casino.”
4. Hynix New ADR Issuance After October Lockup Expiry: Low Probability for Now
- ADR chatter is building for October, but there is still no solid Yeouido read. Political, regulatory and Square 20% constraints make an aggressive buyback plus ADR primary a tough call.
- Base case remains a late execution for the special dividend and buyback, preserving flexibility around FCF volatility rather than committing to an aggressive schedule upfront.
- We should assign low odds to Hynix front loading the buyback and executing aggressively within a tight window to facilitate a new ADR issuance.
5. FleetPartners (FPR AU): A Simmering Bidding War as Element Fleet Lobs an Offer
- FleetPartners Group (FPR AU) has received a non-binding indicative proposal from Element Fleet Management (EFN CN) at A$3.80 per share, representing a 5.6% premium to Sg Fleet (SGF AU)‘s offer.
- Element has also offered an enhanced offer of A$4.00 if the Board grants it a three-week period of hard exclusivity by 11 August.
- Element’s offer remains light. While the Board has rejected its offer, SG Fleet is likely to return with a revised offer supported by significant cost synergies.
6. Merger Arb Mondays (10 Aug) – GJTAI, Con Aero, Get Nice, Cygnus, OOh!Media, Digital Hearts, JPMC
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), Guotai Junan International (1788 HK), OFX Group (OFX AU), Cygnus Metals (CY5 AU), European Lithium (EUR AU), Z Fin (1168 HK).
- Lowest spreads: Accent Group (AX1 AU), Kakaku.com Inc (2371 JP), Taiyo Holdings (4626 JP), Future Corporation (4722 JP), Japan Property Management Center (3276 JP), oOh!Media Ltd (OML AU).
7. BetMakers Technology (BET AU) Enters Scheme With Tabcorp (TAH AU)
- This morning (10th August), gambling tech play BetMakers (BET AU)announced it had entered into an offer, by way of a Scheme, with Tabcorp (TAH AU), at A$0.24/share, in cash.
- That’s a 45.5% premium to undisturbed. BetMakers’ shareholders can also elect scrip (25%/50%/75%/100%) with the balance in cash. Scrip is capped. The default option is cash.
- BetMakers’ board, holding ~10% of shares out, unanimously support terms. Completion targeted 3Q27 (Jan-Mar’ 27). ACCC approval required. That’s the wild card.
8. Korea Exchange Designates 36 Companies As Administrative Issues for Potential Delisting
- On 12 August, the KRX designated 36 companies as administrative issues for potential delisting for failing to meet share price and market capitalization standards.
- They could potentially be delisted. There are potential trading opportunities among these 36 stocks.
- The key is to be on the lookout for companies with decent balance sheets that are willing to improve their corporate governance.
9. OOh!media (OML AU): I Squared Emerges with the Winning Bid
- The AFR reports that I Squared emerged with a winning binding proposal for oOh!Media Ltd (OML AU) at A$1.70, a 100.0% premium to the undisturbed price of A$0.85 (28 April).
- The offer is light compared to peer and precedent transactions and is below the 52-week high of A$1.73.
- However, shareholders should be supportive, as the offer was the highest in a competitive auction, and it is uncertain whether the Board’s strategic execution could outperform a 100% takeover premium.
10. Cleanaway Waste (CWY AU): EQT’s A$3.13/Share NBIO Is Fair
- It’s been pretty quiet on the M&A front for Cleanaway Waste (CWY AU). KKR was rumoured to be interested four years ago. Around the time Cleanaway acquired Suez Sydney Assets.
- Now Swedish PE outfit EQT has proposed taking Cleanaway private, via a Scheme, at A$3.13/share, a 32.1% premium to undisturbed. EQT has been afforded nine weeks of exclusive due diligence.
- The indicative offer is subject to FIRB, ACCC, MACs, plus the standard Scheme vote from Cleanaway shareholders. Pricing appears fair. The board is supportive at A$3.13/share.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Investigation into Hynix ADR Fungibility Restoration and Key Open Questions
- Hynix might have rushed ADR to price off Q1 within 135 day window, with weak Q1 LTA pricing already baked in and expected to pressure forward earnings.
- Hynix’s aggressive ADR timeline compromised fungibility, leading some investors to view the move as a signal of management’s cautious outlook on forward memory pricing.
- Hynix is more likely to go with incremental filings in batches. That gives them flexibility to manage supply and support the underlying tactically instead of committing to a risky buyback.
2. Square Spread Compression on Early August Hynix Buyback Narrative
- Local chatter says government is pushing early Hynix Samsung shareholder return amid KOSPI weakness. Buybacks would signal support at current levels, counter supply driven memory downside.
- Hynix cited ADR quiet period as reason for limited disclosure, likely tied to Rule 174d window ending August 4. Market expects buyback post expiry, with positioning already tightening Square/Hynix spread.
- Chatter sees Hynix disclosing buyback size and timing soon, likely phased with policy unchanged. Government pressure supports earlier rollout; stay long narrative and lean into Square Hynix pair.
3. [Japan Buyback, But Not] 7&I (3382) To Buy Back ¥400bn from Market, Sell ¥300bn to Crossholders
- On Friday after the close, Seven & I Holdings (3382 JP) announced a ToSTNeT-3 buyback scheduled for Monday morning for ¥400bn, worth 8+% of shares outstanding.
- That’s big. But the seller is likely to be SMBC Nikko. And they will then spend much of the next year buying back ¥400bn of shares on-market.
- Separately, 7&i announced an alliance with Softbank Corp, PayPay, and Sumitomo Mitsui Card. They will buy ¥100bn each. Net, this means a 2% buyback IF successful. More if not.
4. Merger Arb Mondays (03 Aug) – Taiyo, NS United, Future, Kakaku, Shinko Shoji, Dida, ASM, Accent
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), Ns United Kaiun Kaisha (9110 JP), OFX Group (OFX AU), Atlantic Lithium (A11 AU), Cygnus Metals (CY5 AU).
- Lowest spreads: Accent Group (AX1 AU), Kakaku.com Inc (2371 JP), Australian Strategic Materials (ASM AU), Future Corporation (4722 JP), Taiyo Holdings (4626 JP), Dida (2559 HK).
5. Betting Against Aussie Critical Minerals
- On the 20th July 2026, an US executive order was issued requiring major arms manufacturers to trace their supply chains and actively phase out Chinese rare earths.
- A week later, the FT carried an article on hedge funds increasing their bets against US critical minerals companies.
- Given the US-Australia bilateral framework targeting critical minerals projects in Australia and the U.S., it is worthwhile analysing the bets, if any, against Aussie critical minerals companies.
6. SK Inc Agrees To Sell Its 70.6% Stake in SK Siltron to Doosan Corp
- On 31 July, SK Inc (034730 KS)’s BOD approved the sale of its 70.6% stake in SK Siltron to Doosan Corp (000150 KS) for 2.3 trillion won (US$1.6 billion).
- If SK Siltron’s EBITDA exceeds a defined threshold, SK Inc. receives an earn-out payment equal to 40% of the excess amount, scaled to its 70.6% equity stake.
- The SK Siltron sale boosts SK Inc. through the initial 2.3 trillion won cash inflow plus further upside from the performance-linked earn-out clause.
7. FleetPartners (FPR AU): SG Fleet’s NBIO at A$3.60 Is Light
- FleetPartners Group (FPR AU) has received a non-binding indicative proposal from Sg Fleet (SGF AU) at A$3.60 per share, a 27.2% premium to the undisturbed price of A$2.83 (31 July).
- The offer is light compared to precedent transactions and peer multiples. The timing is also opportunistic, as the shares have materially underperformed peers YTD.
- The shareholder structure necessitates an attractive offer. A bump is likely, particularly as this proposal could catalyse a competing bid from Mcmillan Shakespeare (MMS AU) or Smartgroup Corp (SIQ AU).
8. JPMC (3276 JP): Sunrise Capital-Sponsored MBO at JPY2,250
- Japan Property Management Center (3276 JP) announced a Sunrise Capital-sponsored MBO at JPY2,250, a 23.5% premium to the last close of JPY1,822.
- The offer, which resulted from an auction, is attractive as it represents an all-time high and is at the midpoint of the IFA DCF valuation range.
- Key shareholders will be supportive of the offer, particularly as the 23.5% takeover premium is understated, as JPMC shares have materially outperformed its peers over the last month.
9. Digital Hearts (3676 JP): Chairman-Led MBO Is Light but Likely Done
- Digital Hearts Holdings (3676 JP) announced a Chairman-led MBO at JPY1,060, a 40.8% premium to the last close of JPY753.
- The timing is opportunistic as the shares have underperformed peers YTD. The offer is below the midpoint of the target IFA’s DCF valuation range and the special committee’s requested offer.
- However, the deal is likely to complete, as the substantial shareholders have either provided irrevocables or will be supportive, given that the offer provides an attractive ROI.
10. Tencent (700 HK) Earnings on 12 Aug: Elevated Volatility, Modest Implied Move
- Context: Tencent (700 HK)will announce H1 2026 results on 12 Aug, with 14 Aug options providing direct exposure to the earnings event.
- Highlight: Historical earnings-day moves have been modest in absolute terms but remain above the current option-implied move, despite realised and implied volatility sitting near the top of their historical ranges.
- Why Read: Gain insight into Tencent’s earnings-day price history, option-implied move, volatility term structure, and trade implications around straddles and calendar spreads.