
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
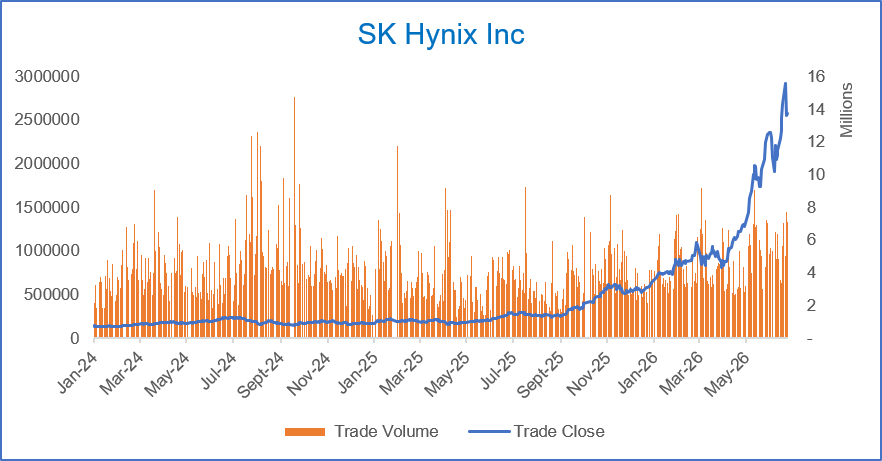
1. SK Hynix (000660 KS; SKHY US): Buyback Provides More Optionality than a Special Div
- SK Hynix (000660 KS) / SK Hynix (SKHY US) announces earnings on 29 July. Expectations are for the company to announce a buyback or a special dividend.
- A buyback will provide SK Hynix (000660 KS) with an option to issue more ADSs, something that they cannot do as things stand.
- A buyback and the subsequent issuance of ADSs will help keep the ADS premium under control and reduce volatility transmission from the US markets to the local listing.
2. Hynix ADR Conversion Pool Opening: The Only Realistic Path Forward
- The prior base case was a late October 3Q earnings buyback announcement, followed by a 2~2.5% SO repurchase over six months, but that view is starting to lose traction.
- Hynix may avoid it due to cash burn risks amid memory pivot concerns, meaning the expected buyback announcement may not happen.
- Hynix may use ADR arb flows to support local shares, with KRW 1.46 million to KRW 1.50 million viewed as the trigger zone at around 2.0x forward PBR.
3. [Japan M&A] Nippon Yusen (9101) To Buy Out NS United Kaiun (9110) At ¥10,600/Share
- Nippon Yusen has agreed to buy super-majority control of Ns United Kaiun Kaisha (9110 JP) from erstwhile controller (and shareholder partner) Nippon Steel Corporation (5401 JP).
- The price is a nice premium, and an all-time high, and well above book – which is not bad for a shipping company. But it isn’t a super-high multiple.
- Together, friendly corporate and financial holders own near 60%. Domestic passive enough to get past 67%. This should be OK. Not much need or purpose for activism here.
4. [Japan M&A] Bain Overbids EQT by 2+% and 5.5+% Depending on KDDI Agreement. Market Wants More
- In the latest salvo, Bain+LY have come back with a counter to the last overbid by EQT+DG at ¥3,450. That bid needed a bump because ¥3,500 was <2% higher.
- Bain+LY have bid ¥3,520 standalone and ¥3,640 with KDDI agreement. I expect this is enough to get Kakaku’s support if EQT don’t match.
- The market had priced this outcome PLUS another overbid. I wouldn’t be surprised to see two more but we’re closer to the end than the beginning.
5. A Tender Offer of a 46.5% Stake in SK Signet by SK Inc
- On 24 July, SK Inc (034730 KS) launched a tender offer for common shares of SK Signet (260870 KS), a subsidiary listed on the KONEX market.
- The tender offer is for a 46.5% stake in SK Signet. Post a successful tender offer, SK Inc plans to delist SK Signet.
- Overall, I am negative on this tender offer and on SK Signet. I think the more realistic scenario is for investors to tender about 10-15% of outstanding shares.
6. Future Corp (4722 JP): A Chairman-Led MBO Could Invite Activism
- Future Corporation (4722 JP) announced a Chairman-led MBO at JPY2,451, a 2.9% premium to the last close of JPY2,382.
- The low takeover premium could be explained by the mysterious 65.13% share price surge from 24 June to 27 July. Also, the offer represents an all-time high.
- However, the offer is below the midpoint of the special committee’s IFA DCF valuation range and is light relative to precedent transactions, potentially attracting activists.
7. Merger Arb Mondays (27 Jul) – Skyworth, Changhong Jiahua, Z Fin, Con Aero, OFX, Cygnus, Kakaku
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), OFX Group (OFX AU), Cygnus Metals (CY5 AU), Atlantic Lithium (A11 AU), Tourism Holdings (THL NZ), Z Fin (1168 HK).
- Lowest spreads: Accent Group (AX1 AU), Australian Strategic Materials (ASM AU), Kakaku.com Inc (2371 JP), Shinko Shoji (8141 JP), Taiyo Holdings (4626 JP), J.S.B (3480 JP), Clearview Wealth (CVW AU).
8. Samsung Likely Pivots to ADR Driven Buybacks to Conserve Cash Amid Memory Turn and Capex Pressure
- Compression not driven by memory multiple derating but FX flows. KRW strength vs JPY from Hynix ADR inflows drove futures rotation. As FX normalizes, positioning unwinds, implying pref discount reversion.
- Key trigger is special div timing under 50% FCF. Samsung wary of cash outflow amid memory pivot and capex push, likely shifting to buybacks via ADR to retain cash.
- Pref compression near pivot as KRW normalizes. Low odds of special div. Aggressive buyback plus ADR flow could trigger sharp reversal.
9. Perpetual (PPT AU): EQT Lifts Its NBIO To A$22.50/Share
- Following its curious A$22.07/share self-destructing NBIO on the 15th July, EQT has returned with a A$22.50/share NBIO for Perpetual Ltd (PPT AU), by way of a Scheme.
- That’s a 4% bump to its initial NBIO of A$21.64/share on the 1st July, which was rejected as being inadequate. $22.07/share was similarly deemed inadequate.
- PPT’s board is assessing the revised tilt. Optically, terms appear fair. Ot at least sufficient to engage. A$22.50/share is a 45.2% premium to undisturbed.
10. SK Chairman Chey Tae-Won To Pay 944 Billion Won to Roh So-Young in Divorce Payment
- On 24 July, it was reported that the Seoul High court finalized the divorce case between SK Group Chairman Chey Tae-Won and his estranged wife Roh So-Young.
- The final verdict was that Chairman Chey will need to pay Roh 944 billion won ($638 million) in cash which is the largest divorce case amount in Korea’s history.
- If an appeal is filed, the Supreme Court determines final asset division. However, both parties will likely accept this decision by the Seoul High court, in my view.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. On Headlines that Hynix Will Fully Block ADR Conversion
- Seoul Economic Daily flagged senior sourced messaging. Points to Hynix running TSMC style setup, capping usable pool near 2.5 percent and scaling ADR only via secondary issuance.
- Worst case for arb. Strong incentive to capture ADR premium as funding. Hard to directly link to recent drawdown, though buyback plus secondary timing could support it.
- Market still anchors 2Q reset on utilization shifts under US regulatory pressure, so coordinated ADR setup is a stretch. Base case is downside from arb shutdown, watching for TSMC-style execution.
2. Zhongji Innolight (3308 HK): (Fast) Global Index Inclusions Post H-Share Listing
- Zhongji Innolight (300308 CH) could raise up to US$8.1bn in its H-share listing if the Overallotment Option is exercised. The H-shares are offered at a 23.3% discount to the A-shares.
- There is a big allocation to cornerstone investors with a 6-month lockup. Fast Entry to global indices is still high probability, though early exercise of overallotment will help.
- The H-shares should be added to Southbound Stock Connect from the open of trading on 27 August following the end of the Price Stabilisation period.
3. KSD Confirms Hynix ADR 2.5% Hard Cap, Only Hynix Can Expand It. Outlook on the Actual Playbook
- KSD CEO confirms 2.5%t hard cap on ADR conversion despite 25% SEC headroom. Two way conversion starts July 29, but scaling the cap is fully Hynix call.
- Hynix not pushing 2.5% cap hike, instead engaging FSC on ADR registration including third-party conversions. Market confused as past exemptions existed, raising questions on intent and signaling possible hidden agenda.
- Market suspects Hynix may limit ADR pool expansion to capture premium, using FSC registration talks as cover. Base case is gradual pool opening with controlled conversion flow.
4. StubWorld: Prosus Is A Buy Here
- Prosus NV (PRX NA) is coming up “cheap” on my monitor versus Tencent (700 HK). And Naspers (NPN SJ) “rich” to Prosus.
- Preceding my comments on Prosus/Tencent/Naspers are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
5. [Japan Activism/Value] – Mitsui Matsushima (1518) Raises; Low PER, High ROE/Growth (Still), Now Div!
- Today, Mitsui Matsushima (1518 JP) upped full-year guidance, lifting revenue by 4.4%, OP by 3%, and NP by 21% (at earnings, they guided revenue +3.9%yoy, NP +5.7%yoy after decent beats.
- Today, they announced the purchase of an asset-rich q-tip maker with 10% OPMs and NPMs >OPMs on ¥3.6bn revenue the last 3yrs. Deal closes August. We’ll know more in September.
- The earnings uplift is frankly not that impressive. There were stock sale gains, and the uplift in consolidated numbers from the buy. But the dividend hike is REALLY impressive.
6. [Japan M&A] EQT+DG Up Their Kakaku.com (2371 JP) TOB Price by 15% to ¥3450; Bain Needs To Bump
- On Friday 17 July, EQT and DG announced their consortium would lift their Tender Offer Price to ¥3,450/share, up 15% from their previously-announced ¥3,000/share, already extended.
- This is a pre-emptive official response to the legally-binding offer made to Kakaku by the Bain/LY consortium earlier this month at ¥3384 (¥3500 if KDDI agree).
- This “obstructs” the Bain/LY deal, slightly, for the moment, but there are nuances within. I still think Bain/LY come over the top.
7. Guotai Junan International (1788 HK): Privatisation by Guotai Haitong Securities?
- Guotai Junan International (1788 HK)/GJTAI is in a trading halt “pending the issuance of an announcement pursuant to the Code on Takeovers and Mergers.”
- It is likely that Guotai Haitong Securities (2611 HK) is seeking to privatise GJTAI. The timing would be opportunistic, as GJTAI has underperformed its peers over the last 12 months.
- I use three methods to triangulate the likely offer price. My methods suggest a price range of HK$2.80 to HK$3.50 per share, a 34.6%-68.3% premium to the last close.
8. A Partial Tender Offer of Gabia by Macquarie
- On 20 July, Macquarie Korea Opportunities Private Equity Fund No. 6, managed by Macquarie Asset Management announced that it is conducting a tender offer for Gabia Inc (079940 KS) shares.
- The tender offer price is 48,000 won per share and the tender offer period lasts from 20 July to 17 September. Post tender offer, Macquarie plans to delist Gabia.
- I believe this partial tender offer of Gabia by Macquarie could trigger a potential M&A fight for the control of the company, leading to much higher share price.
9. StubWorld: Legend’s Bifurcation To Lenovo Is Unsustainable
- A double dose of StubWorld this week: Legend Holdings (3396 HK)‘s implied stub and simple ratio (Legend/Lenovo (992 HK)) are both around multi-year lows.
- Preceding my comments on Legend and Lenovo are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
10. Merger Arb Mondays (20 Jul) – Kakaku, Shinko Shoji, Get Nice, Shengmu, Skyworth, Steadfast, Vault
- I summarise the latest spreads and newsflow for the merger arb situations covered across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), Atlantic Lithium (A11 AU), Cygnus Metals (CY5 AU), Tourism Holdings (THL NZ), Continental Aerospace Technologies (232 HK).
- Lowest spreads: Accent Group (AX1 AU), Kakaku.com Inc (2371 JP), Australian Strategic Materials (ASM AU), Shinko Shoji (8141 JP), Taiyo Holdings (4626 JP), J.S.B (3480 JP).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SK Hynix (000660 KS; SKHY US): Updated Index Flows/Timing & Where Could the Premium Settle?
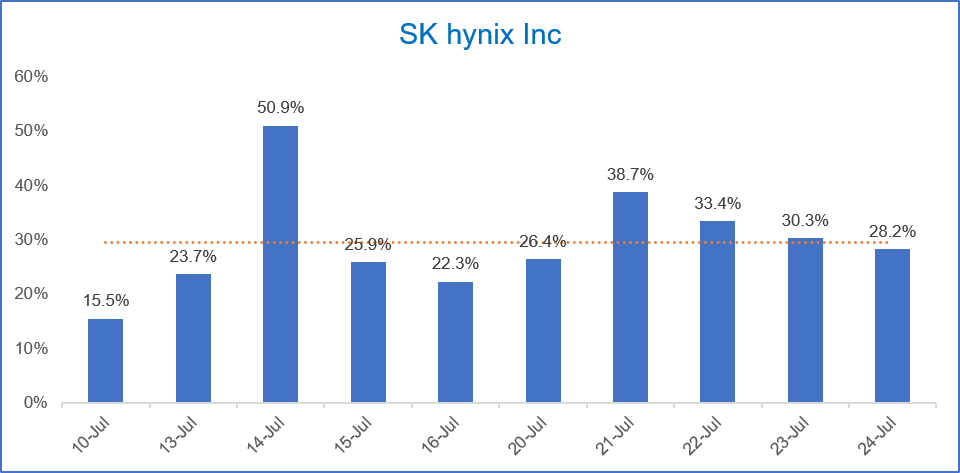
- SK Hynix (000660 KS) raised US$26.5bn selling 177.9m shares of SK Hynix (SKHY US) at US$149/share. SK Hynix (SKHY US) closed at a 15.5% premium to the local line.
- There will be passive buying in the local shares and the ADR line over the next few months. The ADR line could trade at a premium in the near-term.
- We expect the ADR to trade between a 30-35% premium in the very short-term and that could drift lower following the limited passive buying in the ADR.
2. Newly Surfaced Risk to Hynix ADR Premium Trade
- Hynix’s FSS engagement strongly signals a potential treasury buyback into ADR conversion.
- Tight early conversion quotas could let Hynix capture capacity upfront, pressuring local shares and forcing ADR premium assumptions above TSMC’s 30% historical peak.
- Need to price in upside beyond TSMC’s 30% peak, as Hynix could capture premium expansion early, creating a key risk for ADR premium trading setup.
3. Story Behind Hynix 2Q Earnings Reset Leak
- 2Q price reset was inevitable, but Hynix’s early leak three weeks before earnings raises questions. The timing matters given significant memory multiple compression and potential strategic positioning.
- Need a precise Hynix playbook as memory multiple compression persists. Focus on capturing ADR conversion headroom as a micro catalyst and assessing its role as a relative buffer versus peers.
- KSD guidelines could come earlier than expected. Medium term, combine US passive flows with memory hedges. Watch Samsung utilization ramp and potential preferred discount compression.
4. Genesis (GMD AU) & Vault (VAU AU) Merger: Index Implications with A$1bn to Buy
- The Genesis Minerals (GMD AU) and Vault Minerals Ltd (VAU AU) merger will bring much larger passive flows compared to the Regis Resources (RRL AU) and Vault merger.
- For each share of Vault Minerals Ltd (VAU AU) held, shareholders will receive 0.7629 shares in Genesis Minerals (GMD AU) plus A$0.475 in cash.
- The MergeCo could be added to a couple of indices and be upweighted in a few others, bringing in over A$1bn of inflows following merger completion in October/November.
5. Kakaku.com (2371 JP): Rethinking the Arb Trade
- Kakaku.com Inc (2371 JP)’s shares have been trading above Bain/LY (4689 JP)’s preconditional binding offer of JPY3,384 (if KDDI agrees to a share buyback, the offer is at JPY3,500).
- I previously opined that the probability of a bidding war is low. However, disclosure on 2 July showed that EQT increased its offer to JPY3,300 on 22 June.
- EQT can match Bain/LY’s JPY3,500 offer with a modest 2.4% increase to the effective cost of its 22 June offer. If it matches Bain/LY’s effective cost, EQT can offer JPY3,643.
6. Kakaku.com (2371 JP): Sheer Gamesmanship
- Nikkei reported that EQT/Digital Garage (4819 JP) has increased its offer for Kakaku.com Inc (2371 JP) to the mid-JPY3,400, while Bloomberg reported that EQT/DG is now offering JPY3,440-3,460 per share.
- The latest EQT/DG offer is designed to game the competing-offer clauses to retain the Board’s and KDDI’s support and potentially secure Oasis’s allegiance.
- The bidding battle is not done yet. By increasing its offer by 1% from JPY3,384 to JPY3,419 (from JPY3,500 to JPY3,535 on an equivalent basis), Bain/LY can regain the advantage.
7. Baycurrent (6532) Preview Before Q1 Earnings Wednesday
- When I pounded the table pre-buyback in mid-March, Baycurrent (6532 JP) was trading a lot lower, hit by the selloff in the SaaS/growth bias. AI was going to take over.
- The Skynet Takeover, while not thwarted, is delayed by the simple fact that Baycurrent is a tech/business consultant and a leading voice in corporate Japan for AI integration.
- Baycurrent reiterated guidance. Multi-year mid 20%s CAGR against 16x PER. The stock bounced. Now 20.6x Feb27e NP. Q1 earnings Weds. Seasonality matters. KPIs matter. That’s a question.
8. Digital Garage (4819 JP): Cheap, but Not Cheerful
- Digital Garage (4819 JP) shares popped 12% on news that Old Peak had emerged as a substantial shareholder, potentially signalling an activist push for the Board to prioritise shareholder returns.
- DG’s shares have languished since the announcement of the Kakaku.com Inc (2371 JP) transaction on 12 May. DG is undoubtedly cheap and could be worth 2x more.
- However, closing this valuation gap remains challenging, particularly if Resona continues to support the Board. Pasona is a cautionary tale that a material windfall does not result in a rerating.
9. China Shengmu (1432 HK): Fast-Tracking Towards Being Declared Unconditional
- China Shengmu Organic Milk (1432 HK)’s mandatory offer from China Modern Dairy (1117 HK) is HK$0.35, subject to a 50% minimum acceptance condition. The first closing date is 21 July.
- I previously opined that meeting the minimum would be challenging. However, based on CCASS data, including acceptances, CMD’s shareholding was 45.69% of outstanding shares as of 10 July.
- The offer is on track to be declared unconditional by the first closing date. At the last close and the 30 July payment, the gross/annualised spread is 7.7%/294%.
10. Genesis And Vault Firm Terms After Regis Walks
- After Genesis Minerals (GMD AU) pitched a “superior” cash/scrip Offer for Vault Minerals Ltd (VAU AU) on the 6th July, Regis Resources (RRL AU) was expected to walk. And they did.
- This morning, Genesis/Vault firmed terms: 0.7629 new shares for every Vault share, plus A$0.475/share in cash – for an implied value of A$5.274/share. Terms are unchanged from the 6th July.
- The Offer is by way of a Scheme. Expect a Scheme Booklet by August/September, a meeting a month later, and expected implementation by October/November. Clean deal.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: SK Hynix US$26.5bn ADR Trading – Where to from Here? Samsung -Ve, Micron +ve Influence
- SK Hynix (000660 KS) (SKH), a leading global memory producer, raised around US$26.5bn via an ADR listing.
- We have looked at the past performance and other deal dynamics in our previous notes.
- In this note, we talk about the recent updates and trading dynamics.
2. StubWorld: Stay Long Digital Garage (4819 JP)
- Digital Garage (4819 JP) is comfortably worth 50% more. Even doubling from here is achievable.
- Preceding my comments on Digital Garage and Kakaku.com Inc (2371 JP) are the current setup/unwind tables for Asia-Pacific Holdcos.
- Hese relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
3. Merger Arb Mondays (06 Jul) – Kakaku, Taiyo, Shinko Shoji, Arclands, Qoria, Steadfast, Dida
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Changhong Jiahua (3991 HK), Qoria (QOR AU), Atlantic Lithium (A11 AU), Continental Aerospace Technologies (232 HK), Cygnus Metals (CY5 AU), European Lithium (EUR AU).
- Lowest spreads: Accent Group (AX1 AU), Taiyo Holdings (4626 JP), Kakaku.com Inc (2371 JP), Shinko Shoji (8141 JP), Atlas Arteria (ALX AU), Avarga (AVARGA SP).
4. [Japan M&A] Kakaku Governance A Shining Example; Bain+LY and EQT+DG May Fight Longer
- I wrote about Bain/LY having shown their cards on Kakaku.com Inc (2371 JP) on 2 July. Just before I published (but after it went to compliance), Kakaku responded.
- Kakaku’s response was an exercise in good governance. It was an anti-FujiSoft situation. It was very welcome. Investors should appreciate this and learn from it.
- EQT+DG Consortium has bid ¥3,300 unofficially but that’s about ¥3,415 equivalent. My bet is they will go higher. And Bain+LY will too (theirs is equivalent ¥3,640 if DG gives up).
5. China Shengmu (1432 HK): Touch and Go
- On 30 June, the IFA opined that China Modern Dairy (1117 HK)’s mandatory conditional cash offer for China Shengmu Organic Milk (1432 HK) at HK$0.35 was fair and reasonable.
- However, the independent directors’ recommendation was not unanimous, with Mr Wang Liyan (Independent non-executive director) dissenting. The first closing date is 21 July.
- While meeting the 50% minimum acceptance condition has been aided by the significant derating of peers over the last month, it remains challenging.
6. Dida (2559 HK): Tongcheng (780 HK)’s VGO and Special Dividend
- On 29 June, Dida (2559 HK) announced two transactions: Tongcheng Travel (780 HK)‘s voluntary conditional offer at HK$1.3875 per share and a special dividend of HK$1.1745 per share.
- The total consideration of HK$2.5620 is a 108.3% premium to the undisturbed price. The key condition is a minimum acceptance of 50%, which will be satisfied by the irrevocables.
- This is a low-risk deal as the offer does not require PRC regulatory approvals. Despite being below the 52-week high, the total offer is attractive.
7. Genesis Crashes Regis & Vault’s Party With Superior Terms
- Back on the 5th May, West Aussie gold miners Regis Resources (RRL AU) and Vault Minerals Ltd (VAU AU) announced a A$11bn scrip merger, by way of a Scheme.
- What appeared to be another straightforward, albeit, large gold merger, has unravelled after Genesis Minerals (GMD AU) pitched a “superior” cash/scrip Offer yesterday morning.
- Post merger, Genesis shareholders would own ~59.8% of the combined company, and Vault ~40.2%; versus 51%/49% under Regis’ terms. Regis has until the 13th July to match Genesis’ terms.
8. Strategy (MSTR US)’s “Strategy” Unravels. What A Surprise. Not
- Strategy (MSTR US) has conditioned shareholders that everything is groovy; provided its market cap exceeds its bitcoin holdings. That’s no longer valid.
- The board’s narrative has now shifted from “never sell BTC, reserves alone will cover us“, to an explicit formalised capital framework treating bitcoin as a monetisable backstop for dividend/interest obligations.
- Tellingly (ominously?), Strategy sold 3,588 bitcoins late June/early July, its largest sale ever, at a weighted average of $60,197/bitcoin, below its $75,476/bitcoin average in-cost.
9. Yamada-Edion: The ¥2.5 Trillion Merger that Was Always Coming but Where Are the Benefits?
- Yamada and Edion may finally be tying the knot, creating a ¥2.5 trillion electronics behemoth that could dominate a shrinking market – although Edion shareholder, Nitori, might oppose the deal.
- But previous talks failed, and the initial announcement, while positive, doesn’t say a lot about how the new company will grow.
- What it does demonstrate is just how fashionable M&A has become across all formats and sectors to shore up share in a fast-consolidating retail market.
10. Buy CR Power (836 HK) As CRNE (More Than) Doubles On Debut
- Priced at RM10.11/share, China Resources New Energy (001248 CH) (CRNE) appeared fairly priced on a trailing P/B; to possibly “cheap” on a trailing PER metric, depending on your forecast viewpoint.
- However, at ~700x oversubscribed, and given CRNE is part of the vast SOE China Resources Holdings, a pop on debut was a safe bet. CRNE is now up 109%.
- China Resources Power (836 HK)‘s 81.8% stake in CRNE accounts for 307% of its market cap. And places the discount to NAV at ~74%, That’s not sustainable.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: SK Hynix ADR Listing – Filings Updates, Micron Results, Valuations
- SK Hynix (000660 KS) (SKH), a leading global memory producer, aims to raise up to US$30bn via an ADR listing.
- We have looked at the past performance and other deal dynamics in our previous notes.
- In this note, we talk about updates from its filings, Micron’s results and provide further thoughts on valuations.
2. [Japan M&A] Likely Bain/LY Overbid for Kakaku.com – STILL Not a Done Deal
- On 12 May, EQT launched an LBO for Kakaku.com Inc (2371 JP) with the agreement of two large holders. With 38% in the bag, EQT wanted another 17.5% at ¥3,000.
- Digital Garage (4819 JP) (20.5%) and KDDI (~17.55%) agreed to sell later (¥2,439). The bidder figured passive funds would vote with management post-deal. DG would reinvest in the back end.
- Bain and LY Corp announced a possible overbid at ¥3,232 without due dili. Then they got due dili. Media articles suggest Bain/LY have put forth a legally binding bid.
3. [Japan M&A] Nikkei Reports Dentsu To Lead Buyout of System Integrator Sub Dentsu Soken (4812)
- After the close today, the Nikkei reported (Japanese, English) that Dentsu Inc (4324 JP) had finalised plans to take its system integrator subsidiary Info Services Intl Dentsu (4812 JP).
- Articles are still updating but the idea is Dentsu will keep its 61.8% stake. Fujitsu and Unnamed Trading Houses will buy the rest for “around ¥200bn” implying +13.1% to ¥2,675/share.
- Dentsu responded with a TDNet filing. It’s less smokey than many other releases are. BUT… we take a look anyway at the parameters.
4. [Japan Event] Digital Garage (4819) Is The Wrong Price
- Digital Garage (4819 JP) got very exciting when an activist got involved. The less so when that activist sold its shares to Resona Holdings (8308 JP) at a fat premium.
- DG lost its driver. Perhaps Resona is a longer-term catalyst but it’s unclear. Given they are down 60% so far, they may be looking for new blood. Hayashi-san is 66.
- Now Digital Garage’s big equity affiliate stake asset will turn into cash. This is real value. It has been but this deal will double (or more than double) BVPS.
5. Luxshare Precision (2475 HK): Index Inclusion Timeline for US$3.6bn Offering; Tighter H/A Discount
- Luxshare Precision Industry (002475 CH) could raise up to HK$27.9bn (US$3.6bn) in its H-share offering if the Overallotment Option is exercised.
- The cornerstone investor allocation will be around 42% of the maximum offering size and those shares will be locked up for 6 months. Fast entry index inclusion probability is small.
- The H-shares are priced at a 17.2% discount to the A-shares last close and that is tighter than other large issues. Stock Connect from the open on 6 August.
6. [Japan M&A] Bain/LY Show Their Cards on Kakaku.com (They’re Good Cards Brent)
- Late night 1 July, LY (4689 JP) released a document showing their hand on the Kakaku.com Inc (2371 JP) TOB they proposed. It is astutely structured, in price and context.
- It’s complicated because it expects different possibilities with two headline numbers – ¥3,384/share if KDDI doesn’t sign up, and ¥3,500/share if they do. That’s a bit misleading.
- They expect a Kakaku response within 4 weeks and a deal launch by end-Sep. The big question here is if EQT+DG stump up to match, or if they play hardball.
7. Merger Arb Mondays (29 Jun) – Con Aero, Skyworth, Changhong Jiahua, Shinko Shoji, Nippon Dry, Qoria
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Qoria (QOR AU), Changhong Jiahua (3991 HK), European Lithium (EUR AU), Cygnus Metals (CY5 AU), Continental Aerospace Technologies (232 HK).
- Lowest spreads: Accent Group (AX1 AU), Taiyo Holdings (4626 JP), Kakaku.com Inc (2371 JP), Clearview Wealth (CVW AU), Paltac Corporation (8283 JP), Kodensha Co (1948 JP).
8. Dentsu Soken (4812 JP): Dentsu’s Potential Privatisation Offer
- On 2 July, Nikkei reported that Dentsu Inc (4324 JP) plans to take Dentsu Soken (4812 JP) private by partnering with Fujitsu and other general trading companies.
- The rumoured JPY200 billion valuation for the 38.12% stake not owned by Dentsu suggests an offer of JPY2,688 per share, a 26.0% premium to the undisturbed price.
- Due to Dentsu’s large stake, a generous offer is unnecessary. Nevertheless, the rumoured offer is attractive compared to precedent transactions and peer multiples.
9. Kakaku.com (2371 JP): Bain/LY’s Binding Offer May Get the Job Done
- Bain/LY (4689 JP)’s preconditional binding offer for Kakaku.com Inc (2371 JP) is at JPY3,384, a 12.8% premium to EQT’s JPY3,000 offer. If KDDI provides an irrevocable, it is JPY3,500.
- Bain/LY expect the Board to decide whether to recommend the proposal around mid-to-late July. The Bain/LY offer will automatically trigger a 10-day extension of the EQT offer.
- The probability of a bidding war is low, as the Bain/LY offer represents an all-time high and EQT lacks a strong partner to support one.
10. Alpha Generation Through Share Buybacks in Korea: Bi-Monthly (May & June 2026)
- In this insight, I discuss the alpha generation through companies that announced share buybacks in the Korean stock market in May and June 2026.
- I provide a list of 59 companies in the Korean stock market that have announced share buyback programs in the past two months.
- There were eight companies with more than 300 billion won in market cap that announced share buybacks in the past two months with at least 1% of outstanding shares.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SK Hynix (000660 KS; SKHY US) ADR Issue: Large Index Flows & Potential Timing
- SK Hynix (000660 KS) is looking to raise around US$30bn via a new share issue to back ADRs listed on the NASDAQ.
- The ADR to local share ratio is 10:1 and the ADRs are expected to start trading in the second half of July.
- There will be passive buying from multiple index trackers and that will mop up a significant amount of the new share offering.
2. Samsung July Buyback: Impact on the Hynix ADR Listing Setup
- Street chatter points to Samsung buyback board approval likely landing in the first half of next month, pre mid month, with management increasingly focused on Hynix market cap flip risk.
- Samsung common outperforms prefs today. Street reads it as management leaning into Hynix relative performance and skewed toward common driven flow impact.
- Lean into Hynix ADR setup with overhang reinforcing long Samsung short Hynix. July buyback flow adds tailwind. Square Hynix outperformance may re lock into listing window despite today’s pullback.
3. Curator’s Cut: Levered ETFs in Asia, Listed and Listing Exchanges & Robotaxis’ Road Ahead
- Welcome to Curator’s Cut – a fortnightly roundup of standout themes from the 1,200+ insights shared on Smartkarma.
- In this cut, we cover the fast growth of levered ETFs including in Asia, weigh two exchange plays in India and Japan, and assess the competing models in robotaxi.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
4. Samsung Electronics: Expectation of a Massive Share Buyback Announcement in the Next Few Weeks
- There is a growing expectation of a massive share buyback by Samsung Electronics (005930 KS) in the coming weeks.
- In this insight, I discuss the likelihood, reasons for the buyback, potential size amount, and the impact on the ordinary vs preferred shares price differential.
- In my view, the potential buyback size amount could about 90 trillion won to 110 trillion won over the next three years.
5. On the SK Holdings/Square Merger Noise Circulating in the Local Market Since Yesterday
- Korea street is buzzing on SK governance revamp, with merger talk between SK Holdings and SK Square driving extreme price divergence.
- Merger idea is highly radical with no conviction level intel, so likely noise, but outsized Holdings price action suggests the narrative could stick and keep driving flows near term.
- Speculative chatter links early fab expansion news leak to boosting Holdings valuation via SK Ecoplant exposure, shaping relative trades across Holdings, Square, Hynix.
6. Merger Arb Mondays (22 Jun) – Kakaku, Nippon Dry, Shinko Shoji, Accent, Humm, Qoria, Skyworth
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Qoria (QOR AU), Changhong Jiahua (3991 HK), Humm Group (HUM AU), Cygnus Metals (CY5 AU), Continental Aerospace Technologies (232 HK).
- Lowest spreads: Accent Group (AX1 AU), Taiyo Holdings (4626 JP), Kakaku.com Inc (2371 JP), Nippon Dry Chemical (1909 JP), Shinko Shoji (8141 JP), Atlas Arteria (ALX AU).
7. Makino Milling Machine (6135 JP): NSSK’s Rumoured Revised Offer Around JPY16,000
- The Nikkei reported that NSSK has made a revised proposal for Makino Milling Machine Co (6135 JP) at around JPY16,000, a 36.2% premium to the failed MBK JPY11,751 offer.
- The Nikkei highlights a risk that the NSSK tender offer may be rejected in favour of implementing the updated corporate enhancement plan (announced on 13 May).
- However, the Board is likely to support an NSSK offer of around JPY16,000, as it would represent an all-time high and exceed the peer- and market-adjusted undisturbed price.
8. Shinko Shoji (8141 JP): Intriguing Shareholder Movements Ahead of 26 June Close
- Sand Grove Capital, which started buying on the day of the offer announcement, has increased its Shinko Shoji (8141 JP) shareholding to 6.12% of outstanding shares.
- Sand Grove, primarily an event-driven fund, has bought marginally above terms, suggesting that it is either playing the bumpitrage trade or waging its first Japanese activism campaign.
- While Murakami’s exit and Sand Grove’s emergence increase the chances of a bump, Kaga Electronics (8154 JP) retains options to force completion at current terms.
9. Ajinomoto Malaysia (AJI MK): Ajinomoto’s Fair Offer
- MSG-Manufacturer Ajinomoto Malaysia (AJI MK) has announced Ajinomoto Co (2802 JP), its controlling shareholder, intends to delist the company via a selective capital reduction.
- Ajinomoto is offering RM20/share in cash, a 31.6% premium to last close; but more like 67% due to apparent price leakage. Ajinomoto holds 50.38% of shares out.
- The Offer price is a decade-high. For shareholders in an illiquid stock, here’s your exit.
10. StubWorld: Sino American Silicon (5483 TT)’s Decade-Low Implied Stub
- The implied stub for Sino American Silicon Products (5483 TT) (“SAS”) – and simple ratio (SAS/GlobalWafers (6488 TT) – are both at decade-lows.
- Preceding my comments on SAS are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [More Japan Navel-Gazing] Thinking About The Value of Toshiba with Kioxia at ¥96k
- On 19 May 2026 I wrote [Japan Navel-Gazing] Thinking About The Value of Toshiba. I pointed out that it was a fair bit more than people might think.
- Since then, Kioxia Holdings (285A JP) shares are up 95% and the value of Toshiba’s shares in Kioxia are up an additional ¥4trln.
- That has repercussions. Since I wrote, one company told investors the impact on their results. There are read-throughs.
2. ENN Energy (2688 HK): Precedent Set as the Offer Is Effectively Blocked by Regulators
- More than a year in, the ENN Natural Gas (600803 CH) offer for ENN Energy (2688 HK) lapses as the long stop date (12 June) was not extended.
- The offer was effectively blocked, not by an explicit CSRC rejection with stated reasons, but by the approval process failing to conclude within a viable timeframe.
- The CSRC’s non-approval is unprecedented, as the transaction has received NDRC, MoC, and SAFE approvals. My estimated deal-break price is HK$49.00 (broadly in line with the last close).
3. Kingboard Laminates (1888 HK): Placement Will Bail Out Shorts; Index Implications
- Kingboard (148 HK) is looking to sell 155m shares of Kingboard Laminates (1888 HK) at a price range of HK$75.6-77.7/share, a discount of 9.5-12% to the last close.
- At the current placement size, there could be passive buying from trackers of one global index. A small increase in the placement size could result in more passive buying.
- Short interest has soared in the stock, and some shorts will be looking to stem the bleeding by subscribing to the placement.
4. [Japan Value] TRE Holdings (9247) Clear MTMP With Growth, and Hidden Asset Worth 1x MarketCap
- TRE Holdings (9247 JP) was formed 5yrs ago by the merger between two waste management/recycling companies – Takeei Corp (2151 JP) and Rever Holdings Corp (5690 JP).
- They had a couple of boom years in March 2025-2026 cleaning up after the Noto Peninsula Earthquake. That falls off this year. But there is growth ahead.
- The company’s aggressive investment plan plans for significant capex and revenue growth. It is entirely funded by OPCF, new debt, and cash. NOT by the hidden asset worth 1x marketcap.
5. [Japan M&A] JSB Gets A Big Bid from Warburg Pincus at ¥9,000 – +172% from Undisturbed
- Friday after the close, Tokyo student housing specialist J.S.B (3480 JP) announced a takeover by Warburg Pincus’ Asia real estate fund.
- The family which owns 38.5% and Hikari Tsushin which owns 19+% have agreed. The family will reinvest in a 30% stake, taking out substantial cash.
- This is a big win for investors. The stock was trading somewhat cheap in late March when a specialist media article said it was in Round 2. +172% from there.
6. HK A+H IPO Cornerstone Lock-Up Expiry: Price and Liquidity Evidence (Updates)
- We update the A+H cornerstone lock-up expiry study with 18 deals and a longer post-expiry observation window.
- The revised pattern is timing-driven. Early post-expiry trading was resilient, while weakness appeared later than the February note captured.
- A-H premium is a clear cross-sectional screen in this sample.
7. Kingboard (148 HK) Places Out More Shares In Kingboard Laminates (1888 HK)
- In StubWorld: Big Moves In “Kings”, I mused, given 66.62%-held Kingboard Laminates (1888 HK)‘s meteoric price gain, Kingboard (148 HK) may seek another placement. And so it has.
- Kingboard is placing out 155mn shares in Laminates, or 4.92% of shares out, at HK$76/share, a 11.5% discount to last close, raising HK$11.8bn. This placement reduces Kingboard’s stake to 61.7%.
- This is Kingboard’s second placement in 2026 after it sold 130mn shares (4.15% of shares out) in Laminates back on the 18th March 2026, pocketing HK$2.72n
8. Merger Arb Mondays (15 Jun) – Skyworth, Changhong Jiahua, Con Aero, JSB, Nippon Dry, Steadfast
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Qoria (QOR AU), Changhong Jiahua (3991 HK), Humm Group (HUM AU), J.S.B (3480 JP), Continental Aerospace Technologies (232 HK), Tourism Holdings (THL NZ).
- Lowest spreads: Taiyo Holdings (4626 JP), Kakaku.com Inc (2371 JP), Nippon Dry Chemical (1909 JP), Australian Strategic Materials (ASM AU), Shinko Shoji (8141 JP), Kodensha Co (1948 JP).
9. An Update on Delisting of Hyundai Home Shopping and the Merger Ratio with Hyundai GF Holdings
- Hyundai Home Shopping/Hyundai GF Holdings ratio started out as high as 6.3x on 10 February. In the past several days, this ratio has drifted lower to about 5.9x.
- Merger ratio is 6.357x and there is an increasing probability that over the next several days the price gap between the two companies narrow back closer to the merger ratio.
- If Hyundai GF Holdings’ share price stays the same (until shares exchange date) and Hyundai Home Shopping catches up to the merger ratio, Hyundai Home Shopping could increase by 7.9%.
10. Accent Group (AX1 AU): Frasers’ On-Market Offer Is Less Opportunistic Than At First Glance
- Frasers Group (FRAS LN), footwear/clothing play Accent Group (AX1 AU)‘s largest shareholder (22.9%), has launched an on-market Offer at A$0.65/share, a zero premium to last close.
- Frasers has been on the scene since August 2024, when it acquired a 14.65% stake; then inked a 25-year strategic partnership in April 2025. And bumped its holding to 19.9%.
- Optically, $0.65/share appears a steal. Accent is down 73% from its December 2024 high. Yet Frasers raises legitimate concerns on, inter alia, Accent’s capital allocation priorities and the board’s remuneration.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Con Aero Tech (232 HK) Should (Almost) Double At The Bell
- After SOE-backed small plane engine maker Continental Aerospace Technologies (232 HK)‘s share price popped on the 26th May, it confirmed a possible sale that could have Takeovers Code implications.
- Late Friday (5th June) CAT confirmed it has entered into an SPA to sell its core business, potentially leading to a large cash distribution (HK$0.419-HK$0.436/share), and subsequent winding up.
- The SPA requires reg approvals and a Scheme-like vote. 46.4% of the register is supportive. Additional dividends expected from the sale of property. Get involved.
2. Merger Arb Mondays (08 Jun) – ENN, Con Aero, Skyworth, Kakaku, Shinko Shoji, Cygnus, Tourism Hldgs
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Continental Aerospace Technologies (232 HK), Skyworth (751 HK), ENN Energy (2688 HK), Qoria (QOR AU), Humm Group (HUM AU), Changhong Jiahua (3991 HK), Tourism Holdings (THL NZ).
- Lowest spreads: Australian Strategic Materials (ASM AU), Taiyo Holdings (4626 JP), Magnetic Resources Nl (MAU AU), Kakaku.com Inc (2371 JP), Emmerson Resources (ERM AU), Shinko Shoji (8141 JP).
3. Curator’s Cut: Memory’s Hold on the KOSPI, Counting Down to SpaceX & Iron Ore’s Cold Snap
- Welcome to Curator’s Cut – a fortnightly roundup of standout themes from the 1,500+ insights shared on Smartkarma. We’re back after a brief one-issue hiatus.
- In this cut, we revisit memory’s grip on the record-breaking KOSPI, count down to the record-setting SpaceX (SPCX US) IPO, and unpack cooling iron ore prices.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
4. StubWorld: Big Moves In “Kings”
- Yesterday, Kingboard (148 HK) gained 25% and ~67%-held Kingboard Laminates (1888 HK) 13%. Unrelated, Kingsoft (3888 HK) gained ~10% and 51.4%-held Beijing Kingsoft Office Software (688111 CH) just 0.9%.
- Preceding my comments on the “Kings” – are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
5. Con Aero Tech (232 HK): Q&A With The FA
- Back on the 5th June, SOE-backed Continental Aerospace Technologies (232 HK)‘s entered into an SPA to sell its core business, potentially leading to a substantial cash distribution.
- The SPA requires reg approvals and a Scheme-like vote. 46.4% of the register is supportive. Separately, additional dividends are expected from the sale of property. And possibly cash on hand.
- I had a number of questions concerning the transaction – as did many readers. This afternoon I pinned down a one-on-one with the FA to the Purchaser.
6. Con Aero Tech (232 HK): Q&A With The Other FA
- Back on the 5th June, SOE-backed plane engine maker Continental Aerospace Technologies (232 HK)‘s entered into an SPA to sell its core business, potentially leading to a substantial cash distribution.
- In Con Aero Tech (232 HK): Q&A With The FA, I discussed my one-on-one with the FA to the Purchaser.
- In this insight, I discuss my one-on-one with the FA to the Seller – or Con Aero Tech.
7. Nippon Sheet Glass (5202 JP): Widening Spread Ahead of the 26 June Vote
- On 24 March, Nippon Sheet Glass (5202 JP) outlined its restructuring plan to create a new NSG group. The minority cash-out price is JPY500. The AGM is on 26 June.
- The gross spread has increased to 6.4% due to heightened vote risk from the significant re-rating of peers and the decent FY2026 results on 11 May.
- However, the AGM vote remains low-risk as no activist has emerged, key shareholders are supportive, and the leverage remains precarious.
8. Nippon Dry-Chemical (1909 JP): Neuberger Starts an Activist Campaign, but Success Is Uncertain
- Neuberger issued a letter concerning the unfair terms of the Alsok (2331 JP) and Carlyle offer for Nippon Dry Chemical (1909 JP). The first closing date is 29 June.
- Neuberger, the second-largest shareholder, highlights six issues with the tender offer. While Neuberger’s criticisms have merit, the Board could credibly refute most of them.
- The probability of a bump is low, as Neuberger cannot block the tender, the offer is attractive on several measures, and ALSOK/Carlyle can use the playbook to counter activists.
9. Steadfast (SDF AU): Amwins’ (Possibly Opportunistic) A$6/Share NBIO
- As discussed in Steadfast (SDF AU): Suitors Circle As Share Price Languishes After Internal Complaint, insurance play Steadfast (SDF AU) was reportedly attracting PE interest, such as Blackstone.
- Steadfast has now entered into a process deal with Amwins and Dragoneer at A$6/share by way of a Scheme, a 51.9% premium to undisturbed.
- Amwins/Dragoneer have been provided with eight weeks of exclusive due diligence access. A firm Offer will requires FIRB and OIO signing off.
10. On James Hardie (JHX AU)’s Class Action Suit
- This morning (9th June), building products outfit James Hardie Industries Plc (JHX AU) announced a shareholder class action filing.
- The class action initiated by law firm Maurice Blackburn – see attached at bottom – currently involves seven group members.
- James Hardie is being accused of misleading the market, and the proceeding is brought on behalf of shareholders who acquired shares between 21st May 2025 and 19th August 2025.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
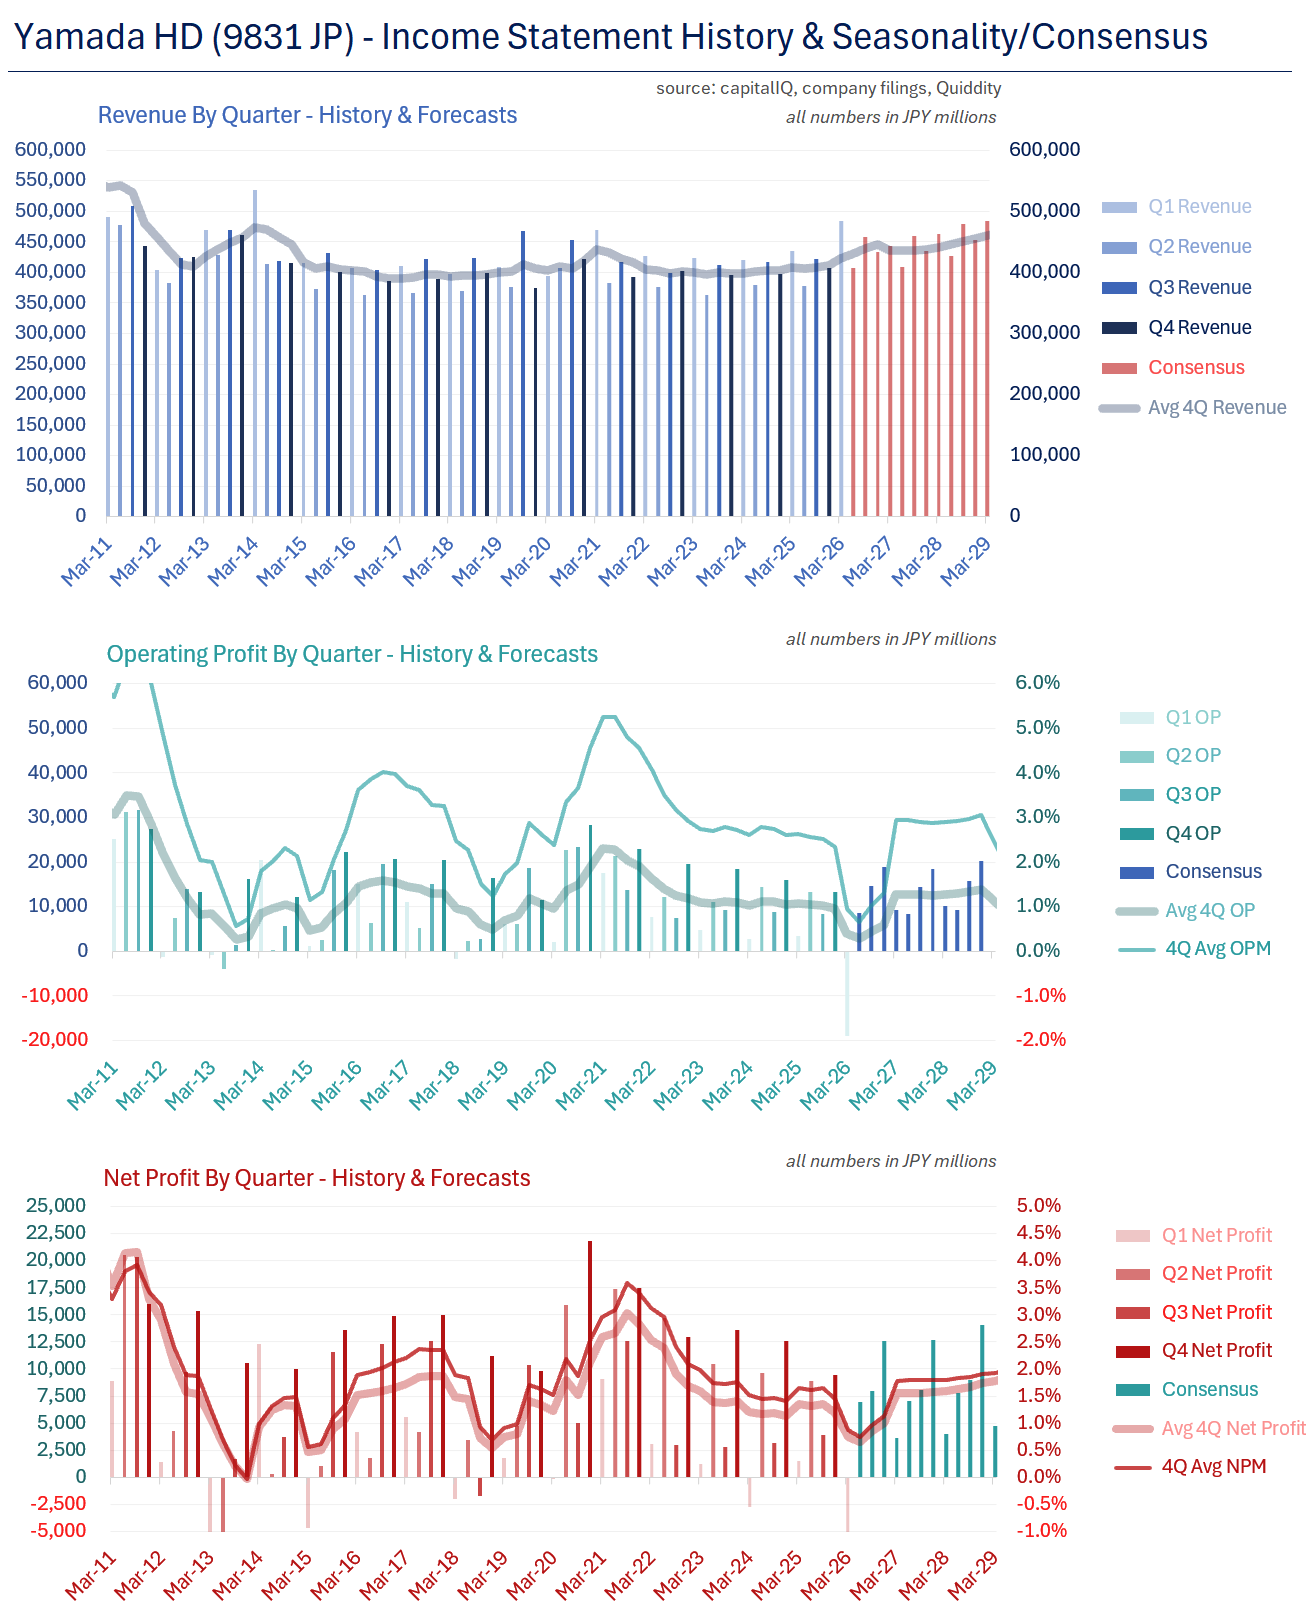
1. [Japan M&A] Yamada Denki (9831) And EDION (2730) Merger? Yamada Cheap But Weak Recent History
- Yamada Denki (9831 JP) is Japan’s top electronics retailer by sales. Edion Corp (2730 JP) is #5. The Nikkei carried an article last night saying they intended to merge.
- Both (Yamada, Edion) confirmed the talks, and board meetings set for tomorrow will likely approve path forward for negotiations. That’s not a done deal, but it gets definitive talks.
- Yamada has suffered mightily the last few years. Guidance this next year sees a rebound and on a forward basis, is cheap vs Peers (also cheap on a PBR basis).
2. Kakaku.com (2371 JP): Digital Garage Moves to Thwart Bain/LY
- On 4 June, the Nikkei reported that Digital Garage (4819 JP) will not accept Bain/LY (4689 JP)‘s higher offer for Kakaku.com Inc (2371 JP), as it is not feasible.
- Digital Garage’s reasoning is not credible. The most likely reason is that, unlike the EQT offer, Bain/LY are not allowing reinvestment to take a 20% stake in the offeror.
- While a setback, Bain/LY can succeed if it secures support from KDDI Corp (9433 JP) and Oasis. Irrespective of Digital Garage’s stance, EQT will likely need to bump to succeed.
3. [Japan Event] DeNA (2432 JP) – BIG Buyback, Asset Sale, Murakami Selling, but Squeeze Building?
- DeNA (2432 JP) announced a large buyback at end-Feb 2026. They also announced a sale of Nintendo shares and the day before, Murakami Group announced a drop in shareholdings.
- Shares were sold, the big buyback started. They were 8.4% of volume in March, 15.5% in April. Theoretically, the buyback goes to Feb2027. I expect it completes by end-July 2026.
- Mid-May 2026 DeNA announced it would sell shares in GO (581A JP) at IPO. At expected IPO price less 5%, that’s ¥36bn. Murakami is still selling.
4. MGM China (2282 HK): An MGO Based on the Chain Principle Is Not a Sure Thing
- On 1 June, MGM Resorts International (MGM US) confirmed that it had received an offer from People Incorporated (IAC) (IAC US) to acquire it for US$48.30 per share.
- MGM China (2282 HK) rose 7% due to the near-term possibility that the acquisition could trigger a mandatory general offer (downstream offer) and the long-term possibility of a privatisation offer.
- The triggering of an MGO based on the chain principle is not guaranteed, and the potential offer would be well below the last close. Nevertheless, MGM China’s valuation remains undemanding.
5. [Japan Buyback] Kawasaki Kisen/KLINE (9107) – Big Buyback Advanced in Size and Timing, More Later
- In mid-May 2026, Kawasaki Kisen Kaisha (9107 JP) said that in preparation for its next Mid-Term-Management-Plan starting next year, they allocated ¥50bn to a buyback, and ¥80bn more sometime later.
- On 29 May, KLINE decided “sometime later” meant now. They upped their buyback plan from ¥50bn to ¥130bn and started with a big ToSTNeT-3. Insiders agreed. They sold ¥50.7bn.
- The other ¥79.3bn/24.8mm shares will be bought in the market over four months. At current price, that’s ¥62bn. Expect more later.
6. Local Read Through on Samsung Special Dividend Sizing for This Year
- Samsung sticks to legacy record dates and is unlikely to adjust dividends intra year, with special returns typically confirmed only after earnings and FCF are effectively locked.
- Year end FCF driven special return setup is creating pre positioning flow and dividend arb via uncertainty and spot futures dislocation as market front runs mix.
- Mirae shows wide special dividend range with no Samsung guidance, while market consensus anchors FCF at 250 to 270 trillion implying 115 to 125 trillion for special plus buyback split.
7. Merger Arb Mondays (01 Jun) – Taiyo, Kodensha, Shinko Shoji, Atlas, Qoria, OOh!media, Tourism Hldgs
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), ENN Energy (2688 HK), Changhong Jiahua (3991 HK), Qoria (QOR AU), Humm Group (HUM AU), Tourism Holdings (THL NZ), European Lithium (EUR AU).
- Lowest spreads: Taiyo Holdings (4626 JP), Kakaku.com Inc (2371 JP), Magnetic Resources Nl (MAU AU), Nippon Dry Chemical (1909 JP), Matsuya R&D (7317 JP), Paltac Corporation (8283 JP).
8. Shinko Shoji (8141 JP): An Increasing Chance for a Bump as Murakami Exits
- On 15 May, Shinko Shoji (8141 JP) announced a tender offer from Kaga Electronics (8154 JP) at JPY1,580. While Murakami, the largest shareholder, provided an irrevocable, it could sell down.
- Murakami ceased to be a substantial shareholder by reducing its stake from 15.85% to 4.53% of the outstanding shares. There is a high probability that they are no longer shareholders.
- The Murakami entities disposed of the shares from 18 to 27 May when the shares were trading through terms, suggesting they were bought by one or more activists.
9. Diller’s Offer For MGM Resort Should Trigger A Downstream Offer For MGM China
- Barry Diller’s People Inc. is offering to buy MGM Resorts International (MGM US) at US$48.30/share. People Inc., formerly known as IAC, owns ~26.1% stake in MGM Resorts.
- MGM Resorts owns 55.95% in MGM China (2282 HK). A successful Offer should require People Inc to make a downstream Offer for MGM China; unless its obtains an SFC waiver.
- It should also kick off a regulatory vetting process by the Macau government on MGM China’s 10-year gaming concession.
10. Hynix Expiry Setup Spot Negative Both Roll and Non Roll, Key for Trades Vs Square
- Hynix futures open interest trends lower since June 2 with LPs still rolling exposure into next month, while aggressive daily rolls are pressuring Hynix spot and deepening front month backwardation.
- Desks are focused on non rolled size into next Thursday expiry, with potential forced unwind from long cash short futures setups driving spot selling and higher volatility risk.
- Hynix setup is spot negative into expiry in both roll and non roll cases, a key factor for structuring trades into next Thursday outright or relative value versus Square.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. A Wild First Day Trading for 2x Single Stock Leveraged Products for Samsung Electronics and SK Hynix
- In this insight, I discuss the wild trading of 2x single stock leveraged ETF products for Samsung Electronics (005930 KS) and SK Hynix (000660 KS) which were launched today.
- In particular, i focus on their trading volume, AUM, and share performances.
- In just one day, the AUM of the 2x single stock leveraged ETF products for Samsung Electornics and SK Hynix has jumped to 5.2 trillion won ($3.5 billion).
2. [Japan M&A] Kinden (1944) To Take Over Kodensha (1948) At HUGE UNBELIEVABLE AMAZING Price (¥11,501)
- Today after the close, Japan’s biggest electrical equipment construction co Kinden Corp (1944 JP) announced a deal to take over a smaller electrical equipment construction co Kodensha Co (1948 JP).
- Mitsubishi Electric (6503 JP) owns 51%. Other corporates own 7%. A few banks own a bit under 2%, then retail owns everything else. As of Mar2025, foreign investors held <1%.
- Shares rose sharply last year, and apparently a Nikkei article in January suggested they’d sell the asset. Shares popped on that. Well-flagged. (Inexplicably?) HUGE price. Big win for retail.
3. [Japan Event] Air Water (4088) – Small Picture Vs Big Picture
- Air Water Inc (4088 JP) was a problem stock because of accounting issues. Management got the boot. The TSE said “Security on Special Alert” three weeks ago.
- That meant it got the boot from various domestic indices and there were 30mm shares for sale. It turns out Murakami Group has bought half of that.
- Shares are +35% since the day after I wrote. Small picture, that brings PSR near its 8yr high. Big picture, EV/Revenue is half that of closest Japan comp Nippon Sanso.
4. Taiyo Holdings (4626 JP): Watching and Waiting as the Case for a Bump Gains Credence
- Since KKR & Co (KKR US) announced its preconditional tender offer for Taiyo Holdings (4626 JP) on 31 March, the shares have largely traded above the JPY4,750 offer.
- The case for a bump is gaining credence due to Taiyo’s better-than-expected results, significant peer rerating, the diminishing control premium and the irrevocables’ competing offer clauses.
- Nevertheless, KKR has no immediate cause for concern as no activist has emerged, and the market could sell off in the four months remaining before the offer opens.
5. [Japan Event] Carlyle and ALSOK Compete Then Join To Take Over NDC (1909) – ¥3,730
- ALSOK and Carlyle produced competing bids, overbid each other, then joined, then overbid themselves, to launch a TOB to buy fire safety company Nippon Dry Chemical (1909 JP).
- It’s a ten bagger since pre-covid and 10x forward EBITDA. It’s a decent outcome. But it’s trading through terms a week+ after announcement despite ALSOK+corps owning 50+%.
- While it is not impossible an activist digs their teeth in, this is long enough in the tooth that a strategic jumping in seems unlikely.
6. Merger Arb Mondays (25 May) – Kakaku, Nippon Dry Chem, Skyworth, Changhong Jiahua, Shengmu, Qoria
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), ENN Energy (2688 HK), Qoria (QOR AU), Changhong Jiahua (3991 HK), Humm Group (HUM AU), European Lithium (EUR AU), Atlantic Lithium (A11 AU).
- Lowest spreads: Kakaku.com Inc (2371 JP), Taiyo Holdings (4626 JP), Shinko Shoji (8141 JP), Nippon Dry Chemical (1909 JP), Magnetic Resources Nl (MAU AU), Toho Titanium (5727 JP).
7. Samsung FCF Estimate Factoring in Bonus Hit
- Despite KRW 37T headline cost, cash impact is mainly tax, so FCF drag is limited; street sees KRW 125T returns split into KRW 10T base dividend, 45T special, 70T buybacks.
- Implied DPS ~KRW 8300, ~3.6% SO retired; yields ~2.6% on commons and ~4.2% on prefs.
- Buybacks may skew prefs, pricing that optionality; with labor risk gone, focus shifts to returns, 37% pref spread and ~4% yield could drive yield rotation and spread compression.
8. I-Med: Jardine Matheson’s Big Push Into Digital Healthcare
- Jardine Matheson (JM SP) has agreed to buy a 100% stake in I-MED Radiology Network (I-MED) from Permira for A$3.4bn (US$2.4bn) in an all-cash deal.
- The outlay for the largest X-ray and medical scan provider in Australia, backs out 11.5x EBITDA for FY26E (June Y/E), excluding I-MED’s minority stake in Harrison.ai.
- The transaction remains “subject to customary closing conditions including regulatory approvals” – that should include FIRB – and is “expected to complete later in 2026“.
9. Atlas Arteria (ALX AU): The IE Says NOT Fair & Reasonable. All Eyes On Skyway’s Put Option
- A lot to unpack: the Panel declines IFM’s application; the Skyway ROFO has expired; and the Target Statement is now out – the IE says NOT fair and NOT reasonable.
- The ROFO expiration should come as no surprise. Nor should the IE conclusion. IFM’s independent directors previously issued a strongly worded rebuttal to IFM’s Offer.
- A key tenant of IFM’s Offer evolves around the Skyworth put option: would/will IFM waive the put condition; or Ontario Teachers’ Pension Plan (OTPP) irrevocably waives its right to put?
10. Atlas Arteria (ALX AU): Target’s Statement Makes Good and Bad Points
- The Atlas Arteria (ALX AU) target’s statement recommends rejecting IFM’s takeover offer. The IE opines that the offer is neither fair nor reasonable.
- The IE valuation range is A$5.39 to A$6.20 per share. IFM will have several reasons to take issue with the IE’s valuation, particularly relating to the Chicago Skyway.
- Despite the Board’s assertions, it could be commercially prudent for OTPP to waive the put option. It is also possible that IFM waives the maximum offer acceptance threshold.