
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
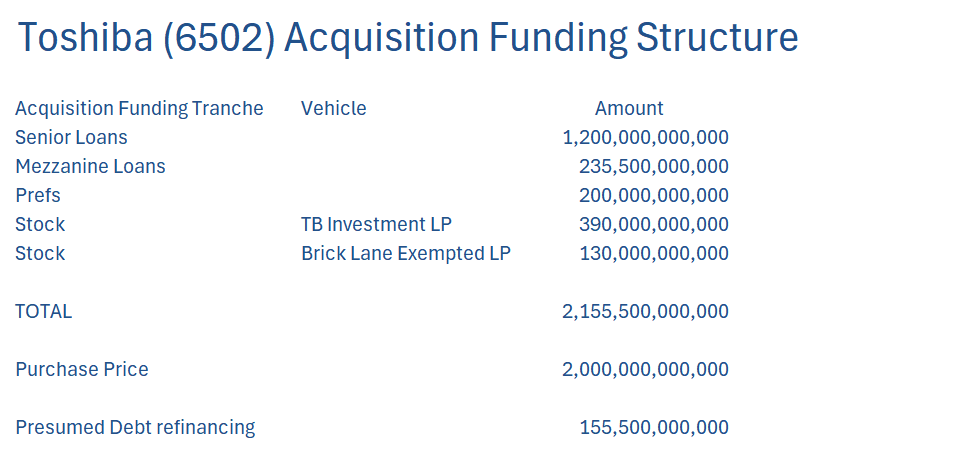
1. [Japan Navel-Gazing] Thinking About The Value of Toshiba
- Toshiba was taken over in late 2023 by a consortium led by local PE firm Japan Industrial Partners. The official takeover price was ¥2.0 trillion.
- That was financed by ¥1.2trln of senior lending, ¥200bn of prefs, ¥520bn of equity, and ¥235.5bn of mezzanine finance which meant net debt on Day1 was likely about ¥1.1trln.
- EBITDA was ¥180bn in Mar24, ¥338bn in Mar25, and ¥482bn in Mar26. Things are improving. And Toshiba held Kioxia shares. That’s gone well too. How well? Look inside.
2. [Japan Event] Rakuten Fintech Group Restructuring – Dirty Deeds Done Unto Rakuten Bank (5838)
- Today post-close, Rakuten Bank (5838 JP) and Rakuten (4755 JP) announced the Fintech Restructuring. “Fintech” is a stretch. It’s an e-bank and an e-broker with a credit card company.
- There are likely a lot of synergies, but this may be a bad deal for Rakuten Bank shareholders. They are paying much more for the synergies than the others are.
- Rakuten Bank contributes 55.4% of the last four quarters of NEWCO OP, but get only 43% of the shares in NEWCO. Securities+Card OP is 30% “stronger” than Bank OP.
3. Samsung Labor Deal: Detailed Structure and Stock Impact Breakdown
- Stock based bonus with lockup removes overhang, supports tape. OP hurdle intact at KRW 200 trillion, no OP no payout, reinforcing growth narrative and downside support.
- Bonus tied to separate KPI set later, not OP or EVA, pushing dispute out. Strike risk gone, union leverage weak, mgmt likely controls KPI design.
- Mgmt to announce ~KRW 30 trillion buyback given limited treasury stock. Likely bundled with shareholder returns, driving front running flows and near term upside, especially in prefs.
4. [Japan Event] Rakuten Bank (5838) – “Exciting” Mizuho News Doesn’t Do Much But Expect More News Soon
- A weekend report suggested Mizuho Financial Group (8411 JP) might invest in Rakuten Bank (5838 JP) when a Rakuten Financial Group is formed. They own 14.99% of Rakuten Card.
- The story suggested Mizuho would swap that stake for a stake in Rakuten Bank. Mizuho Securities (which eclipsed Daiwa Securities last year) would keep its 49% stake in Rakuten Securities.
- This un-complicates things slightly, and suggests earlier analysis was roughly right. Rakuten Bank jumped 10%. It’s up again today. Expect a decision on Rakuten FG this month.
5. NIKKON Holdings (9072 JP): Thoughts on a Potential Privatisation Offer
- On 20 May, Bloomberg reported that Nikkon Holdings (9072 JP) is considering going private and preparing to hold a first-round bidding round in early June.
- The shareholder structure is conducive to a privatisation bid as two activists (Farallon and Oasis) hold 51.6 million shares (44.23% ownership ratio).
- Bain Capital, Warburg Pincus and Blackstone are expected to take part in the auction. My analysis suggests an offer price of at least 6,200 (7.4% above the last close).
6. My Take on What Is Driving the KOSDAQ Tape Today
- National Growth Fund retail opened today, KRW 720bn first tranche, next in H1 next year. KOSDAQ move is sentiment driven on strong demand chatter this morning, not actual inflows.
- Blaming a 5 percent KOSDAQ move on this alone is a stretch; it is short covering in battery and biotech plus KOSPI to KOSDAQ rotation on a policy signal.
- 5% KOSDAQ move is placebo causality flip; fund hype only catalyst for rotation tape. Key call is durability vs normalization, I lean fade as flows and positioning reset.
7. CR Power (836 HK): CSRC Clears Clean Energy Spin-Off
- A fortnight after the Shenzhen Stock Exchange approved SOE-backed power play China Resources Power (836 HK) (CRP)’s A-share listing of its renewable energy unit, CSRC approval is now satisfied.
- The process has taken over three years. Since that time, CRP’s earnings and attributable installed capacity, is now evenly split between its thermal and renewable energy segments.
- With CSRC and SZSE approvals in the bag, the final stretch should move relatively quickly.
8. Flow Cannibalization Trade Setup Around Samsung and Hynix Leveraged ETF Listings
- Focus is on rotation from semi leveraged ETFs, about KRW 700bn to 1tn in 5 days, mainly cannibalizing KODEX and TIGER which proxy Samsung and Hynix leverage.
- Better trade is smaller names, not Samsung or Hynix. Futures likely take heavy sell pressure post listing, driving outsized basis blowout and spot futures dislocation versus turnover.
- Screen names are Hanmi, Leeno, Wonik IPS, EO Technics, ISC. Expect 1 to 1.3x futures sell flow. Play via cash shorts or basis on backwardation.
9. Merger Arb Mondays (18 May) – ENN, Skyworth, Tohoku, Shinko Shoji, Kakaku, Taiyo, Qoria, OOh!media
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Tohoku Steel (5484 JP), Skyworth (751 HK), Qoria (QOR AU), ENN Energy (2688 HK), European Lithium (EUR AU), Changhong Jiahua (3991 HK), Humm Group (HUM AU).
- Lowest spreads: Kakaku.com Inc (2371 JP), Taiyo Holdings (4626 JP), Australian Strategic Materials (ASM AU), Toho Titanium (5727 JP), Vault Minerals Ltd (VAU AU), Nippon Dry Chemical (1909 JP).
10. [Japan Event] Kosaido (7868) – Death Had a Bad Year in FYMar26 but It’s a Growth Business
- Kosaido (7868 JP) used to be a stationer and printing business. Printing has been a bad business for decades. But the company also has a large funeral parlour business.
- That business dominates Operating Profits and Assets. Years ago, the CEO tried to MBO it cheaply. Murakami intervened, others bought afterwards, and a few large holders dominate this illiquid stock.
- Today, speculative/investigative media outlet FACTA reported that Kosaido might sell its funeral parlour business. PE funds are reportedly interested. That would create a huge pile of cash but what then?
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
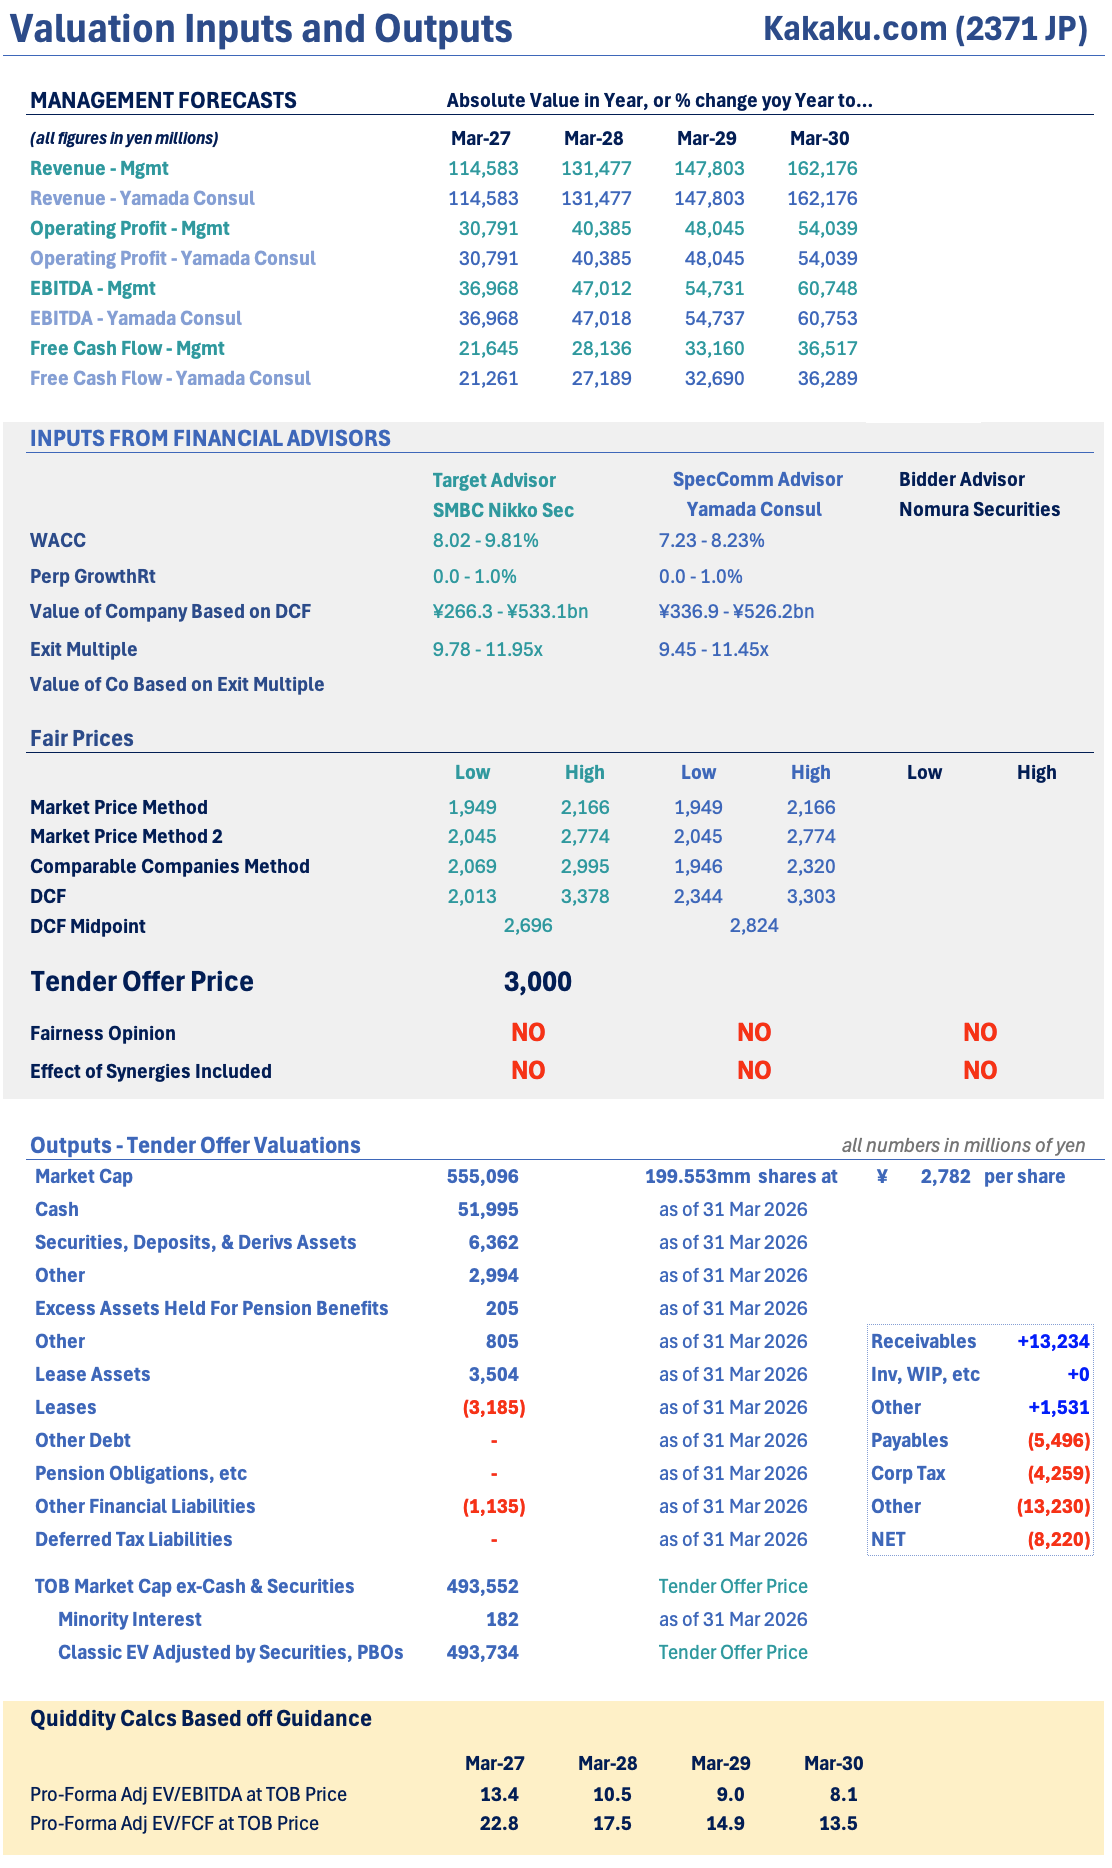
1. [Japan M&A] EQT Launches TOB on Kakaku.Com (2371) But This Isn’t A Done Deal
- Just under 3 weeks ago, Reuters carried an article saying EQT was considering making a bid for Kakaku.com Inc (2371 JP). The stock popped, then drifted higher.
- Today, that bid was launched. Kakaku.com agreed, supports, and recommends at ¥3,000 which is about 10x Adjusted EV/EBITDA for March 2028. Not super rich with such high growth.
- Digital Garage+KDDI own 38% between them. Oasis owns 19%. There are fiduciary out clauses and the docs note that Bain+LY Corp brought in a last minute bid. This isn’t done.
2. Kakaku.com (2371 JP): Pass the Popcorn as EQT Launches a Tender Offer
- Kakaku.com Inc (2371 JP) has recommended a tender offer from EQT (EQT SS) at JPY3,000, a 2.6% premium to the last close and a 41.4% premium to the undisturbed price of JPY2,121.
- At first glance, the offer is attractive compared to historical trading ranges and IFA peer multiples, and it is above the midpoint of the IFA DCF valuation range.
- The conspicuous lack of Oasis’s support, the absence of an auction despite a Bain/LY bid, reliance on passives’ vote and irrevocables with competing offer clauses suggest a bump is probable.
3. [Japan M&A] Nisshin Shoji “MBO” Is An Exercise in Offensively Bad Board Negligence
- Today post-close, Nissin Shoji (7490 JP) – gasoline retailer and energy company affiliated with ENEOS Holdings (5020 JP) – announced the Tsutsui family would conduct an MBO at ¥2,210.
- That’s a 60% premium, which looks nice, but book value is 185% higher than today’s close. Most of the Adjusted EV is receivables and inventory.
- The remaining assets are about ¥10-14bn worth of market value of real estate. All told, this is probably worth ¥3,500+ to the right person.
4. [Japan M&A] Medipal (7459) Takes Out OTC Drugs Wholesaler Sub PALTAC (8283) At ATH – Not Bad
- Today after the close, Medipal Holdings (7459 JP) announced it would take out minorities in its Paltac Corporation (8283 JP) subsidiary which wholesales OTC drugs, personal care, etc.
- Paltac is a high-turnover low margin product jockey. Medipal is the parent with too much cash. This works. And it gets minorities out of low-beta “quality” at a 43% premium.
- This looks like it gets done. ¥100bn+ of Max Real World Float for arbs to buy.
5. Paltac (8283 JP): MediPal (7459 JP)’s Attractive Tender Offer
- Paltac Corporation (8283 JP) has recommended a tender offer from Medipal Holdings (7459 JP) at JPY6,650, a 43.2% premium to the last close.
- The offer is attractive as it represents an all-time high and is above the midpoint of the special committee and target IFA’s DCF valuation range.
- The required tendering rate is achievable due to an attractive offer. This is a done deal. The first closing date is 7 July, with payment commencing 14 July.
6. Kakaku.com (2371 JP): How High Can It Go as Bain/LY Ups the Ante?
- On 13 May, Bain/LY (4689 JP) sent Kakaku.com Inc (2371 JP) a revised non-binding offer at JPY3,232, a 7.7% premium to EQT’s JPY3,000 offer but 4.9% below the last close.
- While remaining non-binding, the Board will be forced to engage under its fiduciary-out clause and Digital Garage (4819 JP) and KDDI Corp (9433 JP)’s competing-offer clauses.
- Bain/LY’s second offer, belatedly and publicly, sets in motion an auction process. My analysis suggests that a competing bidding war could result in an offer of at least JPY3,500.
7. Baoye (2355 HK): Unusual Activism Which Could Be a Template for Dealing with Cash Hoards
- On 8 May, Baoye Group (2355 HK) received a resolution for a special dividend of HK$5.50, which was proposed by a shareholder (representing 1.02% of the outstanding shares).
- The special dividend represents a 40.7% premium to the undisturbed price. The management opposes the resolution and has the votes to block the resolution at the 18 June AGM.
- The proposal shines a light on the Board’s poor capital allocation of the HK$12.58 net cash. Near-term, it also increases the odds of a privatisation proposal from the Chairman.
8. Scenario Development for the Samsung Union Situation
- OPI capped at 50 percent, DS only pool up to 12 percent of operating profit, conditional on top rank in revenue and EBIT, non guaranteed funding pool structure.
- Even if injunction fails, government likely triggers emergency arbitration to block strike. Samsung rejects fixed OP based bonus; focuses on time buying and maintaining flexible cyclical compensation structure.
- Expect drawn out process with incremental engagement, union fragmentation pressure, and no clean positive catalyst for stock. Overhang remains sticky. Base case is 21st strike avoided, supporting downside.
9. Merger Arb Mondays (11 May) – Altas, European Lithium, Atlantic Lithium, Vault, Emmerson, Shengmu
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth (751 HK), Qoria (QOR AU), European Lithium (EUR AU), ENN Energy (2688 HK), Changhong Jiahua (3991 HK), Humm Group (HUM AU), oOh!Media Ltd (OML AU).
- Lowest spreads: Australian Strategic Materials (ASM AU), Taiyo Holdings (4626 JP), Sankei Real Estate (2972 JP), Toho Titanium (5727 JP), E’grand Co Ltd (3294 JP), Global Ltd/The (3271 JP).
10. Digital Garage (4819 JP) Is Cheap As LY & EQT Jostle For Kakaku (2371 JP)’s Control
- On the 12th May, Kakaku.com Inc (2371 JP) recommended EQT’s Offer at ¥3,000/share. The docs flagged Bain+ LY (4689 JP) had also brought in a last minute bid
- On the 14th May (today), LY announced it had submitted an initial bid at ¥3,232/share, contingent on due diligence being granted and passed.
- Kakaku is potentially worth ~¥ 3,700/share, and is currently trading at ~¥ 3,400. Still some gas in the tank. Separately, I’d also run a ruler over Digital Garage (4819 JP).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
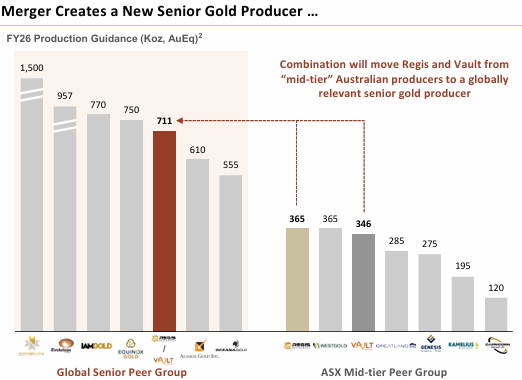
1. Regis Resources (RRL AU) & Vault Minerals (VAU AU) To Merge: Multiple Index Flows
- Regis Resources (RRL AU) and Vault Minerals Ltd (VAU AU) are combining in an all-stock merger of equals to create a new senior gold producer.
- Vault Minerals Ltd (VAU AU) shareholders will receive 0.6947 shares in Regis Resources (RRL AU) for each Vault share held.
- The merger will have implications for the stocks in the S&P/ASX, thematic, and other global indices at the time of implementation.
2. Flow Dynamics in Seed Window for 2x Leveraged Samsung and Hynix ETFs
- Street focused on seed size into first Korea multi single name 2x ETF launch. Samsung Mirae ~KRW100bn others KRW20bn to 50bn total KRW300bn to 400bn per underlying.
- PDF is cash plus futures one-to-one. T minus three seed window implies ~KRW100bn daily. Spot impact muted. Watch futures into May 21 close with ~KRW400bn notional likely driving short-term impact.
- Samsung versus Hynix pair is key post listing trade driven by Hynix skew. That said, also focus on pre-positioning into ~KRW400bn futures buying into May 21 close targeting contango widening.
3. Vedanta (VEDL IN) Demerger: Index Implications (What Stays, What Goes, When & Size)
- Vedanta Ltd (VEDL IN) has demerged into 5 entities to unlock value through separate strategies and the removal of the holding company discount.
- Vedanta Ltd (VEDL IN) is a member of the global indices, NSE Nifty Next 50 Index (NIFTYJR INDEX) and the demerger has index implications.
- The timing of the listing of the demerged entities and the passive flows that follow will create trading opportunities.
4. Regis Resources (RRL AU) & Vault Minerals (VAU AU) Claim Each Other
- Gold fever continues down under as Regis Resources (RRL AU) and Vault Minerals Ltd (VAU AU) announce a A$11bn merger, creating the ASX’s third largest gold miner.
- By way of a Scheme, Regis is offering 0.6947 new shares for each Vault share. Post merger, Regis and Vault shareholders will hold 51% and 49% in the combined entity.
- Both boards unanimously back the transaction, which is projected to complete late August, early September. Clean deal.
5. Guoco (53 HK): Still Deep Value. Still Illiquid
- I see Guoco Group Ltd (53 HK)‘s implied stub at around a decade low. And a trailing P/B of 0.34x, versus the five-year average of 0.4x.
- ~67%-Held GuocoLand (GUOL SP) (trading at 0.64x P/B) looks set to privatise ~68%-held Guocoland Malaysia (GUOL MK) at ~0.55x P/B, further adding to Guoco’s look-through “cheapness”.
- It’s coming up to eight years since the Quek family last attempted to take Guoco private. I can see the family stepping up here.
6. Merger Arb Mondays (04 May) – ENN, Skyworth, European Lithium, OOh!media, Atlas, Humm, Taiyo
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), European Lithium (EUR AU), Qoria (QOR AU), ENN Energy (2688 HK), Humm Group (HUM AU), Changhong Jiahua Holdings (3991 HK).
- Lowest spreads: Taiyo Holdings (4626 JP), Magnetic Resources Nl (MAU AU), Toho Titanium (5727 JP), SOLASTO CORP. (6197 JP), Sankei Real Estate (2972 JP), Global Ltd/The (3271 JP).
7. Court Injunction Outlook on Samsung Union Strike Risk and Key Factors Driving the Decision
- Street leans pro management after Supreme Court of Korea ruled OPI non wage, classifying it as EVA driven profit distribution, while TAI is recognized as wage.
- With Supreme Court of Korea ruling OPI is not wage, union argument is weak and court likely not taking a narrow view on the injunction.
- Street sees pro corporate stance under Lee Jae-myung with election sensitivity, limiting shock risk, so Samsung union strike likely not a major headwind for near term semiconductor rally.
8. Guocoland Malaysia (GUOL MK): IA Opines NOT Fair but Reasonable; Vote on 29 May
- The Guocoland Malaysia (GUOL MK)/GLM IA has opined that GuocoLand (GUOL SP)’s RM1.10 offer is NOT fair but reasonable. The IA values GLM at RM2.96 per share.
- The key conditions are the headcount test (majority in number) and the value test (approval by at least 75% of disinterested shareholders, with rejection by <10% of all disinterested shareholders).
- Due to the lack of a blocking stake and the Board’s recommendation that shareholders vote YES, the vote remains low-risk. The gross/annualised spread for an end-of-July payment is 2.8%/12.0%.
9. GuocoLand Malaysia (GUOL MK): 29th May Vote On Delisting Offer
- Back on the 3rd Feb 2026, property developer GuocoLand Malaysia (GUOL MK) (GMB) announced GuocoLand (GUOL SP), its controlling shareholder, intended to delist the company via a selective capital reduction.
- GuocoLand offered RM1.10/share in cash, a 17.65% premium to last close; but more like >80% to undisturbed. GuocoLand and concert parties hold 67.93% of shares out.
- The Circular is now out, with an EGM on the 29th May, and expected “implementation” late July. The IA (Kenanga) concluded “NOT fair, BUT reasonable“, and to “vote in favour“.
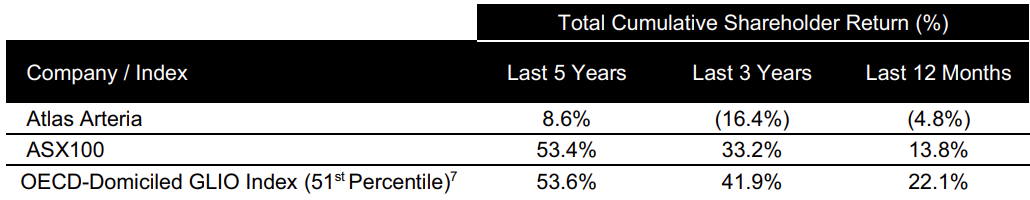
10. Atlas Arteria (ALX AU) Stomps On IFM’s “Opportunistic” Offer
- After IFM launched a A$4.75/share offer for Atlas Arteria (ALX AU), increasing to A$5.10/share IF it secures 45%, I thought Atlas may reject terms, but ultimately would be supportive.
- I was wrong. In a strongly worded rebuttal, Atlas has declared the Offer to be too low, opportunistic, and highly conditional.
- Specifically, Altas unpicks the conditions to the Offer which “seek to constrain Directors and management from running the business“.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Atlas Arteria (ALX AU): IFM Makes Its Move
- On the 8th June 2022, IFM Global Infrastructure announced a 15% stake Atlas Arteria (ALX AU), a US/Europe toll-road play, and subsequently floated a NBIO, which ultimately came to nought.
- IFM continued to accumulate shares, and on the 17th November 2025, announced it had added 2.48%, and held 35.03%.
- IFM has now launched a A$4.75/share Offer cash Offer, increasing to A$5.10/share (best & final) IF it secures 45%, or more, of shares out. Atlas may still reject terms.
2. Sankei Real Estate (2972 JP): Murakami Adds as Tosei/GIC Goes for Broke
- Tosei Corp (8923 JP)/GIC is attempting to use the Bain/MCJ playbook by indicating that the Sankei Real Estate (2972 JP) price and closing date (18 May) are final.
- However, Tosei/GIC is unlikely to repeat Bain’s success, particularly given that Murakami entities’ filing today shows that its ownership increased to 22.75%.
- It is likely the tender will fail. Murakami is likely looking to initiate an auction for all or part of Sankei RE post-deal break, replicating the FMH real estate auction.
3. Kakaku.com (2371 JP): Thoughts on a Potential EQT Privatisation Offer
- On 23 April, Bloomberg reported that EQT (EQT SS) is considering a takeover of Kakaku.com Inc (2371 JP), resulting in the last close being 29.7% above the undisturbed price.
- The shareholder structure is conducive to a privatisation bid. The three substantial shareholders would entertain an attractive offer, despite having differing end goals.
- The Bloomberg article did not disclose the potential offer price. My analysis suggests an offer price around JPY3,000, 9.1% above the last close.
4. Atlas Arteria (ALX AU): Patience Runs Out as IFM Launches a Takeover Offer
- IFM has launched an off-market takeover offer for Atlas Arteria (ALX AU) at a base consideration of A$4.75, which will increase to A$5.10 if IFM holds 45% stake.
- The offer is subject to several conditions. The waiver of third-party rights related to the change of control condition is the most problematic.
- The maximum offer is the best and final. While the Board is likely to recommend that shareholders reject the offer, the maximum offer’s acceptance threshold can still be satisfied.
5. European Lithium (EUR AU): Critical Metals (CRML US) Firms Reverse Takeover
- European Lithium (EUR AU)‘s ~34.4% held Critical Metals (CRML US) has announced a non-binding reverse takeover via a Scheme scrip deal.
- CRML intends to issue 0.035 new CRML shares for each EUR share. The implied value per CRML scrip is A$0.58/share. EUR shareholders will hold ~45% of the combined entity.
- A completed merger sees 100% of Tanbreez Rare Earth project under one roof. Exclusive due diligence to run until around the 7th May. EUR is up 53% as I type.
6. Creation of Hanwha Machinery & Service Holdings, Impact on Galleria and Vision, & NAV of Hanwha Corp
- Hanwha Group plans to create a new holding company called Hanwha Machinery & Service Holdings which will be headed by Kim Dong-Sun (third son of Hanwha Group Chairman Kim Seung-Yeon).
- The newly established entity will be incorporated on 1 August (the spin-off date). The listing date for Hanwha Machinery & Service Holdings is 25 August.
- My NAV valuation of Hanwha Corporation (000880 KS) is 238,189 won which is 81% higher than current price.
7. European Lithium (EUR AU): Reverse Takeover?
- European Lithium (EUR AU), which holds a (estimated) ~34.4% stake in Critical Metals (CRML US), the mining operator of projects in Austria, Greenland, and Ireland, is currently suspended.
- The rumour mill suggest CRML will make an offer for its parent. CRML recently received government approval to control 92% of the Tanbreez rare earths project in Greenland
- Those same rumours are indicating a A$0.58/share, or a 104% premium to European Lithium’s last close.
8. Merger Arb Mondays (27 Apr) – Makino, Skyworth, ENN, Changhong Jiahua, Qoria, Qube, Emmerson
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), Qoria (QOR AU), ENN Energy (2688 HK), Humm Group (HUM AU), Changhong Jiahua Holdings (3991 HK), China Shengmu Organic Milk (1432 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Australian Strategic Materials (ASM AU), Taiyo Holdings (4626 JP), Makino Milling Machine Co (6135 JP), Magnetic Resources Nl (MAU AU).
9. Asia-Pac M&A, April 2026 Wrap: Atlas Arteria, European Lithium, OOh!Media, Global Ltd, Taiyo Holding
- For April 2026, 8 new transactions (firm and non-binding) were discussed on Smartkarma (by the Quiddity team) with an overall announced deal size of ~US$7bn.
- The average premium for the new transactions announced (or first discussed) in April was ~56%, and a year-to-date average of 45%.
- The average premiums for transactions in 2025, 2024, 2023, 2022, 2021, 2020, and 2019 were 49%, 43%, 39%, 41%, 33%, 31%, and 31%.
10. OOh!Media (OML AU): PEP’s Opportunistic Tilt
- OOh!Media (OML AU), the No.1 player in Australia’s outdoor advertising, has announced an NBIO, by way of a Scheme, from PE-outfit Pacific Equity Partners (PEP).
- Subject to completion of satisfactory DD, PEP is offering A$1.40/share, a 65% premium to last close. Apart from shareholder approval, the transaction requires FIRB and NZ’s OIO signing off.
- OML’s share price was down 35% YTD. Tony Faure recently stepped down as Chair. CEO James Taylor assumed the role just five months ago. Yes, timing is opportunistic.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A] Japan Govt Quashes MBK Bid for Makino Milling (6135) – Foreign Buys of Sensitives Toast?
- When Makino Milling tried to block Nidec’s bid but Nidec ran into approvals risk, and MBK stepped in as an alternate bidder.
- The fact that Nidec seemed to run into China approval problems but MBK did not perhaps should have been something of a warning. Delays in Japan approvals definitely were.
- Now the Japanese government has asked MBK to withdraw citing national security concerns according to the Nikkei. First post-New-FEFTA deal block.
2. Samsung Electronics: Rising Narrative Around a Preferred-Only ADR Structure
- Labor standoff and strike risk push ADR onto the table. Preferred-share ADR avoids dilution, taps US income demand, and strengthens leverage vs union without ceding Samsung Group control.
- ADR isn’t only union-driven; CAPEX seen undersized for AI vs SK Hynix. Larger fab spend likely forces US market access; governance tradeoffs increasingly repriced and acceptable.
- Samsung likely waits to see SK Hynix ADR execution; 2H call unlikely. But preferred-ADR narrative may leak gradually, supporting FCF-driven preferred outperformance into year end.
3. Makino Milling Machine (6135 JP): Precedent Set as FEFTA Approval Is Rumoured to Be Not Forthcoming
- The Nikkei reported that the Japanese government has advised MBK to halt its acquisition of Makino Milling Machine Co (6135 JP) on national security grounds.
- This event sets a precedent and will increase the risk premium for foreign takeovers of Japanese companies in core business sectors. FEFTA approval can no longer be considered low-risk.
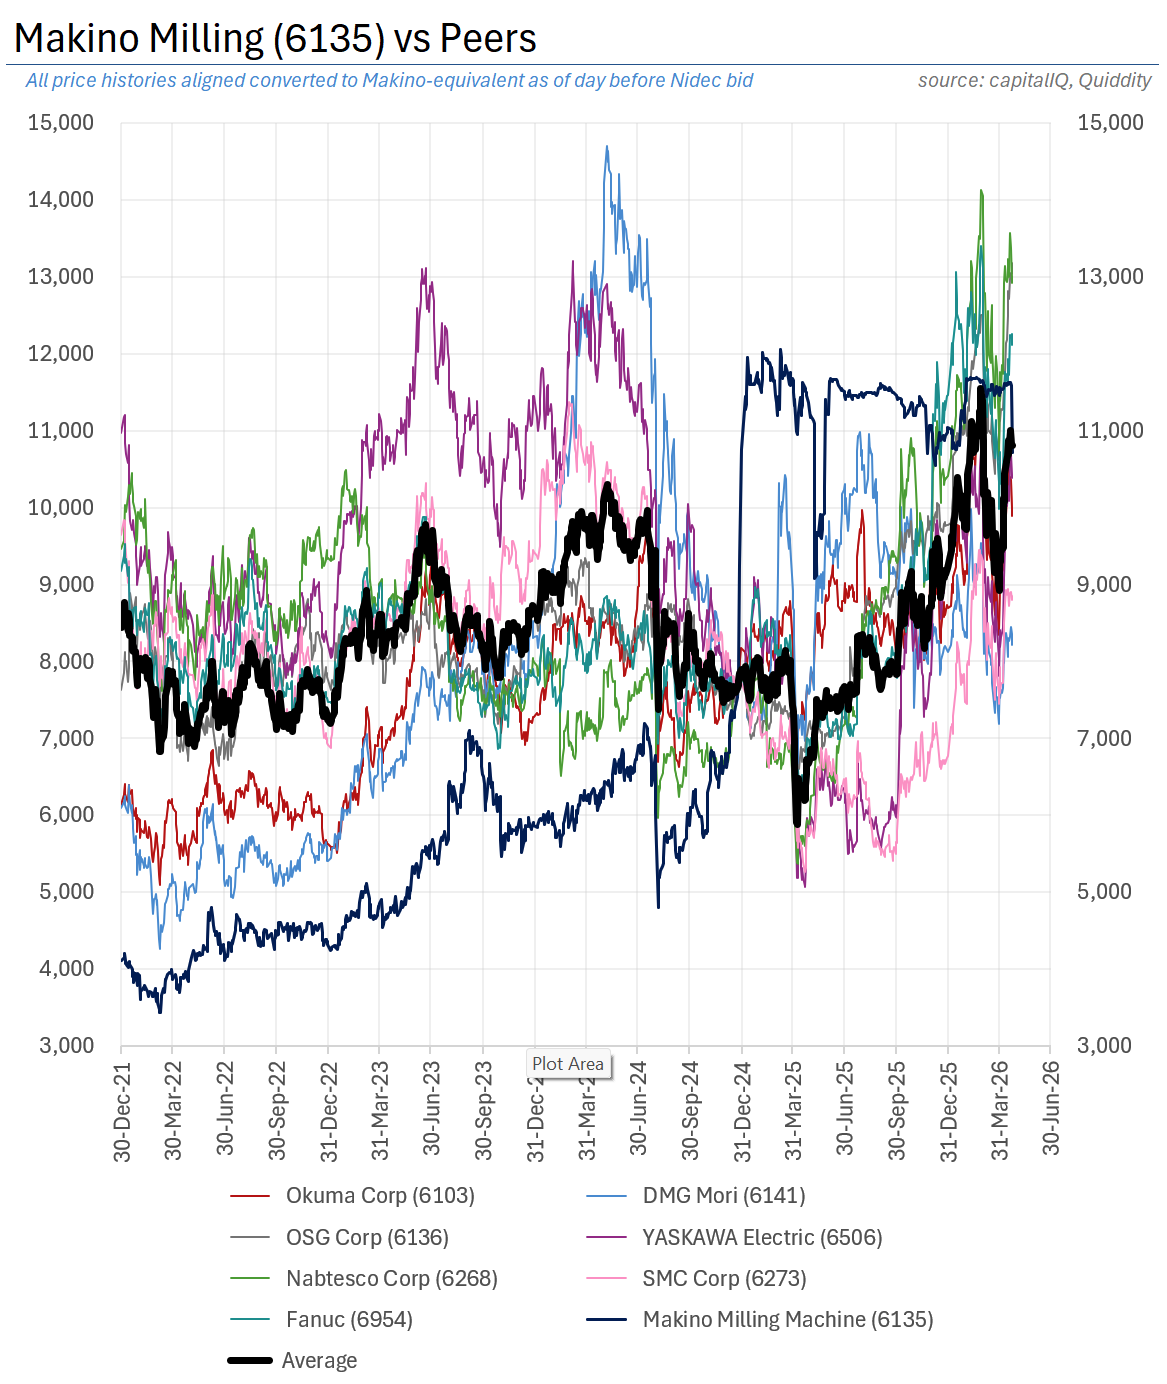
- Due to a significant re-rating of peers/index and Makino’s upgraded forecasts since the offer announcement, the share price fall on a deal break is likely to be modest (<10%).
4. Estimating Alteogen’s KOSDAQ Delisting Driven Passive Outflows Using KOSCOM Data
- KOSDAQ→KOSPI transfers have never seen KQ150 outflows near 4% of market cap. No trading halt means ETFs must fully unwind pre listing, creating a concentrated one day sell flow shock.
- Offsetting KOSPI inflows are delayed due to 15 day market cap screening and uncertain fast track inclusion, likely pushing KS200 demand into December rebalance, creating a 2-month passive mismatch window.
- KQ150 ETFs face about 2.2 million share sell, roughly 6.8x ADV, top tier passive flow. Expect pre positioning, then elevated volatility on rebalance, with downside bias into the event window.
5. Makino Milling Machine (6135 JP): A Rollercoaster Ride as NSSK Rumoured to Launch a Competing Bid
- Makino Milling Machine Co (6135 JP) shares fell 8.8% after it confirmed the Nikkei report that the Japanese government has advised MBK to halt its acquisition on national security grounds.
- However, after market close, the Nikkei reported that Nippon Sangyo Suishin Kiko (NSSK), a Japanese investment company, plans to make a higher competing tender offer.
- While the NSSK offer will be preconditional on regulatory approvals, it will not require FEFTA approval. I estimate the NSSK potential offer to be between JPY12,500 and JPY13,000.
6. [Quiddity Index] MV Global Gold Miners Jun26: Five ADDs Possible; US$1.2bn+ One-Way Flows
- The MV Global Gold Miners index represents the performance of large and mid-cap gold and silver global mining companies. We expect 2-3 ADDs on average each quarter.
- Based on the latest data, we now see five ADDs in June 2026 and we have a little over a month to the base date.
- We expect one-way flow of US$1.2bn for the June 2026 rebal.
7. Changhong Jiahua (3991 HK): What’s Up (Or Down To Be Precise)?
- Back on the 22nd September 2025, SOE-backed Sichuan Changhong Electric Co, Ltd. (600839 CH) made an Offer, by way of a pre-conditional Scheme, for 60.13%-held Changhong Jiahua Holdings (3991 HK)
- Sichuan Changhong, plus provincial bodies, offered HK$1.223/share, a 32.93% premium to last close. The Offer Price is final. And optically is fair.
- City level SASAC has been squared away. Provincial reg clearances outstanding (& tardy), which may be due to governmental personnel changes, and the approval process straddling Chinese New Year.
8. [Japan M&A] – Denso Withdraws Rohm (6963) Takeover Proposal – Now It’s Just Value
- The Nikkei reported Saturday morning that Denso Corp (6902 JP) will withdraw its takeover proposal for ROHM Co Ltd (6963 JP).
- The question was always whether Rohm thought being taken over was good for corporate value or if Denso would go hostile. We now know the answer to both questions.
- Now we are left with Rohm and its standalone value, and the value of being bigger in power semiconductors.
9. Qube (QUB AU): 16th June Vote On MAM’s Scheme
- On the 16th February, logistics and infrastructure play Qube Holdings (QUB AU) announced the Macquarie Asset Management-led consortium had firmed an Offer at A$5.20/share, the same price as the NBIO.
- Terms back out a 27.8% premium to undisturbed. And ~14.5x FY25 EV/EBITDA. Fully franked dividends up to A$0.40/share permitted, but will be netted. An $0.0535/share interim dividend has been paid.
- The Scheme Booklet is now out, with a Scheme Meeting on the 16th June, and expected implementation on the 28th July 2026. The IE (Grant Samuel) says “fair & reasonable“.
10. IDX’s Bubble Stocks: Enhanced Reporting Regs Partly Address Investability Concerns
- As part of a new transparency drive – predicated on MSCI concerns – Indonesia’s IDX flagged nine companies with a high shareholder concentration. All with lofty outperformances to match.
- The list included Indo’s third largest market cap company, coal producer Dian Swastatika Sentosa (DSSA IJ), with an eye-watering trailing PER of 136x. DSSA is backed by the Widjaja family.
- Barito Renewables Energy (BREN IJ), Indo’s second-largest company, also made the cut. I’ve previously flagged this bubble stock in StubWorld: Barito Renewables (BREN IJ) – This Too Shall Pop.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. CATL (3750 HK): Implications of Potential US$5bn Offering
- CATL (3750 HK) listed in May 2025 by selling 135.579m shares at HK$263/share. The overallotment option of 20.337m shares was also exercised fully. The stock is up 151% since then.
- Media reports indicate that CATL (3750 HK) could use the recent runup in the stock price to raise up to US$5bn in a share sale.
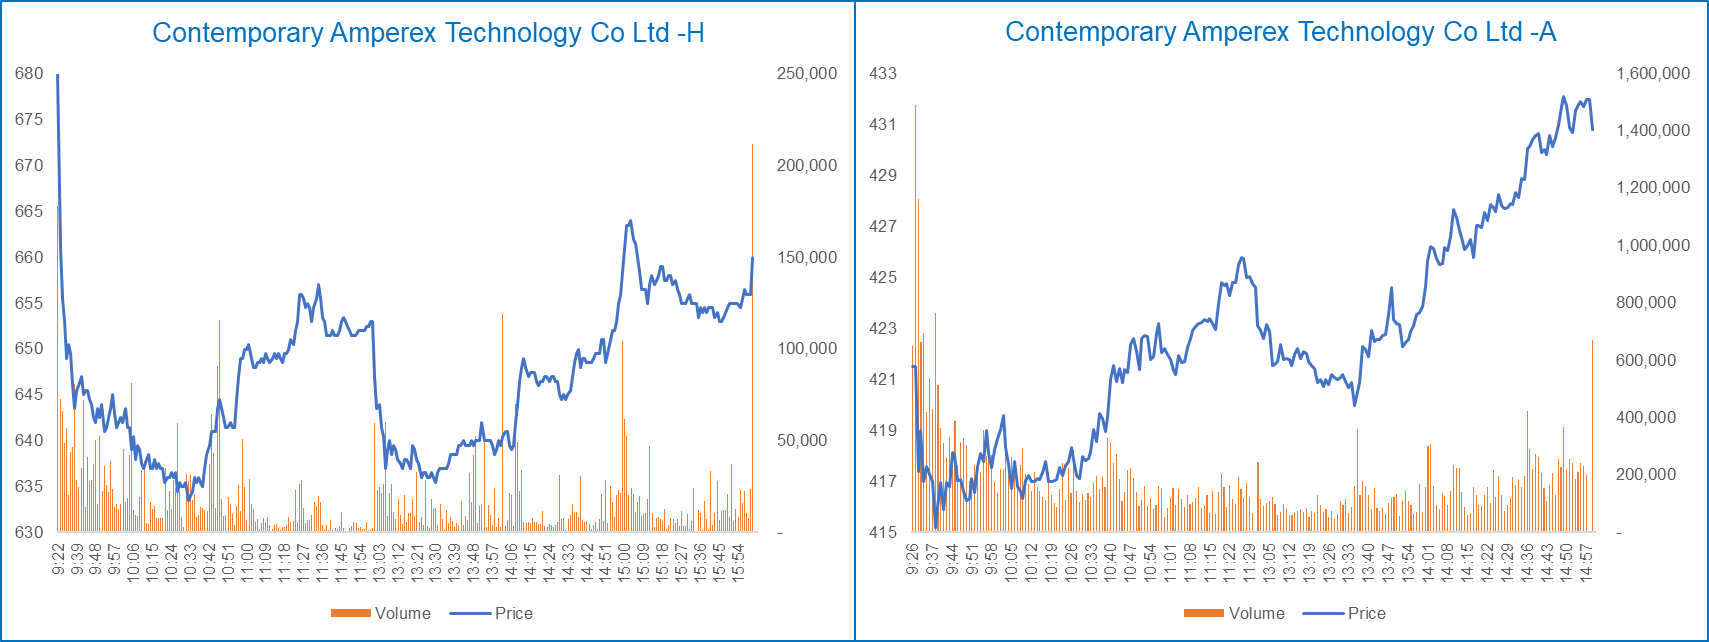
- Passives will mop up around 15% of the offering. Southbound investors have been selling, shorts are rising, and the H/A premium could move sharply lower from here.
2. The Kioxia (285A) Conundrum – Still ¥9trln of Overhang
- Kioxia Holdings (285A JP) tried to IPO but couldn’t. The IPO got pushed back, and shrunk. When it IPOed with a sale of about $700mm in Dec24, it opened down.
- The stock rose 58% to March 2025. Then another 100% to Sep 2025. Then another 100% to Bain’s Dec25 offering. The stock has quadrupled in 4 months since that offering.
- Retail has sold. Passive has bought 45mm shares. Foreign active has 10x-ed their size since March 2025 to 195mm shares. Bain and Toshiba still have 245mm shares left to sell.
3. Victory Giant (2476 HK): Index Inclusion Timeline for US$3bn Offering; Big H/A Discount
- Victory Giant Technology -A (300476 CH) could raise up to HK$23.1bn (US$2.96bn) in its H-share offering if the Offer Size Adjustment Option and the Overallotment Option are exercised.
- The cornerstone investor allocation will vary from 34-45% of the total offering and those shares are locked up for 6 months. Fast entry index inclusion probability is small.
- The H-shares have been priced at a 36.8% discount to the A-shares and that should support the offering. Southbound Stock Connect will come online from the open on 18 May.
4. [Japan M&A] Rohm (6963) – Refreshing Rohm’s Stake Value in Toshiba, and Thinking About NEWCO
- At the end of March, Mitsubishi Electric (6503 JP), Toshiba Corp (6502 JP), and ROHM Co Ltd (6963 JP) agreed to have Mitsubishi Electric join the Toshiba/Rohm power semi talks.
- The language in the documents released is worthwhile a close look. I expect a Rohm/Toshiba deal announcement within the quarter. If control/consolidation/stake levels are agreed, Mitsubishi won’t be far behind.
- Joining the three businesses creates lots of potential synergies, making the businesses #2 in the world. Separately, Kioxia’s recent gains highlight the value of Rohm’s Toshiba stake and Rohm’s value.
5. [Japan Activism] Activists Control Sanken (6707 JP) Going Forward – Watch For Better Plans
- Effissimo Capital Management launched a partial Tender Offer for Sanken Electric (6707 JP) five years ago. The goal was 20%. That tender failed but 6mos later they were at 19%.
- Effissimo bought more, and the company bought back 20% of shares; Effissimo is at 36% now. In late 2022, Oasis bought 6.8%. Now 9.8%. Activists effectively control the vote.
- In Q3 2024, Sanken de-consolidated Allegro MicroSystems (ALGM US) but their stake is still 2x Sanken’s market cap. The “core” business is weak, but should grow. The question is pressure.
6. [Japan Activism] Sun Corp (6736 JP) – Not So Cheap Anymore
- A year ago I wrote Sun Corp (6736 JP) was still/again cheap. Back then it traded at a 48% discount to the value of its shares in Cellebrite DI (CLBT US).
- It spent much of the last few months at a 25-35% discount. Last Tuesday it was a 25% discount. By Friday, it was a 1.2% discount after Cellebrite shares plummeted.
- Sun Corp shares have reacted this morning but the discount is entirely too narrow. If you have the pair on, time to take it off.
7. [Japan M&A/Activism] Sankei REIT (2972) Cancels Previously Announced End-Feb Div – Outcome Murkier
- Through a series of sob stories, Sankei Real Estate (2972 JP) wrote down the value of their biggest building (as of Feb 2025) last August because a tenant left.
- Then they recently said they would have to pay more and wait longer to renovate or sell. Now 11 days later they are taking another writedown. And cancelling the dividend.
- That marks the building down 96% from Feb-25 value. And the dividend is out. And Murakami-san owns 19% of a squeeze-able register. There may be no good outcome here.
8. Makino Milling Machine (6135 JP): Tender Delayed as the Case for a Bump Is Becoming Persuasive
- Due to the delay in securing FEFTA approval, Makino Milling Machine Co (6135 JP) has announced that the start of the MBK tender offer has been delayed to late June.
- Makino is classified as a Type 3 company (core business), suggesting that MBK is negotiating undertakings to secure FEFTA approval.
- Despite mitigating factors, the case for a bump is increasingly persuasive given peers’ material reratings, Makino’s solid financial performance and lack of irrevocables.
9. Merger Arb Mondays (13 Apr) – ENN, Skyworth, Makino, Sankei, Olympic, The Global, NSR, Insignia
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Qoria (QOR AU), Skyworth Group Limited (751 HK), ENN Energy (2688 HK), Humm Group (HUM AU), Bluescope Steel (BSL AU), Emmerson Resources (ERM AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Sankei Real Estate (2972 JP), Gunma Bank (8334 JP), Toho Titanium (5727 JP), Magnetic Resources Nl (MAU AU).
10. Arclands (9842) And Joyful Honda (3191 JP) To Merge, Resulting in Japan’s Leading Home Centre Co
- Arclands Corporation (9842 JP) and Joyful Honda (3191 JP) have agreed to become wholly owned subsidiaries of a new joint holding company through a share transfer.
- For each share in Arclands, one share of the joint holding company will be issued, and for each share of Joyful Honda, 1.15 shares will be issued.
- The terms of the transaction are broadly fair to both sets of shareholders, suggesting that the respective EGM votes should pass. NewCo shares will be listed on 1 March 2027.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Samsung Likely to Drop Second Value-Up Disclosure Before June with Pref-First Cancel to Boost ROE
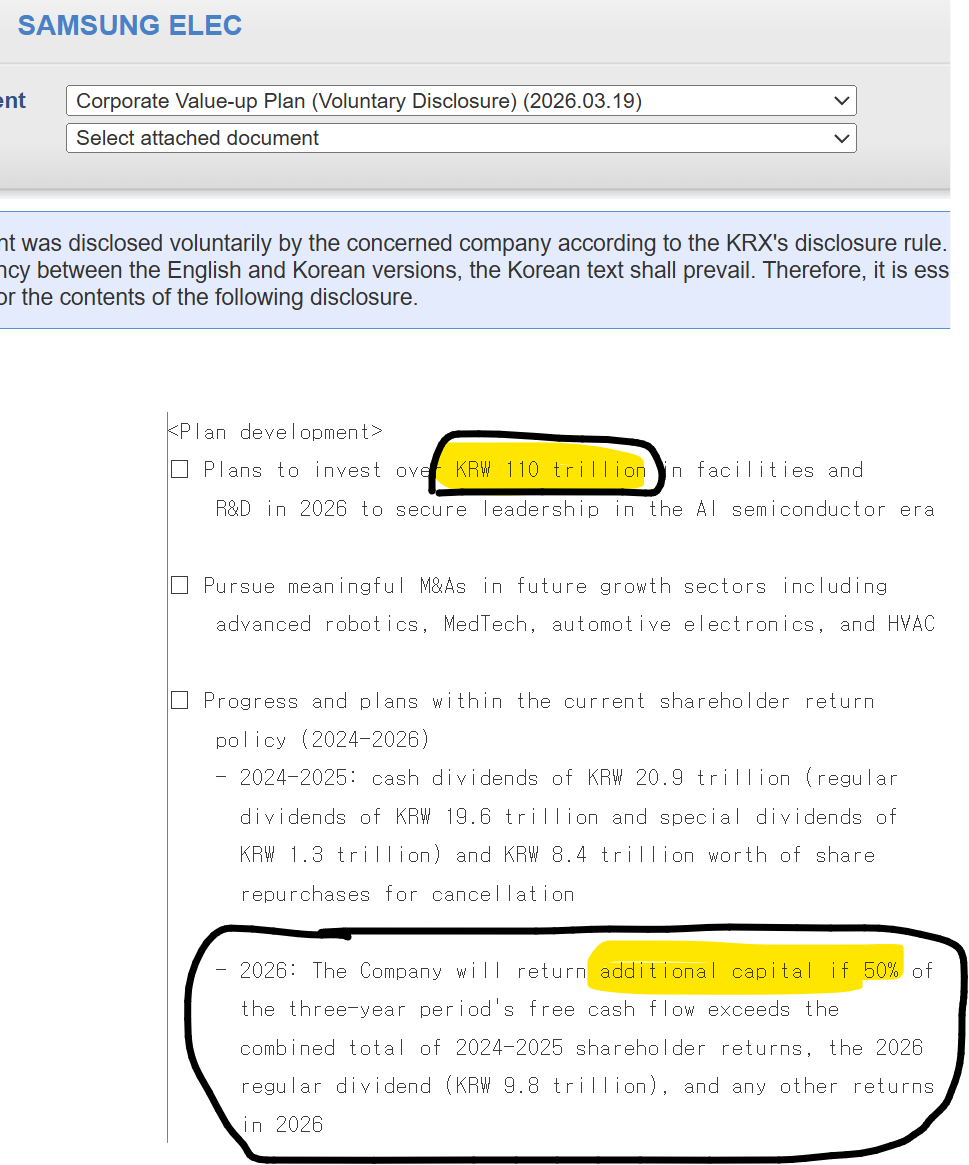
- The local market wants Samsung to clarify FCF deployment and capital allocation, as the March 19 filing just rehashed the 50 percent payout and 2026 capex and R&D guidance.
- With Hong Ra-hee’s final block deal done, Samsung is shifting from defensive buybacks to a structured capital allocation, prioritizing pref-first cancellations to boost ROE ahead of June value-up index rebalancing.
- Samsung’s three year plan stays on the 50 percent FCF framework, but a preferred first buyback roadmap before June could shrink the P/C gap above 75 percent.
2. Why Hynix ADR Proceeds Could Be Used for Cancellations: Square’s EB-ADR Push
- Street chatter says part of Square’s Hynix stake may convert via EB-ADR early, triggering local buybacks and front loading US passive inflows post-ADR listing.
- EB-ADR setup likely decouples Hynix and Square short term. Hynix flow spikes, Square monetizes stake, holding company discount may reprice, but outperformance depends on capital deployment.
- Watch local Hynix shares for delta-driven volatility from EB-ADR flows. Heavy shorting and post-listing pops could create sharp swings, making this a key trading opportunity.
3. [Japan M&A/Activism] Sankei REIT (2972) Extended, and Murakami-San Buys More But…
- Last Wednesday, the consortium bidding to buy out Sankei Real Estate (2972 JP) provided an update regarding the Fukuoka Green Building. A sob story of rising costs and no revenue.
- All known. But the basic idea is to find a reason to lower guidance for the next period started March 1 and provide fodder for a tender update. Announced 2-Feb.
- The extension to 16 April covers the results announcement the day before. On 3 April, Murakami-san announced a 1.29% increase in holding to 17.19%. This doesn’t change much except sentiment.
4. [Japan M&A] Daito Trust To Buy The Global Group (3271 JP) From SBI and Asahi Kasei. Cheapish BUT…
- Daito Trust Construct (1878 JP) yesterday announced a deal to buy Global Ltd/The (3271 JP) from SBI Holdings (8473 JP) who bought 3.5yrs ago. SBI will print a nice gain.
- The deal at ¥1,280 for minorities (and ¥894 for SBI) is probably light given the turnover and the building plans for the next 3-5yrs, BUT, it’s tough to know.
- Shareholder structure is opaque beyond the 62% owned by SBI and Asahi Kasei. This looks easy but could get difficult quickly if someone wanted to make it difficult.
5. Block Deal Sale of 3.1 Trillion Won of Samsung Electronics by Hong Ra-Hee
- It was announced that Hong Ra-Hee has decided to sell 15 million shares (0.25%) of Samsung Electronics in a block deal sale worth about 3.1 trillion won.
- The expected block deal sale price range is 204,395 to 208,605 won, representing a 0.9% to 2.9% discount from the closing price of 210,500 won on 8 April 2026.
- I have a positive view on Samsung Electronics and on this block deal sale. The timing is especially impeccable given the start of the two week ceasefire in Iran war.
6. IJM (IJM MK): Limited Downside As Sunway’s Offer Lapses
- 33.43%. That’s the only number that matters as Sunway Bhd (SWB MK)‘s conditional Offer for IJM Corp Bhd (IJM MK) lapsed on the last closing day.
- My initial optimism that this transaction could get up was misplaced after EPF (20.52% stakeholder)) followed in PNB (13.3%)’s footsteps and rejected terms last week
- Now what? The deal failure was well telegraphed. Comps/KLCI are down 6%/1% since the Offer was announced versus 14% for IJM. The MACC probe did, however, no favours.
7. Merger Arb Mondays (06 Apr) – Skyworth, ENN, Qoria, Bluescope, Emmerson, Taiyo, MCJ, Sankei, Egrand
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Qoria (QOR AU), Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), ENN Energy (2688 HK), Bluescope Steel (BSL AU), Humm Group (HUM AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Gunma Bank (8334 JP), Toho Titanium (5727 JP), Taiyo Holdings (4626 JP), Yomeishu Seizo (2540 JP), Itochu Shokuhin (2692 JP).
8. Aequitas: Tekscend Photomask IPO Lockup Expiry – US$1.1bn Lockup Release
- Tekscend Photomask (429A JP), a manufacturer and distributor of semiconductor photomasks, raised around US$900m in its Japan IPO.
- TP is a global provider of photomasks and related support services. It has been the leader in the merchant photomask market in terms of sales since 2016.
- In this note, we will talk about the lockup dynamics and possible placement.
9. The Global (3271 JP): Daito Trust (1878 JP)’s Tender Offer Is Light but Done
- Global Ltd/The (3271 JP) has recommended a tender offer from Daito Trust Construct (1878 JP) at JPY1,280, a 27.4% premium to the last close.
- While it represents an all-time high, the offer is light, as it is below the midpoint of the target IFA’s DCF valuation range. Also, there was no auction.
- Due to the significant irrevocables, the required tendering rate is low, suggesting a done deal. The first closing date is 22 May, with payment commencing 28 May.
10. Olympic Group (8289 JP): Pan Pacific (7532 JP)’s High Premium Share Exchange Offer
- Olympic Group (8289 JP) announced a share exchange offer by Pan Pacific International Holdings (7532 JP) at 1.18 PPIH shares per Olympic share, a 108.9% premium to the undisturbed price.
- The share exchange ratio resulting from an auction is attractive because it is above the high end of the Olympic IFA’s DCF-derived exchange ratio.
- The significant takeover premium ensures the Olympic EGM vote passes on 28 May. The effective date of the share exchange is 1 July.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Partial Tender] Toyota’s US$23bn Tender Buyback from TICO Is Potentially a Big Put Option
- As promised, as part of the Toyota Industries (6201 JP) takeover, Toyota Motor (7203 JP) was going to launch a Tender Offer Buyback for TICO’s stake. Today, it was announced.
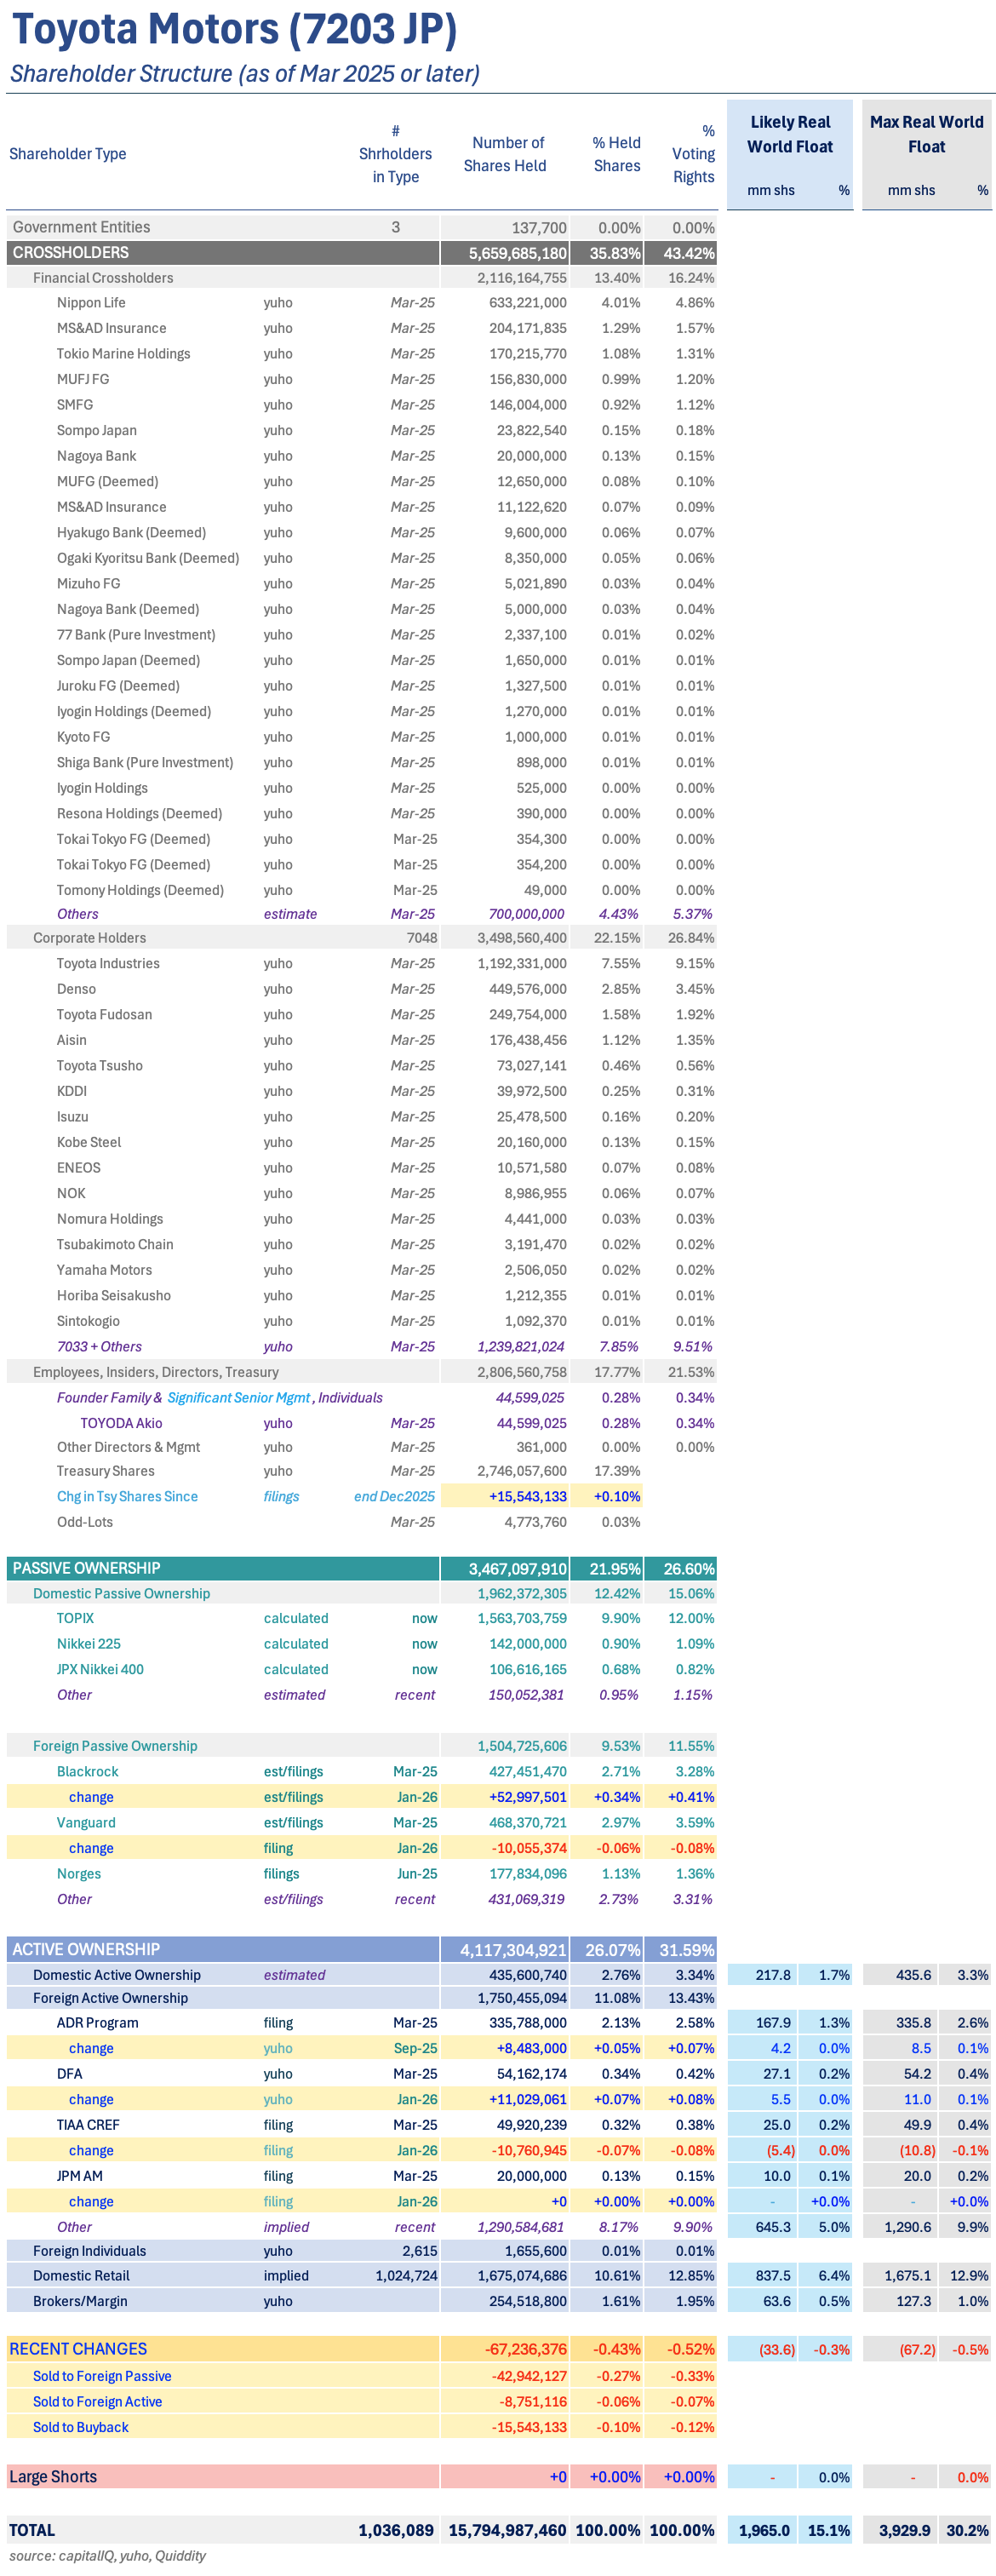
- This buyback in the form of a tender offer at ¥3,067/share is for a maximum of 1,192,331,020 shares, for ¥3.657trln. That’s US$22.8bn. It’s a big buyback. A lot of accretion.
- Everyone can participate, though tendered shares are subject to a Deemed Dividend Withholding Tax. Some investors have found a way to deal with that. It’s worth figuring it out.
2. [Japan M&A/Activism] Bain Releases Presentation Emphasising MCJ (6670 JP) Bid Coercive – Game of 🐓
- Bain had to extend the MCJ Co Ltd (6670 JP) Tender Offer because they did not get enough shares to get over the hurdle. At least two activists object publicly.
- The shares had traded through since the start, fell near the end of the regular tender, and when that did not succeed, shares rose again.
- Bain today released a presentation meant to coerce shareholders into accepting the sub-par deal. And they point out how the deal was coercive in the first place.
3. [Japan Activism] An Odd Little Activism on Tokyo Steel (5423 JP)
- Tokyo Steel Mfg (5423 JP) has long been known as a largely underperforming steel manufacturer, owned by a family which doesn’t push, but the company has cash and securities.
- Last autumn, as the stock reached a two-year low, one or more Iketani family members appear to have sold 6+% of Tokyo Steel to the family asset management Co.
- Family ownership appears to have 53% of the company, making activism a tough row to hoe. But a noted activist just showed up as a 6+% shareholder for end-March.
4. [Japan Event] ARCHION (543A) HAS LANDED! Expensive, Overhang Galore; Risk Is MOOAR SQUEEZE
- Last week? ARCHION INCOMING! This week? ARCHION HAS LANDED! Hino Motors Ltd (7205 JP) closed last week at ¥387/share. The stock is up 32%. On 5x the number of shares.
- 5x? Yes. In order to make this work, Toyota did a giant debt/equity swap AND bought into Mitsubishi Fuso Truck & Bus, gave away value, and delegated management to MFTBC.
- On the third day of trading, ARCHION looks to be 8.9x pro-forma EBITDA, ~17-18x PER, and 1.8x PBR vs Isuzu at 6x, <10x, and <1.1x. And a re-IPO is coming.
5. ENN Energy (2688 HK) Is A Buy
- We’ve now cleared the one-year mark since ENN Energy (2688 HK) first announced a cash/scrip Offer from controlling shareholder ENN Natural Gas (600803 CH) (ENN NG).
- Apart from the ambiguity surrounding the value to be assigned to the scrip into newly-listed ENN-NG H-shares; CSRC, the listing watchdog, has yet to sign off. This should be forthcoming.
- By my calcs, I see at least 30% upside to ENN Energy’s shares here. The market is implying an unreasonable 67% discount for ENN NG’s Hs vs. the As.
6. Likely Setup for Hynix ADR and Square-Hynix Trade Dynamics
- Hynix’s ADR primary issuance maxes at 19.52M shares (2.745% of SO), a hard cap with no room for SK to push beyond.
- Structurally, Square is set to underperform. Hynix’s only lever is an early buyback, sizing and valuation are being calibrated, with ADR issuance now approached more flexibly than a month ago.
- Early buyback could drive Square Hynix dynamics. Local chatter on using ADR proceeds to retire shares looks like noise. Focus is on early buyback from listing to boost ADR volume.
7. MCJ (6670 JP): Bain Moves to Deflate Expectations of a Bump
- Bain notes that its JPY2,200 offer for MCJ Co Ltd (6670 JP) is final and has no intention of extending the close beyond 7 April.
- There remains a chance of a bump as these “final” statements are not binding, and Bain clearly does not have the required acceptances. However, the probability remains low.
- The likely scenario remains that Bain completes the offer by lowering the minimum, as today’s statement is likely designed to secure enough acceptances to complete the deal by doing so.
8. [Japan M&A] SOLASTO (6107 JP) Gets MBK MBO Bid (In Auction) – Decent Price (¥1119) So Likely Done
- Last December, when SOLASTO CORP. (6197 JP) was trading in the high ¥500s, a specialised media source said there were TOB talks. There were, and we got a deal 24-March-2026.
- The deal is at ¥1,119 for minorities (¥776 for Daito Trust). This is a decent price resulting from a competitive bid. It’s just under majority of minority but it’s OK.
- I expect this is done. Daito, employees, insiders, and crossholders hold over 50%. It’s a good price. Clean deal.
9. Webjet (WJL AU): CEO’s Surprise Exit May Kickstart Takeover Discussions
- After some competitive jostling late last year, Helloworld Ltd (HLO AU) and BGH Capital tabled all-cash NBIOs for digital travel agent Webjet Group (WJL AU) at A$0.90/share and A$0.91/share respectively.
- Following protracted due diligence, neither suitor firmed proposals worthy of putting to shareholders, and Webjet subsequently ceased discussion on the 13th February. The share price promptly cratered.
- Katrina Barry has now resigned as chief executive – less than two years into her new role – and just five weeks after the departure of her boss, David Galt.
10. Taiyo Holdings (4626 JP): KKR’s Takeunder Offer a Done Deal
- Taiyo Holdings (4626 JP) announced a preconditional tender offer from KKR at JPY4,750 per share, a 4.7% discount to the last close but an 81.6% premium to the undisturbed price.
- The offer, which resulted from an auction, is above the high end of the IFA DCF valuation range. The offer is attractive compared to long-term historical trading ranges.
- While Oasis and Kowa’s irrevocables have a competing proposal clause, a competing bid is unlikely. This is a done deal, with the tender expected to commence in early October.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
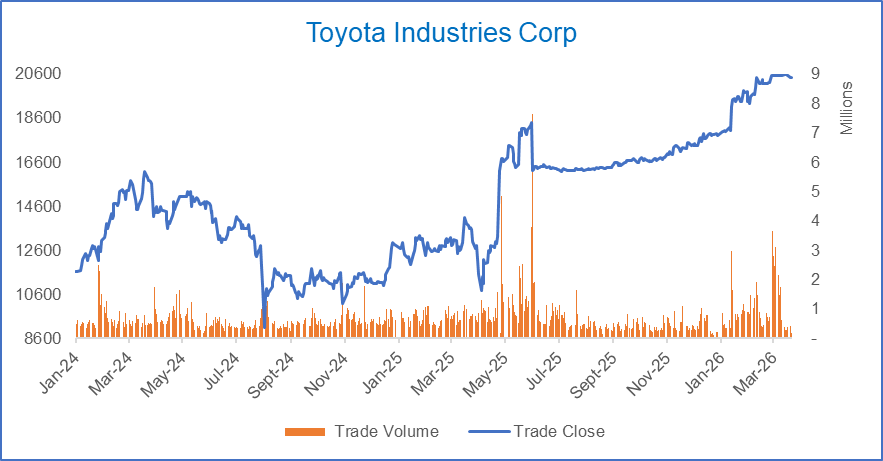
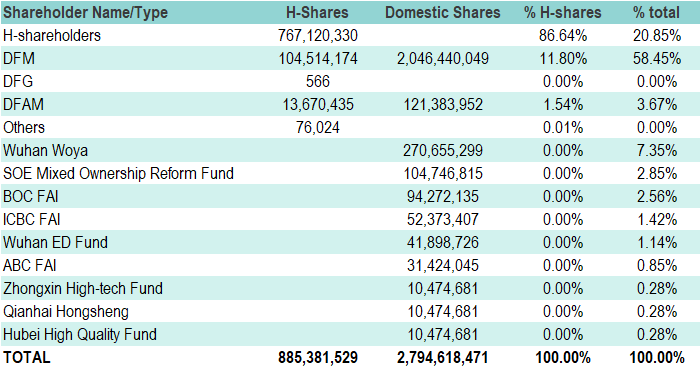
1. Toyota Industries (6201 JP): Huge Staggered Passive Flows
- Following the tender offer completion, Toyota Motor (7203 JP) and TAPCO own 88.26% of the outstanding shares in Toyota Industries (6201 JP). Squeeze-out and delisting are coming.
- Toyota Industries will most likely be deleted from the global indices in one-step. Even if the deletion is done in two steps, the bulk will take place in the near-term.
- Some passives appear to have tendered into the offer already, but there will be a lot of selling over the next month.
2. The Japan March-End Rebal and Dividend Trade (2026 Version)
- Every year (actually, every half year) it is a similar trade. There is a fiscal year-end dividend reinvestment trade for passive funds in Japan.
- The month-end and quarter-end bring big flows, or not, depending on how things have gone.
- Over the past 10-15 years or so, the two-day return on the March trade is pretty good. This year? It’s complicated.
3. HK: Cornerstone/Pre-IPO Lock-Up Expiries in April
- There are 6 companies that listed in October 2025 where the lock-up for cornerstone investors ends in the next 5 weeks.
- The total lock-up expiry across companies is HK$12.6bn (US$1.6bn) with Sany Heavy Industry (6031 HK), JST Group (6687 HK) and CIG Shanghai (6166 HK) making up the bulk of it.
- The cornerstone investor lock-up expiry will increase the number of free float shares between 11-424% and some of the stocks could come under pressure ahead of the expiry.
4. Hynix ADR Listing’s Biggest Mystery: Math Behind US Institutional Inflows
- Local market voices are pushing Hynix for a 10–15% buyback to boost ADR float, aiming for ~10% SO weight, given ~KRW 150tn FCF this year.
- Hynix could target a 3–5% ADR premium, but dividend limits and the 30% primary issuance cap leave little room to sustain premiums early post-listing.
- Float expansion relies on buybacks, as primary issuance is minimal; post-listing ADR premium may drive conversions but could burn off fast, creating a tradable dynamic.
5. [Japan Event] DeNA (2432 JP) – BIG Buyback Does Not Spur Performance, YET
- DeNA (2432 JP) was a serial under-performer vs other game companies for 10 years to end-2024. It spiked in early 2025, then fell back in summer after reporting earnings.
- In autumn 2025, activists Murakami Group built a large stake, then waffled, then bought more and sold more. But in end-February, DeNA announced a Nintendo stake sale and YUUUGE buyback.
- The stock spiked for a day then hasn’t gone anywhere. It’s worth looking at DeNA vs Peers and DeNA historical buybacks.
6. Backstory on Hynix’s ADR Issuance Structure: Staged Buyback Still Needed for Additional 3%
- Tomorrow’s AGM is crucial for legal and procedural legitimacy, as third-party ADR allocations require clear Articles approval to limit preemptive rights and shield the board under the revised Commercial Act.
- With 2.1% of SO canceled and Square’s stake at 20.5%, issuing 2% new shares preserves the 20% threshold and maximizes capital inflows amid lower government CAPEX support.
- Hynix’s remaining 3.1% treasury is mostly EB-collateralized, so securing an additional 3% for ADR will likely require staged buybacks, with treasury use and legal approval addressed in tomorrow’s Articles amendment.
7. [Japan Event/M&A] Nippon Sheet Glass Deal Announced – Fast Schedule, Instant Pref Conversion
- 30 minutes after I published [Japan Event/M&A] Nippon Sheet Glass Injection+Debt-For-Equity-For-Takeover Swap, Nippon Sheet Glass and Apollo announced the deal and terms.
- Basic economic terms are as discussed. AGM timing as mooted. Apollo buys ¥165bn of shares at ¥450/share. Banks convert ¥140bn of debt to pref shares. Existing shareholder squeezeout at ¥500/share.
- The main differences? One version of the timeline has cash-out in Q1 2027 vs Q2-Q3. And JIS is converting all remaining Class A prefs today. They’ll have a big vote.
8. [Japan Event/M&A] Nippon Sheet Glass Injection+Debt-For-Equity-For-Takeover Swap
- Yesterday, the Nikkei carried an article saying that now small-cap Nippon Sheet Glass (5202 JP) would get its debt bailed out into equity.
- Market cap is ¥42bn. Net debt is ¥520bn. ¥177bn of debt is due end-March 2026. Another ¥161bn is due March 2027. Apollo buys new shares at ¥450 (vs ¥405 close).
- Banks would exchange debt for pref equity. Presumably banks would lend to NEWCO. The proposal involves no TOB. Just a squeeze-out. It’s weird. Small-cap. Untested construct. And maybe dead without.
9. Solasto (6197 JP): MBK-Sponsored MBO at JPY1,119
- SOLASTO CORP. (6197 JP) has recommended an MBK-sponsored MBO at JPY1,119, a 100.9% premium to the undisturbed price of JPY557 (9 December 2025) and a 17.3% premium to the last close.
- The offer, which resulted from an auction, represents a three-year high and is above the midpoint of the IFA DCF valuation range.
- The required tendering rate is achievable as the offer is attractive. The first closing date is 11 May, with payment commencing 18 May.
10. Merger Arb Mondays (23 Mar) – Qube, Pepper, Bluescope, Skyworth, ENN, Makino, Sankei Real, MCJ, IJM
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Qoria (QOR AU), Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), Pepper Money (PPM AU), ENN Energy (2688 HK), Bluescope Steel (BSL AU).
- Lowest spreads: Bright Smart Securities (1428 HK), BioDlink International (1875 HK), MCJ Co Ltd (6670 JP), Sankei Real Estate (2972 JP), Australian Strategic Materials (ASM AU).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Voyah Auto (7489 HK): Index & Flow Implications
- Following Dongfeng Motor (489 HK)‘s distribution, VOYAH Automobile Technology Company (7489 HK) shares start trading on the HKEX (388 HK) on 19 March.
- Some global trackers will sell VOYAH Automobile shares at the close on listing day. The stock will be sell-only in Stock Connect for the foreseeable future.
- VOYAH Automobile‘s peers have traded higher over the last few days and that could provide a tailwind for the stock. Valuations are in line with peers.
2. Sunway Healthcare: Index Flows Next Week
- After a huge jump in its stock price on listing day, Sunway Healthcare will be added to the Kuala Lumpur Composite Index (KLCI) (FBMKLCI INDEX) next week.
- There will be also inflows to the stock from passive trackers of one global index. That should provide some support for the stock.
- Active managers in Malaysia use the Kuala Lumpur Composite Index (KLCI) (FBMKLCI INDEX) as a benchmark and there will be buying in Sunway Healthcare from those funds too.
3. Dongfeng Motor (489 HK): Thoughts on VOYAH’s Listing on 19 March
- On 9 March, the vote on the Dongfeng Motor (489 HK) comfortably passed. The offer is HK$6.68 per H Share + 0.3552608 VOYAH H Shares per H Share.
- VOYAH Automobile Technology Company (7489 HK) is set to be listed on 19 March. At the Dongfeng’s last close price of HK$9.54, the implied value of VOYAH is HK$8.05.
- Despite the market turmoil, VOYAH’s peers have fared well, up 7% since the vote. My VOYAH valuation range is HK$10.76 to HK$14.01, with a midpoint of HK$12.45.
4. [Japan Event] Rumblings at TEPCO (9501) Send the Stock Limit Up
- 15 years ago last week, Japan was struck by a huge earthquake accompanied by a tsunami causing nearly 20,000 deaths, and knocking out a TEPCO nuclear power plant, causing disaster.
- The govt+public blamed TEPCO, which has paid out ¥11trln+ of compensation so far. 15yrs later, the company is trying to find a way to grow its way out of debt.
- Today, the Asahi said alliance proposals had come in, including a takeover proposal. The stock went limit up. This is early, and there are LOTS of considerations.
5. [Japan Activism] Elliott Buys Stake In Mitsui OSK (9104) Targets Capital With a Following Wind
- Not long ago, Reuters came out with a headline saying Elliott had taken a “significant stake” in Mitsui O.S.K. Lines (9104 JP) (“MOL”). Minutes later, Elliott issued a press release.
- Shares had been trading at 0.77x book (0.85x TBV) after rising significantly these past few months. They popped 10+% in short order.
- Elliott sees Mitsui OSK as undervalued, wants to “work constructively” with MOL to ensure its “upcoming MTMP” is “appropriately ambitious.” They are pushing with a tailwind.
6. Take on Chey Tae-Won’s Remarks About the Hynix ADR Play
- Hynix will likely present ADR plans at the March 25 AGM. Chey Tae-won’s GTC comments signal the internal decision is done; timing and optics are now the focus.
- March 25 AGM is ideal for Hynix ADR: timing aligns with HBM4 Q2 validation to capture post-milestone valuation uplift.
- Once Hynix announces the ADR, staged 5% buybacks provide strong support, setting up short-term outperformance versus Square, fueled by buyback demand and anticipatory positioning ahead of U.S. passive flows.
7. Merger Arb Mondays (16 Mar) – Skyworth, ENN, BlueScope, Pepper, Humm, Makino, Sankei, MCJ, IJM
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Qoria (QOR AU), Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), Bluescope Steel (BSL AU), Pepper Money (PPM AU), ENN Energy (2688 HK), Humm.
- Lowest spreads: Bright Smart Securities (1428 HK), BioDlink International (1875 HK), Sankei Real Estate (2972 JP), Itochu Shokuhin (2692 JP), MCJ Co Ltd (6670 JP).
8. [Japan M&A/Activism] Maven Writes a Letter on MCJ (6670)
- The Bain-Founder TOB launched on MCJ Co Ltd (6670 JP) in February was at the wrong price. Low-mid single digit equity check to FCF. That’s cheap.
- The Special Committee – unaided by its own advisors – decided the final price was inadequate, but somehow also agreed to not not support it. One committee member dissented.
- Ascender Capital wrote a letter one week later. The stock has traded through terms since announcement. Maven published an open letter today. That’s late. Maybe too late. But we’ll see.
9. Parsing the Underlying Implications of Samsung’s Shareholder Return Comments at Today’s AGM
- Samsung just reaffirmed existing payouts, KRW 9.8tn regular, KRW 1.3tn FY2025 special, and the KRW 16tn buyback, with no new FY2026 dividends or buybacks.
- The AGM’s schedule update covers only the FY2027–FY2029 three-year plan; no guidance or timing was given for FY2026 incremental shareholder returns.
- Local consensus sees FY2026 net income near KRW 170tn, implying KRW 70–80tn for 50% FCF payout; tomorrow’s value-up likely gives a first peek at incremental returns, affecting pref discount.
10. Samsung Just Dropped Its Value-Up Filing: Key Highlights and This Year’s DPS Estimate
- Samsung’s value-up confirms ~KRW 65–70T CAPEX and a hard 50% FCF payout, removing market overhang and signaling strong shareholder returns despite no explicit payout ratio.
- With CAPEX ~KRW 70T and FCF ~KRW 170T, Samsung’s cash build could reach KRW 260–270T, giving the market a solid base to model DPS and structure narratives.
- Samsung’s 50% FCF payout leaves ~KRW 75T for shareholder returns, implying ~KRW 5,500/share special dividend and total DPS ~KRW 7,000, or ~5% yield on preferred shares.