This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
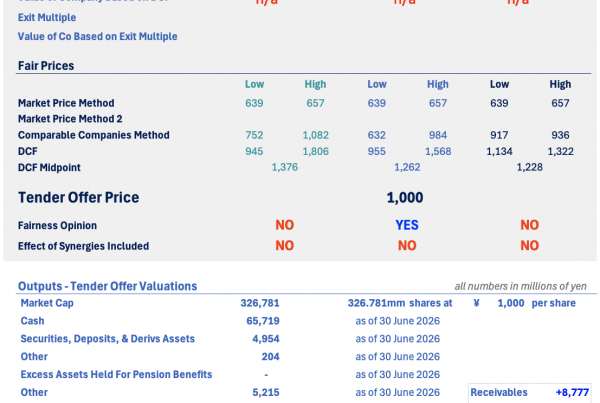
1. [Japan Navel-Gazing] Thinking About The Value of Toshiba
- Toshiba was taken over in late 2023 by a consortium led by local PE firm Japan Industrial Partners. The official takeover price was ¥2.0 trillion.
- That was financed by ¥1.2trln of senior lending, ¥200bn of prefs, ¥520bn of equity, and ¥235.5bn of mezzanine finance which meant net debt on Day1 was likely about ¥1.1trln.
- EBITDA was ¥180bn in Mar24, ¥338bn in Mar25, and ¥482bn in Mar26. Things are improving. And Toshiba held Kioxia shares. That’s gone well too. How well? Look inside.
2. [Japan Event] Rakuten Fintech Group Restructuring – Dirty Deeds Done Unto Rakuten Bank (5838)
- Today post-close, Rakuten Bank (5838 JP) and Rakuten (4755 JP) announced the Fintech Restructuring. “Fintech” is a stretch. It’s an e-bank and an e-broker with a credit card company.
- There are likely a lot of synergies, but this may be a bad deal for Rakuten Bank shareholders. They are paying much more for the synergies than the others are.
- Rakuten Bank contributes 55.4% of the last four quarters of NEWCO OP, but get only 43% of the shares in NEWCO. Securities+Card OP is 30% “stronger” than Bank OP.
3. Samsung Labor Deal: Detailed Structure and Stock Impact Breakdown
- Stock based bonus with lockup removes overhang, supports tape. OP hurdle intact at KRW 200 trillion, no OP no payout, reinforcing growth narrative and downside support.
- Bonus tied to separate KPI set later, not OP or EVA, pushing dispute out. Strike risk gone, union leverage weak, mgmt likely controls KPI design.
- Mgmt to announce ~KRW 30 trillion buyback given limited treasury stock. Likely bundled with shareholder returns, driving front running flows and near term upside, especially in prefs.
4. [Japan Event] Rakuten Bank (5838) – “Exciting” Mizuho News Doesn’t Do Much But Expect More News Soon
- A weekend report suggested Mizuho Financial Group (8411 JP) might invest in Rakuten Bank (5838 JP) when a Rakuten Financial Group is formed. They own 14.99% of Rakuten Card.
- The story suggested Mizuho would swap that stake for a stake in Rakuten Bank. Mizuho Securities (which eclipsed Daiwa Securities last year) would keep its 49% stake in Rakuten Securities.
- This un-complicates things slightly, and suggests earlier analysis was roughly right. Rakuten Bank jumped 10%. It’s up again today. Expect a decision on Rakuten FG this month.
5. NIKKON Holdings (9072 JP): Thoughts on a Potential Privatisation Offer
- On 20 May, Bloomberg reported that Nikkon Holdings (9072 JP) is considering going private and preparing to hold a first-round bidding round in early June.
- The shareholder structure is conducive to a privatisation bid as two activists (Farallon and Oasis) hold 51.6 million shares (44.23% ownership ratio).
- Bain Capital, Warburg Pincus and Blackstone are expected to take part in the auction. My analysis suggests an offer price of at least 6,200 (7.4% above the last close).
6. My Take on What Is Driving the KOSDAQ Tape Today
- National Growth Fund retail opened today, KRW 720bn first tranche, next in H1 next year. KOSDAQ move is sentiment driven on strong demand chatter this morning, not actual inflows.
- Blaming a 5 percent KOSDAQ move on this alone is a stretch; it is short covering in battery and biotech plus KOSPI to KOSDAQ rotation on a policy signal.
- 5% KOSDAQ move is placebo causality flip; fund hype only catalyst for rotation tape. Key call is durability vs normalization, I lean fade as flows and positioning reset.
7. CR Power (836 HK): CSRC Clears Clean Energy Spin-Off
- A fortnight after the Shenzhen Stock Exchange approved SOE-backed power play China Resources Power (836 HK) (CRP)’s A-share listing of its renewable energy unit, CSRC approval is now satisfied.
- The process has taken over three years. Since that time, CRP’s earnings and attributable installed capacity, is now evenly split between its thermal and renewable energy segments.
- With CSRC and SZSE approvals in the bag, the final stretch should move relatively quickly.
8. Flow Cannibalization Trade Setup Around Samsung and Hynix Leveraged ETF Listings
- Focus is on rotation from semi leveraged ETFs, about KRW 700bn to 1tn in 5 days, mainly cannibalizing KODEX and TIGER which proxy Samsung and Hynix leverage.
- Better trade is smaller names, not Samsung or Hynix. Futures likely take heavy sell pressure post listing, driving outsized basis blowout and spot futures dislocation versus turnover.
- Screen names are Hanmi, Leeno, Wonik IPS, EO Technics, ISC. Expect 1 to 1.3x futures sell flow. Play via cash shorts or basis on backwardation.
9. Merger Arb Mondays (18 May) – ENN, Skyworth, Tohoku, Shinko Shoji, Kakaku, Taiyo, Qoria, OOh!media
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Tohoku Steel (5484 JP), Skyworth (751 HK), Qoria (QOR AU), ENN Energy (2688 HK), European Lithium (EUR AU), Changhong Jiahua (3991 HK), Humm Group (HUM AU).
- Lowest spreads: Kakaku.com Inc (2371 JP), Taiyo Holdings (4626 JP), Australian Strategic Materials (ASM AU), Toho Titanium (5727 JP), Vault Minerals Ltd (VAU AU), Nippon Dry Chemical (1909 JP).
10. [Japan Event] Kosaido (7868) – Death Had a Bad Year in FYMar26 but It’s a Growth Business
- Kosaido (7868 JP) used to be a stationer and printing business. Printing has been a bad business for decades. But the company also has a large funeral parlour business.
- That business dominates Operating Profits and Assets. Years ago, the CEO tried to MBO it cheaply. Murakami intervened, others bought afterwards, and a few large holders dominate this illiquid stock.
- Today, speculative/investigative media outlet FACTA reported that Kosaido might sell its funeral parlour business. PE funds are reportedly interested. That would create a huge pile of cash but what then?