
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Event] DeNA (2432 JP) – BIG Buyback After Asset Sale, Commits to Better Capital Allocation
- On Friday, Nintendo (7974 JP) announced 3 banks and DeNA (2432 JP) would sell Nintendo shares in a secondary offering.
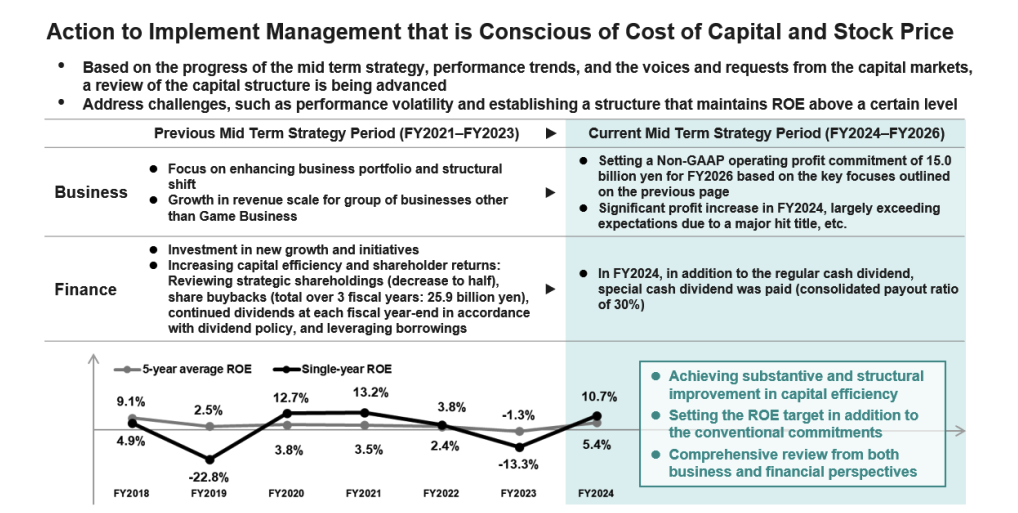
- DeNA simultaneously announced an update to “Action to Implement Management that is Conscious of Cost of Capital and Stock Price” (10Nov25). AND announced a BIG buyback and DOE policy.
- The buyback is big, but long-term, not big enough. They need more. Can do more. Shareholder structure is odd so buyback dynamics quirky. This alone is worth looking into.
2. Toyota Industries (6201 JP): Winners and Losers
- Fudosan’s offer for Toyota Industries (6201 JP) will be increased by 9.6% to JPY20,600. The offer has been declared best and final. Elliott intends to accept the offer.
- Despite 26.4% premium to the first offer, Fudosan has emerged as the winner, as it will get TICO below real-time book value and the core unlisted business at <1x EV/EBITDA.
- Elliott emerges with a sullied reputation, having accepted an offer 21% below its base-case value, not being able to reinvest in BidCo, and declining to pursue appraisal rights.
3. Dongfeng (489 HK): On VOYAH’s Imminent Spin-Off
- On the 22nd August 2025, SOE-backed Dongfeng Motor (489 HK) announced a privatisation; together with a concurrent listing of its EV arm, VOYAH.
- The two proposals are inter-conditional. Key PRC reg pre-approvals (Mofcom/NDRC/SAFE) are now all satisfied. A Composite Doc has been dispatched with an EGM (Scheme-like) vote on the 9th March.
- A basket of VOYAH peers are down 26% since the dual proposals were announced. And the peer average P/S & EV/S have dipped to 1.8x from 2.2x since the Offer.
4. [Japan M&A] TAPCO-TICO (6201) Deal VIII – Toyota Group Bumps, Elliott Agrees, STILL the Wrong Price.
- Today during market hours, Toyota Asset Preparatory Co (TAPCO) announced an amendment to its Tender Offer Registration Statement (for the Toyota Industries (6201 JP) tender) on EDINET. TDNet confirmation followed.
- TAPCO extends, and plans to bump from ¥18,800 to ¥20,600, +1.5% vs last, assuming banks agree. That’s above 31Dec25 BVPS but below real-time BVPS, and far below Transaction Structure-adjusted BVPS.
- I admit to being surprised. And disappointed. It’s admittedly Big Bumpitrage but not a “watershed moment.” TAPCO is buying TICO at <0.8x book, and the Opco for <0.15x book.
5. [Japan Event] Rakuten (4755) Fintech Group Led By Rakuten Bank (5838) Gets Bigger and Keeps 20% ROE
- On 1 April 2024, Rakuten (4755 JP) announced Rakuten Bank (5838 JP) and Rakuten Group would start talks aimed at creating a Fintech Group. I wrote this. Talks halted 6mos later.
- Back then, word was Bank was dissatisfied with the ratios. As of 25 Feb 2026, they are starting talks again as Rakuten Group sees greater bank competition as rates rise.
- This is slightly complicated. Mizuho owns 14.99% of Card, and 49% of Securities. But this can be done. And the formation leads to interesting outcomes.
6. Clearing up the Confusion Around Samsung’s March 19 Deadline for Submitting the Value-Up Disclosure
- For 2026, companies can file a simplified Value-Up disclosure, but must at least include explicit ROE and payout ratio targets to signal capital return metrics.
- Samsung’s March 19 filing, full or simplified, must include this year’s payout ratio, giving the market a clear dividend policy signal.
- Samsung’s March 19 filing will confirm payout and ROE targets, letting the market estimate net income and DPS, potentially triggering a key pivot to tighten the wide 1P discount.
7. ROHM (6963 JP): Denso’s Rumoured Tender Offer Is Light
- Nikkei reported that Denso Corp (6902 JP) is considering a tender offer for ROHM Co Ltd (6963 JP) at a valuation of around JPY1.3 trillion.
- If the rumoured valuation refers to market cap based on outstanding shares, it suggests an offer around JPY3,240, a 18.0% premium to the undisturbed price of JPY2,743.
- While marginally below the 20-year high, the rumoured offer is light when accounting for the value of Rohm’s stake in Toshiba.
8. Sunway Healthcare IPO: Global Index Inclusion in Aug/Sep; KLCI Missing
- Sunway Healthcare is looking to raise MYR 2.86bn (US$734m) in its IPO, valuing the company at MYR 16.7bn (US$4.3bn). There is a big allocation to cornerstone investors.
- Sunway Healthcare should be added to the small cap segment of the global indices with one inclusion in August and the other in September.
- Sunway Healthcare will not get Fast Entry to the Kuala Lumpur Composite Index (KLCI) and will need to move a lot higher to get inclusion at the June review.
9. Check on the Setup Suggesting Hynix Could Start ADR Moves Right After the AGM on the 25th
- SK Group leadership remains keen on a Hynix ADR, viewing SEC compliance as manageable versus rising AI-era funding needs, framing ADR as a strategic balance sheet lever.
- Hynix will use treasury shares, not new stock, for ADR. SK sees 4–5% treasury deployment as needed to pull passive flows, with cash (~₩35T) enough to fund the staged buyback.
- The buyback announcement is likely right after the AGM, with capital reserve cut prepping it, creating a near-term setup for Hynix to outperform Square.
10. Merger Arb Mondays (02 Mar) – Dongfeng, ENN, Bluescope, Humm, ClearView, Toho Titanium, Sankei, IJM
- I summarise the latest spreads and newsflow for the merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, the Philippines, Thailand, and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), ENN Energy (2688 HK), Bluescope Steel (BSL AU), Dongfeng Motor (489 HK), Pepper Money (PPM AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Toyota Industries (6201 JP), MCJ Co Ltd (6670 JP), BioDlink International (1875 HK), Sankei Real Estate (2972 JP), Itochu Shokuhin (2692 JP).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
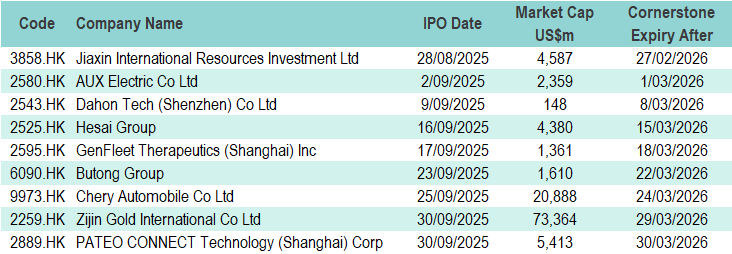
1. HK: Cornerstone/Pre-IPO Lock-Up Expiries in Feb/March
- There are 9 companies that listed in August and September 2025 where the lock-up for cornerstone investors ends in the next 5 weeks.
- The total lock-up expiry across companies is HK$50.3bn (US$6.45bn) with Zijin Gold making up the bulk of it. Butong and Jiaxin International have a lock-up for pre-IPO investors too.
- The cornerstone investor lock-up expiry will increase the number of free float shares between 29-78% and some of the stocks could come under pressure ahead of the expiry.
2. [Japan M&A] JX Advanced Metals (5016) And Toho Titanium (5727) To Merge VERY Quickly
- On 25 February, JX Advanced Metals (5016 JP) and subsidiary Toho Titanium (5727 JP) announced they would conduct a scrip merger to be effective in three months.
- Unlike most scrip mergers in Japan in recent years, this time the parent is paying a 50% premium vs last trade.
- There is, however, an interesting quirk to this transaction. It will be super-aggravating to some after what looks like, on the face of it, an OK result.
3. Toyota Industries (6201 JP): Risk/Reward Ahead of the Second Close
- Reuters reports that Elliott has offered to pay around market price to buy Toyota Industries (6201 JP) shares from holders who have agreed to tender. The close is 2 March.
- Elliott’s strategy is three-fold: increase its stake without launching an expensive partial offer, ensure the minimum is not met, and ensure Fudosan discloses, at best, a modest increase in acceptances.
- Elliott’s campaign may work too well, and there remains a possibility that the tender offer fails. In such a scenario, the downside to a deal break price is limited.
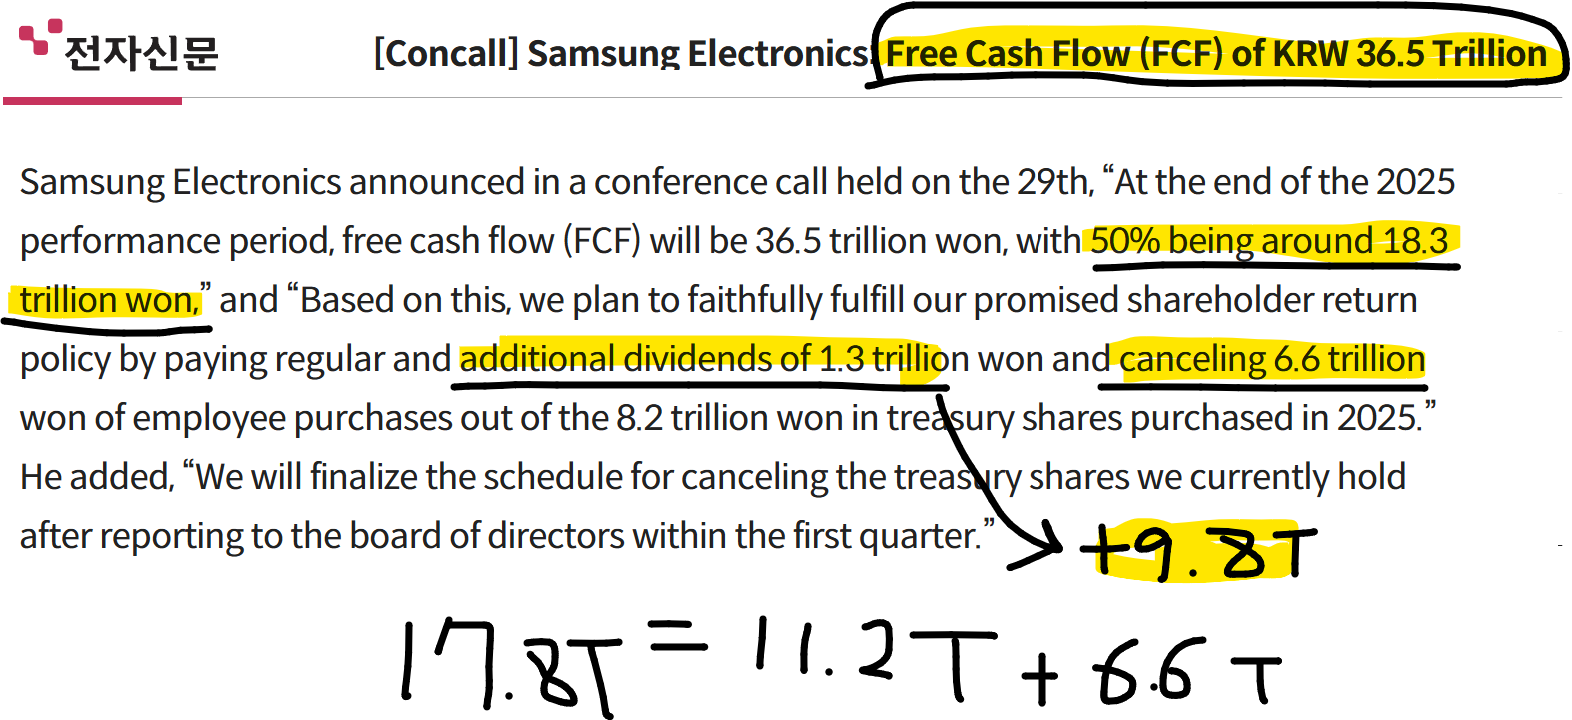
4. Timing for Samsung Electronics KRW 3.2tn Block: Next Thursday
- Local market now expects the Samsung block to land next Thursday, pushed a week from this Thursday/Friday expectation to avoid overlap with EWY’s 25% reversion rebalance today.
- Hong Ra-hee’s camp and Shinhan Bank face a tight window: mid-April cash settlement needed, avoiding missed 1Q dividends and potential May market pullback pressures.
- 1P discount widened from 20% to ~35%, pre-deal support lifts ords now, but block clearance likely hits ords flows and removes key narrative, making next Thursday critical.
5. Ibiden (4062 JP): Secondary Offering Comes Hot on the Heels of Index Inclusion
- Five banks are looking to sell up to 7.9m shares of Ibiden Co Ltd (4062 JP) in a secondary offering that will raise just short of US$500m.
- Ibiden Co Ltd (4062 JP) is an inclusion to a global index at the close on Friday and passive trackers need to buy over US$900m of stock.
- The stock has run up a lot in the short-term and reversion post index inclusion will be aided by the increased float following the placement.
6. Duzon Bizon’s Massive Tender Offer Drops Today: Checking the Bump-Play Dynamics
- EQT’s SPV is tendering ~18.16 mn shares (~60% of SO) at ₩120K/share, a ~25% premium to Feb 20, targeting full take-private after existing stakes and treasury are carved out.
- Bump-Play angle: ₩120K price is stale from Nov 2025. Strong Q4 reset gives holdout institutions cover to say “no” and push for a higher valuation.
- EQT faces a 95% delist clock; aggressive treasury cancellation risks litigation under the new Commercial Act, so expect more institutions than usual to chase a bump play.
7. Merger Arb Mondays (23 Feb) – Toyota Ind, MCJ, Raksul, Sankei, AJIS, Skyworth, Humm, Bluescope, Qube
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Humm Group (HUM AU), Bluescope Steel (BSL AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Toyota Industries (6201 JP), MCJ Co Ltd (6670 JP), BioDlink International (1875 HK), Sankei Real Estate (2972 JP), Krosaki Harima (5352 JP).
8. Korean Gov’t Signals Aggressive Push on Anti–Share-Price Suppression Law Today: Trading Setup Check
- The Korean government signaled this morning it will fast-track the “anti share-price suppression” law, moving even faster than expected, with multiple local channels confirming the aggressive push.
- Local desks are aggressively trading this narrative. Many names moved, but with the bill not yet cleared, we should track laggards and under-owned stocks for potential follow-through.
- Local desks are targeting liquid stocks (PBR ≤0.8, treasury ≥10%), with buybacks as a direct re-rating tool. Top names are ranked by PBR undervaluation and treasury holdings.
9. [Japan Event] Itochu Partial Tender for 13+% of Sun Frontier Fudosan (8934). Tiny Premium. No Min.
- Today, Sun Frontier Fudousan (8934 JP) and Itochu Corp (8001 JP) signed a capital alliance. As part of that, Itochu is buying up to 6.657mm shares in a partial tender.
- It is also buying 5.5mm shares at a discount in a 3rd party placement. Advantage Partners will convert and tender some of its CB. Itochu will own 15-20+% post-deal.
- This is Itochu getting into a new position. It’s a new career being made. It is possibly a precursor to buying out the founder in a couple of years.
10. [Japan M&A] Itochu Buys Out Itochu Shokuhin (2692) Cheaply as Crossholders Get It Over The Line
- Today during market hours, the Nikkei released a headline saying Itochu Corp (8001 JP) would buy out 52.5% sub Itochu Shokuhin (2692 JP) at a tiny premium.
- Post-Close, it was confirmed. Tiny premium. Low multiple. Kind of insulting assumptions. But that is par for the course for an Itochu takeover of a subsidiary.
- This gets done because Itochu + crossholders own 70%. Tough to see an activist effort because one can’t join in the back end.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Samsung Prefs: 4% Floor Yield Vs 30% Discount—Unsustainable Vs 2020 Levels
- At Friday’s close, common yields ~2.9%, prefs ~4%—the floor for tax benefits. Despite a 4%+ pref yield, the 1P discount remains ~30%, unsustainable versus 2020’s 6–8%.
- The main tail risk—dividend cuts via capital reduction—is unlikely. With KRW 400tn retained earnings and bellwether status, Samsung will likely stick to straightforward earnings-based dividends.
- Even on minimum assumptions, Samsung prefs yield low-4%, with ~30% discount likely unsustainable. Easing memory tightness or catalysts like DeepSeek V4 may trigger aggressive pref discount plays.
2. [Japan M&A] Bain Capital To Buy Growthy Inforich (9338 JP) – High Premium but Low Multiple
- On Friday, Bain Capital announced it would buy ChargeSpot provider Inforich (9338 JP) in an MBO which takes the CEO out of most of his position (and margin debt).
- The price is a strong ¥4,560/share which is a 116% premium. That is a 52-week high. It is not a 53-week high.
- The register may be somewhat open. It’s a high premium, but low multiple on high WACC. Seems light-ish but their moat may not be that high.
3. [Japan M&A/Activism] GS Bumps Raksul, Says Final, Gets One Investor Agreed, Gaslights Minorities
- Today in the PM session, the GS-led consortium bidder for Raksul Inc (4384 JP) extended the Tender Offer and raised its bid from ¥1,710/share to ¥1,900/share.
- “The Tender Offer considered such price to be the maximum and final price that it could offer to the Target Company shareholders.” This looks binary. Done or dead.
- Since there appear to have been no acquisition proposals made to the company, it looks like this is “it.” Activists will be allowed to roll in if they act quickly.
4. Merger Arb Mondays (16 Feb) – ENN, Dongfeng, Inforich, Takara Bio, Raksul, Toyota Ind, Pepper Money
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Inforich, Takara Bio Inc (4974 JP), Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Pepper Money (PPM AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Raksul Inc (4384 JP), Toyota Industries (6201 JP), BioDlink International (1875 HK), Sankei Real Estate (2972 JP), MCJ Co Ltd (6670 JP).
5. Inforich (9338 JP): Bain-Sponsored MBO at a 117% Premium, but Is Potentially Light
- Inforich has recommended a Bain-sponsored MBO at JPY4,560, a 116.6% premium to the last close.
- The offer is arguably attractive given the hefty premium and aligns with the midpoint of the IFA DCF valuation range. Also, Inforich’s near-term outlook remains challenging.
- However, the offer is light, as it is below the 52-week high, the IFA forecasts are well below the VISION 2030 plan, and the MBO will benefit from cost front-loading.
6. [Japan M&A/Activism] Murakami Bought, Squeezed, Now Tender Closing
- On 6-Jan-2026, Tosei Corp (8923 JP) and GIC announced a Tender Offer of Sankei Real Estate (2972 JP), as Fuji Media Holdings (4676 JP) was disposing of non-operating assets.
- I recommended buying for the possible squeeze as the minimum might be difficult. Murakami started buying and now has 15.9% at last look. I recommended selling. Now it’s VERY difficult.
- The Bidders and Murakami have been strangely quiet. The unit price has fallen back close to terms. The tender ends tomorrow. What To Do?
7. HSCI / HK Connect Inclusion (Mar 2026): Lessons from a Sep 2025 Retrospective Event Study
- Hang Seng Indexes announced the latest Hang Seng Family / HSCI review results after market close on Feb 13
- We reviewed the Sep 2025 HK Connect round to guide positioning for the upcoming adjustment.
- We highlight the most actionable patterns from the Sep 2025 episode.
8. [Japan M&A] Activist-Pressured Takara Holdings (2531) Takes Out Sub Takara Bio (4974)
- Takara Holdings (2531 JP) has been under pressure from activist Value Act. Friday they announced they would buy out their major listed subsidiary Takara Bio Inc (4974 JP).
- The premium is at 43+%. That’s pretty good, but the Tender Offer at ¥1,150/share is below the price at which it traded for a decade til two years ago.
- This will almost certainly get done. By itself, it doesn’t seem to be an activist bumpitrage target.
9. MCJ (6670 JP): Ascender Capital Sets an Activist Campaign in Motion
- Today, Ascender Capital issued a PR Times release raising concerns over what it states is a conflicted Bain-sponsored MBO for MCJ Co Ltd (6670 JP).
- Ascender, which first published its concerns on its website on 16 February, highlights four issues with the MBO and seeks a higher price. Most of Ascender’s criticisms are valid.
- Bain’s initial approach will be to wait until the first close approaches (24 March). However, with significant volume trading above the offer, a bump is very likely.
10. Quiddity M&A Guide 2026: South Korea
- This insight is part of a series of M&A guides our Quiddity* team are publishing to aid investors in understanding the rules, parameters, possibilities, and processes when companies conduct M&A.
- The initial guide – Quiddity Korea M&A Guide 2020 – was published in May 2020. Since that time, there have been various new developments.
- This is an update. These insights are designed to be used as a reference. They are not actionable. For a list of Quiddity M&A Guides, click here.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
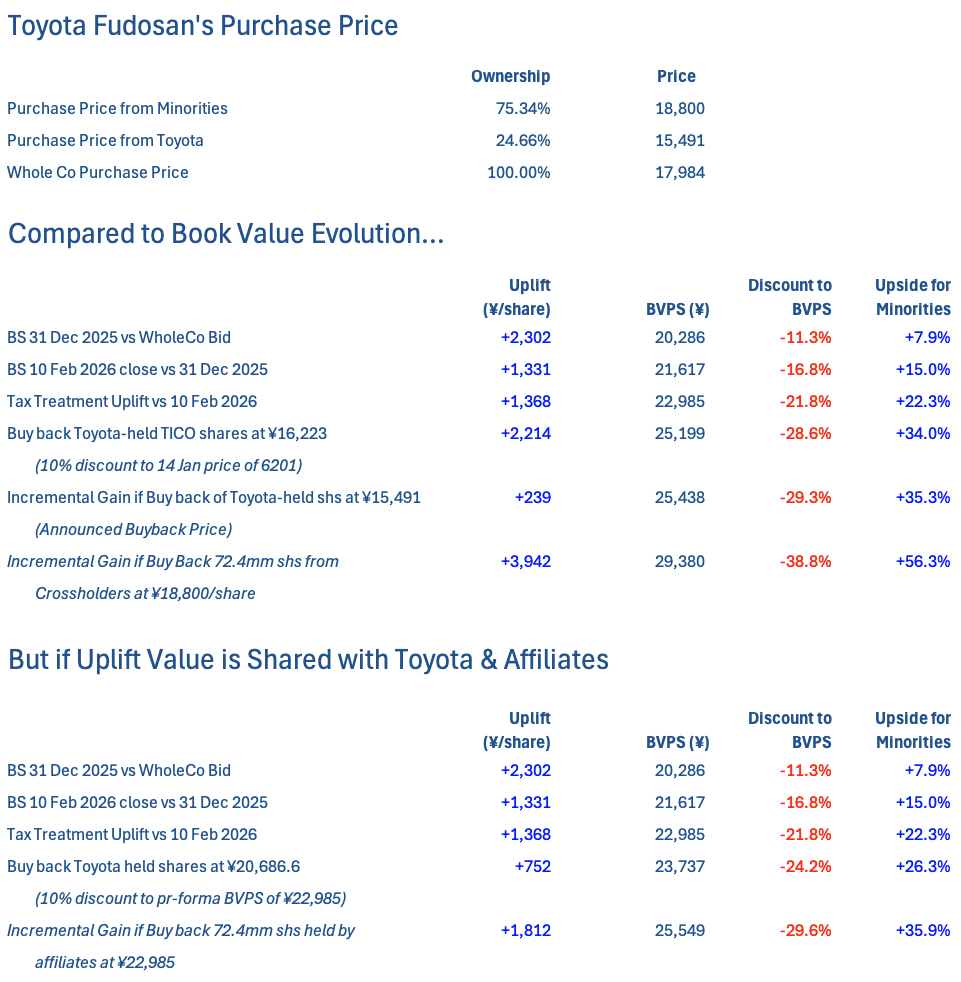
1. [Japan M&A/Activism] Toyota RE Deal for Toyota Industries (6201 JP) Last Looks
- The fact Toyota Industries (6201 JP) is only 4+% through terms is an indication investors are unconvinced blocking this deal gets a good governance result. That’s bad.
- Remember TICO+Toyota Group were already unwinding cross-holdings. The original docs said they’d agreed. I doubt they un-agree. The transaction WITH buybacks WITHOUT takeover (or restructuring) has a BVPS of ¥28,855.
- If the benefits of uplift are shared with Toyota and all Crossholders, they receive an extra ¥385bn and ¥159bn and post-deal minority BVPS is “just” ¥25,549. Best outcome? Deal break.
2. Toyota Industries (6201 JP): Scenarios Ahead of the First Close
- The first closing date of Toyota Fudosan’s JPY18,800 offer for Toyota Industries (6201 JP) is 12 February. Shares continue to trade above terms.
- Ahead of the first close, internal and external factors have continued to underscore that the offer is light.
- There are several potential scenarios at the first close. The most likely scenario is the extension of close and additional irrevocables. The least likely scenario is successful completion.
3. [Japan M&A/Activism] Toyota RE Deal for TICO (6201) Extended. VERY Few Minorities Have Tendered.
- Toyota Asset Preparatory Co today extended its tender for Toyota Industries (6201 JP) til 2 March. They indicated 33.1% had tendered as of 1pm. That suggests 95+% of minorities hadn’t.
- It repeated its statement that it is paying full intrinsic value for the company. I think that is patently, demonstrably false. If they think so, they are the wrong buyer.
- Shares popped after the news. They reiterated they had no intention to pay more. That’s par for the course. I expect they may bid up, but still not get it.
4. Ferretti (9638 HK): On KKCG’s Partial Offer
- On 19th January, privately-held KKCG Maritime announced a partial offer for luxury yacht maker Ferretti SpA (9638 HK), seeking to lift its stake to 29.9% from 14.5%.
- Ferretti is a dual-primary listing, the first company to be listed on both the Hong Kong and Milan exchanges.
- Ferretti’s major shareholder is Shandong SASAC (37.54%). The Italian regulator is running a ruler over the transaction. Comfortably trading through the HK$31.71/share cash terms.
5. StubWorld: On Toyota Inds (6201 JP)’s Last Day Of Offer
- A double dose of StubWorld this week as the Tender Offer for Toyota Industries (6201 JP) closes today. Will Fudosan extend? Possibly. Will they bump? Unlikely.
- Preceding my comments on Toyota are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
6. [Japan M&A] CVC/Family “Re-Nudge” Mandom (4917 JP) MBO Price from ¥2,600 to ¥3,105, Eclipsing KKR
- Almost two weeks ago, Kalon Holdings – the CVC+Nishimura Family entity bidding for Mandom Corp (4917 JP) in an MBO upped their ¥2,520 Bid to ¥2,600 against KKR’s ¥3,100 Bid.
- They said they might meet KKR’s price. Today, at 9am JST, they met KKR’s price and raised it by ¥5/share to ¥3,105.
- The resulting Amended Target Opinion is a masterpiece of Board self-justification for going with the original MBO rather than with KKR. But it’s an OK price.
7. Merger Arb Mondays (09 Feb) – Mandom, MCJ, Toyota Ind, Raksul, IJM, Guocoland, Skyworth, ENN
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), Dongfeng Motor (489 HK), Australian Strategic Materials (ASM AU), Webjet Group (WJL AU), ENN Energy (2688 HK), Ijm Corp Bhd (IJM MK).
- Lowest spreads: Bright Smart Securities (1428 HK), BioDlink International (1875 HK), Hisamitsu Pharmaceutical Co (4530 JP), Toyota Industries (6201 JP), Sankei Real Estate (2972 JP).
8. Front-Running Korea’s 2x Single-Stock ETFs: Basis Blowouts & Calendar Spread Arb Pre-June Launch
- The one-ETF-per-desk rule matters because concentrated hedging flow can blow out single-stock futures basis, creating ugly contango and juicy cash-and-carry opportunities as one desk dominates futures buying.
- Focus on pre-loading long-basis positions 1–2 months ahead, monitor contango closely, set short-basis trades, and capture the basis blowout once ETF flows hit.
- ETF listing likely pushes June flows into September, creating a timing arb: short front months (June/July), long Sep, capturing curve steepening and widened calendar spreads.
9. Pepper Money (PPM AU): KKR/Challenger’s NBIO
- This morning (9th Feb), leading non-bank lender Pepper Money (PPM AU) confirmed KKR and Challenger Ltd (CGF AU) have submitted an NBIO by way of a Scheme.
- KKR/CGF are offering A$2.60/share, a 47.7% premium to undisturbed. And ~1.49x P/B (based on 1H25 numbers). KKR currently holds 60.34%.
- CGF announced it would hold no more than 25% in Pepper Money, if delisted. CGF is down 3.6%.
10. Hisamitsu Pharma (4530 JP): Risk/Reward as Shares Trade Through Terms
- Since announcing the offer, Hisamitsu Pharmaceutical Co (4530 JP)’s shares have traded consistently above the MBO offer price of JPY6,082. The offer closes on 19 February.
- While there was no auction, the offer is reasonable. The spate of recent MBOs that attracted activists successfully securing better terms may also be behind the share price action.
- The probability of a bump is low due to no visible activism, peers not re-rating, irrevocables, several crossholders, and the minimum can be lowered. Take profits.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A/Activism] Toyota RE Says No Bump for Toyota Inds (6201) Part III – Elliott Makes Its Case
- This morning, Elliott made its case to interested investors, explaining much of its presentation and the possible choices investors face. TF’s average buy price is <¥18,000. Q3 BVPS likely ¥20k+.
- But of course, realtime BVPS is higher, and transaction structure BVPS comes out near ¥24k. This is too cheap. Still.
- Post-Close today, BidCo said “[The TOB Price] is the best possible price that reflects the intrinsic value of [TICO]”. That tells me and many others, Bidco isn’t the right buyer.
2. Toyota Industries (6201 JP): Who Wins This Game of Chicken?
- Toyota Industries (6201 JP)’s 3Q results further emphasise that Toyota Fudosan’s JPY18,800 offer is light. The offer implies a P/B ratio of 0.93x based on the 3Q book value.
- Fudosan’s assertion that it will not change the offer price is not credible. Elliott is likely to further increase its stake but is unlikely have its price expectations met.
- Fudosan’s likely gameplan is to bump above 3Q book value (JPY21,300 to bring the P/B back to the pre-3Q ratio of 1.05x) and possibly also lower the minimum.
3. [Japan Activism] Fuji Media (4676) Offers Activists a Possible Juicy Way Out
- Fuji Media Holdings (4676 JP) ran into a scandal a year ago. It was scandalous before but it all got ugly a year ago. I discussed last year here.
- Last June, activist Dalton tried to spill the Board. It did not work. Incumbents and recommended got 81-86% support. Dalton’s slate got 10-27%. No joy.
- Activists are in big. Murakami at 17%. Dalton at 7+%. Last week, the Nikkei reported Dalton would push for a 10% of TSO buyback. Today, we got a bigger one.
4. Montage Technology (6809 HK): US$1bn Offering at a Near 50% Discount to A-Shares
- Montage Technology (688008 CH) could raise up to HK$8.1bn (US$1.04bn) in its Montage Technology (6809 HK) listing if the Overallotment Option is exercised.
- Nearly half the base offering is allocated to cornerstone investors; those shares are locked up for 6 months. That eliminates the already small possibility of early inclusion to global indexes.
- Montage Technology (6809 HK) should be added to Southbound Stock Connect from the open of trading on 9 March following the end of the Price Stabilisation period.
5. Guoco (53 HK): Now Even A Deeper Value Play
- After GuocoLand (GUOL SP)‘s Offer for Guocoland Malaysia (GUOL MK), it seemed appropriate to revisit Guoco Group (53 HK). Just as well – it is totally bombed out.
- I see Guoco’s implied stub – net of GuocoLand, Hong Leong Financial (HLFG MK), Bank of East Asia (23 HK), and Rank Group (RNK LN) – at a decade low.
- It’s coming up to eight years since the Quek family reloaded an Offer for Guoco. Which subsequently failed. Time for the family to step up. Again.
6. [Japan CorpGov] TSE “Mgmt Conscious” Reports (Feb26) – Disappointing Case Studies, Weak Study Group
- TSE-Listed companies are asked to file “Management Conscious of Capital Cost/Stock Price” awareness reports/policies. Many have. Some are still working on it. And policies change, and CGR reports are updated.
- There were case study updates published late-Dec25. Interesting, but not ground-breaking. 146 CGRs were filed in January after 475 in December 2025. It’s low season til spring.
- The ongoing Study Group to review Minority Shareholder Protection, etc has interim comments suggesting Toyota Fudosan’s claim of Majority of Minority is false (of course it is, but they’re nicer).
7. Makino Milling Machine (6135 JP): Twin Headwinds as Chinese and US Approvals Secured
- Makino Milling Machine Co (6135 JP) has announced that MBK has secured the two highest risk approvals (US CFIUS and China SAMR).
- The remaining approval (Japan) should be obtained by mid-February. However, the offer must now contend with twin headwinds of a bull market and upgraded guidance.
- While MBK’s improving deal economics support a bump, several mitigating factors (such as deal fatigue and no competing bid) suggest a low probability of a bump.
8. MCJ (6670 JP): Bain-Sponsored MBO at JPY2,200
- MCJ Co Ltd (6670 JP) has recommended a Bain-sponsored MBO at JPY2,200, a 43.0% premium to the last close.
- Mr Yuji Takashima (Chairman and CEO) will reinvest to take a 33.1% stake. The offer represents an all-time high and aligns with the midpoint of the IFA DCF valuation range.
- However, the sale process was lacking (no auction) and is light compared to peer multiples. Barring the emergence of an activist, this is a done deal.
9. Same Product, Two Different Prices – The GOLD’en Opportunity
- The price gap between gold on the US Comex and in Shanghai has widened and is significantly larger than normal.
- Price divergence is due to paper vs. physical – the US is mainly driven by futures and paper trading, while Shanghai is real physical supply and demand.
- Arbitrage is not possible due to logistical and regulatory barriers. The gap will have to narrow, with paper gold heading higher to match the physical price!
10. CKH (1 HK): The Courts (Predictably) Annul The Panama Concessions. Now What?
- It was a sure bet Panama’s highest court would annul CK Hutchison Holdings (1 HK)‘s Panama Ports Company (PPC) port contracts. Less clear are the next steps.
- The Panamanian government has tapped AP Moeller – Maersk A/S (MAERSKB DC)‘s APM Terminals as the temporary administrator – or “neutral stabiliser” – via a phased handover of the ports.
- PPC has already indicated it will seek a “clarification” of the ruling. And CKH can still sue the Republic of Panama in international tribunals.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A/Activism] Toyota RE Deal for Toyota Inds (6201) Part II: Trading Through, Buns at Dawn
- When Toyota Fudosan came out with their Tender Offer announcement, I wrote [Japan M&A] Toyota RE Deal for Toyota Inds (6201) Part I; Offensive Process, Light Deal, Bun Fight?
- I intended to write a Part II to address the valuation arguments in the TICO and Bidder docs. I didn’t bother, but worked on other aspects.
- Elliott released a letter on the 18th, and yesterday AM released a 50+ page presentation. It’s compelling. The math is similar to mine above. More new news last night. Fun!
2. Muyuan Foods (2714 HK): US$1.6bn Offering at a Big Discount to A-Shares
- Muyuan Foodstuff Co Ltd A (002714 CH) could raise up to HK$12.3bn (US$1.575bn) in its Muyuan Foods (MUYUAN HK) listing if the Overallotment Option is exercised.
- Exactly half the base offering is allocated to cornerstone investors; those shares are locked up for 6 months. That eliminates the already small possibility of early inclusion to global indexes.
- Muyuan Foods (MUYUAN HK) should be added to Southbound Stock Connect from the open of trading on 6 March following the end of the Price Stabilisation period.
3. Breaking Down Hynix’s Latest Treasury Share Cancellation and ADR Filings, Step by Step
- Hynix is likely dropping treasury-stock ADRs; despite regulatory flexibility, burning shares now then reissuing for ADR would be counterintuitive.
- The move isn’t just optics — Hynix is avoiding ~25% tax on treasury sales by favoring new-share issuance after a big stock run-up.
- With treasury shares bought at KRW 80–90k, tax is real. ADR likely alive via new issuance, as local desks read and after-hours moves confirm.
4. Merger Arb Mondays (26 Jan) – Toyota Ind, Raksul, Mamezo, Skyworth, IJM, ENN, Australian Strategic
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Skyworth Group Limited (751 HK), Ijm Corp Bhd (IJM MK), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Australian Strategic Materials (ASM AU), Webjet Group (WJL AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Raksul Inc (4384 JP), Mamezo (202A JP), Hisamitsu Pharmaceutical Co (4530 JP), Toyota Industries (6201 JP), BioDlink International (1875 HK).
5. Busy Ming (1768 HK): Not so Busy on the Index Inclusions
- Busy Ming Group (1768 HK) is looking to raise up to HK$4.22bn (US$541m) in its IPO, valuing the company at HK$50.7bn (US$6.5bn).
- The large allocation to cornerstone investors reduces free-float market cap and could delay inclusion in global indices. Inclusion in one global index could take place in September at the earliest.
- Busy Ming Group (1768 HK) should be added to the HSCI in June and subsequently added to Southbound Stock Connect.
6. Eastroc Beverage (9980 HK): Index Inclusion Timeline for US$1.5bn Offering
- Eastroc Beverage Group (605499 CH) could raise up to HK$11.7bn (US$1.5bn) in its Eastroc Beverage Group (9980 HK) listing if the Overallotment Option is exercised.
- Half the base offering is allocated to cornerstone investors; those shares are locked up for 6 months. That eliminates the already small possibility of early inclusion to global indexes.
- Eastroc Beverage Group (9980 HK) should be added to Southbound Stock Connect from the open of trading on 2 March following the end of the Price Stabilisation period.
7. [Japan M&A/Activism] Murakami Group Jump into Sankei REIT (2972) Complicating Things
- Friday after the close, City Index Eleventh announced that it and joint holders held 7.36% of Sankei Real Estate (2972 JP) which is currently undergoing a Tender Offer.
- I had said at the beginning this might need a bump. Units opened just above terms on Day 1, stayed at or around. Now they are trading 7% through.
- Murakami group likely controls the outcome here. That could mean a bump. It could mean buying into the bidco as a silent partner. Think of what you’d rather own.
8. Intel on Government KOSDAQ Stimulus: KRW 17tn Annually Via Broker IMA Accounts for 3 Years
- NPS allocation hike to KOSDAQ is dead, so the government’s pivoting to Plan B: push anchor capital via broker IMA accounts and issuance-note products to fix the retail-heavy market.
- The government plans to channel ~KRW 17tn/year from broker IMA accounts into KOSDAQ, creating a sticky three-year flow worth ~7% of market cap, far above retail net buying.
- This is the most aggressive KOSDAQ flow play yet, anchoring sentiment and setting up a near-term uptrend, though weak earnings cap upside. Policy-backed cash makes today’s rip stickier.
9. Samsung Likely to Drop Shareholder Return Update Tomorrow: 1P Spread Pivot
- Looks like a replay of last October’s playbook—family block deal prepped, shares dumped fast, and Samsung likely to drop a value-up–style shareholder return update tomorrow.
- Samsung’s KRW 2.5tn buyback finished ~3 months early, signaling a pre-positioning move ahead of a fresh shareholder return rollout, possibly as soon as tomorrow.
- Best-Case 100% special dividend for 1P spread unlikely; expect a hybrid of conditional dividend plus buybacks. Still enough to pivot near-29% 1P discount. So we need a tactical approach tomorrow.
10. Skyworth (751 HK)’s Spin-Off & CSRC’s (Possible) Stricter Rules
- Back on the 20th January, Skyworth Group Limited (751 HK) announced an inter-conditional Scheme and concurrent listing of 70%-held Skyworth Photovoltaic on the HKEx, by way of introduction.
- I discussed the deal in Skyworth (751 HK): Delisting/Spin-Off Terms Are Fair. Get Involved. Terms appeared fair. Just a question on how best to hedge the transaction.
- On the afternoon of the 23rd Jan, media reports surfaced that CSRC will (reportedly) tighten rules for firms to list in Hong Kong. Nothing definitive, but still worth a discussion.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Toyota Industries (6201 JP): Evaluating Elliott’s Letter
- Elliott has released a letter urging shareholders to reject Toyota Fudosan’s JPY18,800 offer for Toyota Industries (6201 JP).
- Elliott’s letter makes both sensible (the offer is below 3Q book value, with limited downside risk on a deal break) and outlandish (the standalone plan is worth JPY40,000) assertions.
- There is a good chance of a further bump (to JPY21,000), as an offer below the 3Q book value (disclosed on 3 February) will give Elliott’s campaign a huge boost.
2. China ETF: Huge Outflows; National Team Unwinding?
- Over US$55bn has been redeemed from mainland China ETFs over the last 3 weeks. Headline ETFs take the largest hit while there have been inflows to sector ETFs.
- The large-scale redemptions across a variety of indices point to the National Team unwinding holdings that have been built up over the last year.
- Margin trading rules have been tightened, and this could be another way of ensuring that markets do not run-up too far in the short-term.
3. StubWorld: The Maths For A MUCH Higher Bid For Toyota Inds (6201 JP) Remains Compelling
- A double dose of StubWorld this week as I recap the latest developments in Toyota Group’s egregiously low-balled Offer for Toyota Industries (6201 JP).
- Preceding my comments on TICO are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
4. Skyworth (751 HK): A Long-Dated but Attractive Distribution and Share Buyback Scheme Proposal
- Skyworth Group Limited (751 HK) disclosed a preconditional privatisation through a share buyback scheme along with a proposed distribution and listing of Skyworth Photovoltaic shares.
- The offer comprises HK$4.03 + 0.3699779 Skyworth Photovoltaic shares per Skyworth share, for an estimated total value of HK$10.16, representing a 96.1% premium to the last close price.
- While the offer is attractive, the appraised value of Skyworth Photovoltaic is optimistic – my estimated total value is HK$8.43. Timing is the key risk.
5. [Japan M&A/Activism] The Raksul MBO Is In Danger; Bump Clearly Needed
- In [Japan M&A] CEO & Chairman Entice GS to Sponsor an MBO for Recently Lackluster Raksul (4384) I wrote that this deal was at the wrong price, and “eminently block-able.”
- Day1 it traded a lot just above terms, then it went higher, then lower. Today it’s up strongly after a Nikkei article saying Baillie Gifford is unhappy with the price.
- That’s about 14% of the register who is apparently explicitly unhappy with the price. It’s still block-able. There will likely have to be a bump here.
6. StubWorld: WuXi Biologics (2269 HK)’s Double Discounts; Melco (200 HK) Further Out Of Whack
- WuXi XDC Cayman (2268 HK)‘s Offer for BioDlink International (1875 HK) will add an additional discount layer to WuXi Biologics (2269 HK).
- Preceding my comments on WuXi stable – and Melco International Development (200 HK) – are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
7. Skyworth (751 HK): Delisting/Spin-Off Terms Are Fair. Get Involved Here
- Skyworth Group Limited (751 HK) has announced an inter-conditional Scheme and concurrent listing of 70%-held Skyworth Photovoltaic on the HKEx by way of introduction.
- Independent shareholders are offered HK$4.03/share under the Scheme, or new scrip. All shareholders will be in-specied Skyworth Photovoltaic shares with a theoretical value of HK$6.13/share. Or HK$10.16/share all-in.
- Delisting the loss-making old school ops (TVs, set top boxes), and listing the now dominant photovoltaic ops, makes sense. Now it’s just a question of timing.
8. PhonePe IPO: Limited Float & Index Inclusion Timeline
- Phonepe is looking to list on the Indian exchanges with pre-IPO investors looking to sell 50.66m shares at a valuation of US$13.1bn and raising around US$1.3bn in the IPO.
- The stock will not get Fast Entry to either of the global indices. The earliest inclusion in a global index should take place in September.
- The stock should be added to the Large Cap segment in the AMFI Classification in July and to the NSE Nifty Next 50 Index in September.
9. HK Connect SOUTHBOUND Flows (2Wks To 16 Jan 2026) – China Mobile Sold Heavily, Tech Bought Heavily
- HK$128bn+/Day of gross SOUTHBOUND activity the first two weeks of the year, and net buying of HK$43bn.
- Relatively high div low vol SOEs were net sold. Again. China Mobile shellacked with net selling every day for 10 days (actually net sold every day since 11 Dec).
- The data tables below update daily in the Tools section of Smartkarma. The Southbound Flow Monitor and AH Pairs Monitor are both there – free – for all SK readers.
10. CKH (1 HK): Trading Full Ahead Of Supreme Court Ruling
- Panama’s Supreme Court is expected to make a decision shortly on whether CK Hutchison Holdings (1 HK) (“CKH”) will retain the concessions to operate two key Panama Canal ports.
- CKH and Panama’s Comptroller hold diametrically opposite views on the legitimacy of the 2021 licence renewal and operational compliance/status of these ports. To categorise the situation political is an understatement.
- The (largely) expected Panamanian pushback appears factored in, with the market looking further afield to the sale of the remaining 41 global ports. CKH is trading full here.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
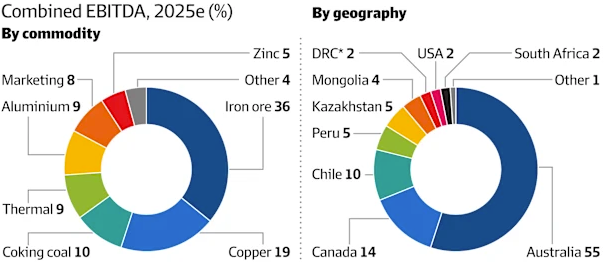
1. Rio Tinto (RIO AU/LN): Glencore Musings
- Back in August 2024, Jakob Stausholm, Rio Tinto (RIO AU)‘s previous CEO, said any stock issuance to fund Arcadium Lithium (LTM AU)‘s takeover would just add a layer of complexity.
- Eight months later, Stausholm “stepped down”, with Simon Trot taking over the reins. Now the mining giant has revived talks with Glencore Plc (GLEN LN), via an all-scrip Offer.
- Given Rio’s dual-headed structure, the deal mechanics for Glencore have not been publicly fleshed out. The drop in the Aussie line is indicative.
2. [Japan M&A] Toyota RE Deal for Toyota Inds (6201) Part I; Offensive Process, Light Deal, Bun Fight?
- ~9 months ago as Japan reeled from Trump’s Tariff Tantrum, Toyota Group announced a potential takeover of Toyota Industries (6201 JP). In June, we got a process+price. Non-transparent. Opportunistic. Unfair.
- They valued the transaction in one way, then announced a transaction structure which immediately changes the entire asset base of the company, and creates huge excess value for the buyers.
- Process is bad. Analysis bad. The Special Committee and Board decisions bad. Sub-1x BVPS. Transaction structure immediately offers an additional 10+% to BVPS in cash to the buyers. It’s offensive.
3. Rio Tinto / Glencore: M&A as a Stress Test for the Dual-Listed Structure
- Rio–Glencore talks revived: Confirmed 9 January, reopening strategic pressure on Rio’s dual-listed structure amid record copper prices and renewed sector consolidation.
- Spread reacts to structure, not sentiment: Ltd–plc premium tightened from ~23% to ~19%, signalling rising market sensitivity to DLC inefficiency under M&A stress.
- Optionality improves, timing uncertain: No unification signal yet, but M&A introduces a forcing mechanism activism failed to deliver.
4. Samsung Pref Pivot: Eyes on H1 Value-Up Disclosure for Special Dividend
- The key is Samsung’s Jan 2024 clause allowing flexible capital returns before the 3-year program ends, sparking Street focus on a possible mid-year special dividend announcement.
- Samsung must drop its Value-Up disclosure before May, with no buyback this year, making it the key vehicle to outline how leftover capital will fund shareholder returns.
- With a May Value-Up filing likely outlining special dividends, it is potentially a pivot point for pref-share momentum and a key trade setup.
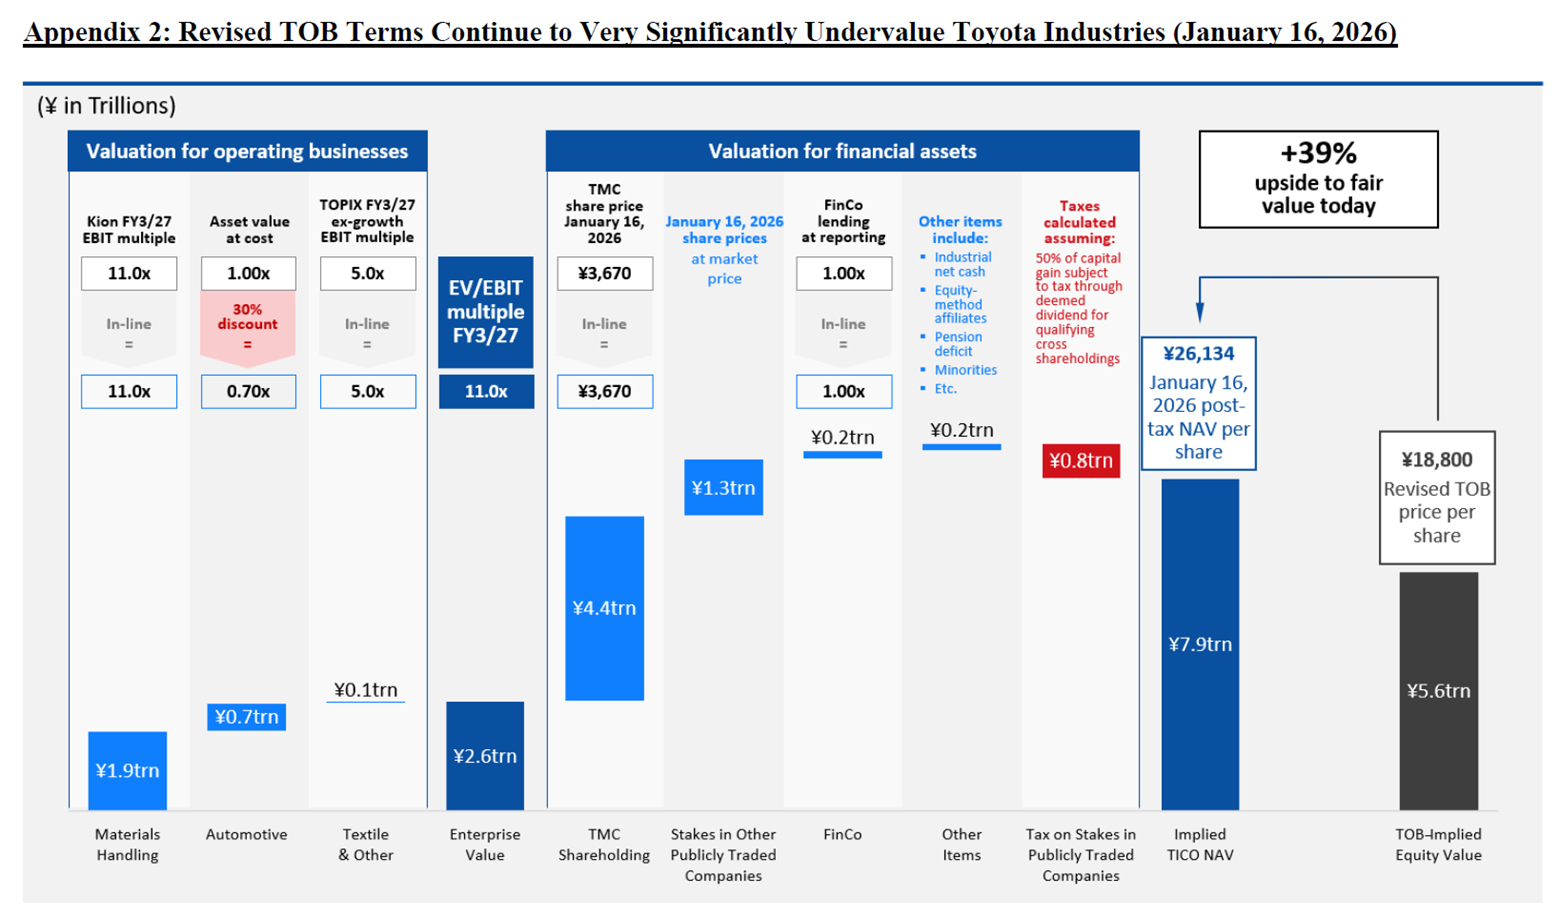
5. Toyota Industries (6201 JP): Toyota Fudosan’s Revised Offer Is Arguably Light
- Toyota Industries (6201 JP) has recommended a revised offer from Toyota Fudosan at JPY18,800, a 15.3% premium to the previous JPY16,300 offer.
- While the revised offer represents an all-time high, it remains arguably light. The revised offer is below the midpoint of the special committee IFA’s SOTP valuation range.
- The revised offer also does not fully account for the increase in value of TICO’s core crossholdings. Elliott is not mentioned in the statement, suggesting a lack of support.
6. Merger Arb Mondays (12 Jan) – Makino, Dongfeng, ENN, Hisamitsu, Pacific Ind, Mandom, Sankei
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Dongfeng Motor (489 HK), ENN Energy (2688 HK), Changhong Jiahua Holdings (3991 HK), Qube Holdings (QUB AU), Makino Milling Machine Co (6135 JP).
- Lowest spreads: Bright Smart Securities (1428 HK), Mandom Corp (4917 JP), Toyota Industries (6201 JP), Raksul Inc (4384 JP), Hisamitsu Pharmaceutical Co (4530 JP), Pacific Industrial (7250 JP).
7. IJM Corp (IJM MK): Sunway’s Cash/Scrip Conditional Voluntary Offer
- Ijm Corp Bhd (IJM MK) disclosed a cash/scrip conditional voluntary offer from Sunway Bhd (SWB MK) valued at RM3.15, a 14.5% premium to the last close price.
- The offer is unattractive as the terms favour Sunway rather than IJM shareholders. The timing is opportunistic, given Sunway’s relative share-price strength vs. IJM.
- The key conditions are Sunway shareholder approval and a 50% minimum acceptance condition. Despite an unattractive offer, both these conditions are low risk.
8. [Japan M&A] KKR Officially Bids ¥3,100 for Mandom (4917), Tender May Start Late January
- This morning, Mandom Corp (4917 JP) gave up an update to the document regarding its “Support” for the MBO at a lower price and the situation regarding the KKR overbid.
- Yesterday, KKR submitted an official ¥3,100/share Bid Intention. This morning, the Board resolved to send the matter to its Special Committee. Shares are trading up.
- The bid is still pre-conditional. KKR being a PE firm, it requires a pre-condition slightly unusual in competitive bidding situations.
9. Dongfeng Motor (489 HK): Regulatory Precondition Satisfied
- Four months after the offer was announced, Dongfeng Motor Corporation has satisfied the regulatory precondition related to its Dongfeng Motor (489 HK) offer.
- The remaining precondition is approval from the CSRC and HKEx, both of which are low-risk. The appraised value of HK$10.85 is the key point of debate.
- The peers have since derated, which affects the appraised value. However, based on several methodologies, I estimate the offer is worth HK$11.51-11.55 per H Share.
10. IJM Corp (IJM MK): Sunway’s Offer Is Light. But Scale Is Key
- Sunway Bhd (SWB MK) has tabled a voluntary RM11bn cash/scrip Offer for IJM Corp Bhd (IJM MK), in a move to combine two of Malaysia’s largest construction and property plays.
- The Jeffrey Cheah-backed Sunway is offering RM3.15/share, split 10% (RM0.315/share) in cash, and RM 2.8350 in new Sunway shares. The key condition is a 50% acceptance hurdle.
- Pricing appears light – IJM traded higher in August 2024. Yet IJM’s bottom line has stalled. Enhanced scale is attractive. A tie-in has been long-rumoured.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
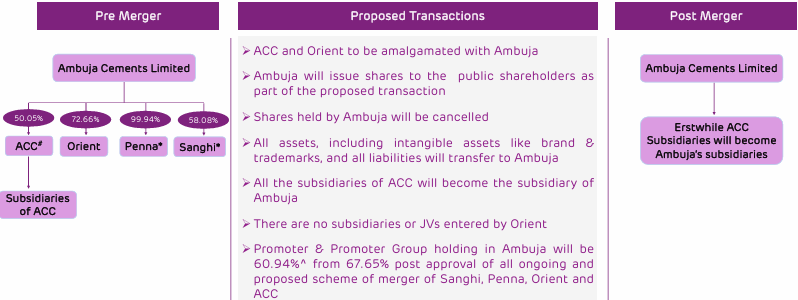
1. Ambuja Cement/ ACC/ Orient Cement Merger: Index Flows
- Ambuja Cements (ACEM IN), ACC Ltd (ACC IN) and Orient Cement (ORCMNT IN) will be merging to create a pan-India cement giant.
- There are a whole bunch of approvals needed, and the mergers are expected to complete in the next 12 months.
- With the stocks part of different indices, there will be index flows on completion of the merger.
2. Merger Arb Mondays (05 Jan) – ENN, Dongfeng, Jinke, ANE, Mandom, Toyota, Qube, Insignia
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Dongfeng Motor (489 HK), ENN Energy (2688 HK), Jinke Smart Services (9666 HK), Changhong Jiahua Holdings (3991 HK), Qube Holdings (QUB AU), Humm Group (HUM AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Toyota Industries (6201 JP), Mandom Corp (4917 JP), Raksul Inc (4384 JP), Low Keng Huat Singapore (LKH SP).
3. Alteogen (196170 KS): Index Impact of KOSDAQ to KOSPI Transfer
- On 6 November, Alteogen Inc (196170 KS)‘s Board approved the delisting of the stock from the KOSDAQ market and the listing on the KOSPI market. Shareholders approved on 8 December.
- Alteogen has not yet applied to the KRX for the listing change. While the listing transfer approval had historically taken around 2-3 months, there have been no approvals recently.
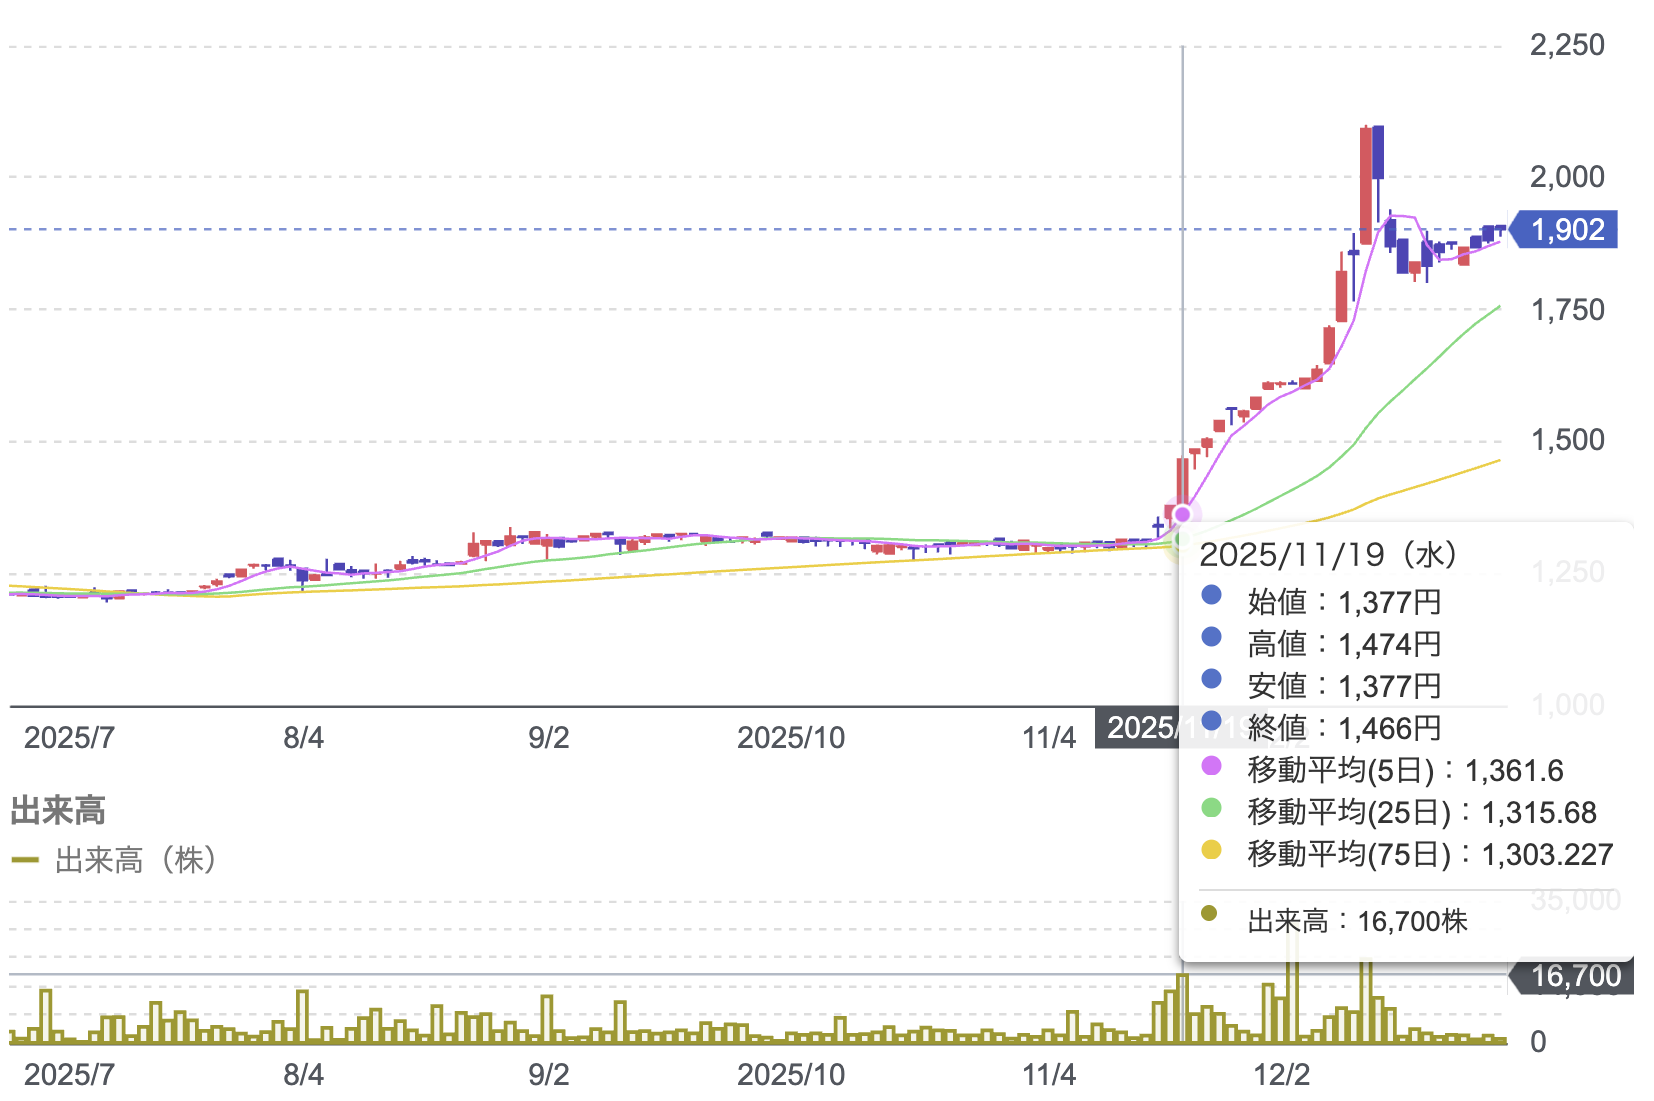
- Alteogen will be deleted from the KOSDAQ150 Index on its last trading day and inclusion in the KOSPI200 Index will take place at the next regular rebalance (or earlier).
4. [Japan M&A] Reports of Hisamitsu “Family” MBO at ~¥450bn (Suggests ¥6400) Preview
- A Bloomberg article mid-morning suggests the 53yr old CEO – a member of the founding family of Hisamitsu Pharmaceutical Co (4530 JP) will launch a ~¥450bn MBO with bank financing.
- Revenues are growing. Earnings less so. It’s not well-covered. It’s an old company with LOTS of cross-holdings and cash. The family doesn’t own much but crossholders do.
- Valuation vs Future Earnings are a question. There are some private holdings which may be worth more than their book value but this may be tough to block.
5. Baidu (9888 HK)’s Spin-Off And Listing Of Kunlunxin
- On the 2nd Jan 2026, Baidu (9888 HK) announced the proposed listing of subsidiary Kunlunxin on the HKEx. The Street promptly bumped its fair values. Shares gained a punchy 9.4%.
- Kunlunxin is Baidu’s AI chip subsidiary, held as to ~59.45%. Baidu’s stake is expected to fall to 51% after the spinoff.
- What is Kunlunxin worth? ~US$3bn if using recent founding rounds; up to US$16-US$23bn according to some Street analysts. Baidu’s market cap is ~US$52bn.
6. Recent Narrative Shift on Hynix ADR Issuance: Focus on Tomorrow (Or Today)’s Re-Disclosure
- Since last weekend, the ruling camp signals ADRs aren’t a loophole; value-accretive ADRs using treasury stock can beat straight burns without policy pushback.
- For now, only Hynix’s treasury-to-ADR story resonates with shareholders; near-term, this narrative stays focused on the memory bellwether with a clear value gap vs peers.
- Hynix’s re-disclosure hits by tomorrow (or today after close), likely still “under review,” but the market may read it as an ADR tilt, potentially driving multiple upside—key near-term radar point.
7. Bluescope Steel (BSL AU): Kerry Stokes-Backed SGH’s NBIO Needs More Gruel
- This morning (6th Jan), SGH Limited (SGH AU) and Steel Dynamics (STLD US) (SDI) confirmed they have submitted an NBIO for Bluescope Steel (BSL AU), Australia’s largest steel manufacturer.
- The Kerry Stokes-backed SGH and SDI are offering A$30/share, a 27% premium to undisturbed. And ~18.6x and 9.5x FY25 EV/EBIT and FY25 EV/EBITDA.
- Regulatory clearance should include FIRB and (perhaps) ACCC. SGH’s entrance should smooth over these conditions.
8. [Japan M&A] Tosei & GIC Bid for Office-Heavy Sankei REIT (2972 JP) At 1.15x PNAV
- Today, Tosei Corp (8923 JP) and GIC announced they would launch a TOB for Sankei Real Estate (2972 JP), which is end-sponsored by Fuji Media Holdings (4676 JP).
- This gets Fuji Media out of a small asset and side business they don’t need, and it clears out a small office-heavy diversified REIT which doesn’t need to exist.
- This is not a bad price. It is not necessarily over the top, but other larger REITs are cheaper. There is some weirdness in holder structure to watch out for.
9. Square Now Top-5 by Float Mkt Cap, Passive Flows in Focus into June 10
- Near to mid term, the key Square vs. Hynix proxy watch is ETF inclusion—but FnGuide and KRX semis ETFs are structurally off-limits without a sector re-tag.
- That leaves TIGER Korea Top 10 and KODEX Top 5 Plus—free-float, mkt-cap ETFs—where Square’s top-10 rank and 67% float turn inclusion from theoretical to tradable.
- TIGER Top 10 is pure float-cap top 10; KODEX Top 5 Plus prioritizes float-cap top 5. Square ranks 4th, qualifying for both, with rebalance at June 10 close.
10. Hisamitsu Pharma (4530 JP): MBO at JPY6,082
- Hisamitsu Pharmaceutical Co (4530 JP) has recommended an MBO at JPY6,082, a 17.0% premium to the last close and in line with Bloomberg’s stated JPY450 billion valuation.
- The offer is attractive compared to precedent transactions and peer multiples. The offer is struck at the midpoint of the IFA DCF valuation range.
- The sheer number of irrevocables and the presence of several cross-holders will aid in deal completion. The tender closes on 19 February.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A] Regional Bank Consolidation Efforts May Pick Up
- Regional bank consolidation is on the menu in Japan. Expect more of it.
- Intra-Prefecture is the obvious case. In rural prefectures, JA and the Post Bank are credible deposit-taker competition. SME lending is less obvious, though cross-border (neighbouring prefecture) combinations could arise.
- A new transaction suggests another combination is on its way. I’d buy.
2. Biren Tech (6082 HK) IPO: Index Inclusion Possibilities & Timeline
- Shanghai Biren Technology (6082 HK) has raised HK$5.58bn (US$717m) in its IPO, valuing the company at HK$46.96bn (US$6.03bn). The raise size could increase if the overallotment option is exercised.
- The large allocation to cornerstone investors reduces free float market cap and could delay inclusion in global indices. Inclusion could take place in May/June or August/September.
- Shanghai Biren Technology (6082 HK) should be added to the HSCI in June and subsequently added to Southbound Stock Connect.
3. Tender Offer of a 56.4% Stake in Echo Marketing by Bain Capital
- On 1 January 2026, it was reported that Bain Capital has launched a tender offer to acquire a 56.4% stake in Echo Marketing, the parent company of Andar.
- Tender offer price is 16,000 won (49.5% higher than closing price on 31 December 2025).
- After acquiring Andar in 2021, Echo Marketing transformed the company into Korea’s leading athleisure brand. It is considered a rival to global sportswear brand Lululemon.
4. Merger Arb Mondays (29 Dec) – Toyota Ind, Logisnext, Pacific Ind, Jinke, ENN, Changhong Jiahua
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Dongfeng Motor (489 HK), Jinke Smart Services (9666 HK), ENN Energy (2688 HK), Humm Group (HUM AU), Qube Holdings (QUB AU), Changhong Jiahua Holdings (3991 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Mandom Corp (4917 JP), Toyota Industries (6201 JP), Raksul Inc (4384 JP), Ainsworth Game Technology (AGI AU).
5. Jinke Smart Services (9666 HK): Delisting Resolution Passed, but Now for the Hard Part
- Boyu’s enhanced offer (HK$8.69) for Jinke Smart Services (9666 HK) requires satisfaction of the delisting resolution and the delisting acceptance condition (90% minimum acceptance from disinterested shareholders).
- On 24 December, the delisting resolution was comfortably passed with 99.37% of disinterested shares voting in favour. The disinterested shareholder participation rate was 67.4%.
- However, the key data points from the EGM results suggest that satisfying the delisting acceptance condition is increasingly challenging. The closing date is 26 January.
6. ENN Energy (2688 HK): Regulatory Precondition Satisfied
- Nine months after the offer was announced, ENN Natural Gas (600803 CH) has satisfied the regulatory precondition related to its ENN Energy (2688 HK) offer.
- The remaining precondition is approval from CSRC and HKEx, which are low-risk. The long stop date is 13 March 2026, which may have to be extended.
- The appraised offer HK$80.00 value is the key debating point. Based on several methodologies, I estimate a realistic offer value of HK$78.53 (range of HK$71.85 to HK$89.72).
7. Event Driven: Coforge Acquisition ~ The Fall Analysis
- Coforge (COFORGE IN) ’s stock fell 9.5% in five sessions as investors reacted to the massive equity dilution triggered by the board’s approval to acquire Encora.
- The $2.35 billion all-stock deal aims to create a scaled AI-led engineering powerhouse, significantly expanding Coforge’s presence in LATAM and the US.
- While massive share issuance creates a short-term headwind, the acquisition is structurally accretive, targeting$2.5 billion in revenue without diluting consolidated earnings.
8. HSCI / Hong Kong Connect Inclusion (March 2026): A Preliminary Assessment
- We identify stocks likely to be added to the Hang Seng Composite Index in the upcoming review and, in turn, become eligible for Hong Kong Stock Connect.
- Using market cap, free float and liquidity screens, we compile a preliminary list of potential inclusion candidates ahead of the review cut-off.
- A follow-up note will focus on which inclusion candidates are most likely to translate eligibility into actionable trading opportunities.
9. TIGER Semis ETF: Hynix Cut Spurs ₩200B Passive Out, 8 Smaller Names Soak Cash Jan 5
- This 10-name ETF saw Hynix stay above 30% over December’s last five sessions. FnGuide updates weights Jan 6, with TIGER rebalancing off Jan 5 close.
- This ETF’s first ad-hoc rebalance plus ₩1T Q4 retail inflows push AUM to ₩2.9T, making it Korea’s largest sector ETF. Price swings could get wild.
- Hynix dropping from 32% to 25% triggers ₩200B passive out, while eight smaller names soak cash. Single-day ad-hoc flow could drive notable price impact despite high volumes.
10. (Mostly) Asia M&A, Dec 2025 Wrap: ANE Cayman, Mandom, Predictive Discovery, Hogy Medical
- For December 2025, 5 new transactions (firm and non-binding) were discussed on Smartkarma (by the Quiddity team) with an overall announced deal size of just ~US$3bn.
- The average premium for the new transactions announced (or first discussed) in December was ~87%, with a year-to-date average of ~49%.
- The average premiums for transactions in 2024 (124 transactions), 2023 (114), 2022 (104), 2021 (143), 2020 (133), and 2019 (110) were 43%, 39%, 41%, 33%, 31%, and 31%.