
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A] Regional Bank Consolidation Efforts May Pick Up
- Regional bank consolidation is on the menu in Japan. Expect more of it.
- Intra-Prefecture is the obvious case. In rural prefectures, JA and the Post Bank are credible deposit-taker competition. SME lending is less obvious, though cross-border (neighbouring prefecture) combinations could arise.
- A new transaction suggests another combination is on its way. I’d buy.
2. Biren Tech (6082 HK) IPO: Index Inclusion Possibilities & Timeline
- Shanghai Biren Technology (6082 HK) has raised HK$5.58bn (US$717m) in its IPO, valuing the company at HK$46.96bn (US$6.03bn). The raise size could increase if the overallotment option is exercised.
- The large allocation to cornerstone investors reduces free float market cap and could delay inclusion in global indices. Inclusion could take place in May/June or August/September.
- Shanghai Biren Technology (6082 HK) should be added to the HSCI in June and subsequently added to Southbound Stock Connect.
3. Tender Offer of a 56.4% Stake in Echo Marketing by Bain Capital
- On 1 January 2026, it was reported that Bain Capital has launched a tender offer to acquire a 56.4% stake in Echo Marketing, the parent company of Andar.
- Tender offer price is 16,000 won (49.5% higher than closing price on 31 December 2025).
- After acquiring Andar in 2021, Echo Marketing transformed the company into Korea’s leading athleisure brand. It is considered a rival to global sportswear brand Lululemon.
4. Merger Arb Mondays (29 Dec) – Toyota Ind, Logisnext, Pacific Ind, Jinke, ENN, Changhong Jiahua
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Dongfeng Motor (489 HK), Jinke Smart Services (9666 HK), ENN Energy (2688 HK), Humm Group (HUM AU), Qube Holdings (QUB AU), Changhong Jiahua Holdings (3991 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Mandom Corp (4917 JP), Toyota Industries (6201 JP), Raksul Inc (4384 JP), Ainsworth Game Technology (AGI AU).
5. Jinke Smart Services (9666 HK): Delisting Resolution Passed, but Now for the Hard Part
- Boyu’s enhanced offer (HK$8.69) for Jinke Smart Services (9666 HK) requires satisfaction of the delisting resolution and the delisting acceptance condition (90% minimum acceptance from disinterested shareholders).
- On 24 December, the delisting resolution was comfortably passed with 99.37% of disinterested shares voting in favour. The disinterested shareholder participation rate was 67.4%.
- However, the key data points from the EGM results suggest that satisfying the delisting acceptance condition is increasingly challenging. The closing date is 26 January.
6. ENN Energy (2688 HK): Regulatory Precondition Satisfied
- Nine months after the offer was announced, ENN Natural Gas (600803 CH) has satisfied the regulatory precondition related to its ENN Energy (2688 HK) offer.
- The remaining precondition is approval from CSRC and HKEx, which are low-risk. The long stop date is 13 March 2026, which may have to be extended.
- The appraised offer HK$80.00 value is the key debating point. Based on several methodologies, I estimate a realistic offer value of HK$78.53 (range of HK$71.85 to HK$89.72).
7. Event Driven: Coforge Acquisition ~ The Fall Analysis
- Coforge (COFORGE IN) ’s stock fell 9.5% in five sessions as investors reacted to the massive equity dilution triggered by the board’s approval to acquire Encora.
- The $2.35 billion all-stock deal aims to create a scaled AI-led engineering powerhouse, significantly expanding Coforge’s presence in LATAM and the US.
- While massive share issuance creates a short-term headwind, the acquisition is structurally accretive, targeting$2.5 billion in revenue without diluting consolidated earnings.
8. HSCI / Hong Kong Connect Inclusion (March 2026): A Preliminary Assessment
- We identify stocks likely to be added to the Hang Seng Composite Index in the upcoming review and, in turn, become eligible for Hong Kong Stock Connect.
- Using market cap, free float and liquidity screens, we compile a preliminary list of potential inclusion candidates ahead of the review cut-off.
- A follow-up note will focus on which inclusion candidates are most likely to translate eligibility into actionable trading opportunities.
9. TIGER Semis ETF: Hynix Cut Spurs ₩200B Passive Out, 8 Smaller Names Soak Cash Jan 5
- This 10-name ETF saw Hynix stay above 30% over December’s last five sessions. FnGuide updates weights Jan 6, with TIGER rebalancing off Jan 5 close.
- This ETF’s first ad-hoc rebalance plus ₩1T Q4 retail inflows push AUM to ₩2.9T, making it Korea’s largest sector ETF. Price swings could get wild.
- Hynix dropping from 32% to 25% triggers ₩200B passive out, while eight smaller names soak cash. Single-day ad-hoc flow could drive notable price impact despite high volumes.
10. (Mostly) Asia M&A, Dec 2025 Wrap: ANE Cayman, Mandom, Predictive Discovery, Hogy Medical
- For December 2025, 5 new transactions (firm and non-binding) were discussed on Smartkarma (by the Quiddity team) with an overall announced deal size of just ~US$3bn.
- The average premium for the new transactions announced (or first discussed) in December was ~87%, with a year-to-date average of ~49%.
- The average premiums for transactions in 2024 (124 transactions), 2023 (114), 2022 (104), 2021 (143), 2020 (133), and 2019 (110) were 43%, 39%, 41%, 33%, 31%, and 31%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiyo Holdings (4626 JP): An Impending KKR Takeunder?
- On 19 December, Bloomberg reported that KKR has emerged as a frontrunner to privatise Taiyo Holdings (4626 JP), but “the tender offer price may be lower than the current price.”
- Since the first Bloomberg article on 27 May, Taiyo’s shares are up 84% vs. the median peers’ shares, which are up 62%. Therefore, the shares reflect some takeover premium.
- Based on the medium-term management plan, which is likely KKR’s base case, I estimate a tender offer of around JPY4,624, 1.2% below the last close.
2. Aimed Bio Set for KOSDAQ 150 Fast-Entry: Selvas AI Faces Exit
- Aimed Bio (Dec 4 IPO) averages KRW 3.81tn mkt cap, 1.52tn free-float, clearing KOSDAQ 150 fast-entry hurdles vs #30 Pearl Abyss (2.40tn).
- Selvas AI exits KOSDAQ 150; KRX announces Aimed Bio fast-entry after tomorrow’s close, effective next trading day post front-month KOSPI 200 futures expiry, March 13.
- Aimed Bio faces ~0.3–0.4x DTV, Selvas AI ~1.0–1.2x DTV outflows; key alpha likely at fast-entry announcement, prompting a potential post-close setup tomorrow.
3. March KOSPI Size Rebalance: Sanity-Check for Front-Run Angles
- LARGE stands at 99 post-HD Hyundai Mipo merger; March sees 5 into LARGE (including Samsung Epis), 4 to MID, with top movers comfortably above cutoff and MID gaps watchable.
- Two points: any names riding carryover rally momentum and mid-cap flows rising on sector rotation; LARGE candidates are hitting a pause phase, while top MID movers show clear rebound.
- Distortion risks should ease by T-1M; if sector rotation ramps, price action could occur earlier than usual—worth monitoring.
4. Doosan Corp To Sell 18.05% Stake in Doosan Robotics for 948 Billion Won
- On 23 December, Doosan Corp (000150 KS) announced that it plans to sell an 18.05% stake (11.7 million shares) in Doosan Robotics (454910 KS) for 948 billion won.
- It appears that the main purpose of sale is to secure adequate capital for Doosan Corp to acquire SK Siltron which is up for sale.
- SK Siltron’s corporate value is estimated at around 5 trillion won, so the transaction size for the 70.6% stake up for sale is expected to 3-4 trillion won+.
5. Merger Arb Mondays (22 Dec) – Dongfeng, Jinke, ANE, ENN, Makino, Pacific Ind, Raksul, Toyota Ind
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Smart Share Global (EM US), Dongfeng Motor (489 HK), ENN Energy (2688 HK), Jinke Smart Services (9666 HK), Humm Group (HUM AU), Qube Holdings (QUB AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Mandom Corp (4917 JP), Toyota Industries (6201 JP), Pacific Industrial (7250 JP), Ainsworth Game Technology (AGI AU), Hainan Meilan International Airport (357 HK).
6. OCI Global’s Merger
-
In what can only be described as a masterclass in public equity value destruction disguised as strategic transformation, OCI Global (Euronext: OCI) announced on December 9, 2025, a proposed merger with Orascom Construction.
-
This merger represents capitulation by independent directors and a betrayal of minority shareholders at an exchange ratio of 0.4634 Orascom Construction shares per OCI share, implying a valuation of approximately €3.73 per OCI share, prior to a 15% withholding tax. Post-tax, it is worth €3.17 on a stock trading at €3.00.
- The deal delivers a cash-rich, debt-free liquidating balance sheet into the hands of a controlling shareholder at a deep discount while stranding minority shareholders in illiquid foreign-listed paper with tax leakage.
7. KT Treasury Burn: Flow Distortion & Sticky ADR Premium Trade Angle
- Structural foreign-cap tightness blocks ADR issuance, disabling arb and making KT’s ADR premium sticky and persistently elevated, especially in high-vol premium expansion phases.
- KT’s ADR premium ranged ~0–10% this year, trending higher when local shares sold off, then reversing lower as onshore prices turned up into year-end.
- KT’s gradual treasury burn tied to foreign flows may distort onshore trading and cap upside, while ADR premiums stay structurally pinned, creating a clear window for underlying/ADR trades.
8. A/H Premium Tracker (Wk to 19 Dec 2025): Hs Underperform Again, Beautiful Skew Behaving Badly
- Hs within the liquid AH pair universe UNDER-performed As on average by 0.87%. Beautiful Skew behaved BADLY. Spreads were a bit all over the place.
- Quiddity H/A Portfolio performance slightly positive (+11-13bp). Low H/A “beta” helps. Stay the Beautiful Skew course.
- The data tables below update daily in the Tools section of Smartkarma. The Southbound Flow Monitor and AH Pairs Monitor are both there – free for all SK readers.
9. Korea Small Cap Gem #51: Hanssem (Cancellation of 29.5% of Outstanding Shares)
- After the market close on 22 December, Hanssem Co Ltd (009240 KS) announced that it will cancel all of its 6.933 million treasury shares (29.5% of outstanding shares).
- The fact that this share cancellation is a whopping 29.5% of outstanding shares is likely to result in a sharply higher share price for Hanssem in the next several days.
- We believe that this massive treasury shares cancellation is likely to have a significantly positive impact on Hanssem’s share price in the next several days/weeks.
10. HK Connect SOUTHBOUND Flows (Wk To 19 Dec 2025) – Lower Activity, Net Buying, but High-Div SOEs Sold
- HK$82bn+/Day of gross SOUTHBOUND activity last week vs HK$90+bn the week before. Gross flows are winding down. Net rebounded to +HK$16bn.
- Relatively high div low vol SOEs were net sold. Again. This is getting heavy. It matters because some have less international buying support (they are Trump military names).
- The data tables below update daily in the Tools section of Smartkarma. The Southbound Flow Monitor and AH Pairs Monitor are both there – free – for all SK readers.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Makino Milling Machine (6135 JP): Progress Update While Mixed, Should Calm Nerves
- On Friday, after market close, Makino Milling Machine Co (6135 JP) finally issued a progress update on the MBK preconditional tender offer. The update, while mixed, should calm nerves.
- The positive read-across is a pathway to regulatory approvals, the Homeplus saga has not derailed the offer, and the likely breach of the long-stop date is not a termination event.
- The negative read-across is the lack of a revised tender start timeline, an unexplained delay in securing most regulatory approvals and ongoing uncertainty on the long-stop date.
2. Merger Arb Mondays (15 Dec) – Toyota Ind, Makino, Raksul, Pacific Ind, Jinke, Meilan Airport, NSR
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Smart Share Global (EM US), Dongfeng Motor (489 HK), Raksul Inc (4384 JP), Jinke Smart Services (9666 HK), Qube Holdings (QUB AU), ENN Energy (2688 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Toyota Industries (6201 JP), Hainan Meilan International Airport (357 HK), Ainsworth Game Technology (AGI AU).
3. [Japan M&A] Nikkei Reports KKR Has Proposed an Overbid for Mandom (4917) At ¥2800+
- The Nikkei came out post-close with an article saying that KKR had offered “more than 10%” (“higher than ¥2,800”) for Mandom Corp (4917 JP) vs the revised ¥2,520 CVC Bid.
- Mandom announced a revision to the Opinion Statement to include some but not a lot of details. That triggers an extension to the deal, closing 5 Jan vs 18 Dec.
- The language in the Mandom release is kind of interesting. This price gets us closer, but it may not be high enough.
4. [Japan M&A] Nippon Life Shoots the Lights Out with a Bid at ¥1,693
- Over the weekend the Nikkei reported that Nippon Life would bid ¥60bn for Medical Data Vision (3902 JP). At one price per share, that meant ¥1,585.
- There is a deemed dividend treatment buyback for SBI at ¥1,189 which means they will end up with a capital loss (their in-price is ¥1,630) but they’ll offset that.
- This is the biggest win for minorities in a long while. Be happy.
5. ANE Cayman (9956 HK): Shareholder Vote On 9th Jan. No Mention Of CDH In Latest Doc
- Back on the 28th October, ANE Cayman (9956 HK), a road freight transportation play, announced an Offer from Centurium Partners, a pre-IPO investor, Temasek, and Singapore-based asset manager True Light.
- The Scheme Doc is now out, with a Scheme Meeting on the 9th Jan 2026, and expected payment on the 16th Feb. The IFA (Anglo Chinese) says “fair & reasonable“.
- Noticeably absent from this Doc is CDH, believed to be in control of ~18% of shares out. Given precedents with similar fact patterns, this is probably one deal to avoid.
6. Hang Seng (11 HK): 8th Jan Vote On HSBC’s Offer. Clean Deal.
- Back on the 9th October, Hang Seng Bank (11 HK) announced an Offer from controlling parent, HSBC Holdings (5 HK), by way of a Scheme.
- HSBC offered HK$155/share, a 30.3% premium to last close. The price was final. A third interim dividend was bolted on. Optically – and fundamentally – the price was bang on.
- The Scheme Doc is now out, with the Court Meeting on the 8th January 2026. Payment around 4th Feb. The IFA, in a bare-bones report, concluded “fair & reasonable”.
7. [Japan M&A] Hogy Medical (3593) Carlyle Launches Their TOB at ¥6700, Dalton Agrees But Buys Back In
- Hogy Medical (3593 JP) and Carlyle have announced the Tender Offer at ¥6700, mooted by the Nikkei and confirmed by Hogy the other day.
- The big activist Dalton Group with 27+% has agreed to tender, but has also agreed to buy back into Bidco, owning 20%.
- When the activist pushing for a deal decides not to sell, and instead to continue owning, the price is probably a bit light for everyone else, but this gets done.
8. Local Desks Target Year-End Dividend Boost Trading Setup
- Names outside the new tax regime may hike year-end payouts, with gov’t push boosting odds despite fuzzy timing, drawing local desk interest.
- With timing murky, local desks are targeting high-yield names, 25–40% FY25 payout, and ~10%+ DPS growth as prime candidates for year-end dividend hikes ahead of AGMs.
- Nine first-tier names (25–40% payout, <10% DPS growth, 3%+ yield) are prime dividend plays; five second-tier names (20–25% payout) need monitoring for potential Q4 expense tweaks.
9. Mandom (4917 JP): When You Thought It Was Done, KKR Emerges as a Competing Bidder
- Mandom Corp (4917 JP) has disclosed that it has received a non-binding letter of intent from a third-party candidate, with purchase prices exceeding the CVC JPY2,520 offer.
- The Nikkei identifies the bidder as KKR and states that the offer is over JPY2,800, a 11.1% premium to the CVC offer. KKR want a Board-recommended offer.
- CVC has extended the close of its offer to 5 January 2026, but will need to revise terms as its irrevocables (particularly Murakami and Hibiki) can switch to KKR.
10. Fresh Intel Just in on KRX’s L2 Warning Revamp
- “Effective immediately” matters for L2 exit timing and re-flag risk; KRX confirmed year-end announcement with instant rollout, making year-end the key flow inflection if big L2 names get exempted.
- Large caps (₩10tn+ market cap) pulled from market-warning universe, with L2 tagging now factoring relative outperformance, not just absolute price gains, to curb overuse.
- Of 33 L2 names, five KOSPI blue chips see re-flag risk drop after their mandatory 10-day lockup; near-term trades focus on timing these expiries for relief rallies and flow resets.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. AU Small Finance Bank (AUBANK IN): Increased FOL & Large Passive Flows/ Impact
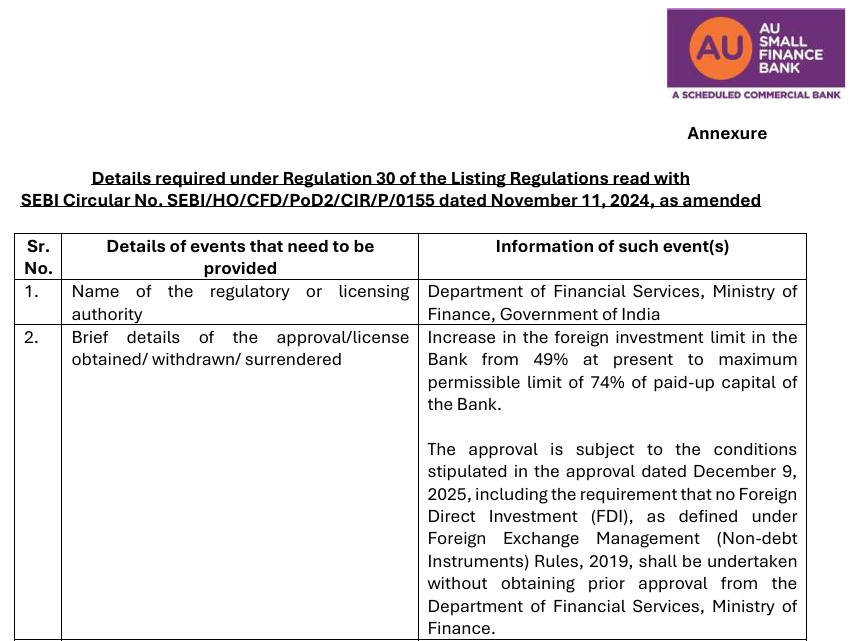
- AU Small Finance Bank Limited (AUBANK IN) has received approval from the Ministry of Finance to increase its Foreign Ownership Limit from 49% to 74% (the maximum permitted).
- The increased FOL will result in passive inflows from global index trackers in February and March. The inflows are multiple days of ADV.
- There has been little increase in positioning. The increased Foreign Ownership Limit and the passive flows to come could lead to the stock moving higher over the next few weeks.
2. More Detailed Insight into Hynix’s Internal Situation Regarding the ADR Issue
- They’re maxing out M15X ahead of schedule, facing a fab gap until ’27, and now need more capex than their KRW 28tn cash pile comfortably covers.
- SK doesn’t want an Hynix ADR; they’re focused on tapping the KRW 150tn Growth Fund to fill the capex gap while avoiding dilution and protecting their already-fragile control stack.
- ADR noise spiked because Hynix’s near-term capex needs exceed Growth Fund capacity, pushing them toward a 2.4% treasury dump—but I still don’t see SK pulling the ADR trigger.
3. Toyota Industries (6201 JP): Elliott Ramps up the Pressure
- Elliott has filed a substantial shareholder notice reporting a Toyota Industries (6201 JP) ownership of 16.3 million or 5.01% of outstanding shares.
- The disclosure is likely a tactic to pressure Toyota Fudosan (offeror) and also a useful signalling tactic to other minorities that Elliott is committed to securing a bump.
- A potential bump could reach JPY19,000. While this would require an additional US$4 billion, financing should not be an issue as the book value (understated) is close to JPY18,000.
4. Makino Milling Machine (6135 JP): Tender Offer Risk/Reward
- Makino Milling Machine Co (6135 JP)’s pre-conditional tender offer from MBK Partners is at JPY11,751 per share. The gross spread has increased to 9.9% due to several concerns.
- The wide gross spread reflects the risk in satisfying the precondition, the fallout from the Homeplus saga and breaching the long stop date (16 January 2026).
- While these concerns have merit, there are mitigating factors. The risk/reward is favourable as the upside (9.9% spread) exceeds the downside (6.3% to my estimated deal break price).
5. Read-Through on the Samsung/Hynix ADR-Listing Noise
- ADR odds are tiny. Both Samsung and Hynix have thin control stakes, making governance risk too high. Neither is willing to chase a valuation pop at the expense of stability.
- Still can’t ignore it, since the ADR chatter is meaningfully swinging the pair trades. Samsung pref spread and Hynix/Square are both getting pushed around.
- ADR noise cooled today, but it can easily resurface and skew the setup. Treat as noise, but be ready to hit aggressive reversion trades when it pops again.
6. [Japan Activism/M&A] Activist Launches Partial Tender to Put Microcap Broadmedia (4347 JP) In Play
- Today after the close, Broadmedia Corp (4347 JP) announced that UK-based Japan activist AVI and one of its funds would launch a tender offer for just over 10% of shares.
- The Tender Offer comes at a 29.5% premium, and it would take the activist to ~40% – close to board-spilling influence.
- This creates an interesting setup. One wonders whether this is meant to spill the Board post-tender, and whether the Company will seek alternate solutions.
7. [Japan M&A] CEO & Chairman Entice GS to Sponsor an MBO for Recently Lackluster Raksul (4384)
- Raksul Inc (4384 JP) is a business roll-up business. They do printing, and advertising, and marketing, and supply. They want to be all things to all SMEs.
- They are pretty good at it. Revenues and EBIT have been growing at 20-30% a year for years, and are scheduled to grow 19% and 26% for several years ahead.
- The bid is up 40% from last, but that gets them to a 30-month high. The register is very open. Lots of active institutional shareholders who have to agree. Maybe.
8. A Potential Listing of ADRs for SK Hynix Using Its Treasury Shares?
- According to numerous local media, SK Hynix is considering on listing its treasury shares (2.4% of outstanding shares representing 17.4 million shares) as ADRs.
- SK Hynix could cancel its treasury shares or list them as ADRs. The bigger bang for the buck will likely be to list them as ADRs.
- By listing its shares as ADRs, the valuation gap between SK Hynix and other listed peers (such as MU and TSMC) could be reduced.
9. Strategy (MSTR US)’s Bitcoin Premium Evaporates. And Then Some
- Strategy (MSTR US)‘s market cap has for near-on five years, traded at a premium to its bitcoin holdings.
- The backbone of Strategy’s levered strategy is issue new shares or debt, acquire more bitcoins, which in turn, boost the share price. Rinse and repeat. Until the music stops.
- That market cap is now at its widest discount in five years. And chairman Michael Saylor scandalously mooted the company may sell some bitcoins IF the discount persists.
10. Hynix & Square L2 Flags Set to Squeeze Spread Near Term
- SK Hynix and SK Square hit L2 flags; cash-only until Dec 24. Margin off, >40% two-day rip triggers halt. L2 lifts if below T-5/+45%, T-15/+75%, and 15-day high.
- L2’s usually a non-event, but this time the margin freeze probably smacks Hynix harder. Key trigger is staying below the 15-day high: Hynix ₩587,000, Square ₩324,000.
- Govt set to roll out AI-semiconductor holdco deregulation this week, boosting AI holdcos like Square and juicing a near-term Square-over-Hynix trade opportunity.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan M&A] Toyota Inds (6201) – Process ALWAYS Bad, Price Bad To Worse; Easily Worth ¥20k+
- In April there was a story suggesting Toyota Group would buy out Toyota Industries (6201 JP). In June, they announced a deal. It was a BAD DEAL.
- The price was low, but it was BAD governance because it was the WRONG DEAL. TICO’s Board declared a valuation fair for a deal not announced, ignoring the ACTUAL DEAL.
- The valuation? Assumed no changes to the business. Actual deal? Sell 90+% of net assets driving 50% of net income, buy back 24+% of shares at discount.
2. [Japan Partial Tender] AEON (8267) Partial Offer for TSURUHA (3391) Announced at ¥2,900/Share
- Tsuruha Holdings (3391 JP) had been planning to release a Medium Term Management Plan this month BUT stock prices are higher, goodwill effects changed, so they announced a “Vision” instead.
- Today post-close, Aeon Co Ltd (8267 JP) announced its Partial Tender Offer on TSURUHA (Japanese) at ¥2,900/share. Slightly lower than hoped. Much better than before.
- AEON obviously really did not want to bump, but they did, considering synergies and the desire to consummate the deal. The Tender Offer shrinks so minimum pro-ration is lower.
3. [Japan M&A] Possible Partial TSURUHA (3391 JP) Tender Changes – More Accretion! Smaller Tender?
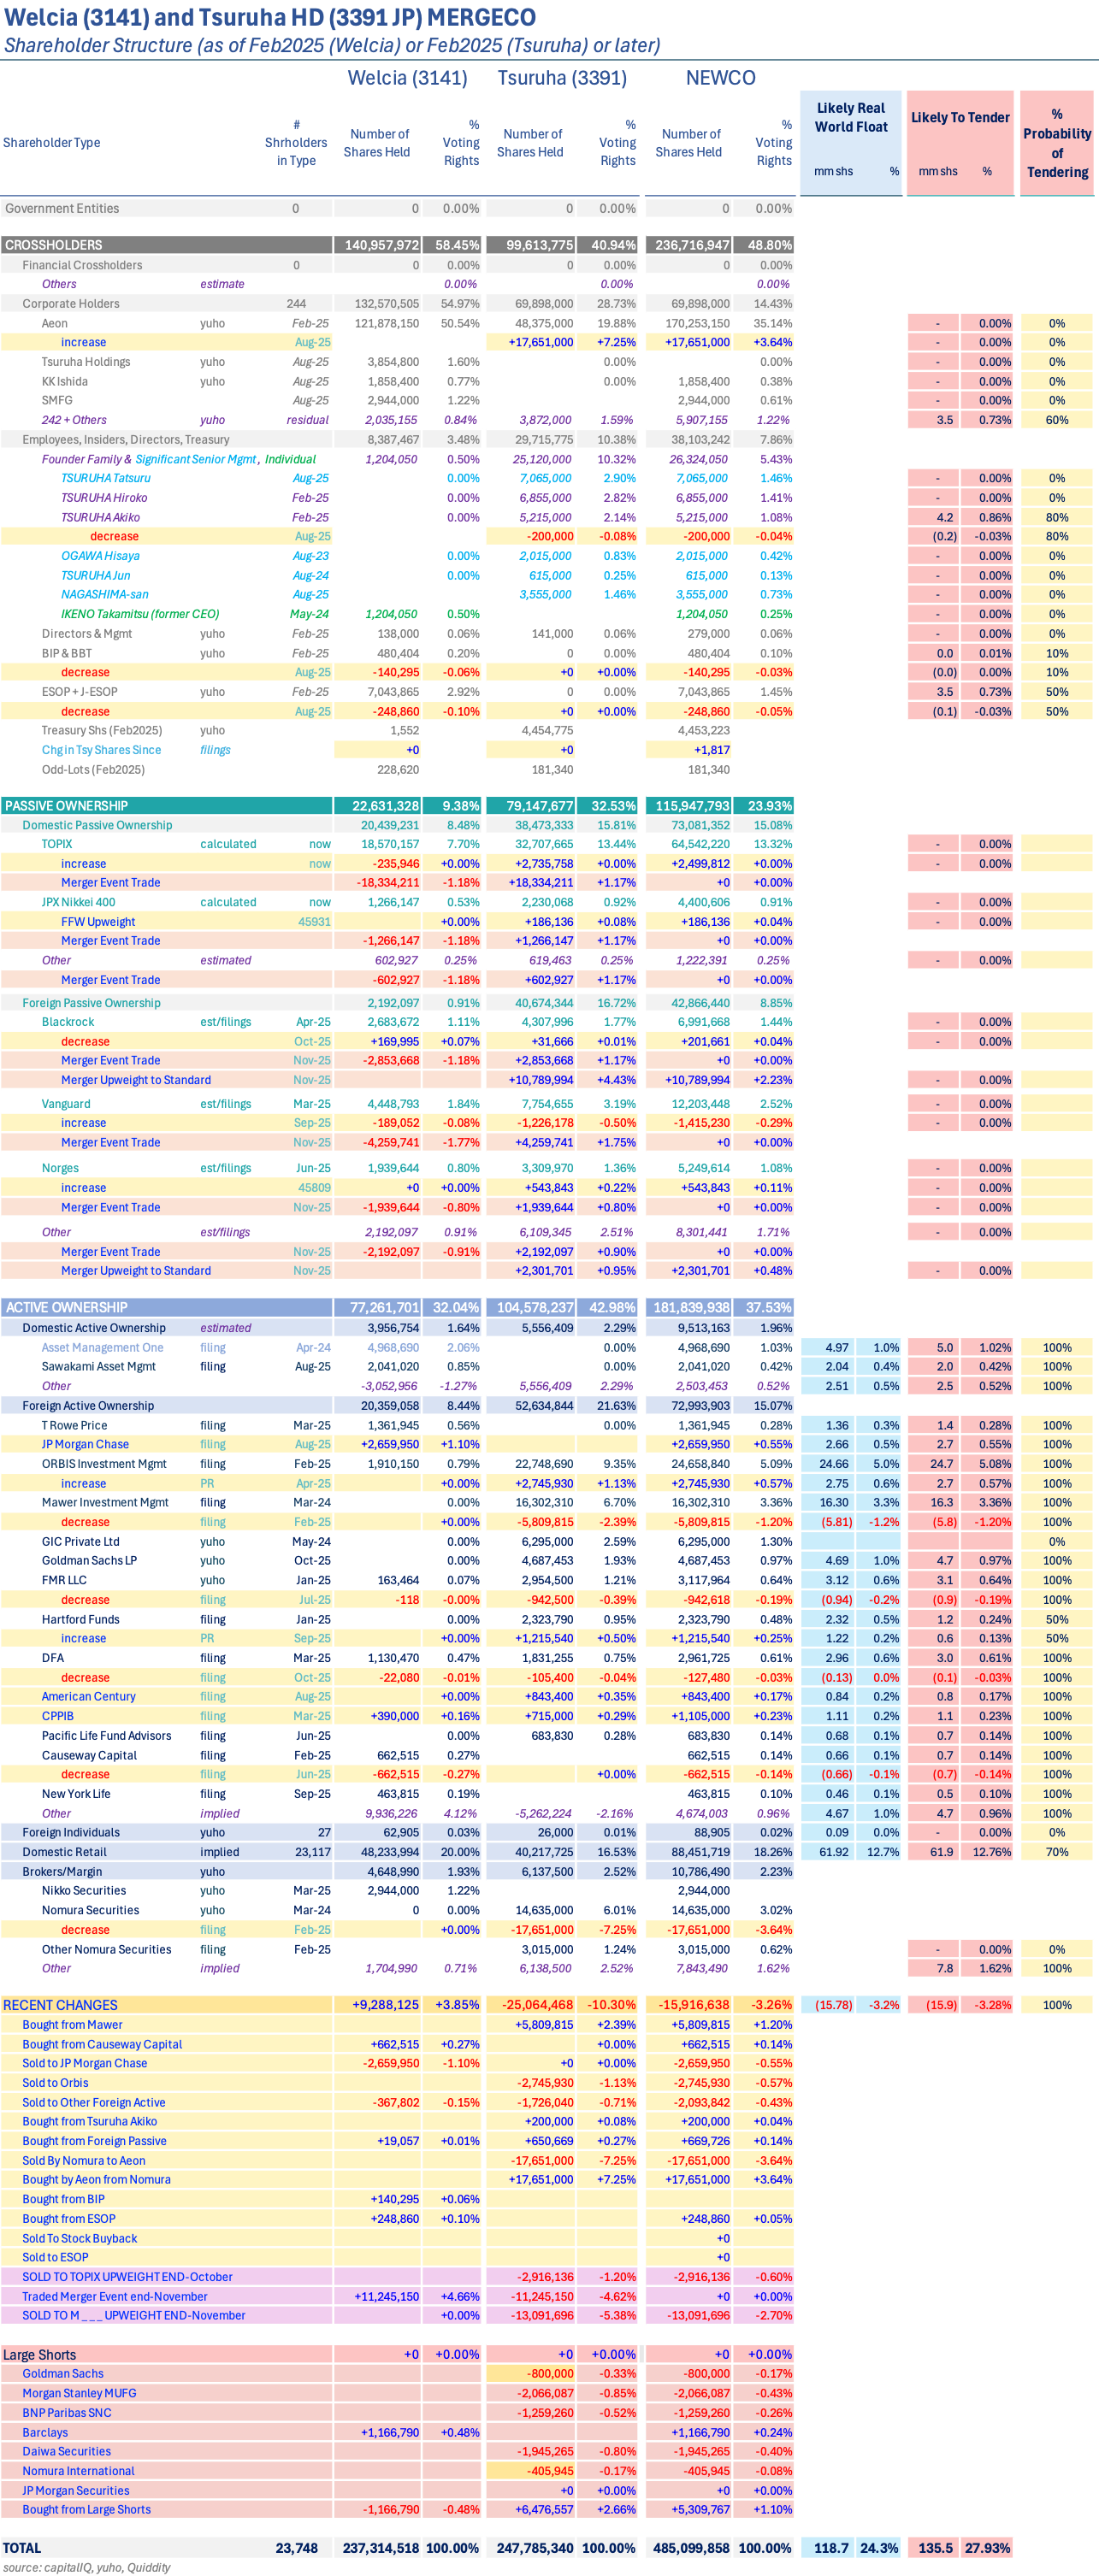
- Today, post-close of its first day of trading as MergeCo, Tsuruha Holdings (3391 JP) announced 12 different investors who had voted against the deal filed for dissenting shareholder share repurchase.
- This covers 27.154mm shares – a bit more than what Orbis owned when they last filed (25.5mm shs) and is just over half the AGM dissension.
- This creates some weirdness. A 5+% buyback is strong accretion, but “fair price” is a question, and it could mean smaller tender offer quantity and larger eventual index selldowns.
4. ANE Cayman (9956 HK): Q&A With The FA
- On the 28th October, ANE Cayman Inc (9956 HK), a road freight transportation play, announced a Scheme from Centurium Partners, a pre-IPO investor, Temasek, and Singapore-based asset manager True Light.
- The consortium offered HK$12.18/share, a 48.54% premium to undisturbed. A special dividend was bolted on. All pre-cons, including SAMR’s approval, have been satisfied. Scheme Doc dispatch expected on/before 31st December.
- I had a number of questions concerning the transaction, and yesterday pinned down a one-on-one with the FA to the Offeror.
5. Tsuruha (3391 JP): Aeon (8267 JP) Bumps Its Partial Tender Offer to JPY2,900
- Tsuruha Holdings (3391 JP) announced a partial tender offer from Aeon Co Ltd (8267 JP) at JPY2,900, a 27.2% premium over the previously stated offer price of JPY2,280.
- Aeon will acquire a maximum (upper limit) of 43.2 million shares (9.52% ownership ratio) such that it attains a 50.90% ownership ratio. There is no lower limit.
- The offer is above the midpoint of the IFA DCF valuation range and marginally below the JPY3,100 price Aeon paid in 2024 to acquire Oasis’ stake.
6. StubWorld: Don’t Sell Toyota Inds (6201 JP) – Buy More
- At ¥17,340/share, Toyota Industries (6201 JP) is cheap. Corporate governance supporting this deal is shocking. In Travis Lundy‘s words: “Stay long. Buy more. And make some noise.”
- Preceding my comments on Toyota are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
7. Dongfeng (489 HK): Revisiting VOYAH’s Spin-Off Valuation
- Back on the 22nd August 2025, SOE-backed Dongfeng Motor (489 HK) announced a privatisation; together with a concurrent listing of its EV arm, VOYAH. The two proposals are interconditional.
- In its October application proof, VOYAH turned a profit in 7M25. The market was implying a price-to-trailing-sales of 1.5x for VOYAH, versus the basket average of 2.1x. It’s now ~1.2x.
- Key PRC reg approvals (Mofcom/NDRC/SAFE) remain outstanding. Meanwhile, a basket of peers are down 21% since the dual proposals were announced. And their average price-to-trailing-sales are down to 1.7x.
8. A Review of Tender Offers in Korea in 2025
- In this insight, we review the major tender offers of Korean companies in 2025. Some of the major M&A tender offers in 2025 include HMM, Kolon Mobility Group, and VIOL.
- The tender offers have mostly been profitable for the investors in these targeted companies (especially those shareholders who owned these shares prior to the tender offer announcement).
- What is also impressive is that even after the 1st day of trading (post tender offer announcement), there have been extra alpha for the following week.
9. Korea’s 4th Policy Trade Is Right Around the Corner: Mandatory Tender Offers
- The next policy swing is mandatory tender offers (MTO), with the gov’t + ruling party pushing for passage this session, likely alongside the mandatory treasury-share cancellation.
- 2022 FSS/FSC 50%+1 trigger scrapped; 25% stays. Ruling party favors 50%+ MTO, base case 100%, but pushback may reduce to 70–80%.
- MTOs tighten discounts, benefit minority holders; focus on local holding firms, PE-backed exits, and parent-driven M&A prospects.
10. ANE (9956 HK): Precondition Satisfied
- The precondition for the consortium’s privatisation offer for ANE Cayman Inc (9956 HK) has been satisfied. The right to increase the share alternative cap was also satisfied.
- The consortium has until 12 December to decide whether to increase the share cap. The option helps the consortium gain support from shareholders who would not accept the cash offer.
- The scheme vote remains low risk, as the offer is attractive relative to historical ranges and peer multiples. The de-rating of peers is also helpful.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Kioxia (285A JP) Placement: Limited Passive Buying & Big Runup Opens Up More Downside
- Bain Capital is looking to place 36m shares of Kioxia Holdings (285A JP) to overseas investors at a 7-9% discount to the last close of the stock.
- The stock has run up a lot since its IPO with the last leg driven by inclusion in a global index that took place at the close on Friday.
- Toshiba (6502 JP) had already been selling stock, and the Bain selling could take the stock lower, especially with limited passive buying in the short-term to support the big runup.
2. Curator’s Cut: Powering Down CATL, Iron Ore Plays & Japan Consumer Consolidation
- Welcome to Curator’s Cut — a fortnightly roundup of standout themes from the 1,500+ insights published on Smartkarma.
- In this cut, we review CATL’s H-share lock-up expiry, iron ore equity opportunities in the face of Simandou’s expected supply, and the accelerating consolidation in Japan’s consumer sector.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
3. National Storage REIT (NSR AU) In Trading Halt Ahead Of Possible Brookfield/GIC Tilt
- Reportedly, Brookfield and Singapore’s GIC will make an Offer for National Storage REIT (NSR AU), Australia and New Zealand’s largest landlord of self-storage sites .
- The AFR is reporting that Brookfield/GIC are on the cusp of launching a bid around NTA. NSR entered into a trading halt this morning.
- Earlier this year, key peer Abacus Storage King (ASK AU) fielded an NBIO from Ki Corporation/Public Storage (PSA US) at a ~3% premium to NTA; however, Ki/PSA ultimately walked.
4. Qube (QUB AU): Macquarie’s Lobs NBIO
- Qube Holdings (QUB AU), a logistics and infrastructure play, has announced a A$5.20/share non-binding indicative Offer from Macquarie Asset Management, a unit of Macquarie Group (MQG AU).
- That is a 27.8% premium to last close. And ~14.4x FY25 EV/EBITDA. The proposal “follows an earlier unsolicited, non-=binding and indicative offer at lower value.” Dividends paid will be netted.
- Qube directors are supportive. The proposal is conditional on due diligence, board approvals, no MACs at Qube, plus regulatory clearance, including FIRB and ACCC signing off.
5. [Quiddity Index] Bengo4.com (6027 JP) To TSE Prime and TOPIX Inclusion
- Back in mid-August, Bengo4.Com Inc (6027 JP) (“Bengoshi.com”) announced that it had applied to transfer to TSE Prime. 3+mos later, today it announced it will move on 4 Dec 2025.
- That sets up a TOPIX inclusion for end-January 2026 and then a likely upweight at end-April 2026.
- There is no accompanying offering, and the float is likely small. But the inclusion displaces the current active base. And there’s at least one large holder selling recently.
6. Korea Dividend Tax Cut: Eligibility Criteria & Market Impact on Large Caps, Including Samsung Prefs
- Market eyed 25% top rate, but 30% is still punchy; <100 people hit it, lower than before, giving big shareholders incentive to rotate back into dividends.
- The new regime hits only companies with 25% payout last year and +10% YoY dividend: lower than the original draft, and the 10% bump is a solid positive.
- Companies >5tn KRW with ≥25% payout last year must boost dividends +10% YoY to get the tax cut; Samsung could add ~1tn KRW, potentially easing its pref discount.
7. A Tender Offer of 10% Stake in Gabia by Align Partners Asset Management
- After the market close on 24 November, it was announced that Align Partners is conducting a partial tender offer of a 10% stake in Gabia Inc (079940 KS).
- Tender offer price is 33,000 won (20% higher than current price). Tender offer amount is 44.7 billion won.
- If Align Partners successfully completes this tender offer, its stake would rise to 19.03%. Plus, the combined stakes of Align Partners and Miri Capital would be 42.99%.
8. HK Connect SOUTHBOUND Flows (Wk To 21 Nov 2025) – BIG Net Buy on Lower Gross Flows. BABA Bought
- HK$100bn a day of gross SOUTHBOUND activity with US$600mm+ of net buying on average. Net flows continue to be impressive. SOEs/Energy/Financials dominate.
- Watch for news on the Dual Counter (RMB) Trading eligibility for SOUTHBOUND near-term. That could up the pace of things.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The Southbound Flow Monitor and AH Pairs Monitor are both there – free – for all SK readers.
9. [Japan Activism] Mandom (4917) Holders Get an Early Win as MBO Bidder CVC Bumps 29%
- Today late in the afternoon session, the Nikkei reported that the MBO price would be bumped by “about 30%”. The stock popped 4.6%.
- Post-Close, the deal is bumped from ¥1,960 to ¥2,520 (+29%). Activist holders Murakami Group with 21.4% and Hibiki Path Advisors with 5.5% have agreed to tender.
- With the two main activists publicly engaged now agreed to tender, this looks like a done deal.
10. [Japan Activism/M&A] SilverCape Renews Its Effort on Digital HD (2389 JP) To Resolve Board Complaint
- Digital Holdings Inc (2389 JP) jumped today after spending a week or more at levels just above the revised Tender Price of Hakuhodo Dy Holdings (2433 JP).
- SilverCape had promised to bid ¥2,380 against Hakuhodo’s ¥1,970 and the Company responded by threatening a Poison Pill against SilverCape, for relatively spurious reasons (as discussed here).
- Hakuhodo bid slightly more, and lowered its minimum, thereby nearly ensuring their success. HOWEVER…. SilverCape’s CIO interviewed yesterday promised a higher price. The stock popped today. But…
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Activism/M&A] Thinking About the Partial Tender Trade Coming in Dec25
- A month ago I wrote [Japan Activism/M&A] – Closing In On the Tsuruha Partial Tender – Likely Needs To Be Higher. Now we are <2wks to the deal.
- At the time, I said the Partial Tender Offer Price needed to be higher than the mooted ¥2,280. Tsuruha Holdings (3391 JP) shares are up 10.0% in that month.
- The three largest peers are -2.0% on average in that period. The average of 8 peers is +0.5%. I still expect the partial offer price needs to be near ¥3,100
2. China Hongqiao (1378 HK): Index Impact of US$1.2bn Placement
- China Hongqiao (1378 HK) is looking to raise US$1.2bn via a top-up placement at an indicative price of HK$29.2/share, a 9.6% discount from the last close.
- There will be limited passive buying from global index trackers at the time of settlement of the placement shares. However, there are a couple of potential index inclusions in December.
- Then there will be more passive buying from trackers of a global index, Hang Seng Index (HSI INDEX) and Hang Seng China Enterprises Index (HSCEI INDEX) next year.
3. CATL IPO Lockup – US$5.3bn Lockup Release, with H-Shares at Significant Premium to A-Shares
- CATL (3750 HK) raised around US$5.2bn in its H-share listing in May 2025. The lockup on its cornerstone investors is set to expire soon.
- CATL is the global leader in new energy vehicle battery solutions, in China and globally, as per SNE Research.
- In this note, we will talk about the lockup dynamics and possible placement.
4. SBI Shinsei Bank (8303 JP) IPO: TPX Add in Jan; Global Index: One in May; One in June
- SBI Shinsei Bank (8303 JP)‘s listing has been approved by the JPX and the stock is expected to start trading on the Prime Market from 17 December.
- At the indicated IPO price of ¥1,440/share, the IPO will raise up to ¥367.6bn (US$2.38bn) and value SBI Shinsei Bank (8303 JP) up to ¥1,290bn (US$8.34bn).
- The stock should be added to the TOPIX INDEX at the close on 29 January while inclusion in global indices should take place in May and June.
5. [Japan Activism/M&A] Hakuhodo DY Lowers Digital Holdings (2389 JP) TOB Threshold, Bumps a Tiny 2.2%
- Today after the close, Hakuhodo Dy Holdings (2433 JP) announced changes to the terms of its Tender Offer for Digital Holdings Inc (2389 JP), which faces an overbidder in SilverCape.
- Hakuhodo had bid ¥1,970. Silvercape came over the top with a proposed ¥2,380 but a delay for approvals. DH is fighting against SilverCape because of “remaining minority shareholder risk.”
- That’s garbage. Utter blatherskite. Trumpworthy trumpery. Now Hakuhodo DY has lowered the minimum threshold making it hard to miss, and raised the price 2.3% to ¥2,015.
6. Alibaba (9988 HK / BABA US): Brace for a Big Earnings Move
- Alibaba (9988 HK) / Alibaba (BABA US) will announce quarterly results on Tuesday, November 25, 8:30 p.m. HKT (7:30 a.m. U.S. Eastern Time)
- Options markets anticipate an above average move with a bearish bias in traders’ expectations. Implied volatility is expected to drop significantly after the event.
- Get ready for Alibaba‘s earnings announcement. Potential above-average volatility in Alibaba has the potential to impact the wider market and Chinese benchmark indices.
7. Merger Arb Mondays (17 Nov) – Mandom, Paramount Bed, Maruwn, Paris Miki, Mayne, AUB, Genting
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Smart Share Global (EM US), AUB Group Limited (AUB AU), Dongfeng Motor (489 HK), ENN Energy (2688 HK), Digital Holdings Inc (2389 JP).
- Lowest spreads: Bright Smart Securities (1428 HK), Mandom Corp (4917 JP), Seven West Media (SWM AU), Pacific Industrial (7250 JP), Toyota Industries (6201 JP), Jinke Smart Services (9666 HK).
8. Grindr (GRND US)’s Wide Spread As Majority Owners Court Delisting
- Back on the 24th October, Ray Zage (director) and James Lu (chairman), collectively holding ~60% in Grindr (GRND US), proposed to take the company private in a US$3.5bn deal.
- The non-binding cash Offer of $18/share, is a 51% premium to undisturbed. A condition to a firm Offer may incorporate a majority of minority vote.
- While the Special Committee considers the proposal, James Lu has unusually opted to step down. Currently trading at a ~30% gross spread to indicative terms.
9. Tsuruha-Welcia Merger to Form Biggest Drugstore Alliance, +Aeon TOB
- The Tsuruha-Welcia merger creates Japan’s largest drugstore alliance, poised for long-term growth and market dominance, driven by an expected JPY 50B in synergies over three years.
- A two-step corporate action—share exchange (Dec 1, 2025) followed by an Aeon TOB—provides structural certainty and strategic backing, securing the combined entity’s market leadership.
- These catalysts establish a large market leader in the consumer staples space, suggesting a timely opportunity to gain exposure to the new entity.
10. Webjet (WJL AU): Helloworld Steps Up As Weiss/BGH Seek Board Spill
- In Webjet (WJL AU): Undisclosed Buyer Buying, rumours surfaced earlier this year of an undisclosed buyer with ~5%. On the 12th May, Helloworld (HLO AU) emerged with a 5.015% stake.
- On the same day, Gary Weiss/BGH, collectively holding 10.76%, launched a A$0.80/share NBIO, which was subsequently rejected. Undeterred, Weiss/BGH has called for an EGM (21st November) to spill the board.
- Helloworld has now tabled a A$0.90/share non-binding Offer, by way of Scheme. The 1H26 dividend of A$0.002/share will be added. Helloworld currently holds 17.27%. Weiss/BGH hold 17.75%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
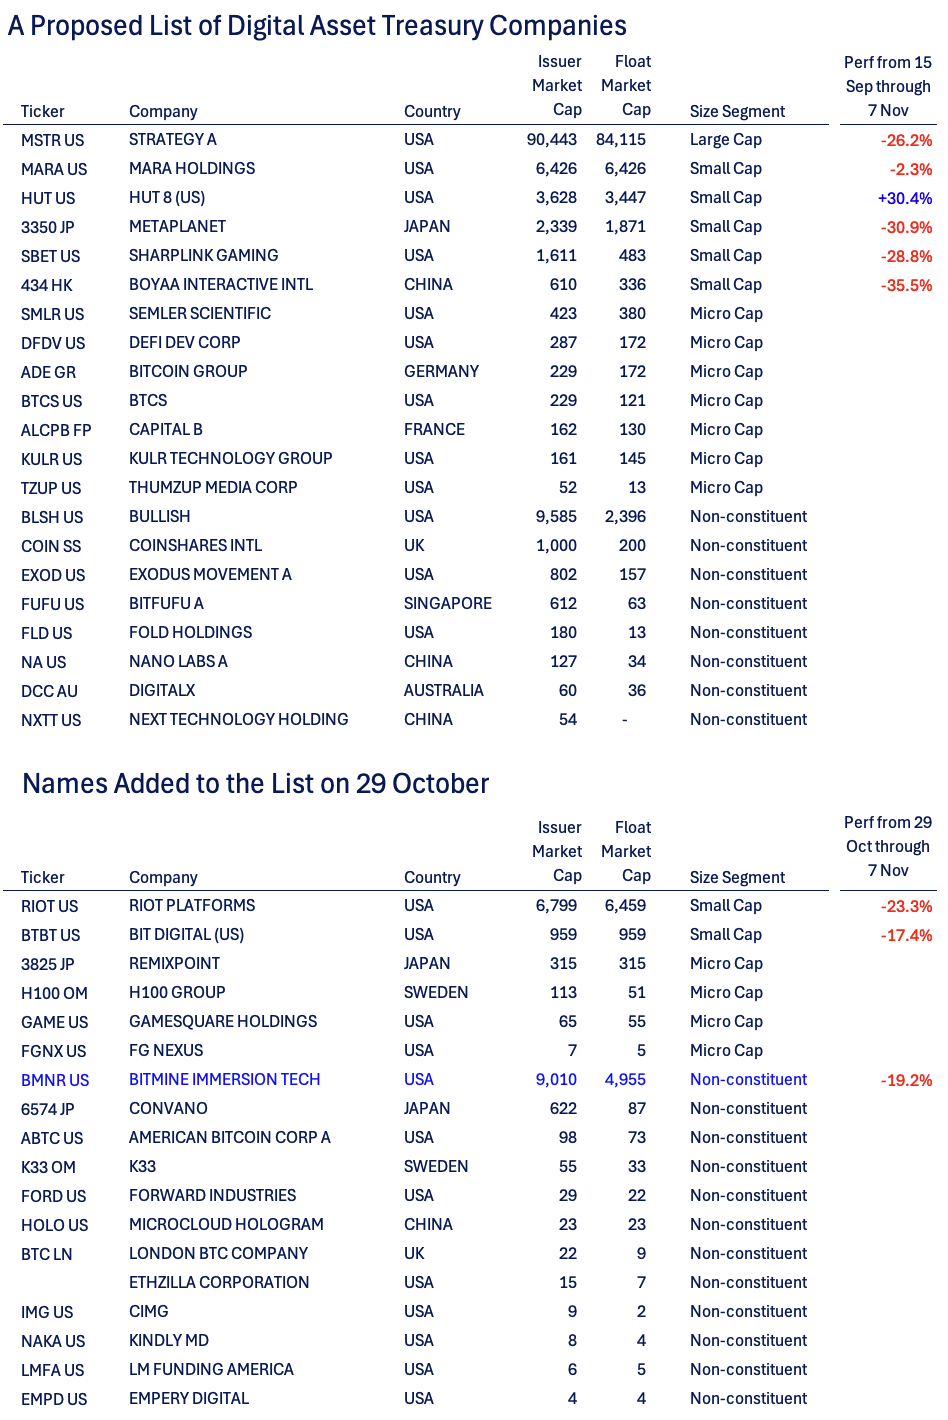
1. Index Consultation on DATCos Means MORE Selling Likely, and Another Index Questionable
- In mid-September, global index provider M _ _ _ announced that they were conducting an index consultation on Digital Asset Treasury Cos. I wrote about it here.
- My recommended short at the time is down 30%, despite announcing a large buyback program. Others have lost significant premium vs underlying digital assets.
- The same index provider expanded their list of affected names on 29 Oct. And a DIFFERENT Index provider this week added DATCOs to a US Advisory Panel Meeting Agenda Wednesday.
2. [Japan M&A] Senko Group (9069 JP) Bids for Maruwn (9067 JP) In Deal Which May Trigger Fireworks
- Today, logistics company SENKO Group Holdings Co., Ltd. (9069 JP) announced a bid for logistics company Maruwn Corp (9067 JP) with help from 35% holder JX Advanced Metals (5016 JP).
- The TOB only needs 11+% to get to 50.1%. There are three holders who Senko clearly regard as not necessarily agreeable to the deal. They hold 28.0% between them.
- If someone wanted to thwart this deal, there are a number of ways to do it. This could get interesting.
3. [Quiddity Index] Light & Wonder (LNW US/AU) US Delisting Event – Updating The Assumptions/Estimates
- Light & Wonder (LNW US) will be delisted at the close of tomorrow US time (two trading days left) and shares converted to Australian CDIs.
- After studying the matter we have amended our assumptions on how flows work. More net selling than expected in November, irksome uncertainy in December, more buyback flows in the meantime.
- The stock was higher on earnings in Australia, skipped a day, then skipped another day, then jumped in the US yesterday.
4. ChiNext/ChiNext50 Index Rebalance Preview: Maxing Out the Changes
- With the review period complete, we forecast 10 changes for the ChiNext Index (SZ399006 INDEX) and 5 changes for the ChiNext 50 Index in December.
- The largest flows will be in 2 stocks that are forecast adds for both indices. There are 14 stocks with over 0.5x ADV to trade from passive trackers.
- The forecast adds outperformed the forecast deletes from June to August, but there has been significant underperformance since then. Outperformance could resume as positioning kicks in prior to announcement.
5. [Japan M&A] Taiyo Pacific Offers ¥2,210 for Star Micronics (7718) Completing the Shareholder Ripoff
- Today after the close, well-known Japan engagement fund Taiyo Pacific Partners announced a deal to buy Star Micronics (7718 JP) for ¥2,210/share. They’ve been involved small-big-small for 20yrs.
- The company launched a new capital plan and MTMP in February. Cash-rich, it needed no money to grow aggressively. So TPP proposed buying a third of the company. Board agreed.
- Despite ActionsToImplementManagementConsciousOfSharePriceAndCostOfCapital announced February, in April-November the Board decided to sell the entire company to TPP at <1x book. This is borderline outrageous. It deserves notice and complaint.
6. Hynix L2 Flag Risk: Why Stuck Below ₩620k? Eyes on Nov 17 Pivot
- Hynix tagged L2: cash‑only, no margin. >40% two‑day rip triggers KRX halt. L2 caps distort tape; Square’s Oct 27–Nov 10 run showed the messy playbook.
- Hynix L2 review: five >200% YoY prints since Nov 4, but no fresh 15‑day high—₩620k from Nov 3 still the cap, yesterday stalled just below.
- Break above ₩620k likely triggers L2, leverage caps, volatile tape, Square outperformance; hold below into Monday kills L2 risk, keeps Hynix’s relative bid with retail still piling in.
7. [Japan M&A] Paris Miki Is Indeed an MBO Target; Luxottica May Complain But Tough To Block
- Today after the close, Paris Miki Holdings (7455 JP) announced the Tane family Holdco would buy out the company in an “MBO” at ¥581, or 4.8x current year EBITDA.
- World famous eyeglass/sunglass manufacturer Luxottica bought 13.8% of the company in the low ¥300s almost stopping about a year ago. They might complain, but Paris Miki is a big outlet.
- This looks like it gets done. The family+crossholders+ESOP+warrants have 65% of the expanded share count. Those who would complain would need to do so soon, and loudly.
8. Square’s Level 2 Leverage Caps End Tomorrow — Fresh Near‑term Factor in the Square Vs Hynix Setup
- Square closed ₩290,000, missing all criteria; Level 2 removal effectively confirmed, with KRX disclosure expected ~8 p.m. Seoul, effective from tomorrow’s open.
- Square vs Hynix hinges on retail chase structurally, but near‑term Square’s underperformance worsened by asymmetric leverage shackles.
- Square’s Level 2 setup ends tomorrow; flows normalize, likely giving Square more juice vs Hynix. Key spot to watch from tomorrow’s open.
9. [Japan M&A] KKR and Founder to Take Engineer Staffing Agency Forum Engineering (7088) Private
- Today after the close, KKR announced a deal whereby they and founder OKUBO Izumi-san would take Forum Engineering Inc (7088 JP) private in an LBO.
- The process of this deal ticks most all of the “bad process” boxes but the price is pretty good.
- 52% is locked in. Insiders and cross-holders appear to own another 15-18%. This looks like a done deal to me. Money comes 30 December.
10. Merger Arb Mondays (10 Nov) – Soft99, Digital Holding, Saint-Care, ANE, ENN Energy, Mayne, AUB
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Saint-Care Holding (2374 JP), Smart Share Global (EM US), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Digital Holdings Inc (2389 JP).
- Lowest spreads: Bright Smart Securities (1428 HK), Mandom Corp (4917 JP), Pacific Industrial (7250 JP), Toyota Industries (6201 JP), Seven West Media (SWM AU), Jinke Smart Services (9666 HK).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
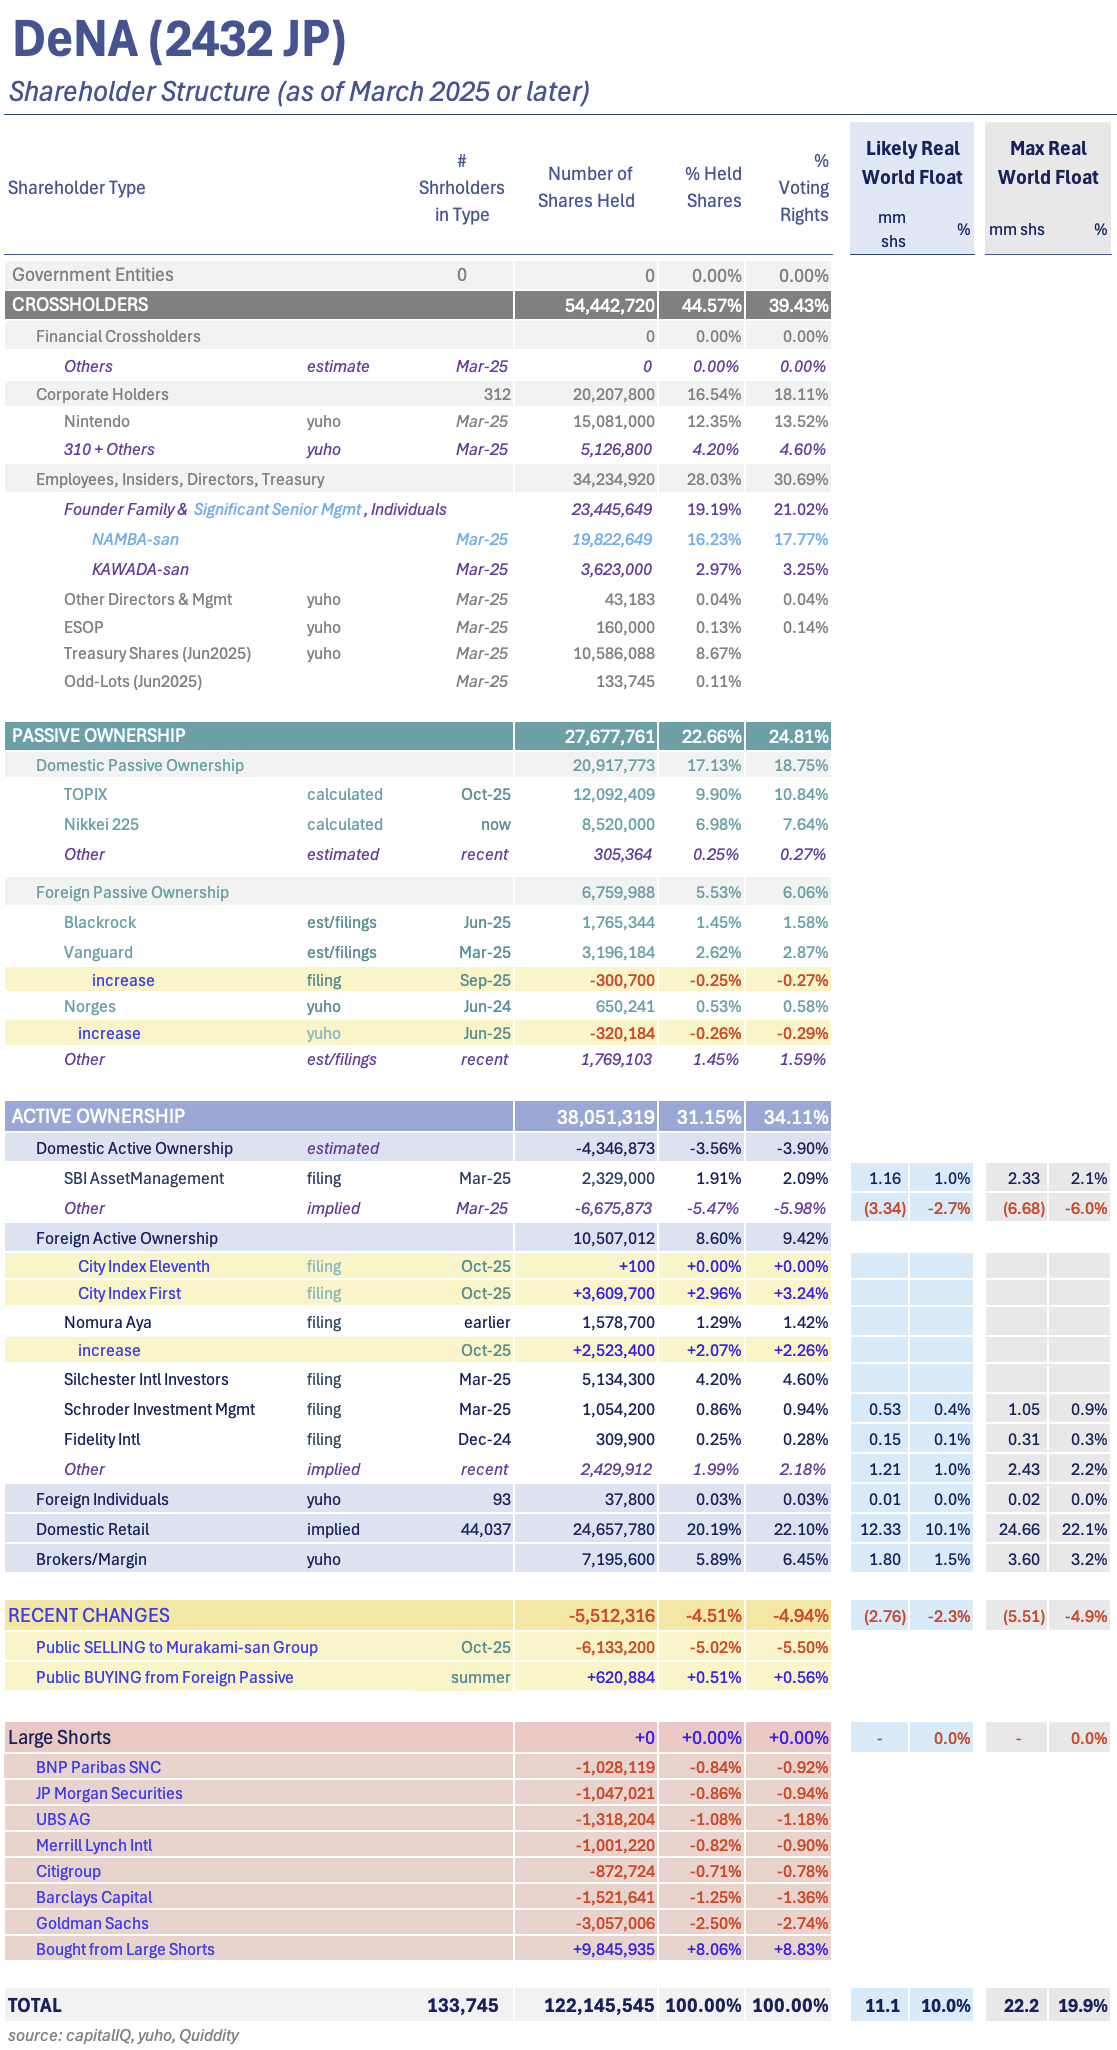
1. [Japan Activism] DeNA Attracts Murakami Group – Potentially Squeezable With Reason
- Last week, “Murakami Group” (a group of investors who jointly file large shareholder filings) announced a 5+% stake in DeNA (2432 JP). The stock popped. Then they filed again.
- This was not surprising. It has long been known as a “value” name (and has the requisite short balance to prove it). The question is how much value IS there
- The question is how much value IS there. And to whom? It’s an interesting question which deserves a look, so we take a look.
2. Pine Labs IPO: Slashed Offering Size & Lower Valuation
- Pine Labs (0568874D IN) is looking to list on the exchanges by selling 176.5m shares via a primary and secondary offering to raise US$439m at a valuation of US$2.86bn.
- The price band has been set at INR 210-221/share and could price at the top end of the range. The IPO raise and valuation are sharply lower than earlier reports.
- Inclusion at regular rebalances will commence in May but flow will be small given the low float and the Smallcap indices that it is added to.
3. Toyota Industries (6201 JP): Market Movements Support the Case of a Higher Offer
- Last month, nearly two dozen global asset managers, through ACGA, submitted a joint letter to the boards of Toyota Industries (6201 JP) and Toyota Motor regarding the tender offer.
- The letter outlined five issues, which distilled down to concerns about a low-balled offer. Their cause is increasingly supported by market movements, which support the case for the bump.
- Recent activism against several low-balled tenders signals that TICO, despite its size, is not immune. My SoTP valuation is JPY19,607, which is 20.3% above the offer price.
4. [Quiddity Index] Light & Wonder (LNW US/AU) US Delisting / ASX Relisting Index Event
- In August, Light & Wonder (LNW AU) / Light & Wonder (LNW US) announced that the company would give up its US listing and move to an ASX Primary Listing.
- The NASDAQ delisting has been confirmed (as expected) for 12 November. October saw significant CDI conversions. More have come in the last few days.
- This creates a significant, and interesting set of index events to track.
5. Matheson’s Motive For Avoiding MAND’s Dissentient Shareholders
- Back in 2021, Jardine Matheson (JM SP) took 84.89%-held Jardine Strategic (JS SP) private by way of an Amalgamation. As Matheson was permitted to vote, the outcome was assured.
- Less clear are “fair value” appraisal rights afforded Strategic’s dissentient shareholders, the outcome of which navigates the Bermuda/UK courts. To date, dissenters have mostly had their way.
- Which may have precipitated Matheson opting for a (full value) Scheme for Mandarin Oriental International (MAND SP), in which appraisal rights are not afforded.
6. Merger Arb Mondays (03 Nov) – ANE, Dongfeng, Mayne, AUB, Digital Holdings, Makino, Soft99, SCSK
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Brainpad Inc (3655 JP), Smart Share Global (EM US), AUB Group Limited (AUB AU), ENN Energy (2688 HK), Dongfeng Motor (489 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Mandom Corp (4917 JP), Pacific Industrial (7250 JP), Seven West Media (SWM AU), Humm Group (HUM AU), Toyota Industries (6201 JP).
7. [Japan Activism] Mandom (4917 JP) – Murakami at 20% and Mandom Offers A Sweet Poison Pill
- Mandom Corp (4917 JP) yesterday decided to launch a question-response effort for the Murakami-san Group ownership of Mandom shares up to and above 20%. This is a Poison Pill precursor.
- There’s a drawn out set of questions, answers, etc, at the end of which, the Independent Committee will decide that Murakami is a Bad Person and the Poison Pill proceeds.
- Murakami Group is apparently now over 20%. That’s a little tricky. But this looks like a Good Poison Pill.
8. Mandom (4917 JP): Countermeasures Ostensibly to Buy Time for a Higher Offer
- Mandom Corp (4917 JP) has proposed countermeasures in response to Murakami’s 18.87% voting stake and to ostensibly secure time for an alternative, viable (higher) offer.
- The read-across from the proposal is that CVC’s offer at current terms will fail, CVC is unwilling to match Murakami/Hibiki’s expectations, and there could be genuine interest from third-party bidders.
- Nevertheless, countermeasures are unnecessary as the share price and presence of activists provide the time needed for the Board’s purported aim to secure a higher offer.
9. Physicswallah IPO: Index Inclusion Possibilities & Timing
- Physicswallah Limited (2076103D IN) is looking to list on the exchanges by selling 319.26m shares via a primary and secondary offering to raise US$392m at a valuation of US$3.5bn.
- The price band has been set at INR 103-109/share, and the issue is likely to price at the top end of the range.
- The stock will be added to the AMFI Smallcap segment and inclusion in the Nifty Smallcap 250 index is likely in March. Global index inclusion could commence in June.
10. StubWorld: Sumitomo Chemical/Sumitomo Pharma, Hyundai Motor/ Kia Corp, Ecopro Co/Ecopro BM
- For a change of pace, this insight briefly canvasses a clutch of Holdco’s trading at extreme levels, in both “set-up” and “unwind” territory.
- Preceding the chart/table-heavy insight are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Tsuruha (3391 JP)/Welcia (3141 JP): Index Promotion & Passive Flows Likely Priced In
- Tsuruha Holdings (3391 JP) acquires Welcia Holdings (3141 JP) in just over 4 weeks. Aeon Co Ltd (8267 JP)‘s tender offer for Tsuruha Holdings (3391 JP) could commence in December/January.
- The enlarged Tsuruha Holdings (3391 JP) could migrate upward in the MGlobal Index and that will bring in large passive flows. But there is one thing to watch out for.
- Tsuruha Holdings (3391 JP) and Welcia Holdings (3141 JP) have outperformed peers over the last 6 months and now trade at a higher forward PE.
2. Seres (9927 HK): Index Inclusion Timeline for a Max Offering of US$2.2bn; Big Discount to A-Shares
- Seres Group (601127 CH) could raise up to HK$17.4bn (US$2.24bn) in its H-share listing if the Offer Size Adjustment Option and the Overallotment Option are both exercised.
- There is a big allocation to cornerstone investors that is locked up for 6 months. That eliminates the already small possibility of Fast Entry inclusion to global indexes.
- Seres (9927 HK) should be added to Southbound Stock Connect from the open of trading on 1 December following the end of the Price Stabilisation period.
3. Lenskart IPO: Earliest Index Inclusion in June
- Lenskart Solutions (0370405Z IN) is looking to list on the exchanges by selling 181.05m shares via a primary and secondary offering to raise US$829m at a valuation of US$7.95bn.
- The price band has been set at INR 382-402/share, and the issue is likely to price at the top end of the range.
- The stock will not get Fast Entry to global indices. Inclusion at regular rebalances will commence in June 2026 but flow will be small given the low float.
4. Groww IPO: Growwing Fast; Index Inclusions Will Be Sloww; Small Floww
- Groww (1573648D IN) is looking to list on the exchanges by selling 663.23m shares via a primary and secondary offering to raise US$752m at a valuation of US$7bn.
- The price band has been set at INR 95-100/share, and the issue is likely to price at the top end of the range.
- The stock will not get Fast Entry to global indices. Inclusion at regular rebalances will commence in June 2026 but flow will be small given the low float.
5. [Japan M&A/Activism] Ashimori Industry (3526 JP) Minimum Lower, May Be a Tough Call
- In August, Toyoda Gosei (7282 JP) announced a deal for Ashimori Industry (3526 JP) at 1.000x book value after writedowns. That was not a coincidence.
- The takeover is cheap for what it is. No synergies were counted. But it wasn’t truly offensive. MURAKAMI Takateru aimed an activist broadside, bought 19.73% across four entities. Then stopped.
- The Bidder lowered the Tender Offer Minimum from 2.3081mm shares (38.29%) to 1.8001mm shares (29.86%). Shares dropped. As of 24-Sep, 2,111,226 shares had been tendered. This looks done. Maybe.
6. [Japan M&A] Sumitomo Corp To Buy Out Minorities in SCSK (9719 JP)
- Yesterday after the close, Sumitomo Corp (8053 JP) announced it would buy out minorities in Scsk Corp (9719 JP) at ¥5,700/share.
- As a “parent takes out subsidiary” deal, this was not unexpected at some point in time. The register looks like there may be a number of people who expected that.
- This gets done pretty easily. It is not a bad price.
7. Sanil Electric Poised for Pop on Nov 20 KOSPI200 Ad‑Hoc (HD Hyundai Merger)
- HD Hyundai merger: both legs in index, Mipo delists, slot opens — one new name gets added to KOSPI200 via ad‑hoc.
- Sanil Electric (062040 KS) to replace HD Mipo pre‑Dec review. If DTV settles back into the 500–600k range, then KS200 ETFs will need to scoop ~0.3–0.4x DTV on Nov 26.
- Better to front‑run KRX; with AI power trade still hot, Nov 20 announcement likely sparks outsized price action vs waiting for rebalance print.
8. ANE (9956 HK): Centurium/Temasek’s Clean Offer
- After ANE Cayman Inc (9956 HK), a road freight transportation play, was suspended pursuant to the Takeovers Code, an Offer from PE outfit Centurium Partners, a pre-IPO investor, was expected.
- And this is what unfolded. Centurium, together with Temasek and Singapore-based asset manager True Light, are offering HK$12.18/share (best & final) via a Scheme, a 48.54% premium to undisturbed.
- A scrip alternative is present (mix & match). This is a pre-conditional Offer: it requires SAMR signing off. The FA is JPM. This should help smooth over the reg process.
9. ANE (9956 HK): Consortium’s Attractive Preconditional Offer
- ANE Cayman Inc (9956 HK) has disclosed a preconditional scheme privatisation offer from a consortium. The offer is cash (HK$12.18) or scrip (One TopCo Class A Share per scheme share).
- The precondition relates to SAMR approval. The scheme vote is low risk, as the offer is attractive relative to historical ranges and peer multiples.
- The offer price is final. Mr Wang Yongjun, the former chairman, holds a blocking stake but should be supportive. Timing is the key risk.
10. Jardine Matheson’s Underperformance Post Mandarin Offer
- Concurrent with the sale of 13 floors of OCB to Alibaba, Jardine Matheson (JM SP) announced on the 17th October an Offer for Mandarin Oriental (MAND SP)‘s minorities at US$3.35/share.
- This is a clean, full, “dull” Offer. And MAND is trading super tight to terms at ~2.1% gross, with possible payment (my estimate) late Feb 2026.
- Proceeds from the OCB sale will be US$925mn. And taking out MAND’s minorities will set Matheson back ~US$1bn. Yet the market is now assigning US$2.1bn less for Matheson’s stub ops.