

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Sany Heavy (6031 HK) IPO: Big Cornerstone Allocation to Delay Global Index Inclusion
- Sany Heavy Industry (600031 CH) could raise up to HK$16.35bn (US$2.1bn) in its H-share listing if the Offer Size Adjustment Option and the Overallotment Option are both exercised.
- There is a big allocation to cornerstone investors that is locked up for 6 months. That eliminates the already small possibility of Fast Entry inclusion to global indexes.
- Sany Heavy (6031 HK) should be added to Southbound Stock Connect from the open of trading on 24 November following the end of the Price Stabilisation period.
2. Mandarin Oriental (MAND SP): Matheson’s Full Offer
- A sale – partial or otherwise – of Mandarin Oriental International (MAND SP)‘s One Causeway Bay (OCB) was always on the cards. But I didn’t see an Offer coming.
- Concurrent with the sale of 13 floors of OCB to Alibaba (9988 HK), Jardine Matheson (JM SP) is seeking to take out MAND’s minorities at US$3.35/share by way of a Scheme.
- That’s a 52.3% premium to undisturbed, and a 53.7% premium to NAV. Unlike the 2021 Jardine Strategic (JS SP) Offer, Matheson is required to abstain from voting on this takeover.
3. [Japan M&A/Activism] Digital HD (2389 JP) Gets a Counter + 20% – Tough But Not Impossible
- Today, in something of a surprise but not a complete surprise, Silvercape came out with its own bid for Digital Holdings Inc (2389 JP) at +20% from the Hakuhodo bid.
- They make it clear that the original bid does not protect minority shareholders or give them sufficient value. This one would. Which means that is Hakuhodo’s bogey.
- It would not be impossible for Silvercape to get to its minimum hurdle, but despite being lower than Hakuhodo’s it’s not a gimme.
4. [Japan M&A/Activism] – Activism Wins as MBO Bidder Pays 42.4% More for Pacific Industrial (7250 JP)
- When the Pacific Industrial (7250 JP) deal was announced in late July, I said it needed to be done 20-40% higher. I hadn’t expected someone to push so hard.
- But Effissimo pushed. They bought 12.5% of shares out, and 13+% of votes at an average price of ¥2,365/share – 15% through terms.
- Three months later after multiple extensions, Bidco bid up. +42.4%, to 1.002x March 2025 BVPS. A raging win for activists and minority investors. I’m genuinely surprised by the quantum.
5. Palliser Capital Goes Activist on LG Chem
- Palliser Capital started to go activist on LG Chem. According to Palliser Capital, LG Chem’s share price is trading at a 74% discount to its NAV.
- Palliser Capital proposed improving the composition of the board of directors, restructuring the executive compensation system to align with shareholder interests, and higher share buybacks.
- Our updated NAV analysis of LG Chem suggests implied price of 613,438 won per share, which represents a 57% higher levels than current levels.
6. Dec KS200 Review: Kakao Pay Poised for Breakout
- Names with the biggest float bumps relative to their old float saw the sharpest moves — Hanwha Ocean and Ecopro Materials were the standout examples.
- Kakao Pay looks set for Dec review spotlight: float likely jumping from 21% to 34% (+13ppt, 60%+ surge), even bigger than Hanwha Ocean/Ecopro last round.
- Kakao Pay’s 13ppt float hike implies ~0.7–1.0x DTV passive inflows; with little pre‑positioning, flows may hit raw and drive outsized intraday impact.
7. Korea’s Next Policy Play: NAV Discount Squeeze on Low‑Float Large Caps
- Market sniffing policy push; low-float names flagged as junk risk with skewed control. Desks circling, Palliser hit early—LG Chem trade popped, timing spot on.
- Trade setup: screen >₩1tn caps with low float, parent stakes 60–80%. Policy push likely forces stake cuts, driving float higher and squeezing NAV discounts—LG Chem shows the play.
- Screening >₩1tn caps flags 11 names: parents hold 60–80%. All potential stake-sale plays to boost float, squeeze NAV discount.
8. Merger Arb Mondays (20 Oct) – ENN Energy, Joy City, Kangji, Mandarin, Soft99, Mandom, Makino
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mandarin Oriental International (MAND SP), Smart Share Global (EM US), Soft99 Corp (4464 JP), ENN Energy (2688 HK), Mayne Pharma (MYX AU), Dongfeng Motor (489 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Mandom Corp (4917 JP), Humm Group (HUM AU), Seven West Media (SWM AU), Toyota Industries (6201 JP).
9. Horizon Robotics IPO Lockup – Last of the Lockups, Large Pre-IPO Investors Still Holding On
- Horizon Robotics (9660 HK) raised around US$800m in its Hong Kong IPO in October 2024. Its first set of lockups expired in April 2025. The next one is due soon.
- Horizon Robotics (HR) is a provider of advanced driver assistance systems (ADAS) and autonomous driving (AD) solutions for passenger vehicles, empowered by its proprietary software and hardware technologies.
- In this note, we will talk about the lockup dynamics and possible placement.
10. Fresh Policy Momentum Hitting Korea Tape: Trade Is Lining up Around 13 Holdcos with CVC Exposure
- Gov’t likely to ease CVC rules; street chatter sees high odds. Tied to KRW150tn Growth Fund push, with corporates lobbying—cleanest path to juice capital flow.
- Holdcos at center of CVC‑easing; scrapping disclosure rule unlocks external capital. Street read: fast flip from control towers to re‑rating plays as real investment shops with growth portfolios.
- KFTC flags 177 holdcos, 14 with CVCs (13 listed). Street sees momentum flows hitting these 13 names; play via basket/overweight, with Doosan, Hyosung, LX as preferred plays.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Activism/M&A] – Closing In On the Tsuruha Partial Tender – Likely Needs To Be Higher
- The merger between Tsuruha Holdings (3391 JP) and Welcia Holdings (3141 JP) will go through in about 6 weeks. In the interim, there are interesting events.
- After, there is a Partial Tender Offer. I expect Aeon Co Ltd (8267 JP) will have to pay up.
- Furthermore, the stock is not overly expensive vs Peers AND there are synergies to come from the merger, making it relatively cheaper. It’s not squeezy, but it’s skewed.
2. Hang Seng (11 HK)’s Offer: HSBC Investors Are Not Sold On The Strategic Benefits
- Since announcing HSBC (5 HK)‘s Offer, Hang Seng Bank (11 HK) has traded tight-ish to terms, at a ~3.9% gross spread (including dividends). Or ~10% annualised if a five month offramp.
- Annualised spreads for clean liquid deals in Asia-Pac, do tend to widen after day 1. Meaning, the gross spread remains roughly static as investors hit their full quota early on.
- HSBC shareholders are questioning the deal merits. For Hang Seng minorities, this is a great exit. Inside this report, I take a deeper dive into Hong Kong bank takeover precedents.
3. Merger Arb Mondays (13 Oct) – Dongfeng, Hang Seng, Soft99, Toyota Industries, Pacific Ind, Mandom
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Smart Share Global (EM US), Mayne Pharma (MYX AU), ENN Energy (2688 HK), Soft99 Corp (4464 JP), Dongfeng Motor (489 HK), Joy City Property (207 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Mandom Corp (4917 JP), Humm Group (HUM AU), Ainsworth Game Technology (AGI AU), Seven West Media (SWM AU).
4. Genting Malaysia (GENM MK): Genting (GENT MK)’s Curious Offer
- Genting Malaysia (GENM MK), the owner of Resort World Genting, has announced a conditional offer from controlling parent Genting Bhd (GENT MK).
- GENT is offering RM2.35/share, an uninspiring 9.81% premium to last close, for the 50.64% of shares out not held. The Offer has a 50% acceptance threshold.
- GENT already consolidates GENM (AFAIK). At this price, compulsory acquisition won’t be afforded (you’d think). GENT should have launched the Offer back in April when the share price was floundering.
5. Korea’s Div Tax Story Suddenly Hits a Radical Inflection: Targeting Samsung Elec & Hyundai Motor
- Kim Yong-beom proposed cutting eligibility to 25%+ payout firms and hinted the Presidential Office may slash the dividend tax ceiling to 25%, potentially the boldest move yet.
- Short-Term spotlight: large-cap 25–40% payout stocks, led by Samsung Elec and Hyundai Motor. Kim Yong-beom hinted the Presidential Office wants them included to drive dividend growth.
- Big-Cap 25–40% payout stocks, especially Samsung Elec and Hyundai Motor, could see heavy flows, with their preferred shares poised to outperform in the near term.
6. [Quiddity Index] Index Consultation Anncmt Suggests The Big M Will Delete 1 LargeCap, 5 Small.
- Global Index Provider M _ _ _ announced an index consultation on Digital Asset Treausry Companies on 27 August. Friday, they extended til year-end, but gave a clear proposal update.
- They propose to exclude companies where digital asset holdings represent >50% of assets. They seek input. They also seek input on whether a company self-defines as a DAT…
- And also look at stated reasons for capital raising. A preliminary list suggests Strategy (MSTR US) and Metaplanet (3350 JP) are obvious targets. Others will be too.
7. Genting Malaysia (GENM MK): Genting’s Conditional Voluntary Offer at RM2.35
- Genting Malaysia (GENM MK) disclosed a conditional voluntary offer from Genting Bhd (GENT MK) at RM2.35, a 9.8% premium to the last close price of RM2.14.
- The 50% minimum acceptance condition is easily met as Genting is the largest shareholder, representing 49.36% of outstanding shares.
- Genting’s preferred endgame is to delist GENM, thereby fully benefiting if GENM successfully bids for a downstate New York casino licence. Therefore, there is a good chance of a bump.
8. Mayne Pharma (MYX AU): Court Rules Cosette Cannot Walk
- In a watershed decision, the Supreme Court of NSW ruled Cosette cannot terminate its Scheme for Mayne Pharma (MYX AU).
- The hearings were the first time a material adverse change clause had been considered by an Australian court under such circumstances.
- The transaction still requires FIRB signing off. Concerns linger over whether Cosette intends to close a South Australian plant. Mayne has previously dispelled these concerns.
9. StubWorld: Genting (GENT MK)’s U.S. Expansion Is A Gamble
- Genting (GENT MK)‘s Offer for Genting Malaysia (GENM MK) is further evidence of the gaming group’s move for even greater U.S. exposure.
- Preceding my comments on GENT are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
10. Value Partners: Supports Samyang Holdings’ Equity Spin-Off Plan But Must Cancel Treasury Shares
- On 13 October, Value Partners has come out in support of Samyang Holdings (000070 KS)’s equity spin-off plan but on the condition that the company must cancel its treasury shares.
- Value Partners believes Samyang Holdings is currently severely undervalued, trading at a P/B of 0.34x. A shareholders meeting for Samyang Holdings is scheduled for 14 October.
- We have a positive view of this equity spin-off. Our NAV valuation of Samyang Holdings suggests an implied price per share of 127,138 won (28.6% higher than current price).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. HSBC (5 HK)’s Clean Offer for Hang Seng (11 HK)’s Minorities
- Hang Seng Bank (11 HK) has announced an Offer from controlling parent (63.3551%), HSBC Holdings (5 HK), by way of a Scheme, in a HK$106bn (US$13.6bn) deal.
- The Scheme Consideration is HK$155/share, a 30.3% premium to last close. The price is final. A “third interim dividend” will be added. Optically, the price is bang on.
- The long stop for conditions is the 30th September 2026. I think this transaction can be wrapped up in around five months.
2. Tata Motors (TTMT IN) Demerger: Interesting Index Implications
- Tata Motors (TTMT IN) is demerging the company into two separate listed entities that will focus on the Passenger Vehicle business and the Commercial Vehicle businesses.
- Based on the estimated valuation for the two entities, both stocks will continue to remain in the MGlobal Index and the FGlobal Index.
- NIFTY and SENSEX trackers will need to sell their Commercial Vehicle business holdings soon after listing. There could be selling in the Passenger Vehicle business holdings at a later rebalance.
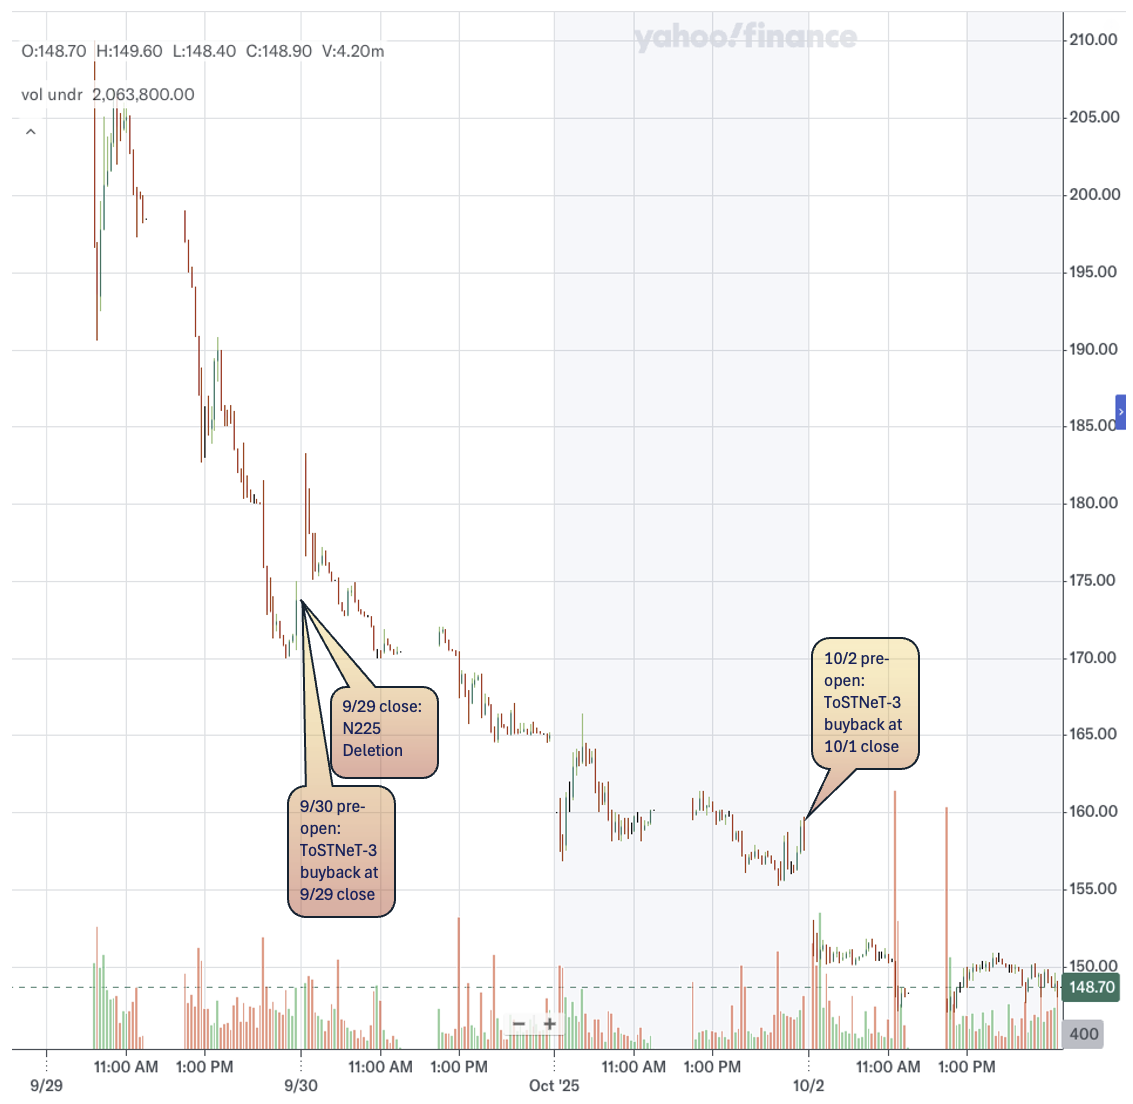
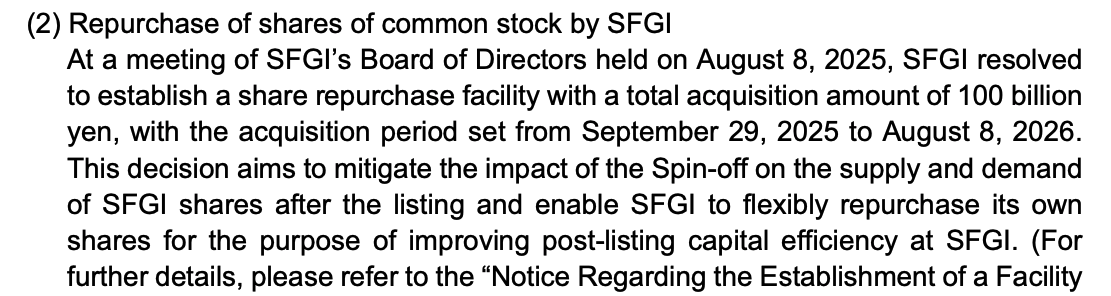
3. [Japan Event] Sony Financial (8729 JP) Moves On From ToSTNeT-3 Buybacks, Now In the Market
- Sony Financial Group (8729 JP) started ToSTNeT-3 buybacks last week and did one this week to jumpstart the buyback, cushioning the Nikkei 225 deletion on 29 Sep and subsequent overhang.
- In three ToSTNeT-3 buybacks in 6 trading days spending ¥28.9bn, the company bought back 177.513mm shares or 2.5% of shares out, or about 6.2% of Max Real World Float (MRWF).
- With ¥71.1bn left, at last that’s 460mm shares, or 16.2% of MRWF. Over 10mos that is 1.62%/month. That will boost Mar26 DPS, Mar27 DPS projections, EPS, etc.
4. Dongfeng Motor (489 HK): VOYAH Listing Docs Underscore the Upside
- On 22 August, Dongfeng Motor (489 HK) disclosed a pre-conditional privatisation by merger by absorption by Dongfeng Motor Corporation, along with a proposed distribution and listing of VOYAH shares.
- The VOYAH application proof, filed on 2 October, points to strong fundamentals and suggests that the appraised value of VOYAH and the offer are conservative.
- Based on the data points from the application proof, I calculate that the implied offer is HK$12.11-12.25 per H Share, a 11.6%-12.9% premium to the appraised value of HK$10.85.
5. Korea’s Mandatory Treasury Share Cancellation Situation Creates New Passive Flow Dynamics
- KRX may preemptively adjust KOSPI 200 screening, switching from full market cap to market cap excluding treasury shares for index inclusion.
- With treasury-share cancellation likely this quarter, KRX may act before June ’26. For December KOSPI 200, we should run both full-cap and ex-treasury screens; flows could behave unusually.
- Focusing on Hanssem (009240 KS) and Taekwang (003240 KS); borderline, high treasury shares, potential KOSPI 200 exclusion, making them key flow-sensitive setups for December reshuffle.
6. Dongfeng (489 HK): On VOYAH’s Updated Financials
- On the 22nd August 2025, SOE-backed Dongfeng Motor (489 HK) announced a privatisation; together with a concurrent listing of its EV arm, VOYAH.
- Dongfeng has now released the application proof for VOYAH, with finances through to July 2025. Of interest, VOYAH is in the black for 7M25.
- The market is implying a price-to-trailing-sales of 1.5x for VOYAH versus the basket average of 2.1x.
7. [Japan Activism] Sun Corp (6736) Gets ANOTHER Public Activist – ValueAct Reports 7.9%
- Today after the close, Value Act reported that it owned 7.87% of shares outstanding in Sun Corp (6736 JP) and it may make proposals to management.
- This has been trading cheaply (and I pointed it out on 13 Aug and 12 Sep). Cellebrite DI (CLBT US) is up 35% in those 8 weeks. Sun Corp +50%.
- ValueAct had owned 4.9+% for at least a few months before, but now it has gone public. They were likely in already under a different name in March, now public.
8. Merger Arb Mondays (06 Oct) – Kangji, Soft99, I-Net, Daiseki, Mandom, Changhong, Smart Share
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Smart Share Global (EM US), Mayne Pharma (MYX AU), ENN Energy (2688 HK), Soft99 Corp (4464 JP), I Net Corp (9600 JP), Daiseki Eco. Solution (1712 JP).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Humm Group (HUM AU), Mandom Corp (4917 JP), Seven West Media (SWM AU), Ainsworth Game Technology (AGI AU).
9. [Japan M&A/Activism] Soft99 Board Rebuts Effissimo’s Rebuttal. Still An Awful “Fiduciary” Response
- Today after the close, Soft99 Corp (4464 JP)‘s Board issued a statement on “Our View” of Effissimo’s “Our View” Press Release. It’s bad.
- But it points out the “weaknesses” that Effissimo’s Tender Offer Press Release had as it concerns a counterbid. And that tells you how Effissimo should amend their Tender Offer docs.
- Soft99 Board’s response is interesting. It asks Effissimo to not be coercive (i.e. bid for 50%+) in response to the MBO Bid’s coerciveness. Not a winning argument but not impossible.
10. [Japan Activism] Mandom (4917 JP) MBO Sees Murakami Pushing Harder, Now at 16.59%
- Four weeks ago, CVC announced a family-led MBO of hair care and cosmetics company Mandom Corp (4917 JP) at a price which was decidedly too light, well below company plans.
- One activist wrote a letter clearly calling them out for accepting a low-ball price well below the Medium Term Management Plan target. Another bought a lot of shares.
- On 25 September, Murakami-san and affiliates reported an 8.39% position. Seven trading days later it is 16.59% and the shares are up small from my last piece + 1.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
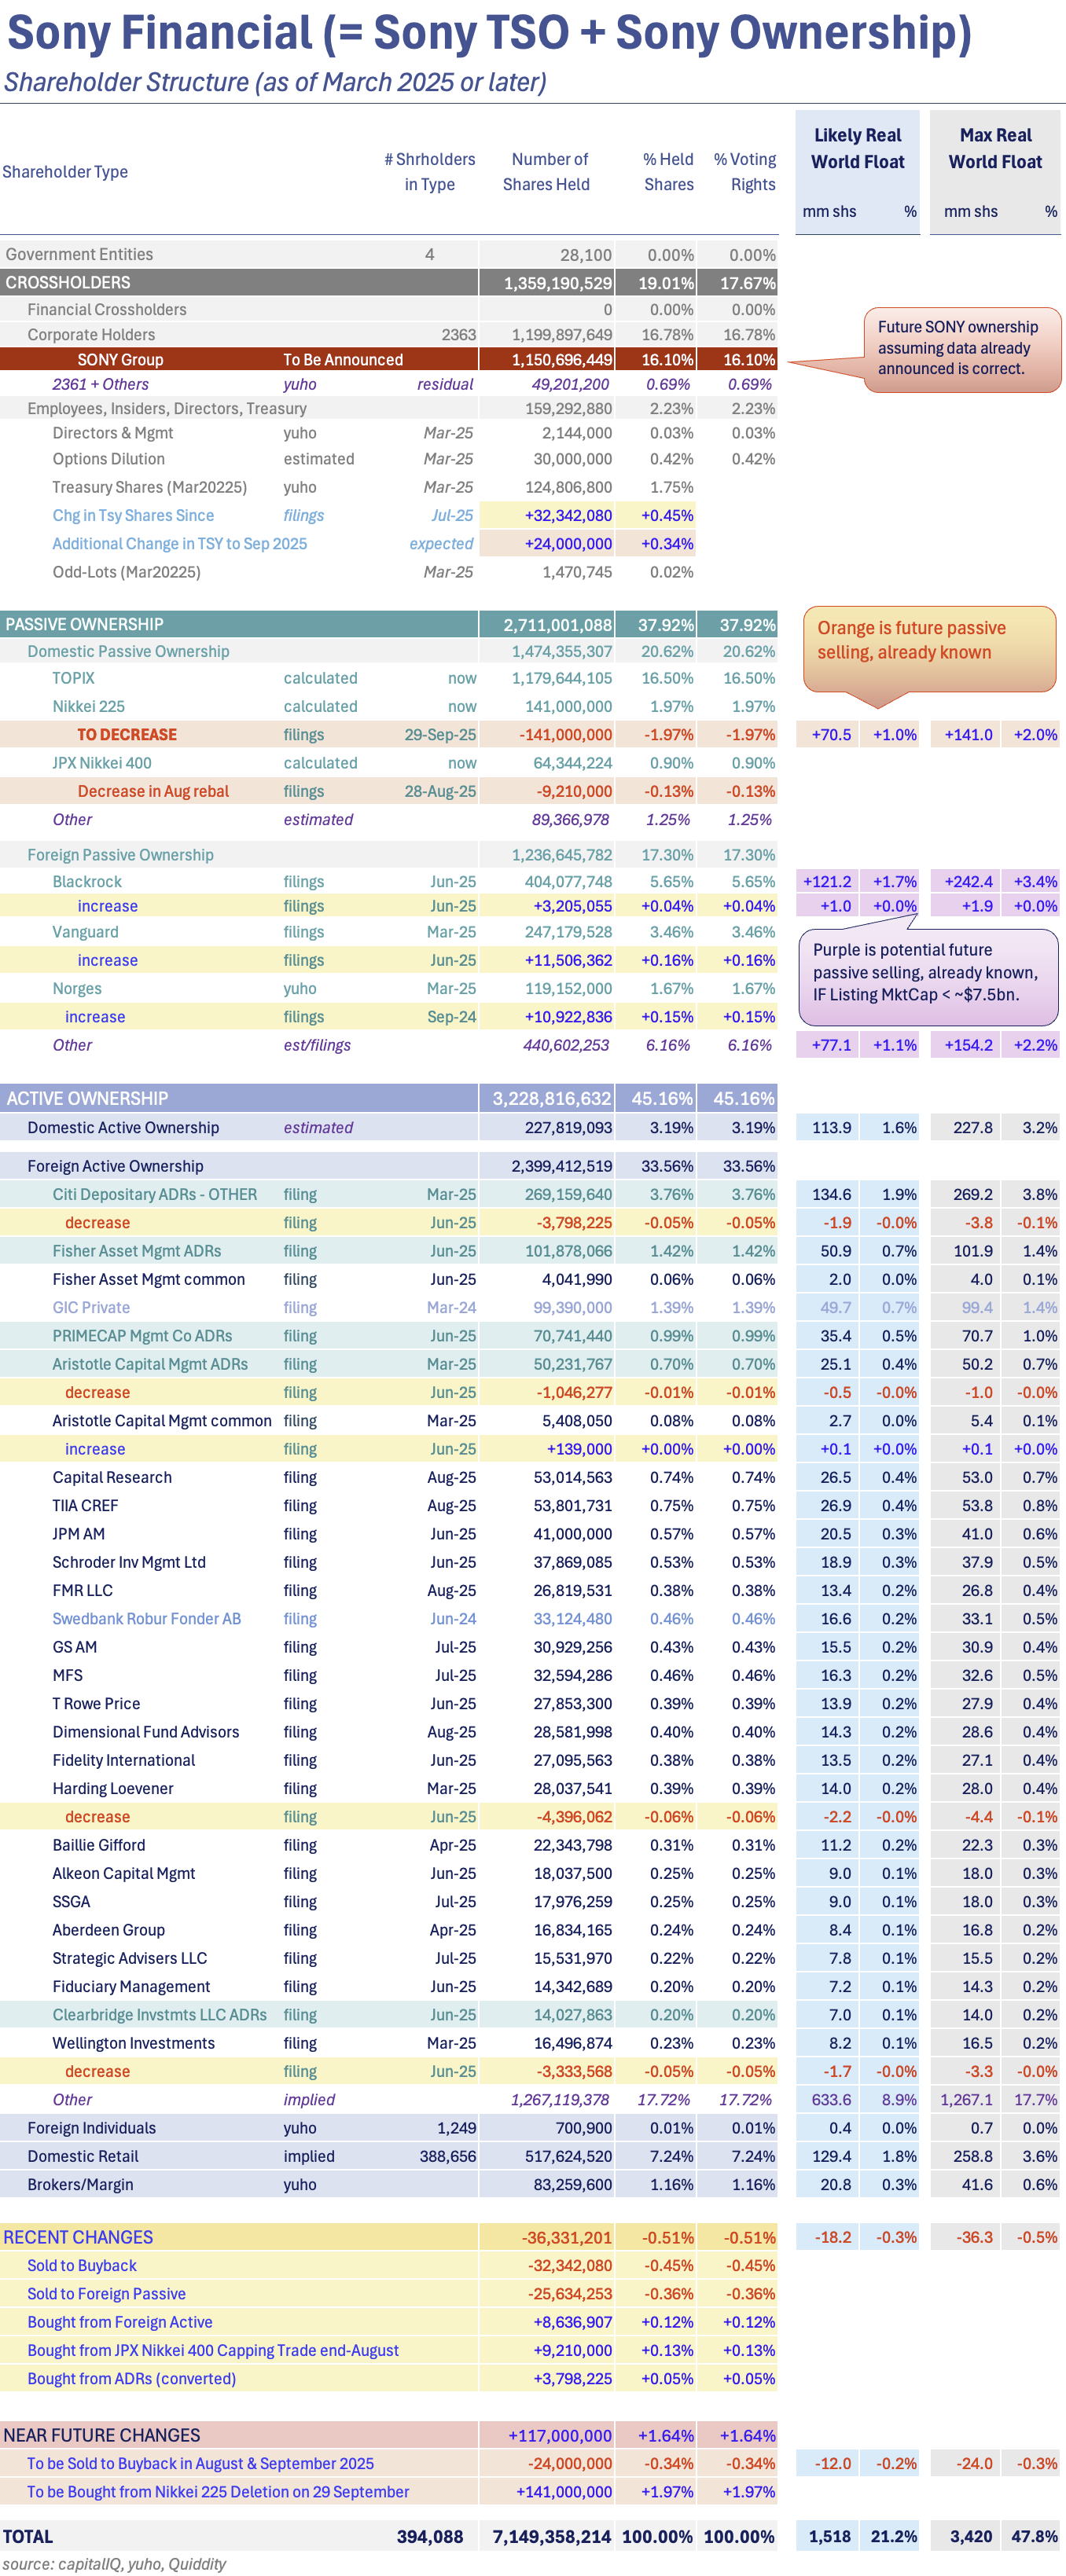
1. [Japan Event] Sony Financial (8729 JP) Overhang Hangs Over, Company Buys Back, ADR Selldown Awaits?
- Sony Financial Group (8729 JP) listed on Monday with a “Reference Price of ¥150. It opened at ¥205, quickly running to ¥210, then fell to ¥198 by lunch. Close? ¥173.8.
- That got a big ToSTNeT-3 buyback at ¥173.8. It traded lower on Day 2, closing at ¥164. Then lower still on Weds with another TN-3 buyback now ¥159.4.
- Neither buyback was full. SFGI has bought back 124mm shares. But the stock has fallen hard. ADRs/ADSs start trading Tuesday. That could see more selling.
2. Tekscend Photomask (429A JP) IPO: TPX Add in Nov; Global Index: One in Feb; One in June
- Tekscend Photomask (429A JP)‘s listing has been approved by the JPX and the stock is expected to start trading on the Prime Market from 16 October.
- At the top end of the IPO range at JPY 3000/share, Tekscend Photomask (429A JP) will be valued at JPY 298bn (US$2bn).
- The stock should be added to the TOPIX INDEX at the close on 27 November while inclusion in global indices should take place in February and June.
3. [Japan M&A] Mitsubishi Logisnext (7105) – This Deal Looks Mighty Bad
- JIP and MitHeavy have announced a takeunder to buy out MitHeavy sub Mitsubishi Logisnext Co., Ltd. (7105 JP) at a weighted average price 42% lower than Target Advisor DCF range midpoint.
- No/Minimal transparency. A sales process interrupted by Trump tariffs, leaving one low-ball bidder. And the sellers goes ahead with it BUT gets to reinvest on the back end. You don’t.
- The Board “supports” the Tender Offer, but leaves it to the opinion of the shareholders as to whether they tender. MitHeavy has 64.4% already so that basically gets done. But…
4. Mitsubishi Logisnext (7105 JP): JIP’s Takeunder Offer
- Mitsubishi Logisnext Co., Ltd. (7105 JP) announced a pre-conditional tender offer from Japan Industrial Partners (JIP) at JPY1,537 per share, representing a 15.3% discount to the last close price.
- The offer resulted from an auction process. The offer is light in comparison to peer multiples and is below the midpoint of the target IFA DCF valuation.
- While Mitsubishi Heavy Industries (7011 JP) irrevocable has a competing proposal clause, it is unlikely that a bidding war will transpire. The low required tendering rate suggests a done deal.
5. Merger Arb Mondays (29 Sep) – Soft99, Ashimori, Mandom, Paramount, OneConnect, Dongfeng, Spindex
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Smart Share Global (EM US), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Soft99 Corp (4464 JP), Joy City Property (207 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Humm Group (HUM AU), Mandom Corp (4917 JP), Paramount Bed Holdings Co Lt (7817 JP).
6. Curator’s Cut: BABA Hedges, Substantive Spin-Offs & Japanese Activist Situations
- Welcome to Curator’s Cut, a fortnightly roundup of standout themes from the 1,000+ Insights published over the past two weeks on Smartkarma
- In this cut, we review strategies to hedge Alibaba (9988 HK) exposure, examine signficant Asian spin-offs, and explore engaging activist situations in Japan
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next
7. LG Electronics India IPO: Big Market Cap, Small Float -> Small Passive Flows
- LG Electronics India (123D IN) is looking to list on the exchanges by selling 101.8m shares at a valuation of US$8.7bn and raising around US$1.3bn in its IPO.
- The new valuation is around 24% lower than the rumoured valuation at the time of the DRHP filing last December.
- The stock will not get Fast Entry to global indices. Inclusion at regular rebalances will commence in June 2026 but flow will be small given the low float.
8. Jardine Matheson (JML SP): Additional Office Recycling Speculated
- The prior MO for the Jardines group was never sell your commercial buildings. This year marks a paradigm shift in that line of thinking.
- First Hongkong Land (HKL SP) sold nine floors of One Exchange Square to HKEX (388 HK). The first such sale since 1988.
- Now Mandarin Oriental (MAND SP) is negotiating the sale of “certain office space” at One Causeway Bay. Jardine Matheson (JM SP)‘s NAV discount and implied stub are at 12-month lows/highs.
9. Tata Capital IPO: Big Listing, Big Valuation, Small Float
- Tata Capital Limited (TATACAP IN) is looking to list on the exchanges by selling up to INR155bn (US$1.75bn) of stock at a valuation of around INR 1,384bn (US$15.6bn).
- The stock will not get Fast Entry to either of the global indices. The earliest inclusion in a global index should take place in June 2026.
- The stock should be added to the Large Cap segment in the AMFI Classification in January and to the Nifty Next 50 Index in March.
10. LG Chem: Announces a PRS Worth 2 Trillion Won Using Its Shares in LG Energy Solution as Base Asset
- LG Chem announced that it plans to complete a price return swap worth about 2 trillion won (US$1.4 billion) using its stake in LG Energy Solution as the base asset.
- This 2 trillion won PRS is likely to have a slightly positive impact on LG Chem and slightly negative impact on LG Energy Solution.
- Our NAV valuation of LG Chem suggests implied NAV per share of 369,187 won, which is 31% higher than current levels.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Event] Sony Financial Spin-Off Trades Monday – Fina(Ncia)L Thoughts
- Today is the last day of trading for Sony Corp (6758 JP) with Sony Financial Group (8729 JP) spin-off rights. SFGI starts trading separately on Monday 29 Sep.
- The reference price is ¥150/share. It will likely stay in all major indices except Nikkei 225, and it likely needs low ¥160s to stay in M _ _ _.
- The estimated Div Yield is higher on SFGI than peers by a fair ways, and looks to grow, and there is a big buyback to come. I like it.
2. Shift (3697 JP) – Short-Selling into Nikkei 225 Inclusion = Crowded Register Dynamic = Squeezy
- Shift Inc (3697 JP) runs a software quality assurance testing business. 400% revenue growth in 5 years, but this year to Aug25 is “only” 17.5% according to Q3 results guidance.
- It was a “growth stock” for a long while, and large long-only growth investors flocked to the name. In the past several months many have exited.
- The stock will be included in the Nikkei 225 Average next Tuesday. The supply/demand dynamics here to there are interesting. Afterwards they may be more interesting.
3. [Japan M&A] Paramount Bed (7817 JP) Founding Family Takeout – Too Cheap, Deserves Activist Response
- In a fairly common pattern, the founding family (38% ownership) of Paramount Bed Holdings Co Lt (7817 JP) have launched an MBO.
- It is too cheap at 4.2x adjusted EV/EBITDA (one could argue it is 5.0x but they also have net receivables) for such a ubiquitous brand and growth.
- Soft99 Corp (4464 JP) may have been a one-off. Maybe not. People may look at this situation through that lens. It deserves that look.
4. [Japan M&A/Activism] Soft99 Board Comes Out Against Effissimo Bid 66% Above MBO Price
- Today after the close, the Soft99 Corp (4464 JP) Board of Directors came out AGAINST the Effissimo ¥4,100/share counterbid to the original ¥2,465/share MBO.
- “The Special Committee advised that the Tender Offer would not contribute to the enhancement of the Company Group’s corporate value, nor would it be fair to the Company’s general shareholders.”
- ¥2,465 is fair. ¥4,100 is not fair. Absolute hogwash. Unmitigated blatherskite. Pure trumpery. Codswallop, buncombe, taradiddle, balderdash, and nincompoopery too. I expound below.
5. HK Connect SOUTHBOUND Flows (To 19 Sep 2025); BIG Single Stock Trading Again, Feels Slightly Toppish
- Gross SOUTHBOUND volumes just over US$22+bn a day this past 5-day week. Biggest week in a while. Net Flows not following gross flows. Feels toppish into GW.
- The recommended name last week was Alibaba (9988 HK) was up 2.2% on the week but only +0.7% from Monday close to Friday.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Pairs Monitor are both there for all SK readers.
6. The BOJ Announces the Start of ETF/JREIT Selldowns – Basically a Nothing-Burger
- In Friday’s Monetary Policy Statement, the BOJ announced it would start selling down its holdings in ETFs and J-REITs at the pace of ¥620bn and ¥5.5bn/year, respectively. BIG NEWS!
- That is US$17mm of ETFs and US$150k of J-REITs per day. The BOJ suggests it is 0.05% of volume per day. That’s close. SMALL EFFECT.
- Given ¥15trln of buybacks and ¥5trln+ of dividend reinvestment + NISA account buys, plus ¥trlns of cross-holding selldowns/year, this is a total nothingburger, even if they up the pace.
7. Korea Semicon ETF Rebal October Play: 2 In, 2 Out Long-Short Setup
- MTD screening results with 5 trading days left point to 2 names going out and 2 names coming in: Gemvax and Wonik IPS replace Dongjin Semichem and Jusung Engineering.
- Unlike last April’s tariff-distorted +1.3% rebalance, this time we expect cleaner, more meaningful price action.
- No pre-positioning seen, so I’ll target ETF rebalance day (Oct 10) and maybe take an anticipatory position a day earlier.
8. Sony Spin-off (Sony Financial Group) Spin-off Deep Dive
- Sony Group Corporation (6758) is planning to spin off 80% of its stake in Sony Financial Group Inc. (8729) on September 29, 2025.
- Sony Financial Group Inc. is the financial services arm of Sony, comprised of three main businesses
- The spin-off will generate ~ ¥100BN in the current fiscal year and pay a ¥50BN annual dividend.
9. Merger Arb Mondays (22 Sep) – Technopro, Soft99, Mandom, Pacific Ind, Dongfeng, Shengjing, Smartpay
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Smart Share Global (EM US), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Oneconnect Financial Technology (6638 HK), Joy City Property (207 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), PointsBet Holdings (PBH AU), Mandom Corp (4917 JP), Humm Group (HUM AU), Fuji Oil Co Ltd (5017 JP).
10. Soft99 Corp (4464 JP): The Board Opposes Effissimo’s Hostile Offer and Hints the MBO Will Succeed
- The Soft99 Corp (4464 JP) Board has, unsurprisingly, opposed the Effissimo offer for several reasons. Notably, they do address the huge price disparity between the two offers.
- While most of the reasons to justify the opposition are weak, the Board unexpectedly notes that as of 24 September, the MBO retained acceptances to satisfy its minimum tendering condition.
- Despite the significant premium of the Effissimo offer, this development suggests that the current acceptances for the MBO are sticky, thereby increasing the likelihood that Effissimo’s offer will fail.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
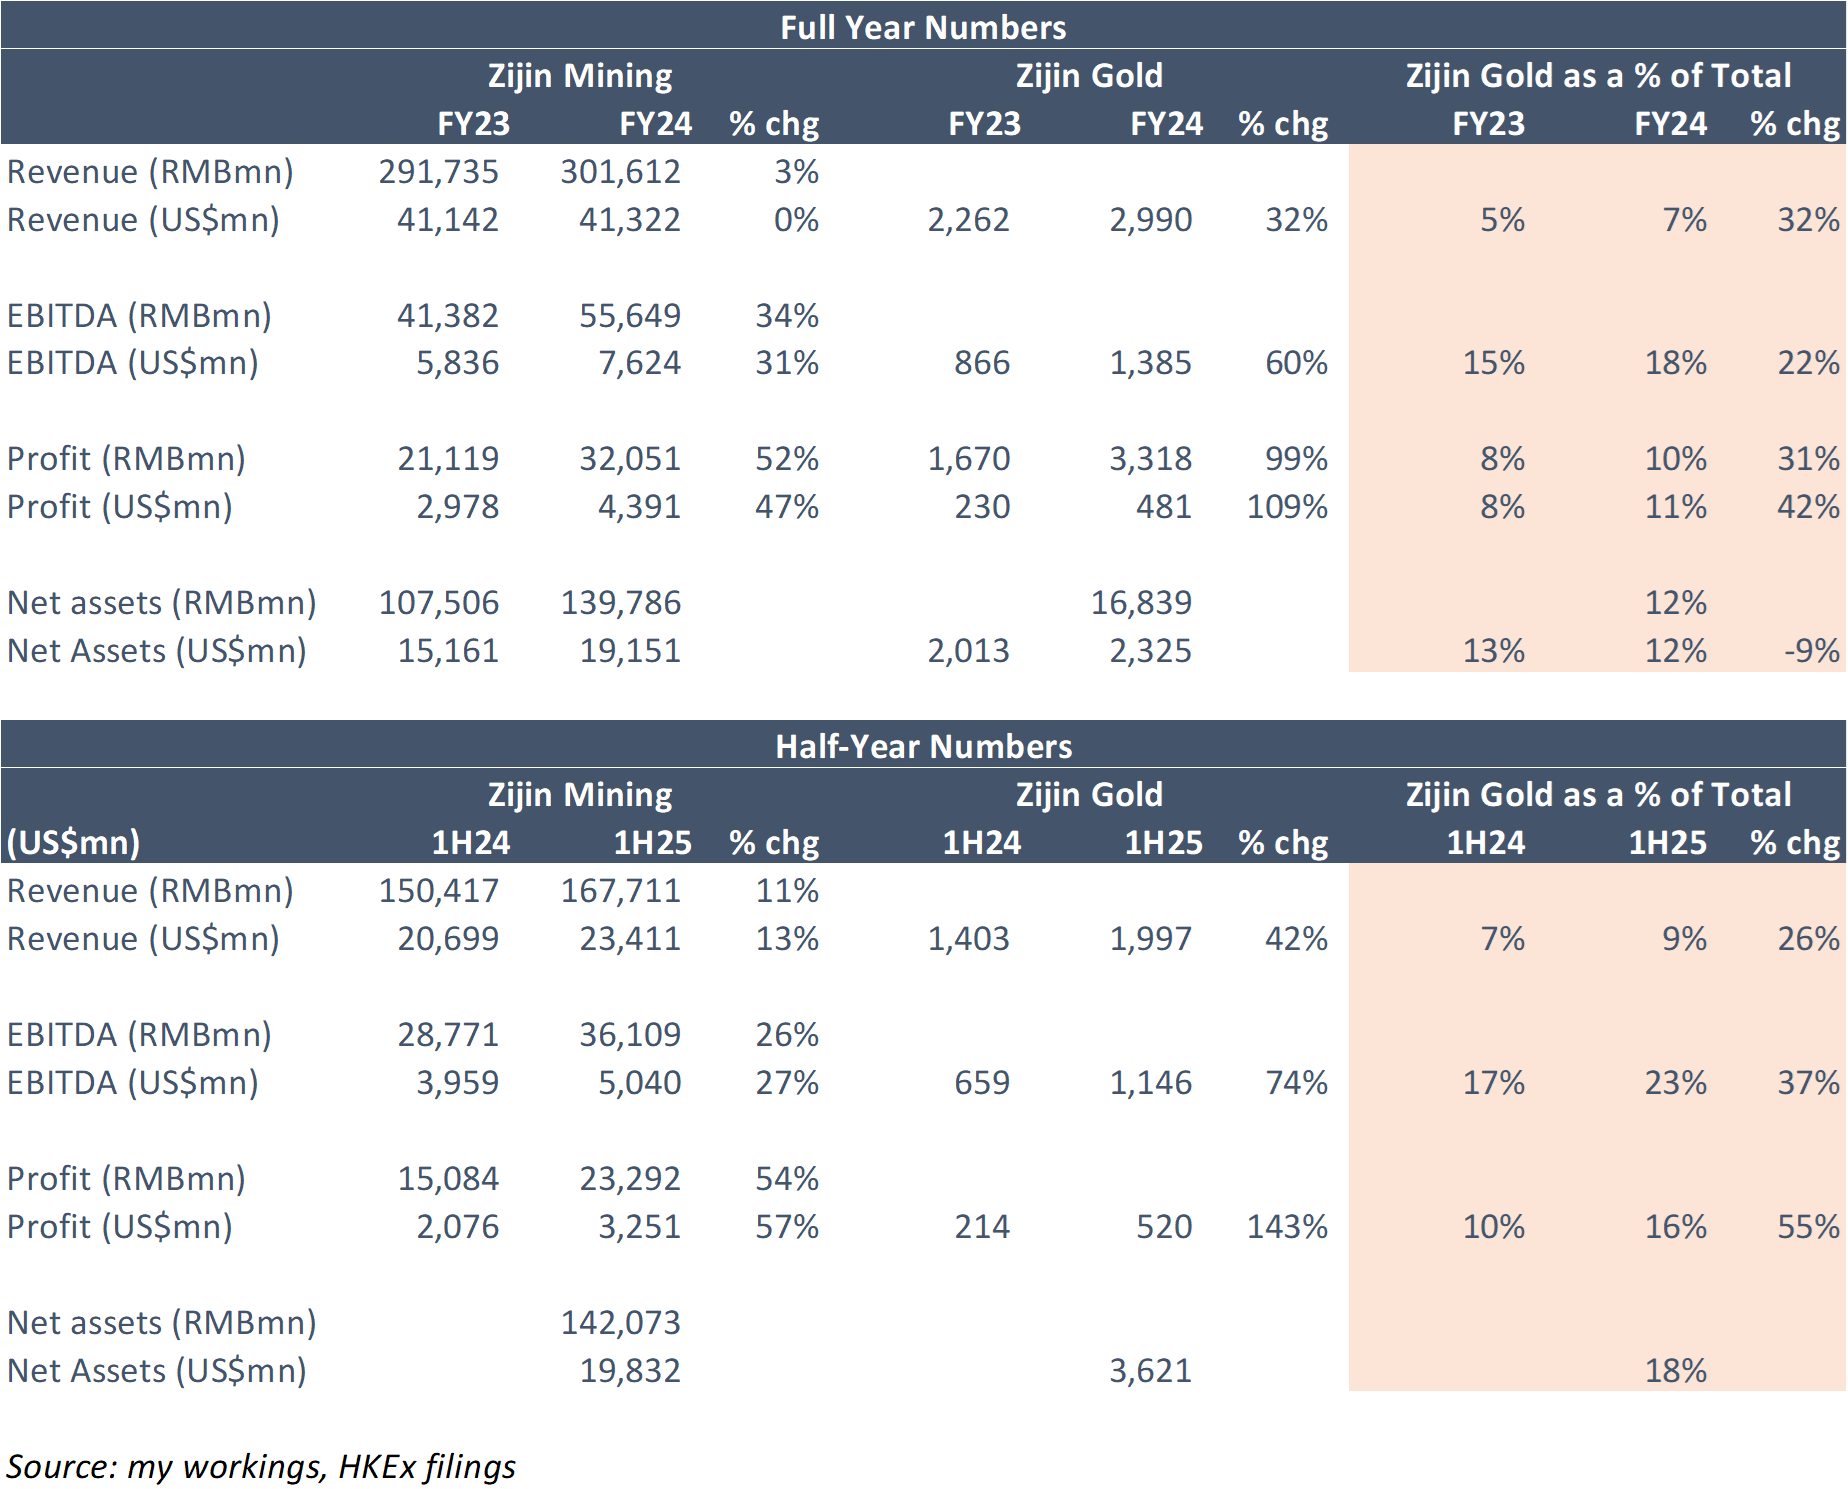
1. Zijin Mining (2899 HK): This Is A Short
- In my June note, Zijin Mining Group (2899 HK) appeared fully valued; but I (thankfully) stopped short of being outright bearish. Its share price is up 48% since!
- A basket of peers is also up 37% since that note. Gold is up~8%, and 41% YTD. On the 14th September, Zijin released Zijin Gold’s PHIP. 1H25 numbers were solid.
- However, Zijin Gold’s earnings are by no stretch an outlier. Zijin’s Mining’s current share price is now baking in exceptional (unrealistic?) metrics for the gold play spin-off.
2. Zijin Gold (2259 HK) IPO: HSCI Fast Entry; Quick Stock Connect Add; Global Indices Entry in 2026
- Zijin Gold (2259 HK) is looking to raise up to HK$28.7bn (US$3.7bn) in its IPO, valuing the company at HK$191.6bn (US$24.6bn).
- Zijin Mining (2899 HK) will hold between 85-86.7% of Zijin Gold and that will limit the free float of the stock. Half the IPO has been allotted to cornerstones.
- Zijin Gold could be added to the HSCI via Fast Entry and to Stock Connect in October. Global index inclusion should take place in the first half of 2026.
3. [Japan M&A/Activism] SOFT99 MBO Sees Activist EffissimoOverbid by 66%! Will This Set New Precedent?
- In early August, the founder-family announced they would MBO the car care company Soft99 Corp (4464 JP). It was a very cheap MBO. Even 20% higher it would be cheap.
- On Saturday, Kyodo, followed by various other media outlets, announced activist Effissimo Capital Management had announced a TOB to buy the company saying the MBO was “an extremely low level.”
- The Nikkei-reported goal would be “to protect the interests of minority shareholders while ensuring medium- to long-term increases in corporate value.” This is REALLY BIG NEWS.
4. Chery Auto (9973 HK) IPO: No Inclusion in Global Indices; HSTECH Is Interesting
- Chery Automobile Co. Ltd. (9973 HK)‘s IPO range is HK$27.75-HK$30.75/share and will raise up to HK$10bn (US$1.3m) if the oversubscription option is exercised, valuing the company at HK$169bn (US$21.7bn).
- The stock should be added to the HSCI Index in December and that will make the stock eligible for inclusion in Southbound Stock Connect.
- There will be no inclusion in global indexes for the next year, but there is a possibility of inclusion in the Hang Seng TECH Index (HSTECH INDEX) in December.
5. Mori Hills REIT (3234) – Large Sponsor Buy in Market as % of Max Real World Float
- In the past 24 months, J-REIT sponsors have bought units in their REITs at sharp discounts to PNAV to raise PNAV and reduce overhang pressure.
- The goal is, basically transparently, to get PNAV to a level at which the REIT can buy more properties from the sponsor, who carries them at a much higher WACC.
- Mori Building has announced a 4.99% buy on Mori Hills REIT Investment Corporation (3234 JP) which is a Very Big portion of Max Real World Float. This should influence price.
6. HK Connect SOUTHBOUND Flows (To 12 Sep 2025); HUGE Single Stock Trading, ETFs Meh. Tech Bought Bigly
- Gross SOUTHBOUND volumes just under US$20+bn a day this past 5-day week. BIG Net buying. Big BABA trading.
- SOUTHBOUND investors traded US$9bn of Alibaba (9988 HK) in the week. Not shy. It was a big net buy as well (4 of 5 days was +US$500mm or more).
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Pairs Monitor are both there for all SK readers.
7. Soft99 Corp (4464 JP): Effissimo Sheds More Light on Its Hostile Offer
- Effissimo has formally launched its hostile tender offer for Soft99 Corp (4464 JP) at JPY4,100, which is 66.3% higher than the MBO price of JPY2,465.
- The Board stonewalled Effissimo’s attempts to negotiate a friendly offer. The huge premium of Effissimo’s offer relies on lower WACC assumptions compared to the target/special committee IFA.
- Management’s initial approach will be to rely on the Board to oppose the Effissimo offer. There is a good chance that Soft99 will remain listed with two large shareholders.
8. [Japan M&A/Activism] The Nagging Little Detail In the Soft99 MBO Extension Target Doc
- Yesterday, Soft99 Corp (4464 JP) announced a slight change in its “Target Opinion Document” after the MBO Bidco extended its TOB by 8 days the day before.
- The detail was not in the MBO Bidco extension. It was just revealed in an added note on p3 of the Target Opinion.
- That details matters A LOT to people looking at the Effissimo Overbid. The company’s Board has some serious work ahead.
9. Flagging a New Passive Flow Trading Opportunity Triggered by Korea’s Divvy Policy Momentum
- PLUS High Dividend ETF (161510 KS) reshuffle is now a key flow catalyst: June saw GS E&C and HD Hyundai out, Hyundai Motor in, with sharp one-day moves.
- December review shaping up as 2-in/2-out: Seoul Guarantee (031210) and LG Corp (003550) in, Shinhan (055550) and KB (105560) out.
- Passive flows: Shinhan/KB ~0.3–0.4x DTV, LG ~3x, Seoul Guarantee 5–6x. With AUM up 30% since June, upcoming adds face outsized passive impact.
10. Zijin Mining (2899 HK): Zijin Gold Priced At US$24bn
- The global offering doc for Zijin Gold (2259 HK) is out.
- At the IPO Price of HK$71.59/share, Zijin Gold’s implied market cap is HK$187.9bn or US$24bn. Commencement of trading is the 29th September.
- Zijin Mining (2899 HK) will hold 86.7% in Zijin Gold post-IPO (before over-allotment). Even if Zijin Gold trades north of HK$100/share, Zijin Mining is fully valued.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Event/Buyback] The Sony Financial Spinoff – ‘Maybe’ BUYBACK Complicates Planning
- The Sony Financial Holdings (8729 JP) (now called Sony Financial Group Inc (“SFGI”)) spinoff approaches. It will start trading 20 days from now.
- Yesterday, the TSE confirmed approval (outline, Securities Report (J), Corporate Governance Report (J). The company provided details of a possible ToSTNeT-3 buyback on Day 2 pre-open. That complicates things.
- The introduction of that type of buyback flexibility indicates that supply overhang may be managed better than buyers would hope. Means other strategies may be necessary.
2. [Japan M&A] Mandom (4917 JP) MBO – Light Price, Open-Ish Register, Tough to Take Over, Could Do Fun
- On 10 September, the founding Nishimura family, the PE Firm CVC, and Mandom Corp (4917 JP) agreed that the first two could take over the latter at 4.9x Mar28 EBITDA.
- A cocktail napkin calculation of expected leverage suggests the equity check is buying this at 5x average Mar27-28 free cash flow. That’s cheap for a growing company.
- The register is open enough to cause problems but not open enough to allow a clean hostile bid by a strategic. But still open enough for someone to have fun.
3. Dongfeng (489 HK): Questioning The EV Listing Valuation
- Back on the 22nd August, SOE-backed Dongfeng Motor (489 HK) announced a privatisation; together with a concurrent listing of its EV arm, VOYAH.
- The share price closed up 54% on the first day, ~15% adrift of the independently valued cash + scrip (into VOYAH) under the privatisation.
- Shares have pared back 5% since. VOYAH’s peer basket has fallen ~15% on average. The market is implying a price-to-trailing-sales of 1x for VOYAH versus the basket average of 1.9x.
4. Merger Arb Mondays (08 Sep) – Kangji, OneConnect, Ashimori, Pacific Ind, RPM, Santos, Zeekr
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Smart Share Global (EM US), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Joy City Property (207 HK), Santos Ltd (STO AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Humm Group (HUM AU), Ainsworth Game Technology (AGI AU), Ashimori Industry (3526 JP), Toyota Industries (6201 JP).
5. Mandom (4917 JP): A Light CVC-Sponsored Preconditional MBO
- Mandom Corp (4917 JP) has recommended a CVC-sponsored preconditional MBO at JPY1,960, a 32.1% premium to the last close price.
- The offer is below the midpoint of the IFA DCF valuation range and the special committee’s requested price. It is unattractive compared to precedent transactions and peer multiples.
- The offer is unequivocally light. The setup has the potential for a bump, particularly if an activist emerges as a substantial shareholder.
6. Regarding the Six KRX Sector Names that Ran Ahead of Friday’s Official Review Drop
- Six names stood out with simultaneous volume spikes and sharp pops last Friday; all Semis and Autos additions with big passive impact, while all others showed no tape action.
- Results likely leaked early, prompting front-running on Semis and Autos adds—high passive impact names—causing Friday’s sharp volume and price spikes.
- Early movers are mostly priced in; Thursday momentum plays still work, but Monday–Thursday morning requires caution. Focus on volume-driven flows before loading positions, long-short basket viable for other passive-impact names.
7. [Japan M&A] Pacific Industrial (7250) The MBO Is Extended After Effissimo Buys Above Terms
- Activist-Ish-Y investor Effissimo reported Friday they had a 6.68% stake as of the end of August.
- Their average price is ¥2,253 which is 10% through the price the family Bidco was bidding (¥2,050).
- As this hasn’t traded below terms at any point since announcement, an extension was likely. This morning, we got one. We’ll get another one before it’s done, BUT…
8. Timing the HHI–Mipo Spread Play Around the Passive Inflow Kick
- HHI–Mipo spread holds 3–4%; cancellation risk minimal. Market views HHI as the cleaner MASGA play vs. Mipo, keeping the spread sticky and unlikely to tighten soon.
- Potential kicker for widening comes from passive inflows when Mipo halts, as HHI gains weight in Global Standard vs. Mipo’s Small Cap.
- HHI may see ~4x DTV passive inflow as it absorbs Mipo; pre-announcement flows could start late October, potentially widening the swap spread ahead of the Nov 27 halt.
9. PointsBet (PBH AU) And Mixi Double Down Ahead Of Offer Closing
- On the 29th August, Mixi (2121 JP) cleared 50% of the voting power in PointsBet (PBH AU). It’s Offer was automatically extended, and will now close on the 12th September.
- Mixi has 51.59%. betr Entertainment (BBT AU) said it holds 20.45%, plus 6.5% in the IAF, the instructions for which can be withdrawn. betr said it won’t accept Mixi’s Offer.
- Mixi adds betr will have no PBH board representation “either now or in the future”; and betr will continue to be a clear competitor. Additionally, PBH questions betr’s buyback funding,
10. StubWorld: The Murdoch Succession Into News Corp, Fox & REA
- After a protracted succession stoush, Rupert Murdoch’s son Lachlan is set to take control of News Corp (NWS US) and Fox (FOXA US).
- Preceding my comments on News Corp and 62%-held REA Group Ltd (REA AU) are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
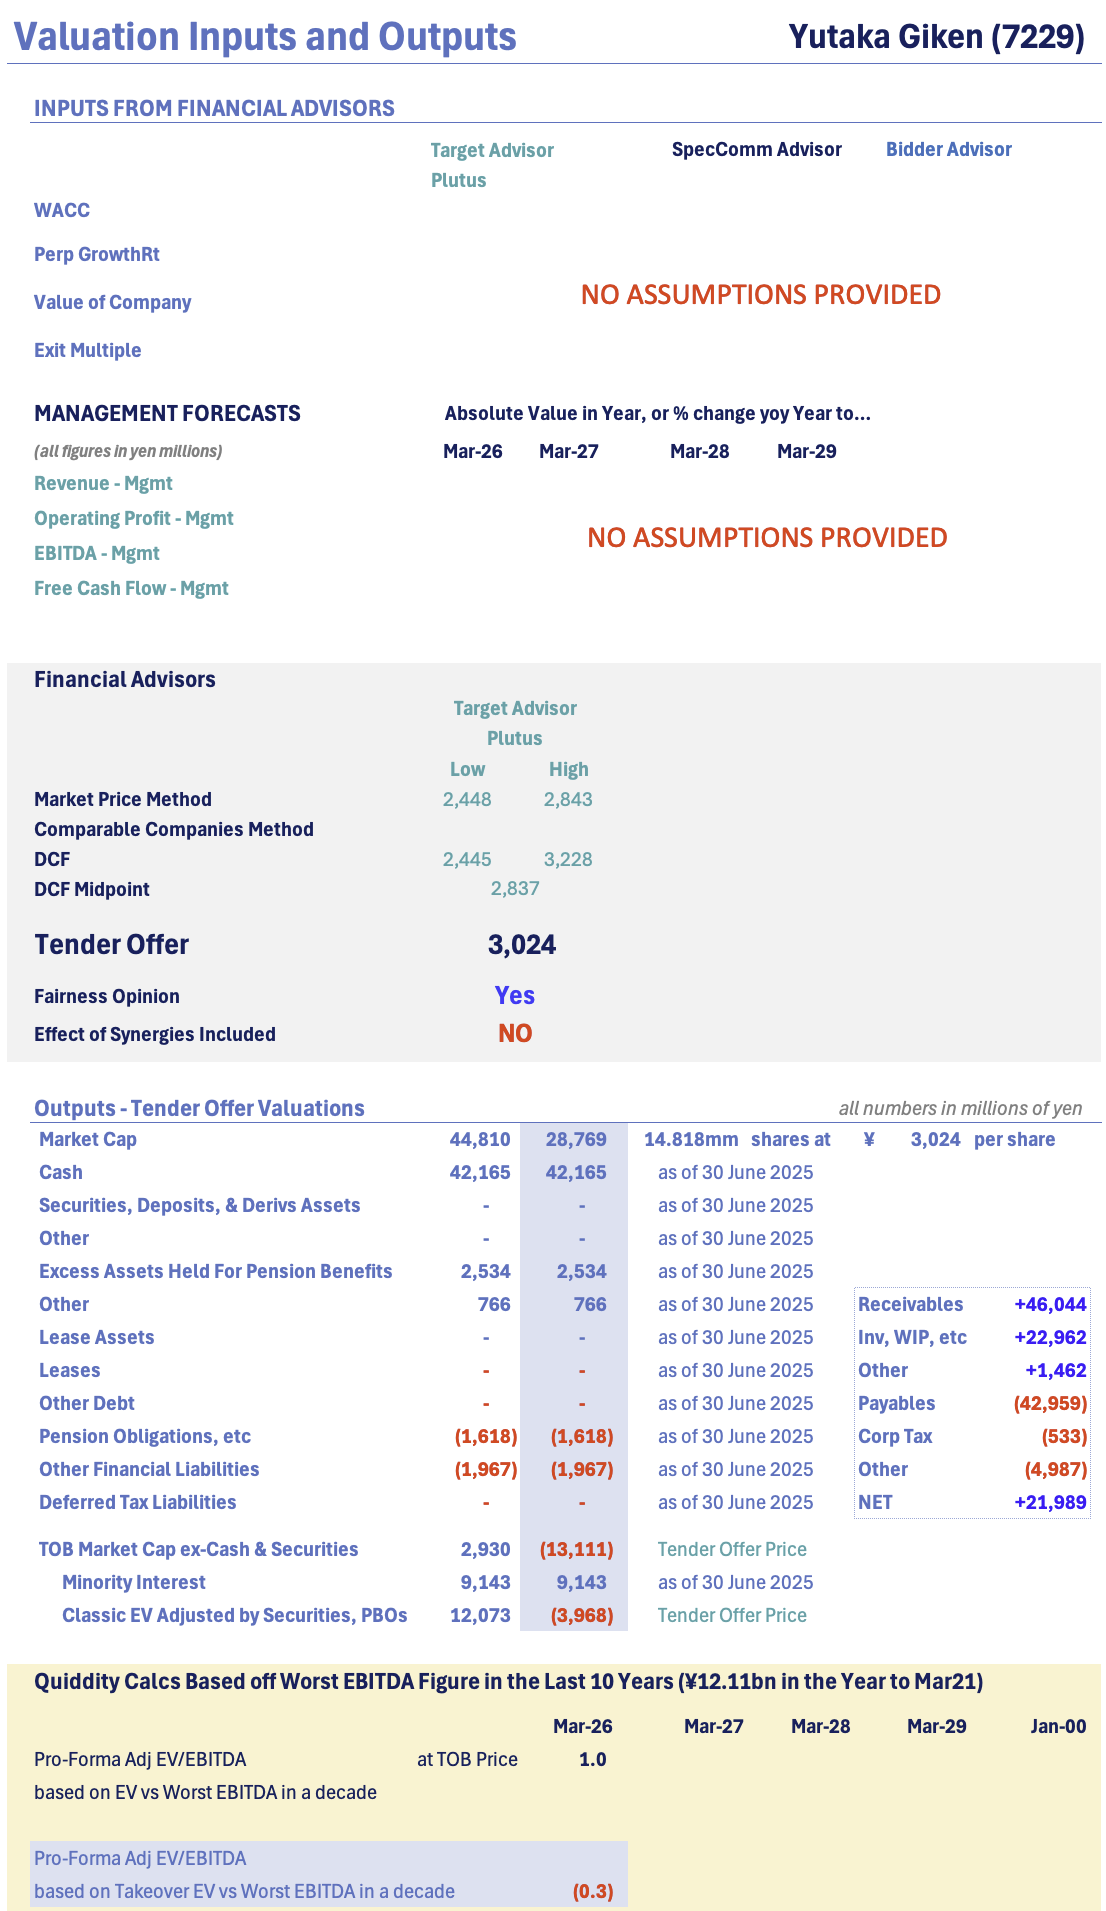
1. [Japan M&A] Yutaka Giken (7229 JP) TOB – Possibly the Most Offensively Low TOB Price I’ve Ever Seen
- Honda Motor (7267 JP) and Samvardhana Motherson International Ltd (MOTHERSO IN) have arranged to buy Honda’s 69.7%-owned subsidiary Yutaka Giken (7229 JP) in a Tender Offer.
- The transaction structure means Motherson buys Yutaka for less than net cash but even assuming Motherson pay minority TOB price for everything, TOB ex-net cash = 0.05x PBR, <1x EBITDA.
- But they are paying less. They are paying ¥12.4bn less than net cash, and getting the other ¥58bn of net assets (¥23bn inventory, the rest in hard assets) for free.
2. Holdco NAV Discount Compression Play on Korea’s Next Policy Narrative: Mandatory Tender Offers
- Korean equities are stalled; macro catalysts are absent. Street focus shifts from treasury share cancellations to next year’s mandatory tender offers, now seen as the top policy driver.
- Pre-MTO trades focus on holding companies with wide NAV discounts or low controlling stakes, front-running policy-driven re-ratings before minority shareholders capture control premiums.
- Focus on 32 Korean holding companies >KRW 500B; those with wide NAV discounts and lighter controlling stakes—SK’s holding companies, Samsung C&T, Hanwha, LG, LS—are prime re-rating plays.
3. ZEEKR (ZK US): Widening Scrip Spread Ahead Of Geely EGM Vote
- On the 15th July, Geely Auto (175 HK), China’s second-largest carmaker, firmed a cash or scrip Offer for 62.8%-held ZEEKR (ZK US), a premium Chinese electric vehicle manufacturer
- ZEEKR has traded through the cash terms US$26.87/ADS from the onset; but at a discount to the scrip terms. The scrip spread has widened recently.
- The Offer is low-balled. However, Geely’s stake plus Li Shufu (founder)’s 10.61% holdings push the Offer through. Geely’s EGM is this Friday (7th July). Li (41.34%) is required to abstain.
4. Merger Arb Mondays (01 Sep) – Dongfeng, ENN, Joy City, Kangji, Mayne, Santos, Shibaura, CareNet
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Smart Share Global (EM US), ENN Energy (2688 HK), Dongfeng Motor (489 HK), Joy City Property (207 HK), Santos Ltd (STO AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Humm Group (HUM AU), Ashimori Industry (3526 JP), Carenet Inc (2150 JP), Ainsworth Game Technology (AGI AU).
5. HKBN (1310 HK): Mobile’s Offer Is Done. Now For The Back End
- China Mobile (941 HK)‘s Offer for HKBN Ltd (1310 HK) will be declared unconditional tomorrow (3rd September), the first closing date.
- As I type, 19.03% of shares out have tendered, lifting Mobile’s stake to 48.9%. Additional shares will tip in today and tomorrow, as per your typical last minute flurry.
- It is not Mobile’s intention to delist HKBN. There will be investors playing the backend on the expectation of a higher Offer down the track.
6. HKBN (1310 HK): On the Cusp of Being Declared Unconditional
- HKBN Ltd (1310 HK)’s offer from China Mobile (941 HK) is HK$5.075 with a 50% minimum acceptance condition. The first closing date is September 3.
- Based on CCASS data, including acceptances, China Mobile’s shareholding was 48.93% of outstanding shares as of September 1.
- Therefore, the offer should be declared unconditional by the first closing date. At the last close and for a September 12 payment, the gross/annualised spread is 0.5%/15.7%.
7. Pacific Industrial (7250 JP): Effissimo Rears Its Head
- Effissimo reported a 5.87% ownership ratio in Pacific Industrial (7250 JP). The average buy-in price of JPY2,235.91 per share is 9.1% above the JPY2,050 MBO offer.
- Effissimo buying significantly above terms is justifiable as the offer implied a P/B of 0.71x. Effissimo is agitating for either a bump or an opportunity to participate in the back-end.
- With the offer closing on 8 September and shares trading 16.9% above terms, the Ogawas have little choice but to revise terms.
8. Alipay: Issuing EB Worth 627 Billion Won Backed By Its Shares in Kakao Pay [A Quasi Block Deal Sale]
- Alipay (second largest shareholder of Kakaopay (377300 KS)) is issuing an overseas exchangeable bonds (EB) worth 627 billion won (backed by its shares in Kakao Pay).
- The exchange price of the EB is 54,744 won (4.5% discount to current price). Total amount of EB issue is 627 billion won ($450 million).
- This deal is basically a quasi-block deal. Alipay is trying to unload some of its stake in Kakao Pay to improve its finances.
9. Ashimori Industry (3526 JP): Murakami Outlines His Case
- Takateru Murakami, Yoshiaki Murakami’s son, has increased his Ashimori Industry (3526 JP) to an 18.36% ownership ratio at an average buy-in price of JPY4,154.28 vs. the JPY4,140 tender offer.
- Crucially, in today’s disclosure, Takateru Murakami outlines the rationale for his stake building, which centres on the book value being materially understated if certain land were revalued at market rates.
- Maintaining current terms is increasingly not a viable option. Toyoda Gosei (7282 JP) is likely to pursue a strategy of either increasing its offer or lowering the minimum acceptance condition.
10. Curator’s Cut: Arbs Go A-H, Copper Plays & China’s Property Pulse
- Welcome to Curator’s Cut, a fortnightly roundup of standout themes from the 1,200+ Insights published over the past two weeks on Smartkarma
- In this cut, we explore A-H share trading dynamics, consider copper market dynamics and plays, and China’s bottoming/stabilizing real estate market
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
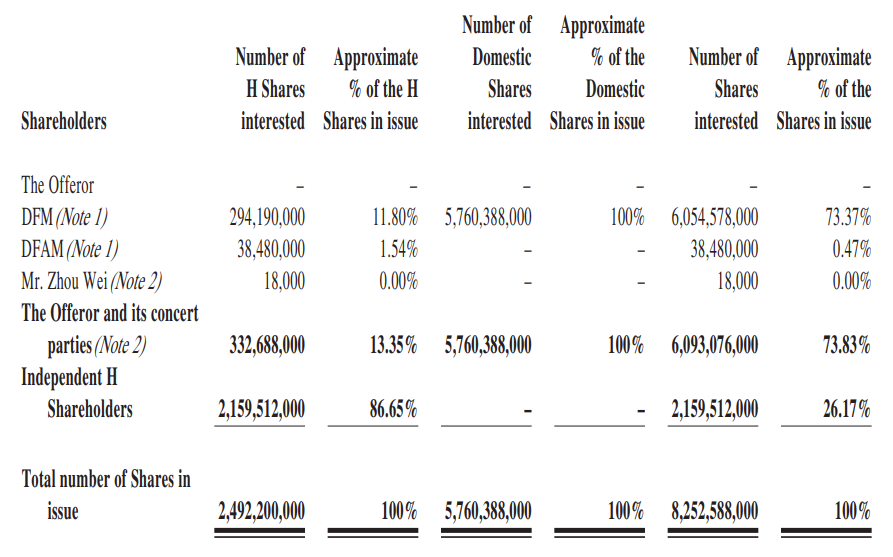
1. Dongfeng (489 HK)’s Privatisation And EV Backdoor Listing
- Dongfeng Motor (489 HK) has announced a privatisation; together with a concurrent listing of its EV arm.
- The same day as the dual proposals, Dongfeng announced an interim loss (1H25). Evidently, the way forward – from an investor standpoint – is electric, not internal combustion engines.
- The cash terms + scrip (into the EV listing) under the proposals are attractive. Even after this morning’s move (+53.6%) in Dongfeng’s share price.
2. Merger Arb Mondays (25 Aug) – Dongfeng, ENN Energy, Shibaura, Santos, Lynch, Smart Share
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Dongfeng Motor (489 HK), Mayne Pharma (MYX AU), Smart Share Global (EM US), ENN Energy (2688 HK), Santos Ltd (STO AU), Shibaura Electronics (6957 JP).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Humm Group (HUM AU), Ainsworth Game Technology (AGI AU), Ashimori Industry (3526 JP), PointsBet Holdings (PBH AU).
3. [Japan M&A] YAGEO Says It Expects FDI Clearance on Shibaura – Minebea Likely To Fold
- Last weekend then post-close Monday, Yageo Corporation (2327 TT) raised its TOB Price for Shibaura Electronics (6957 JP) to ¥7,130 – a full 15% through Minebea’s proposed ¥6,200/share terms.
- Minebea was playing chicken with the result, closing its tender on 28 August, before Japan’s Foreign Direct Investment approval (FEFTA approval) was cleared, expected 1 Sep or later.
- Today post-close, YAGEO announced it had concluded discussions with METI, would make all required regulatory submissions today, and expects to obtain approval “no later than 10 September”
4. PointsBet (PBH AU): Betr’s Dyslexic Bump. Mixi’s Now Holding 42.38%
- Betr Entertainment (BBT AU) has bumped scrip terms to 4.375 betr shares per PointsBet Holdings (PBH AU) share, equivalent to A$1.31/share, based on betr’s last traded price.
- True to form with betr, there’s a typo in its latest announcement stating a 4.735 ratio. betr just issued a Bidder’s Statement with the correct info.
- Apologies: in my last note I mentioned Mixi Inc (2121 JP) had bumped to A$1.30/share. However, that was predicated on Mixi securing 90%, which won’t happen if betr doesn’t tender.
5. A Merger Between HD Hyundai Heavy Industries and HD Hyundai Mipo
- It was announced today that HD Hyundai Heavy Industries will merge with HD Hyundai Mipo. The merger ratio between HD Hyundai Heavy Industries and HD Hyundai Mipo is 1:0.4059146.
- HD Korea Shipbuilding & Offshore Engineering (009540 KS) will own a 66.29% stake in the merged entity.
- HD KSOE is proceeding with this merger of its two major subsidiaries ahead of the full-scale launch of the MASGA (“Make America Shipbuilding Great Again”) project.
6. Near-Term Flows to Watch on Mandatory Treasury Share Cancellation in Korea
- Dems likely to push 3rd package in Q4; near-term flows chasing treasury stock cancellation theme, with locals screening >₩1tn mkt cap, >10% treasury shares of float.
- Little pushback on mandatory treasury cancellations; debate focused on timeline — grace period vs. immediate rollout — highlighting how much leeway government may grant differing governance structures.
- Too early for governance plays; near-term momentum flows likely in names with highest treasury stock relative to float, where cancellation is expected to hit flows hardest.
7. [Japan M&A] CareNet (2150 JP) – Opaque LBO/MBO Garners New Attention from Existing Shareholder
- When EQT launched its deal for Carenet Inc (2150 JP) two weeks ago, I thought it opaque, and light, and strangely lacking in information which should be there.
- It has not gotten clearer, though three days ago, the largest foreign shareholder as of the announcement reported they had lowered their position by 3.77% (4.22% of votes).
- Then yesterday, someone else reported they had gone above 5%. The data implied in that filing suggests this may have legs. I’d buy through terms.
8. ENN Energy (2688 HK): Chipping Away at the Precondition
- ENN Natural Gas (600803 CH) has made steady progress in satisfying the precondition for its ENN Energy (2688 HK) offer. On 22 August, NDRC approval was obtained.
- The appraised offer HK$80.00 value is the key debating point. Based on several methodologies, I estimate a realistic offer value of HK$74.44 (range of HK$67.84 to HK$83.64).
- The protest votes for director re-elections at the 23 May AGM are a risk. On balance, the scheme vote should pass as the offer is reasonable and strategically sensible.
9. HHI–Mipo Merger Swap: Deal Mechanics & Spread Play Opportunities
- HHI–Mipo merger spread looks minimal, but today’s MASGA-driven pop signals momentum flows—likely to mean-revert toward appraisal rights once the theme dissipates.
- Froth lifted prices past fundamentals—once it unwinds, HHI–Mipo could diverge from swap ratio, creating the spread window where traders can get paid.
- This isn’t classic merger arb—it’s about fading a policy-fueled pop, riding the snapback toward appraisal baseline, with flow-driven swings creating short-term tactical arb setups.
10. Shibaura Electronics (6957 JP): Method in the Madness as Yageo Bumps Twice in Two Days
- On 21 August, Yageo Corporation (2327 TT) increased its Shibaura Electronics (6957 JP) offer by 7.0% to JPY6,635. On 23 August, Yageo further increased its offer by 7.5% to JPY7,130.
- The offer is partially in reaction to Minebea’s recent comments around Yageo securing FEFTA approval. Crucially, Yageo finally provided an update suggesting that only a few issues remained.
- Yageo’s JPY7,130 offer is not over-the-top, as Minebea’s 10x EV/EBIT pricing guideline outlined on 18 August potentially justified a JPY7,300 offer. The likelihood of Minebea walking has increased.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. FEFTA Classification Changes Summer 2025
- The Ministry of Finance has published an updated “FEFTA List” of classifications of listed companies as of July 15, 2025.
- 50 names lowered their ranks from the most “core” Type 3 to Type 2(20), or Type 1(30). 104 names raised from Type 1(51) or Type 2(53) to Type 3.
- Smartkarma readers may want to peruse the lists and details to see if they think companies are trying to protect themselves (from threats as yet not known by the public).
2. Merger Arb Mondays (18 Aug) – Santos, Shibaura, ENN Energy, Kangji, OneConnect, Smart Share
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Smart Share Global (EM US), Mayne Pharma (MYX AU), ENN Energy (2688 HK), Santos Ltd (STO AU), Joy City Property (207 HK), Oneconnect Financial Technology (6638 HK).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Shibaura Electronics (6957 JP), Ci Medical (3540 JP), Soft99 Corp (4464 JP), Ainsworth Game Technology (AGI AU).
3. Smart Share Global (EM US): Hillhouse Crashes The Party. And Rightfully So
- Nearly seven months after receiving a preliminary non-binding proposal, Smart Share Global (EM US) announced on the 1st August a firm Offer had been entered into.
- The Offeror consortium, led by Mars Guangyuan Cai, Chairman and CEO, made an Offer of US$1.25/ADS, a 74.8% premium to last close; but ~20% below net cash + short-term investments.
- Now Hillhouse has thrown its hat into the ring with a US$1.77/ADS NBIO. Smart Share’s special committee of independent directors should engage.
4. Today’s HMM Tender Follow-Up Disclosure and Hedge Ratio Setup
- KOBC’s core mission hinges on HMM; without it, no real mandate. Structural incentive to hold remains, so its active tender participation is still questionable.
- Still, max proration risk seems base case, with weak Q2, soft Q3 freight outlook, and post-tender skew pointing bearish for HMM.
- Spread >10% makes this too good to pass, but should also watch policy risk — better to lock futures hedge early as flows show players scrambling for cover.
5. HMM Tender Side Play: Targeting a Basis Squeeze Ahead of Sep Expiry
- Most traders are starting in September, rolling into October. Sep/Oct spread volume has picked up unusually fast, clearly reflecting hedge demand linked to the tender
- As September expiry approaches, basis-squeeze risk rises, likely pushing September cheap and October expensive, widening the spread — creating a clear side trade opportunity.
- With a basis squeeze expected near September expiry, we could enter a Sep/Oct spread (short Sep, long Oct) and also watch for spot-futures decoupling to play the cash-futures spread.
6. Hanon Systems Announces a Major Potential Rights Offering
- On 14 August, Hanon Systems (018880 KS) announced a potential rights offering capital raise. The exact amount will be finalized at the EGM next month.
- The significant size of the rights offering is expected to burden its largest shareholder Hankook Tire & Technology (161390 KS) which owns a 54.8% stake in Hanon Systems.
- We believe the potential rights offering is likely to continue to negatively impact Hanon Systems by diluting its existing shareholders.
7. Krungthai Card (KTC TB): Still A Buy As Pledged Shares Further Decline
- Back in May this year, shares in Krungthai Card (KTC TB), XSpring (XPG TB), BEC World Public (BEC TB), and The Practical Solution (TPS TB) all went limit down. Twice.
- This situation was discussed in Krungthai Card (KTC TB): Buying Opportunity After Margin Call. Reportedly Mongkol Prakitchaiwattana had pledged his shares in all four companies, leading to margin calls.
- On the 16th August, the SET released an updated list of securities pledged, with pledged shares in KTC now at 2.3% of shares outstanding, down from 16.3% in May.
8. Curator’s Cut: Singapore Unlocks Value, India’s Jewellery Caution & Taiwan’s Top ETF’s Rebalance
- Welcome to Curator’s Cut, a fortnightly roundup of standout themes from the 1,200+ Insights published over the past two weeks on Smartkarma
- In this cut, we review value-unlocking moves by Singapore-listed companies, take stock of India’s jewellery retail market, and track how Taiwan’s largest ETF drives flows for its adds and deletes
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next
9. [Japan M&A] Minebea Forces a Game of Regulatory Chicken on Shibaura (6957 JP)
- Minebea Mitsumi (6479 JP) has bid ¥6,200/share for Shibaura Electronics (6957 JP). The tender ends 28 August. YAGEO has over bid now to ¥6,635/share.
- YAGEO’s regulatory clearance decision may not arrive before 1 September, after the Minebea tender closes. Minebea now says they will neither bump nor extend.
- Minebea is hoping people will throw in the towel and tender because if their tender ends and Yageo’s fails, it might a long way down. There are possibilities but… scary.
10. US Government May Acquire Equity Stakes in Samsung Electronics and TSMC
- According to Reuters, the US government may be interested in acquiring equity stakes in Samsung Electronics and TSMC in exchange for CHIPS and Science Act grants.
- The US government is exploring ways to take equity stakes in these two Asian tech giants that have been expanding their semiconductor facilities in the United States.
- If the US government decides to invest $10 billion each in Samsung Electronics and TSMC, they would represent about 3% and 1% of Samsung Electronics and TSMC’s market caps, respectively.