
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Sun Corp (6736) – CLBT Has Round-Tripped, But Now Better ParentCo and a Buyback so Set-Up Is Better
- 12 months on from the Tender Offer which changed the shape of the shareholder register, Sun Corp (6736 JP) is up small and its main asset Cellebrite is -10%.
- The value of the rest of Sun Corp has probably increased to cover that 10% through new business earnings, but the main value is still Cellebrite. An exit still awaited.
- Now Cellebrite is lower, and SunCorp is lower (but recently rising) and SunCorp has announced a buyback which accounts for a big chunk of Real World Float. Hmmm…
2. [Japan M&A] Taisei Corp To Take Toyo Construction (1890 JP) Private – Governance Torture Ends
- In March 2022, Infroneer bid ¥770. The Board said “too low” but then accepted. A month later, YFO offered ¥1,000. Too high, bad owner, not accepted.
- Summer 2023 after a year of palm to the face for YFO, the Board was partly spilled. YFO bid ¥1,255/share and the Board said the premium was too low.
- Now, the Board has accepted a bid from Taisei at a roughly similar premium. But the price is ¥1,750/share. Infroneer and YFO have agreed to sell. Minorities win… -ish
3. Kangji Medical (9997 HK): Consortium’s Light Preconditional Scheme Offer
- Hangzhou Kangji Medical Instrument Co., Ltd. (9997 HK) disclosed a preconditional privatisation from a consortium at HK$9.25, a 9.9% premium to last close and a 21.7% premium to the undisturbed price.
- The precondition relates to SAMR approval. The key condition will be approval by at least 75% disinterested shareholders (<10% of all disinterested shareholders’ rejection). The offer is final.
- The scheme vote risk is medium-to-high due to an unattractive offer, a blocking stake below the substantial disclosure threshold, unfavourable AGM voting patterns, and emerging retail opposition.
4. Identifying the SK Square Vs. Hynix Price Ratio Reversion Alpha Setup
- Hunting the reversion point for Square-Hynix price ratio amid local buzz: need clear pro-business tax signals and Hynix’s downtrend to continue despite today’s bounce.
- Tax tweak likely turns neutral despite gov’s cautious tone today. Hynix’s bounce faces headwinds from supply ramp and yield issues, so fresh rally odds remain slim.
- Focus on hunting SK Square vs. Hynix price ratio reversion, pairing it with Samsung Long/Hynix Short for a strong short-term trade setup to ride the trend.
5. [Japan M&A] Minebea Matches YAGEO for Shibaura Elec (6957) At ¥6,200. Presses on Early Cashout
- After three months of NOT matching YAGEO’s bid for Shibaura Electronics (6957 JP) at ¥6,w00 as YAGEO’s proposal continues its long plod through FEFTA review, Minebea-Mitsumi has now matched ¥6,200.
- Key is that their bid closes before the indicative deadline for YAGEO to receive word on FEFTA approval. They are hoping this bid mollifies the irrevocables and everyone else.
- But if YAGEO cares, it could bump to ¥6,300 tomorrow and extend its tender offer which closes on Monday. But the put option is now struck higher, which de-risks this.
6. Why We’re Eyeing KRX’s Sep 29 KCMC Event for Dividend Momentum Trades
- KCMC 2025 will likely reveal fresh, unpriced stimulus details, potentially sparking a price rally like last year’s 2% KOSPI 200 jump on the value-up ETF rollout.
- The key wildcard at KCMC 2025 is dividends—shifting from Yoon’s Japan-style ROE grind to a Taiwan-style push for bigger shareholder payouts.
- With Sept 29 approaching, dividend policy buzz may drive price moves—smart to prep dividend momentum trades to front-run this catalyst.
7. Current Samsung Biologics Split Dynamics with Alpha Potential Both Ways
- One of the hottest local plays is gauging KRX and FSS leanings on Biologics split, which could drive short-term alpha across the three Samsung names alongside battery and HBM flows.
- Short-Term focus is KRX pre-listing review and FSS registration window. Once approval and lock-up kick in, Biologics and Samsung Electronics could outperform Samsung C&T.
- From a risk-hedge angle, this is a long-short alpha setup: if the split fails, Samsung C&T likely takes the hit, offering alpha potential both ways.
8. Merger Arb Mondays (11 Aug) – Mayne, PointsBet, Infomedia, Ashimori, Toyo Const, HKBN, Joy City
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Ashimori Industry (3526 JP), ENN Energy (2688 HK), Ci Medical (3540 JP), Joy City Property (207 HK), Santos Ltd (STO AU).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), Ainsworth Game Technology (AGI AU), Welcia Holdings (3141 JP), ZEEKR (ZK US), Soft99 Corp (4464 JP).
9. [Japan M&A] Founder, KEPCO, Try ¥2,750 Bain-Led MBO on Rezil (176A). Light Given Growth – Bumpity?
- To my knowledge, this may be the first Tender Offer takeout proposal on a “new ticker.” Rezil (176A JP) was listed just 16mos ago.
- This takeout is done on a highish-growth stock at 11.7x 1yr forward EV/EBITDA. It’s not expensive, but they have ~60%. BUT… there’s another Potential Player who may have Big Thoughts.
- Slightly long-dated, small-cap, likely to be illiquid. Watch how it trades early for hints.
10. Value Unlock SG: Value Creation Via Corporate Action. May the Wind Carry Many More Sails
- A wave of corporate actions by SGX-listed companies has unlocked substantial shareholder value and re-rated select stocks in recent months. In this note, we spotlight five standout cases.
- Our top picks with the strongest catalysts for further upside after delivering significant shareholder returns over the past year are – Keppel Corp (KEP SP) and Yangzijiang Financial (YZJFH SP).
- The outsized value creation delivered by these companies should serve as a wake-up call for other managements to follow suit and initiate actions to boost returns and unlock shareholder value.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
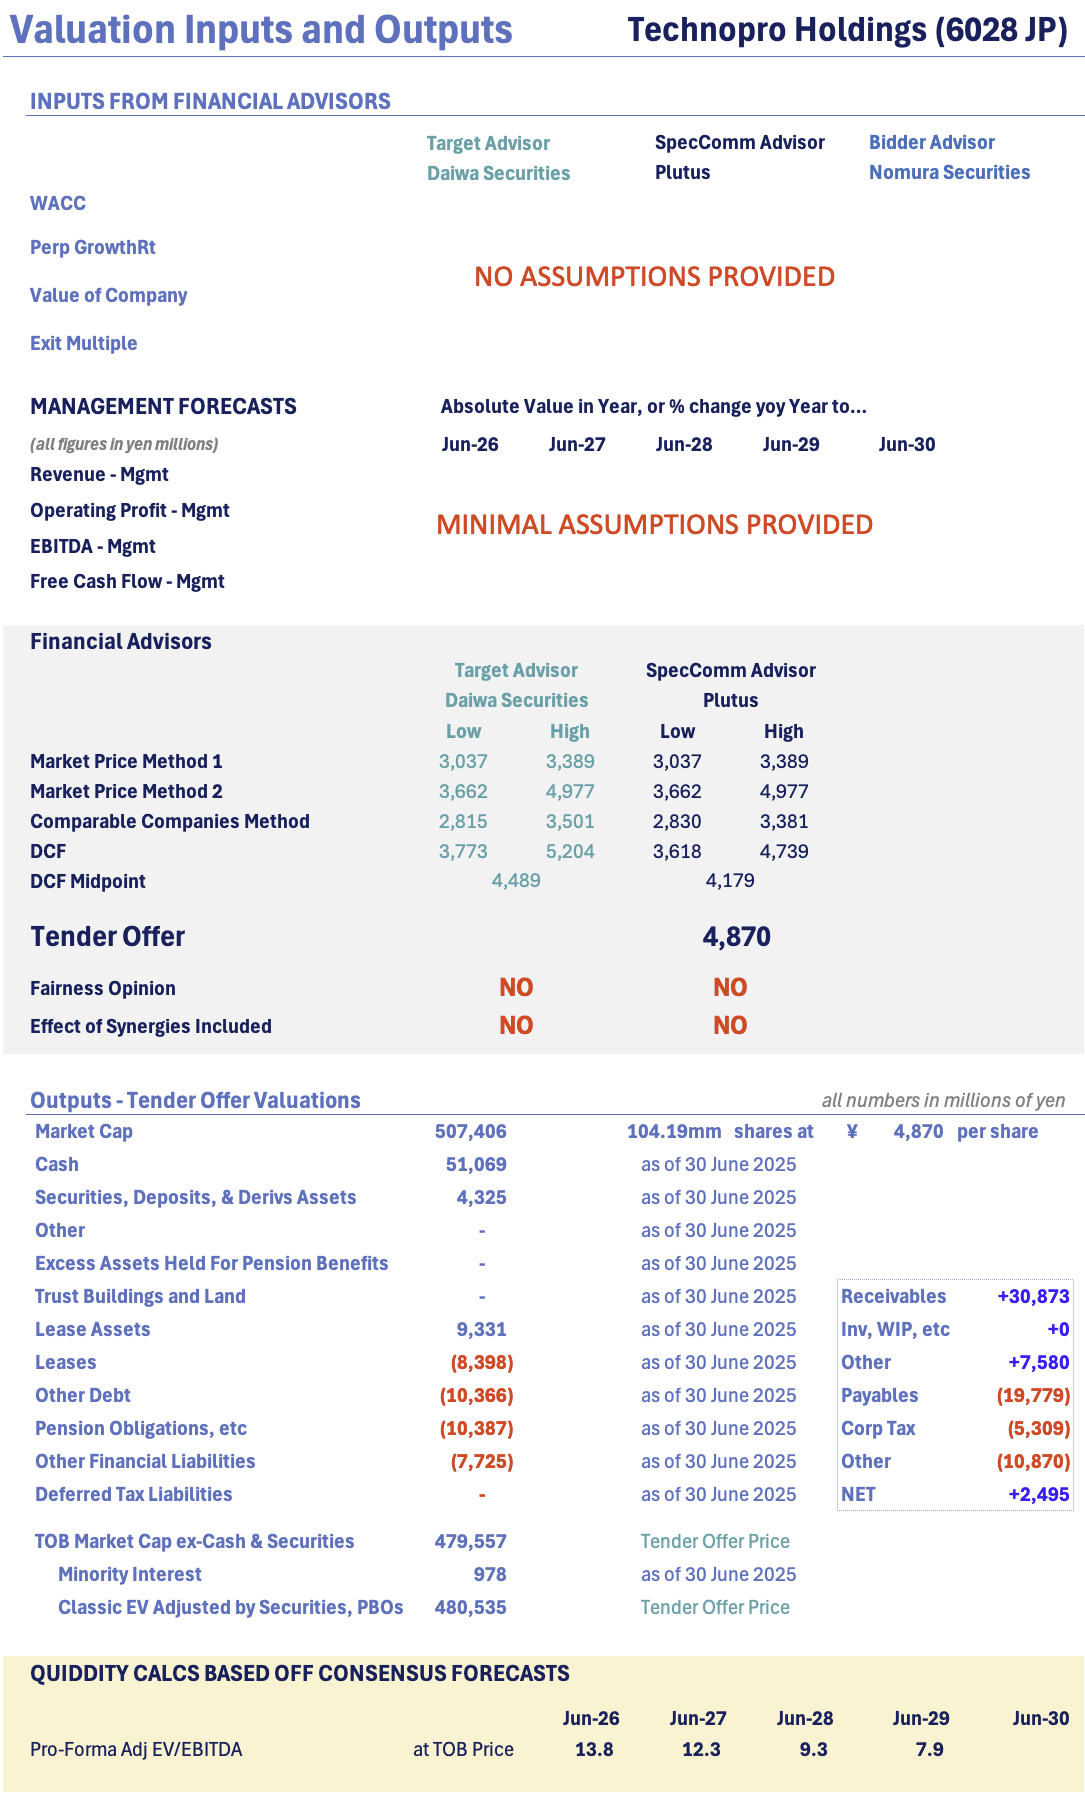
1. [Japan M&A] ¥4,870/Sh Blackstone TOB for Technopro (6028 JP) – Watch the Parameters and Modalities
- This was signaled in May, somewhat confirmed in July, now done. Blackstone buys Technopro at ¥4,870/share which is ~14x EV/EBITDA for next year.
- PE Firms have been scouring the Japanese market to buy companies. The METI Corporate Takeover Guidelines are super-helpful in that regard. This will squeeze the market over time.
- This takeover price is not quite as full as it could have been, and there are some parameters and modalities to this which are worth looking at. Parameters and Modalities.
2. [Japan M&A] Fujitec (6406) PE Bid Not Super High But May Be Tough To Beat
- On 30 July, Fujitec Co Ltd (6406 JP) and Swedish PE Firm EQT announced a deal to acquire the company with the Uchiyama family. Two activists signed tender agreements.
- The deal is not expensive IF you underwrite strong profitability growth and assume the large net receivables position can be better addressed.
- But the stock is trading tight to terms and there are 6+ months until you get your money.
3. [Japan M&A] 99Soft MBO at 52% Premium Is Too Light But A Bump May Be Tough
- Soft99 Corp (4464 JP) is the owner/operator of a set of ubiquitous brands in aftermarket autocare. Anything to do with washing, cleaning, etc.
- The company was founded 70 years ago, and the CEO is 54yrs old. Smells like succession planning.
- This deal is a nice premium, but it is too light. The operating assets with consistent growth and 20% OPMs are being sold at <0.9x book. That’s bad.
4. Merger Arb Mondays (04 Aug) – Santos, Joy City, HKBN, Krosaki Harima, Fujitec, Smart Share
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), ENN Energy (2688 HK), Krosaki Harima (5352 JP), Joy City Property (207 HK), Santos Ltd (STO AU), Smart Share Global (EM US).
- Lowest spreads: Bright Smart Securities (1428 HK), Pacific Industrial (7250 JP), ZEEKR (ZK US), New World Resources (NWC AU), Ainsworth Game Technology (AGI AU), Nippon Concept (9386 JP).
5. [Japan M&A] Furukawa Battery (6937 JP) Take Private – Ugly Then, Ugly Still, But Now It’s On…
- 54 weeks ago Advantage Partners and Furukawa Electric announced a deal to take Furukawa Electric (5801 JP) sub Furukawa Battery (6937 JP) private. The acquisition price was LOW.
- Minorities got more – more than book. But the deal included a payment delay allowing BVPS to rise 8.8% from the announcement date. No synergies.
- Furukawa Electric gets to buy back in at a price below book. And because there are cash and securities and lots of net receivables, the operating assets are well below.
6. [Japan M&A] Krosaki Harima (5352) Takeout by Parent Nippon Steel – Cheapish But Done
- On Friday 1 August, Nippon Steel Corporation (5401 JP) and subsidiary Krosaki Harima (5352 JP) announced the parent would buy out the sub at ¥4,200/share.
- This seems light given the structure of the balance sheet (lots of net receivables – a bunch against the buyer) but it would be awfully tough to see this broken.
- As it is a long-dated deal, I expect it trades too tight early on, then may flatten or fade.
7. [Japan M&A] Nikkei Says Blackstone to Buy TechnoPro Holdings (6028) For “Roughly ¥500bn”
- There was an article in mid-May saying Technopro Holdings (6028 JP) might be privatised. It is an appropriate candidate. The stock popped 20% immediately, and has since risen another 20%.
- Today’s article follows one which came out ~2 weeks ago with non-sourced editorial content suggesting the price might be 20x EBITDA (i.e. a lot higher).
- Today, an article says Blackstone will buy the firm for “Roughly ¥500bn” which would be 3% down from yesterday. Beware the Nikkei. Beware expectations.
8. A Hidden Trading Angle from Dividend Tax Reform: Tax Timing Creates Dividend Trap Risks
- With new tax rules kicking in from FY2026, firms may hold back FY2025 dividends to front-load later, creating potential downside surprise purely from tax-driven deferral, not fundamentals.
- If FY2025 payouts fall short, dividend names could go ex-div on inflated expectations, then trade heavy — setting up mispricing risk around year-end dividend capture trades.
- This may weaken post-ex-div price rebounds, creating dividend trap risks and short-term mispricing that traders can exploit via shorts, dip buys, or dividend swap long-short strategies.
9. A/H Premium Tracker (To 1 Aug 2025): HUGE SOUTHBOUND Buying Helps Beautiful Skew but Premia Up
- AH premia up, erasing the previous week’s gains for Hs. “Beautiful Skew” continues in negative overall performance.
- Last week I said “This is the most significant 60-day AH pair average H outperformance in five years, maybe ever. Remarkable.” This week it unwound some.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers.
10. Korea’s Next Policy Momentum Play: Rapid Unfolding of the National Growth Fund
- From a trading view, no confirmed new ETFs under the National Growth Fund yet; market expects existing ETFs to be the main liquidity and sector play tools instead.
- Out of the KRW 150tn, ETF flows likely come from the 100tn private pool—conservative case: ~3% (KRW 4.5tn), base case: 5–7%, aggressive: up to 10% (KRW 15tn).
- Even conservatively, about KRW 3 trillion could flow into sector ETFs, a signficant AUM boost, mainly concentrated in AI, defense, aerospace, and biotech—driving notable inflow impact.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
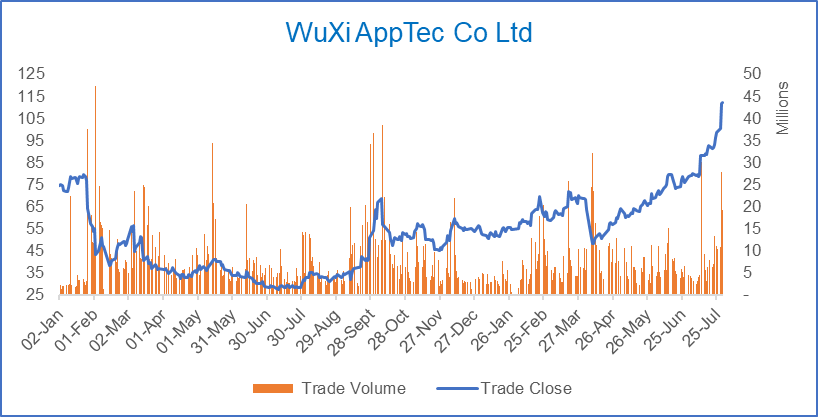
1. WuXi AppTec (2359 HK) Placement: Strong Momentum & Index Flows
- WuXi AppTec (2359 HK) is looking to raise US$650m at a price range of HK$104.16-106.4/share, a 5-7% discount from last close.
- There will be passive buying from global index trackers around the time of settlement of the placement shares. Then there will be some Hang Seng Index buying in August.
- Short interest in WuXi AppTec (2359 HK) has spiked and some shorts could cover into the placement. The AH premium could move higher following the placement.
2. GMO Internet (4784) – GMO Internet Parent Has Been SELLING In The Market
- I have harped on the fact that GMO Internet Group (9449 JP) has to sell GMO Internet (4784 JP) shares with the goal to get 35% tradable shares by end-2025.
- I have written about it here, here, here, and here. The price needs to be lower so the parent can launch a HUGE block. The stock must be less squeeze-able.
- It turns out the parent started selling in the market the day after the Offering was cancelled. The setup is delicious now.
3. NSDL (NSDL IN) IPO: Offering Details & Index Inclusion Timeline
- NSDL (NSDL IN) is looking to list on the exchanges by selling up to INR 40bn (US$464m) of stock at a valuation of up to INR 160bn (US$1.85bn).
- The stock will not get Fast Entry to either of the global indices. The earliest inclusion in a global index should take place in November.
- Central Depository Services (CDSL IN)‘s stock price has dropped following the announcement of NSDL‘s IPO price band and the muted results could lead to further downside in the stock.
4. Korean Policy Tailwinds: Preferred Shares Rerating Play
- Most expect prefs to be in policy crosshairs soon—watch for tighter rules on dividends, discounts, and liquidity, plus likely incentives for redemption or cancellation ahead of commons.
- If Korea rolls out a pref stock overhaul, long-biased rerate plays could pop—focus on liquid, high-yield large-cap prefs trading at 35%+, yield north of 3%, and solid daily turnover.
- Korea Inv, Kumho Petro, CJ Cheil, CJ Corp prefs already screen well; Doosan and Hanwha 3PB could join if dividend hikes materialize on back of strong sub earnings.
5. [Japan Activism/M&A] Hogy Medical (3593) Reportedly Up For Auction – Totally Unsurprising
- Hogy Medical (3593 JP)‘s founder passed and there was a re-arranging of Hoki family deckchairs in 2021. In 2022 there was a BIG buyback from the family at ¥3,130/share.
- I discussed it here. I suggested that meant accretion, a family willing to sell, and an open register for a cheap company always heavily owned by value investors.
- The stock went nowhere for 18mos as activists dallied. In 2024 it ran from ¥3,500 to ¥5,000 as Dalton bought 20%. Then they got a board seat. Now takeover noise.
6. A/H Premium Tracker (To 25 July 2025): “Beautiful Skew” Raging Onward
- AH premia down again among liquid names but “beautiful skew” of wide premia converging more than narrow premia continues bigly. It still pays well to be long wide H discounts.
- This is the most significant 60-day AH pair average H outperformance in five years, maybe ever. Remarkable.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers.
7. Merger Arb Mondays (28 Jul) – Shibaura, Abacus Storage, Insignia, Mayne, Santos, ENN, Smart Share
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Yichang HEC Changjiang Pharma (1558 HK), ENN Energy (2688 HK), Pacific Industrial (7250 JP), Santos Ltd (STO AU), Smart Share Global (EM US).
- Lowest spreads: Bright Smart Securities (1428 HK), Hainan Meilan International Airport (357 HK), Humm Group (HUM AU), New World Resources (NWC AU), Nippon Concept (9386 JP).
8. ADR Arb on Korean Divvy Names: A Side Play Riding the Policy-Driven Liquidity Wave
- ETF rebalancing’s key, but still too early to front-run — both use FnGuide screens based on FY1 DPS and prices from 20 days before November-end.
- Beyond the rebalance noise, ADR-local spreads have been widening — KB hit +6%, Shinhan’s also drifting. Likely tied to the recent liquidity surge in dividend names.
- ADR arb’s more doable with NXT tightening slippage. With proper FX hedging, it’s a clean side play riding the policy-driven liquidity wave.
9. [Japan M&A] Pacific Industrial (7250) MBO Officially Being Done Dirt Cheap
- The MBO for Pacific Industrial (7250 JP) starts with the father+son Chairman and CEO, – combined stake 2.92% – putting nothing in to buy this, with help from banks.
- The Takeover Price is priced at 0.7x book, and a Net Debt to EBITDA of 2x (when adjusted for securities+pension assets+DTLs) and 5-6x average 2026-2030 FCF.
- This is being done too cheap: Toyota is the main customer, one third of revenues comes from Japan, and the company is set for a transition to EVs.
10. [Japan M&A] – KKR Launches Still-Too-Light Topcon (7732) Deal
- In December-2024, this deal was mooted and it came out as expected. But the implied growth in management forecasts was higher than expected so the price came in quite light.
- In March when the deal was announced, it seemed like a tough call, but three weeks later Value Act decided they would tender, but would reinvest in the back end.
- The deal is now approved, and launches tomorrow. It gets done, I expect, but it is not a model deal other than being one showing the loopholes available to buyers.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. The Final ACT Comedy of Errors Opens the Way for Real Value to Emerge at Seven & I
- ACT’s bid for Seven & I has been withdrawn and Seven will be better off long-term because of it – although we detail here how competitors are catching up fast.
- Once York HD has been split off, the company can at last focus on its crucial local CVS operation: Japan makes up 25% of revenues but almost 50% of profits.
- The potential is real and we are bullish on the long-term value but we would have been more bullish if the former CEO Ryuichi Isaka was still on board.
2. SK Hynix Single-Stock ETF Scheduled for 3Q: Watch for a Repeat of the Samsung ETF Playbook
- When the SK Hynix ETF drops, expect meaningful physical buying shaking up supply-demand. Arb desks and alpha shops could pile in early, pushing the stock higher on flow.
- Going long Hynix near listing could pay off if demand mirrors Samsung’s—ETF flows, NAV arb, and delta hedging drove a 4% jump with a noticeable increase in program buying.
- Get in around the listing, watch flows, and take profits quickly. This is a short 2–3 day tactical play, with sharper front-running expected based on the Samsung ETF template.
3. TSI Holdings (3608) – YET ANOTHER Big Buyback, Still Good, Still Cheap, But B/S Restructuring Slow
- A bit over three years ago I re-wrote on Tsi Holdings (3608 JP). Then? EV/Revenue and EV/EBITDA of 0.03x and 0.5x respectively. I pounded the table.
- My recommended trade: “Buy the stock (preferably from cross-holders interested in selling). Buy with both hands. Buy a lot. Buy more later. Pressure the company to go private.”
- Since then, total return has been +295%. Today they announced another buyback. Tomorrow morning it gets done. Details details details!
4. Anthem Biosciences IPO: Lists Today; Index Inclusion Timing
- Anthem Biosciences raised INR 34bn (US$394m) in its IPO valuing the company at INR 320bn (US$3.7bn). The stock lists today.
- The grey market premium is INR 132/share, so the stock could list 23.2% higher than the IPO price. That will help in getting larger index flows.
- Anthem Biosciences could be added to one global index in November while the stock price gain will determine whether the stock is added to the other global index in December.
5. A/H Premium Tracker (To 18 July 2025): “Beautiful Skew” Continues Some More
- AH premia flat again among liquid names but “beautiful skew” of wide premia converging more than narrow premia continues bigly. It still pays well to be long wide H discounts.
- Weeks ago I said, “It has paid to be long the H on those H/A pairs with the biggest H discounts. I would continue to ride that trend.” Ride on.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers.
6. Prosus Is Elevated Vs. Tencent As The Accretion Trade Unfolds
- Since unwinding the Naspers (NPN SJ)/Prosus (PRX NA) circularity, Prosus has been selling Tencent shares, and buying back its share. Separately, Tencent is buying its shares to offset Prosus’ selling.
- Prosus’ stake in Tencent has now edged below 23%, a little over seven months since dipping below 24%.
- On an implied stub and relative value, Prosus is elevated to Tencent, suggesting an unwinding of the stub.
7. Dickson Concept (113 HK): More Minority Teeth Bared As Another Scheme Fails
- Three for three. Three low-balled Hong Kong Offers, by way of Schemes, have now lapsed over the past ten weeks.
- Both Goldlion Holdings (533 HK) and Soundwill Holdings (878 HK) spectacularly failed back in May.
- Now Dickson Concepts Intl (113 HK) has followed suit. But the vote was (much) closer than it should have been.
8. Insignia Financial (IFL AU) Accepts CC Capital’s Reduced Terms
- Insignia Financial (IFL AU), a wealth manager and previously known as IOOF, has entered into a Scheme with CC Capital at $A$4.80/share.
- That’s 56.9% premium to undisturbed (11th December 2024), 20% above Bain’s initial indicative tilt last year, but 4% below CC Capital (% Bain’s) A$5.00/share indictive Offer on the 7th March.
- Apart from the Scheme vote, CC Capital’s Offer requires a raft a regulatory approvals. The SID indicates 1H26 completion.
9. StubWorld: Japan Post Holdings (6178 JP) Is “Cheap”
- As short-term rates rise, Japan Post Bank (7182 JP)‘s perceived superior fundamentals may be leading to a short squeeze on the stock versus Japan Post Holdings (6178 JP).
- Preceding my comments on Japan Post – and Silicon Integrated Systems (2363 TT) – are the current setup/unwind tables for Asia-Pacific Holdcos.
- These relationships trade with a minimum liquidity of US$1mn, and a % market capitalisation >20%.
10. Two New Tax Tweaks Set to Shake Up Korea’s Local Stock Market: Trading Tax & CGT Threshold
- Trading tax gradually dropped from 0.25% in 2020 to 0.15% in 2025, boosting volatility and short-term trades; a hike to 0.25% could cool momentum but widen arbitrage and basis spreads.
- If the major shareholder tax threshold drops to ₩1B, year-end retail dumps and Jan buybacks will return—but with less wild swings and more measured short-term fade and momentum trades.
- If the tax revamp drops end-July, expect a September Assembly push. Usually effective next January, but like 2023’s cap gains hike, changes might apply immediately in 2025.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
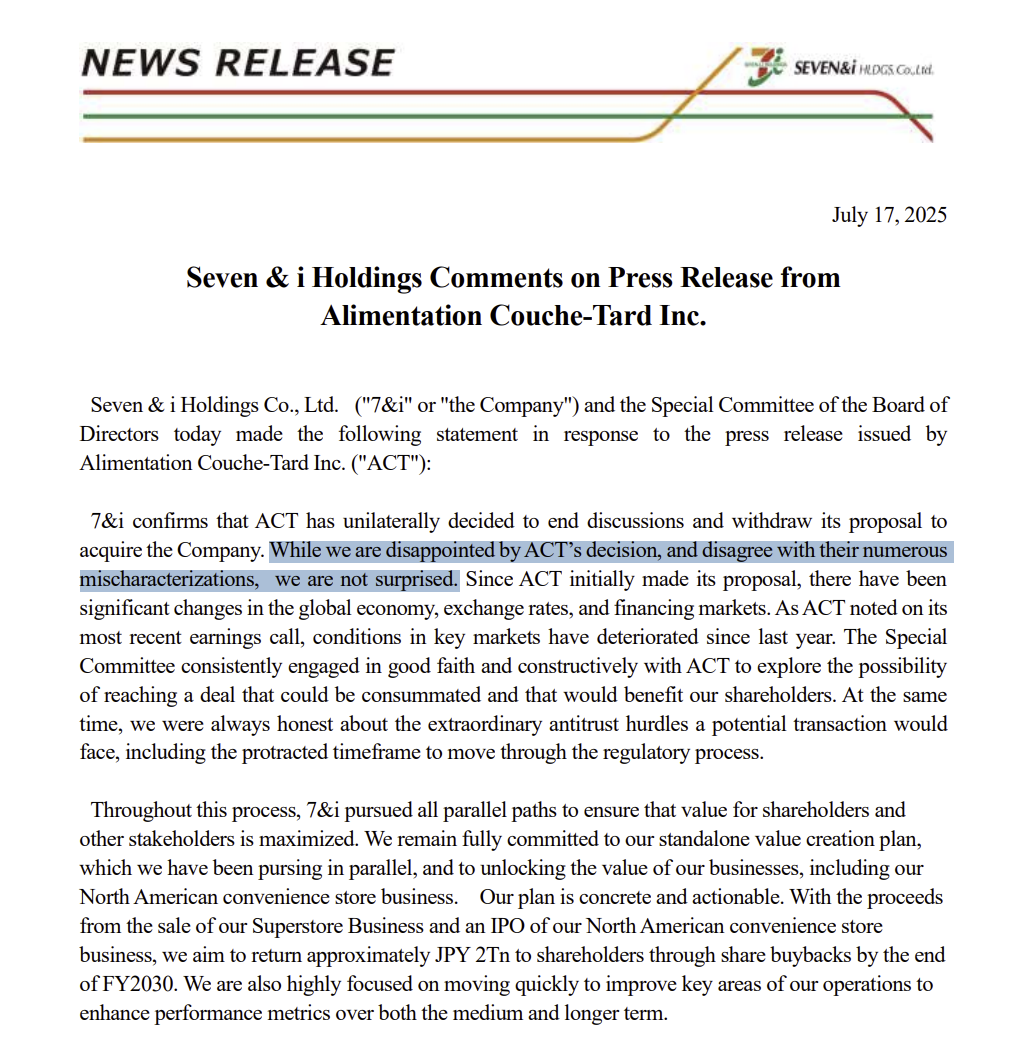
1. 7&I (3382 JP) – Alimentation Couche-Tard Walks, Lobbing a Letter Bomb
- Alimentation Couche-Tard (ATD CN) which proposed a takeover to Seven & I Holdings (3382 JP) almost a year ago, has walked. They delivered a letter bomb on the way out.
- The letter is titled “ALIMENTATION COUCHE-TARD ANNOUNCES WITHDRAWAL OF PROPOSAL TO ACQUIRE SEVEN & I HOLDINGS DUE TO LACK OF ENGAGEMENT.” This is not the first time they have complained.
- The letter is not aimed at the 7&i Board or at ATD stakeholders. It is meant to drive a wedge between 7&i active shareholders and its management team. We’ll see.
2. [Japan Activism] Mitsui Matsushima (1518 JP) Buyback Tender – Surprising Results and Implications
- Today, Mitsui Matsushima (1518 JP) announced the results of its Buyback Tender Offer to repurchase up to 3,999,999 shares (35.8% of shares out ex-Treasury) at ¥5,000/share.
- Murakami-San owned 42% of the voting rights at announcement, then bought more on the dip just below ¥5,000/share.
- The Tender Offer Buyback was “successful” in that it bought back 3.3mm shares. But the result was FAR more interesting than I expected. Surprising Results with Surprising Implications
3. GMO Internet (4784) – Shares Appear Manipulated/Squeezed (Again), but ParentCo MUST SELL
- GMO Internet (4784 JP) was squeezed after a merger which was a Reverse Takeover followed by a ridiculous TOPIX inclusion. Then the parent tried an offering, which failed.
- The clearing price demanded was WAAAY lower so the offering was pulled. Shares fell 70%, then bounced 65%. Now 48x book and 66x EBITDA for an ISP. Super expensive. Manipulated.
- ParentCo needs to sell 90mm shares ASAP. The only clean way is through a liquidation trust to get shares lower before a larger offering.
4. Mandatory Cancellation of Existing Treasury Shares: A Historic Stock Market Event in the Making
- The bill’s side notes clearly state that the mandatory cancellation rule applies retroactively to existing treasury shares without any exemptions.
- If this passes the Assembly as-is, it’ll trigger a historic forced cancellation of treasury stock across ~1,660 companies—about three-quarters of the K-equities market.
- Watch if this punchy bill clears committee and floor without cuts. Dems plan to fast-track it Sept 1, holding the majority to push it solo, aiming for year-end rollout.
5. Merger Arb Mondays (14 Jul) – Shibaura, Topcon, Nissin, OneConnect, Insignia, PointsBet, ENN Energy
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Yichang HEC Changjiang Pharma (1558 HK), ENN Energy (2688 HK), Insignia Financial (IFL AU), Seven & I Holdings (3382 JP), Santos Ltd (STO AU).
- Lowest spreads: Bright Smart Securities (1428 HK), New World Resources (NWC AU), Humm Group (HUM AU), Hainan Meilan International Airport (357 HK), Avjennings Ltd (AVJ AU).
6. [Japan M&A] Polaris MBO for DD Group (3073) – Too Light But Probably a Done Deal
- Diamond Dining (3073 JP) (DD Group) head Matsumura-san appears to be getting out in this Polaris MBO for the dining group.
- The premium is low, and the the price is probably light, but there are a couple of small things which mean it isn’t quite as light as it might look.
- But the company prints cash, so yeah, it’s light. This should probably be a bit better, but F&B is a fickle business.
7. A/H Premium Tracker (To 11 July 2025): “Beautiful Skew” Continues – BIG AH Premia Compression
- AH premia flat among liquid names but “beautiful skew” of wide premia converging more than narrow premia continues bigly. It has paid well to be long wide H discounts.
- Weeks ago I said, “It has paid to be long the H on those H/A pairs with the biggest H discounts. I would continue to ride that trend.” Ride on.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers.
8. ZEEKR (ZK US): Geely Auto’s Binding Offer a Done Deal
- ZEEKR (ZK US) has entered into a definitive merger agreement with Geely Auto (175 HK) at US$26.87 per ADS or 12.3 newly issued Geely shares. The cash offer increased by 4.7%.
- The proposal is conditional on regulatory approvals (low risk, as Zeekr is a subsidiary of Geely), as well as approval from Zeekr’s shareholders and Geely’s independent shareholders.
- The Zeekr shareholder vote is a formality as Geely and undertakings exceed the two-thirds voting threshold. The Geely vote is low risk due to the low takeover premium.
9. Krungthai Card (KTC TB): Buy With Both Hands As Pledged Shares Rollover
- Late last month, shares in Krungthai Card (KTC TB), XSpring Capital (XPG TB), BEC World Public (BEC TB), and The Practical Solution (TPS TB) all went limit down. Twice.
- As discussed in Krungthai Card (KTC TB): Buying Opportunity After Margin Call, Mongkol Prakitchaiwattana had pledged his shares in all four companies, reportedly leading to margin calls.
- Yesterday, the SET released an updated list of securities pledged in margin accounts. Notably, pledged shares in KTC has fallen to 3.5% of shares outstanding from 16.3% the previous month.
10. Seven & I Holdings (3382 JP): Dead Money as Couche-Tard Unsurprisingly Walks
- Couche-Tard has withdrawn its offer for Seven & I Holdings (3382 JP) by unfairly laying the entire blame on the Board.
- The Board has made credible progress, but the jury is still out on whether the Board’s plan will generate returns. Shareholders remain sceptical as the shares have underperformed the index.
- In theory, the sell-off presents a buying opportunity (My SoTP valuation is JPY 2,376). However, the shares are likely to tread water as there are no near-term catalysts.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. NTT DC REIT IPO: Global Index Inclusions Later This Year + A Kicker
- NTT DC REIT (NTTDCR SP) could raise up to US$824m in its IPO if the overallotment option is exercised and the stock is expected to start trading on 14 July.
- Cornerstone investors will own 16.8% of shares out following the IPO but there is no lock-up on these shares. The sponsor will own 20%/25% depending on whether overallotment is exercised.
- NTT DC REIT (NTTDCR SP) should be added to the smallcap segment of global indices in November and December while inclusion in local indices will take a lot longer.
2. Kokusai Electric (6525 JP): Small Index Impact for Now, but Could Lead to Something Bigger
- KKR HKE Investment is offering 30m shares (12.86% of shares out) of Kokusai Electric (6525 JP) in a secondary offering that could raise up to JPY 91bn (US$620m).
- Applied Materials (AMAT US) will become the largest shareholder in Kokusai Electric (6525 JP) after the placement.
- There will not be a lot of buying from passive trackers following the placement, but it could ease the way for inclusion of the stock in the Nikkei 225 Index.
3. [Japan Buybacks] – Japan Bank Metrics, Cross-Holdings and Banks Part 1
- Japanese banks have been in a relative sweetspot for a couple of years. Higher rates, higher inflation, more FX volatility, better earnings, stronger buybacks. Cross-holding sales up but not spectacular.
- The BOJ may raise rates but Trump Tariff retaliation/mitigation is a question. Elections the next two weeks and earnings the 2-3 weeks after that may keep things a question.
- But buybacks should pick up. Lots announced in spring end at or before Q1 earnings. And I expect substantial new buybacks to be announced throughout the from Q1 results on.
4. Toyota Industries (6201 JP): Vocal Activism Gathering Pace
- Toyota Industries (6201 JP)’s preconditional tender offer from Toyota Fudosan is susceptible to a bump if there is enough vocal opposition from minorities.
- In July, two public pieces have sharply criticised the offer – the Asian Corporate Governance Association (ACGA) on 2 July and Sloane Robinson Investment Management on 8 July.
- Some of the criticism has merit, while others do not. Nevertheless, these letters are the first and right step to agitate for terms that are closer to TICO’s intrinsic value.
5. Great Eastern (GE SP): SGX The Winner As Shareholders Block Exit Offer
- After OCBC bumped terms for Great Eastern Holdings (GE SP) to $30.15/share via an Exit Offer, I wasn’t confident a 17.8% bump would dislodge Palliser. That appears the case.
- At today’s EGM, 63.49% of minority shareholders – OCBC abstained – were in favour on the Offer, falling short of the 75% condition. There was no blocking % condition.
- Shareholders voted for the resumption of shares via the issuance of shares (one-for-one bonus), satisfying the SGX free float requirement. The SGX, and dissenters, will be happy with the outcome.
6. Merger Arb Mondays (07 Jul) – Seven & I, Shibaura, Insignia, New World, ENN Energy, HKBN, Fengxiang
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads:Mayne Pharma (MYX AU), Yichang HEC Changjiang Pharma (1558 HK), Insignia Financial (IFL AU), ENN Energy (2688 HK), Seven & I Holdings (3382 JP), Santos Ltd (STO AU).
- Lowest spreads: Bright Smart Securities And (1428 HK), Hainan Meilan International Airport (357 HK), New World Resources (NWC AU), Humm Group (HUM AU), Avjennings Ltd (AVJ AU).
7. [Japan LolWut?] Ikuyo (7273) Says “Iku Yo!” – Bitcoin, M&A, Weirdness, More
- Several Japanese companies jumped onto the OBaaBM/TABaaBM (Own/Talk-About-Bitcoin-as-a-Business Model) last fall to this spring as Microstrategy Inc Cl A (MSTR US) shares went up and bitcoin did too.
- Yesterday, resin coating/injection molding product maker Ikuyo Co Ltd (7273 JP) announced an M&A Policy, and a Shareholder Benefits Program where shareholders will “win” amounts of bitcoin by lottery.
- Ikuyo expects revenues +955% this year. Details are sparse. The shareholder structure has red flags. The CEO sold himself half the company in Feb for peanuts. Forewarned. But it’s interesting.
8. Korea’s Next Policy Trade: Locals’ Screens for Dividend Tax Reform Plays
- With the governance trade fading, local desks are rotating into dividend tax reform—bipartisan tailwinds and rising political chatter are driving early positioning ahead of potential rerating.
- Local desks are screening for names with 35%+ payout and 30%+ individual ownership, key thresholds tied to the ruling party’s dividend tax reform bill gaining traction in policy circles.
- The real trade is in names with individual top holders—direct beneficiaries of the tax reform—most exposed to theme flows and likely to lead on dividend hikes if the bill passes.
9. Meituan Possible US$4bn Selldown – Will End up Being Well-Flagged but Sentiment Isn’t Great
- As per news reports, Prosus NV (PRX NA) could look to sell some/all of its Meituan (3690 HK) stake, worth around US$4bn
- Prosus has held its stake for a few years, owing to the dividend payout by Tencent, but Meituan appears to be planning to take on one of its subsidiaries.
- In this note, we will talk about the possible selldown and other deal dynamics.
10. A/H Premium Tracker (To 4 July 2025): “Beautiful Skew” Continues as SB Buys Wide Spread Hs
- AH premia flat among liquid names but “beautiful skew” of wide premia converging more than narrow premia continues bigly. It has paid well to be long wide H discounts.
- Last week I said, “It has paid to be long the H on those H/A pairs with the biggest H discounts. I would continue to ride that trend.” Ride on.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers. Technical issue delayed this week’s Monitor.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taishin (2887 TT)/Shin Kong (2888 TT) Merger: Index Flows in July
- Taishin Financial Holding (2887 TT) and Shin Kong Financial Holding (2888 TT) announced a Merger of Equals in August 2024 and completion is expected on 24 July.
- Taishin Financial Holding (2887 TT) has underperformed its peers over the last 18 months while Shin Kong Financial Holding (2888 TT) has underperformed its peers following the merger announcement.
- There will be passive flows in the merged entity following the completion of the merger and could help reverse some of Taishin Financial Holding (2887 TT)‘s underperformance.
2. Lens Technology (6613 HK): Offering Details & Index Inclusion
- Lens Technology (6613 HK)‘s global offering opened yesterday, and the raise could reach up to US$800m if the offer-size adjustment option and the overallotment option are exercised.
- The allocation to cornerstone investors is smaller than in other recent AH listings. The discount of over 25% to the A-shares is attractive given the recent trend for large listings.
- Lens Technology (6613 HK) could be added to a global index in December. Inclusion in Southbound Stock Connect in August and HSCI inclusion could take place in March 2026.
3. [Japan M&A] Bain Plays Announcement Games with Nissin (9066) MBO TOB – Noise A Possibility
- On 12 May 2025, Bain Capital announced a deal to buy Nissin Corp (9066 JP). The tender was VERY light in price (Bain’s borrowing more than adjusted EV at TOB Price)
- And it was very long at 41 days. As of Day 1, they announced a long list of “irrevocables” – 16 holders with 5.75% – who had agreed to tender.
- Since then Bain have made 7 separate amendment filings detailing additional irrevocables and one possible additional tender agreement to get to 11.30%. Now it’s extended.
4. A/H Premium Tracker (To 27 June 2025): “Beautiful Skew” Continues as SB Buys, AH Premia Fall Back
- AH premia gives back previous week gains but the “beautiful skew” of wide premia converging more than narrow premia continues. It has paid to be long wide H discounts.
- It has paid to be long the H on those H/A pairs with the biggest H discounts. I would continue to ride that trend.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers. Technical issue delayed this week’s Monitor.
5. [Japan M&A] YAGEO Extends Shibaura TOB Limbo at FSA/METI/BOJ Request on FEFTA
- YAGEO’s deal for Shibaura Electronics (6957 JP) had been extended a couple of times – once for Shibaura’s yuho, and once for Taiwan Investment Commission Approval.
- YAGEO had re-filed its notification for FEFTA on 2 June, and the “normal” 30 day waiting period expired 1 July. YAGEO extended by 4 business days to 15 July.
- The TRS amendment was less informative than the TDNET release today. That’s worth reading. More waiting ahead. But the timing may be politically strategic.
6. Nippon Concept (9386 JP): J-STAR-Sponsored MBO a Done Deal
- Nippon Concept (9386 JP) has recommended a J-STAR-sponsored MBO at JPY3,060, a 37.2% premium to the last close price.
- The offer is attractive as it represents an all-time high and is above the midpoint of the IFA DCF valuation range.
- An attractive offer and irrevocables pave the way for deal completion. The tender runs from July 1 to August 13, with payment due on August 20.
7. Merger Arb Mondays (30 June) – Toyota Industries, Santos, Pointsbet, Dickson, HKBN, OneConnect
- I summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Insignia Financial (IFL AU), ENN Energy (2688 HK), Santos Ltd (STO AU), Seven & I Holdings (3382 JP), Ainsworth Game Technology (AGI AU).
- Lowest spreads: Bright Smart Securities And (1428 HK), New World Resources (NWC AU), Avjennings Ltd (AVJ AU), Hainan Meilan International Airport (357 HK), Toyota Industries (6201 JP).
8. HD HCE–Infracore Merger: Deal Mechanics & Trade Playbook
- This event offers two arb plays—merger swap and appraisal rights—but there’s barely any juice left as pricing locked the market into an unusually tight range.
- Yeah, it’s tight. Unless cancel risk flares up, the spread likely stays muted—major holder’s balanced stakes make vote pushback or ratio disputes pretty unlikely.
- One angle to watch: passive flows. HCE likely joins KOSPI 200 post-merger, triggering index buys around Infracore’s halt on Dec 30—potentially a solid year-end positioning play.
9. KCC Corp: EB Issue of $625 Million Of HD KSOE + KCC Corp and KCC Glass Share Swaps
- KCC announced that it is issuing an EB worth $625 million in foreign currency using its stake in HD Korea Shipbuilding & Offshore Engineering as the underlying asset.
- The asset that is used as the underlying asset for the EB is 2.056 million shares of HD Korea Shipbuilding & Offshore Engineering held by the KCC Corp
- We believe this large EB issue by KCC Corp is likely to have a positive impact on KCC Corp but slightly negative impact on HD KSOE.
10. Merger Between HD Hyundai Infracore and HD Hyundai Construction Equipment
- After the market close on 1 July, HD Hyundai Infracore announced that it will be merging with HD Hyundai Construction Equipment.
- The merger ratio is 0.1621707 common shares of HD Hyundai Construction Equipment for each common share of HD Hyundai Infracore.
- We have Negative ratings on both HD Hyundai Infracore and HD Hyundai Construction Equipment.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Hygon/Sugon Merger: BIG Index Flows on Completion
- On 26 May, Hygon Information Technology (688041 CH) and Dawning Information Industry (603019 CH) announced a merger in a sign of consolidation in China’s chipmaking industry.
- For each share of Dawning held, shareholders will receive 0.5525 shares of Hygon. With uncertainty on the timeline for merger completion, Dawning is trading at a 10% discount.
- On completion of the merger, passive trackers will need to buy over US$1.1bn of Hygon Information Technology C (688041 CH) with nearly of that from local index trackers.
2. Greatland Resources (GGP AU): Big Index Inclusions for Recent IPO
- Greatland Resources (GGP AU) started trading on the ASX Ltd (ASX AU) on 24 June after selling shares worth A$504m in a primary and secondary offering across Australia/UK.
- Greatland has a full market cap of A$4.9bn and a high free float since Greatland Gold Plc (GGP LN) was listed on the AIM market of the London Stock Exchange.
- Given the large market cap and high float, the stock could be added to multiple indices over the next few months.
3. Xero (XRO AU): Index Flows Following the Capital Raise
- Xero Ltd (XRO AU) has entered into a binding agreement to acquire Melio Limited for an upfront cash consideration of US$2.5bn in cash and Xero Ltd (XRO AU) stock.
- The cash consideration is being funded mainly through a fully underwritten A$1.85bn (US$1.2bn) institutional placement. There is also a non-underwritten Share Purchase Plan to raise around A$200m.
- Given the large size of the institutional placement, there will be an increase in index shares and the passive buying that follows should mop up over 20% of the placement.
4. Gemlife (GLF AU): Index Inclusions Start Later This Year
- Gemlife (GLF AU) is looking to raise A$750m in a primary offering, valuing the company at A$1.58bn. The stock is expected to start trading on 3 July.
- The Puljich family and Thakral Corp (THK SP) are escrowed on their shares till mid 2026 at the earliest.
- Gemlife (GLF AU) could be added to global indexes in November and December this year, but S&P/ASX 300 Index inclusion could take place only in March 2026.
5. FWD Group (1828 HK): Offering Details & Index Entry Timeline
- FWD Group Holdings (FWD HK) is looking to raise up to HK$3.99bn (US$508m) in its IPO, valuing the company at HK$48.82bn (US$6.22bn).
- Cornerstone investors will take up more than half the base offering and that will delay index inclusion to well into 2026.
- FWD Group Holdings (FWD HK) could be added to the HSCI Index and Southbound Stock Connect in December. That could bring some buying into the stock from mainland investors.
6. Contact Energy/Manawa Energy: Index Flows as Deal Nears Completion
- Contact Energy (CEN NZ) is acquiring Manawa Energy Ltd (MNW NZ) for NZ$1.12/share in cash and 0.583 Contact Energy shares for each share of Manawa Energy.
- Manawa Energy (MNW NZ) is expected to stop trading after the close on 7 July. There will be passive inflows for Contact Energy (CEN NZ) due to increased index shares.
- As a replacement for Manawa Energy Ltd (MNW NZ), there will be an ad hoc inclusion to the S&P/NZX 50 Index at the close of 7 July.
7. Fresh Low-PBR Policy Color Hitting the Local Tape Today
- The ruling party’s KOSPI 5,000 task force is now eyeing low PBR names with talk of direct penalties — a sharper shift from the prior admin’s soft-touch value-up approach.
- Low PBR penalties may bypass the Assembly, fast-tracked via KRX or enforcement rule tweaks — rollout could follow swiftly post commercial code passage, possibly within 2–3 months.
- Market’s zeroing in on low PBR, high ROE large caps — with 0.8x flagged as the penalty line, 56 KRW 1T+ names screen as potential re-rating plays.
8. Krungthai Card (KTC TB): Buying Opportunity After Margin Call
- Mongkol Prakitchaiwattana is the second largest shareholder in Krungthai Card (KTC TB), behind Krung Thai Bank Pub (KTB TB).
- He also holds stakes in XSpring Capital (XPG TB), BEC World Public (BEC TB), and The Practical Solution (TPS TB).
- All four companies went limit down on the 23rd June. And again the next day. Both KTC and TPS say nothing has fundamentally changed. The cause? Margin calls.
9. Korea Holdco Rerating Pullback Risk: No Retroactive Treasury Cancellation
- Mandatory treasury cancellation isn’t in the current bill, but FSC and MOJ have started internal reviews; enforcement decree could drop as early as Q4.
- An internal policy paper suggests mandatory cancellation will apply only to newly acquired treasury shares, with tight limits on existing ones to curb owner control abuse.
- Lack of retroactive cancellation weakens the bull case, and while holdco sentiment stays upbeat, momentum may fade, opening the door to a tactical pullback.
10. PointsBet (PBH AU): Betr’s “Superior Offer”? In An Alternate Reality
- BETR Entertainment (BBT AU) has now tabled an all scrip off-market offer for PointsBet (PBH AU) – no minimum acceptance condition – which they consider superior to MIXI (2121 JP)‘s.
- Really? 3.81 new betr shares is currently equivalent to A$1.143/share versus MIXI’s A$1.20/share all-cash Offer. Terms backed out just A$1.086/share at the start of trading last Friday.
- PointsBet quite rightly states the obvious – betr’s Offer is materially below MIXI’s.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Santos Ltd (STO AU): FIRB Approval For XRG’s Tilt Will Be No Pushover
- Aussie O&G producer Santos Ltd (STO AU) has announced a non-binding Scheme from XRG, which comprises Abu Dhabi’s National Oil Company, Abu Dhabi Development Holding Company, and Carlyle
- The consortium is offering US$5.76 (A$8.89)/share, a 28% premium to last close. Initial Offers were pitched at US$5.04/share, followed by US$5.42/share.
- Confirmatory due diligence has been afforded. A firm bid would require a multitude of reg approvals in Australia, PNG, and the US.
2. [Japan Event] Potentially Interesting Dynamics of Post-Tender NTT Data (9613) Trading. $8bn+ One Way
- The NTT Data Corp (9613 JP) Tender Offer closed today. Results will come out tomorrow. I expect it will have been successful.
- That will mean some US$8bn+ of passive tracking flows to sell and $8bn+ to buy related to this event alone in the next 3 months.
- And there are some very interesting dynamics to consider in the meantime.
3. Shin Kong (2888 TT)/Taishin (2887 TT) – Short Timer, FX Risk, Index Flows – Time To Buy Vs Peers
- Shin Kong Financial Holding (2888 TT) and Taishin Financial Holding (2887 TT) are scheduled to merge in less than 6 weeks.
- The recent TWD strength has meant sharp losses for Shin Kong Life, but the merger agreement the FSC agreed has Taishin explicitly supporting Shin Kong Life.
- There are near-term flows and technical limitations which make this situation interesting again. Grab your shorts! It could be a bumpy ride!
4. Santos (STO AU): XRG Consortium’s Big Offer; Index Impact
- A consortium comprising ADNOC and Carlyle have offered US$5.76/share (A$8.8807/share) to take Santos Ltd (STO AU) private. That values Santos equity at A$28.8bn and an Enterprise Value of A$36bn.
- With the offer price at a premium of 28%-44% to last and VWAPs, and the Board supporting the offer, this looks like a done deal.
- Santos Ltd (STO AU) is a member of all the major S&P/ASX indices and there will be ad hoc inclusions to the indices at the time of the delisting.
5. Vishal Mega Mart (VMM IN) Placement: PE Selling Will Lead to Large Passive Buying
- Reports indicate that Kedaara Capital Fund is looking to sell 22% of Vishal Mega Mart at a floor price of INR 110/share, a 11.9% discount to the last close.
- The placement will lead to a huge increase in the free float for the stock and Vishal Mega Mart could be added to a global index in August.
- Vishal Mega Mart is also an inclusion to another global index at the close on Friday and we could see more buying in the stock following the increase in float.
6. [Japan Event] Seven Bank (8410) To Buy Back Up to 17.0% of Shares Out Tomorrow
- Today after the close, Seven Bank Ltd (8410 JP) announced a MASSIVE ToSTNeT-3 transaction to buy back up to 200,000,000 shares (17.0% of shares out) for ¥52.4bn. Tomorrow AM.
- There is a complex iterative calculation on the part of Seven Eleven Japan to figure out how many shares they should put into the buyback.
- I see a minimum buyback of 10.8%. 17% would be great. But there is a potential issue on the back end of which investors should be aware.
7. HDB Financial IPO: Offer Details & Index Entry Timing
- HDB Financial Services Ltd (0117739D IN) is looking to list on the exchanges by selling up to INR125bn (US$1.46bn) of stock at a valuation of around INR 620bn (US$7.2bn).
- The stock will not get Fast Entry to either of the global indices. The earliest inclusion in a global index should take place in December.
- HDB Financial Services Ltd‘s peers have traded well over the last 6 months and that could spill over into demand for the stock. Grey market premium is pretty high.
8. [Japan Activism] Mitsui Matsushima (1518) Ups Buyback Tender to 35.8%, Murakami-San Group To Sell
- Today after the close, Mitsui Matsushima (1518 JP) announced it would increase its buyback from 3.5mm shares to 4.0mm shares (31.3% to 35.8%). It also announced a Tender Offer Buyback.
- The tender offer starts tomorrow and goes til mid-July, paid 8 August. Murakami Group will tender a minimum of 3.3mm shares (more likely 4.2mm).
- This is not a huge immediate win, but it’s OK. And it changes the structure of the company’s balance sheet, ROE, effective ROE, and possibly its dividend.
9. ENN Energy (2688 HK): ENN Natural Gas’ Application Proof Is Out. Interesting For What Is Not Present
- On the 26th March, ENN Energy (2688 HK) announced a cash/scrip Offer from ENN Natural Gas (600803 CH) (ENN-NG), its largest shareholder.
- The pushback is that the scrip portion pivots off the value of newly-listed ENN-NG H-shares. And the IFA’s theoretical assessment on such leaves a lot to be desired.
- A redacted version of ENN-NG’s application proof is now out. Curiously, the share ratio – new ENN-NG H Shares for each ENN shares – is noticeably absent
10. [Japan M&A] NTT Docomo Buys Out Carta Holdings (3688) Minorities – Done Deal
- On 16 June 2025, NTT (Nippon Telegraph & Telephone) (9432 JP) sub NTT Docomo and Dentsu Inc (4324 JP) announced Docomo would buy out minorities in Dentsu sub Carta Holdings.
- It’s an OK price, not a great price. But while they are not calculated by advisors, at least the Target Board talks about the value of synergies to minorities.
- The price is light, but the combined irrevocables and large individual shareholders not brought over the wall get this over the line.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Event-Driven and Index Rebalance on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Index Treatment of Sony (6758 JP)’s Spinoff of the Financial Services Business
- For each share of Sony Corp (6758 JP), shareholders will receive 1 share of Sony Financial Group. Ex-date for the dividend in-kind is 29 September.
- The Nikkei has started a market consultation on treatment of the spinoff in the Nikkei225 and that means the dividend in-kind will not be included in the Dividend Point Index.
- There will be some selling in SFGI from passive trackers and the company will buy back some stock following listing. Details of the buyback have not been announced yet.
2. Foshan Haitian Flavouring & Food (3288 HK): Offering Details & Index Inclusion
- Foshan Haitian Flavouring & Food (603288 CH)‘s global offering opens today and the raise could reach up to US$1.5bn if the offer-size adjustment option and the overallotment option are exercised.
- There is a large allocation to cornerstone investors. The discount of around 22% to the A-shares is attractive given the recent trend for Midea (300 HK) and CATL (3750 HK).
- The H-shares could be added to a global index and the FXI ETF in December. Inclusion in the HSCI should be in September and Southbound Stock Connect in July.
3. [Japan M&A] Carlyle Deal for TRYT (9164) – Great Exit for Speculators as HR Co Targets Are Desirable
- In early February, articles suggesting the PE owner of TRYT (9164 JP) wanted to cash out. Performance post-IPO had been bad. Catching up to the IPO price would be tough.
- But a second round of bidding came about, so the stock went limit up. Then it settled in the ¥480 range for three weeks. Then started to climb.
- Now the company and its PE firm owner have announced a sale to a new PE Firm at ¥880/share. This is below IPO Price but it will get done.
4. Toyota Industries (6201 JP): Thoughts on Intrinsic Value
- Several investors have sharply criticised Toyota Industries (6201 JP)’s preconditional tender offer from Toyota Fudosan. Oasis is pushing for a higher offer.
- The offer has several issues that are detrimental to minorities’ interests. The key grievance is that it is below TICO’s intrinsic value.
- Due to TICO’s varied business units, SoTP valuation is the most appropriate methodology. My analysis suggests a base case intrinsic value of around JPY19,000.
5. [Japan M&A] Private Co Takeout of Fuji Corp (7605 JP) – A Done Deal
- The long-term major owner now chairman is getting out. The company was shopped. And bought. And this is the deal. ¥2,830 which is about 5.7x this year’s EBITDA.
- It could have been done a bit better, but irrevocables are 48.5% out of the 50.01% minimum and other directors get this past the minimum hurdle.
- Transparency is lacking but it is an all-time high and you can’t do much about it.
6. Virgin Australia (VGN AU): Touch & Go for Index Inclusion
- Virgin Australia Holdings (VGN AU) is looking to raise A$685m in a secondary offering, valuing the company at A$2.27bn. The stock is expected to start trading on 24 June.
- Bain Capital and management are escrowed on their shares till early 2026. There is no escrow for Qatar Airways, but they have indicated that their shareholding is strategic.
- Virgin Australia Holdings (VGN AU) could be added to the S&P/ASX 300 Index in September and there could be global index inclusions in November and December.
7. Zhejiang Sanhua Intelligent Controls (2050 HK): Big Raise Supported by Cornerstones
- Zhejiang Sanhua Intellignt Controls Co. (002050 CH)‘s global offering opens today and the raise could reach up to US$1.4bn if the offer-size adjustment option and the overallotment option are exercised.
- There is a large allocation to cornerstone investors. The discount of around 22.7% to the A-shares is attractive given the recent trend for Midea (300 HK) and CATL (3750 HK).
- The H-shares should be added to Southbound Stock Connect in July, to the HSCI in September, and to a global index in December.
8. Merger Arb Mondays (09 June) – Mayne, Tam Jai, OneConnect, Toyota Industries, Makino, Fuji Corp
- We summarise the latest spreads and newsflow of merger arb situations we cover across Hong Kong, Australia, New Zealand, Singapore, Japan, Indonesia, Malaysia, Philippines, Thailand and Chinese ADRs.
- Highest spreads: Mayne Pharma (MYX AU), Insignia Financial (IFL AU), Fuji Corp (7605 JP), ENN Energy (2688 HK), Smartpay Holdings (SPY NZ), Seven & I Holdings (3382 JP).
- Lowest spreads: Bright Smart Securities And (1428 HK), Toyota Industries (6201 JP), Dada Nexus (DADA US), Avjennings Ltd (AVJ AU), Nissin Corp (9066 JP), Torii Pharmaceutical (4551 JP).
9. [Japan M&A] Hino & Mitsubishi-Fuso Truck to Join; Bagholding Ugly for Minorities, and a Re-IPO
- On the 10th of June, Toyota Motor (7203 JP) subsidiary Hino Motors Ltd (7205 JP) and Mitsubishi-Fuso Truck & Bus Company announced their long-awaited integration plans. We have a deal.
- An agreement was signed in 2023, but Hino got in big trouble for falsifying testing data on gasoline engine emissions/efficiency. Hino took a hit in 2023, then 2025. Talks advanced.
- The deal announced suggests Toyota has thrown itself and Hino minorities under the proverbial Fuso bus. It’s VERY odd. But… it deserves a look because 2026 will see a re-IPO.
10. A/H Premium Tracker (To 6 June 2025): Narrow Premia Hs Worst Performers, BYD Relents
- AH spreads are slightly narrower. BANKS, INSURERS, BROKERS, INDUSTRIALS, PHARMA and UTILITIES see significant H-share outperformance vs their A pairs. TECH, CONSUMER, ENERGY mixed to worse.
- Ongoing skew on H-vs-A performance this week. Those trading AH Premium <20% saw H outperform sharply but those with H Premia contracted. Quiddity Portfolio alpha trending strongly.
- The data tables below update on a daily basis in the Tools section of Smartkarma. The SOUTHBOUND Flow Monitor and AH Monitor are both there free for SK readers.