This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
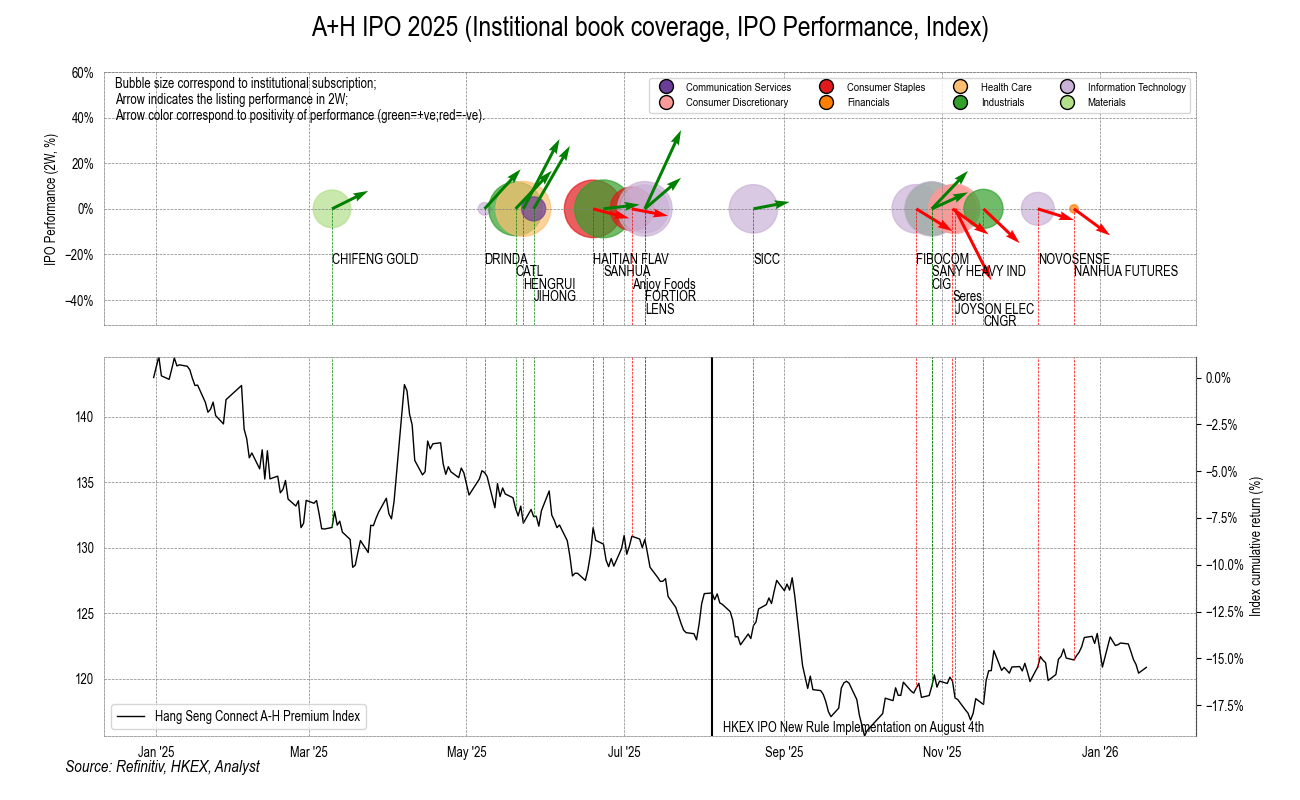
1. HK A+H IPO 2025: Essential Statistics Ahead of the 2026 Wave
- In this note, we take a statistical view of the A+H listing in 2025.
- We examine time-series trends in IPO performance, subscription dynamics, market sentiment, and sponsor performance.
- We also look at A-H premium dynamics post-listing and sector-level deal performance.
2. Busy Ming Hong Kong IPO Preview
- Busy Ming Group (1768 HK) is getting ready to complete its IPO in Hong Kong next week. The IPO price range is between HK$229.60 and HK$236.60.
- At the top of the range, it would bring in about HK$3.3 billion (US$420 million) and value the company at about HK$50.7 billion (US$6.5 billion).
- The company experienced explosive growth in the past four years, driven mainly by rapid store expansion and the Super Ming acquisition.
3. Aequitas: Sinotruk Placement – First Selldown Introduces Overhang After Strong Run-Up
- German truckmaker, MAN SE (via MAN Finance and Holding) is looking to sell a ~2% stake in Sinotruk Hong Kong (3808 HK) to raise upto US$207m via a secondary selldown.
- Sinotruk (Hong Kong) Ltd is China’s leading heavy-duty truck manufacturer, focused on commercial vehicles with strong domestic market share, growing exports, and consistent cash generation.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
4. Muyuan Foods A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Muyuan Foodstuff Co Ltd A (002714 CH), a leader in the hog farming industry, aims to raise around US$1.5bn in its H-share listing.
- MF is a leading pork company with over 30 years of expertise in the hog farming industry.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
5. Busy Ming (1768 HK) IPO: Not Expensive with Moderate Upside
- Busy Ming Group (1768 HK)‘s 3-year EPS CAGR of 43.1% places it ahead of most peers in F&B retailing, including the tea beverage sector.
- Operating on a franchise model, its 13x FY26F and 10.2x FY27F PERs are not expensive, as peers ex-Sun Art Retail (6808 HK) are averaging at 15x and 12.4x.
- It is difficult to trade at Mixue (2097 HK)‘s and Guming (1364 HK)‘s ~20x, due to lower margins. Our fair value is 16.5x PER, equalling HK$300.
6. Busy Ming (1768 HK) IPO: Uplifted Margins, Strong Volumes, Market Reach Make It A Compelling BUY
- Busy Ming (1768 HK) launched its Hongkong IPO aiming to raise up to HK$ 3.3B. The company plans to sell 14.1M shares at HK$229.6-$236.6 per share.
- Busy Ming Group is an established and growing food and beverage retailer in China. The company owns two popular brands, “Busy for You” and “Super Ming”.
- The growth outlook more than justifies the valuation. We would recommend the investors to subscribe to the issue and cash in on the secular growth story the company is offering.
7. Eastroc Beverage H Share Listing: The Investment Case
- Eastroc Beverage Group (605499 CH), the largest functional beverage company in China, is pre-marketing an H-Share listing to raise around US$1 billion.
- The product portfolio includes energy beverages, sports beverages, tea beverages, coffee beverages, plant-based protein beverages, fruit and vegetable juice beverages, and other beverage products.
- The investment case rests on a large TAM, a core business in good health, rising margins and strong cash conversion.
8. Busy Ming (1768 HK) IPO: Valuation Insights
- Busy Ming Group (1768 HK) is a food and beverage retailer in China. It has launched an HKEx IPO to raise up to US$428 million.
- I previously discussed the IPO in Busy Ming IPO: The Investment Case.
- In this note, I present my forecasts and valuation. My analysis suggests that the IPO price range is attractive.
9. Aequitas: Shadowfax IPO – Delivering a Decent Valuation Entry Point
- Shadowfax Technologies (1310315D IN) is looking to raise US$211m in its upcoming India IPO.
- Shadowfax Technologies is a third-party logistics (3PL) company that leverages a unified platform to facilitate digital commerce across India.
- We have looked at the company’s past performance in our previous note. In this note, we talk about valuations.
10. Aequitas: Busy Ming Pre-IPO- Priced at a Discount to Peers
- Busy Ming Group (BMG HK) is looking to raise up to US$430m in its upcoming Hong Kong IPO.
- It is a rapidly growing food and beverage retailer in China. Stores are typically located in high-traffic, high visibility, and easily accessible street-side locations.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.