This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
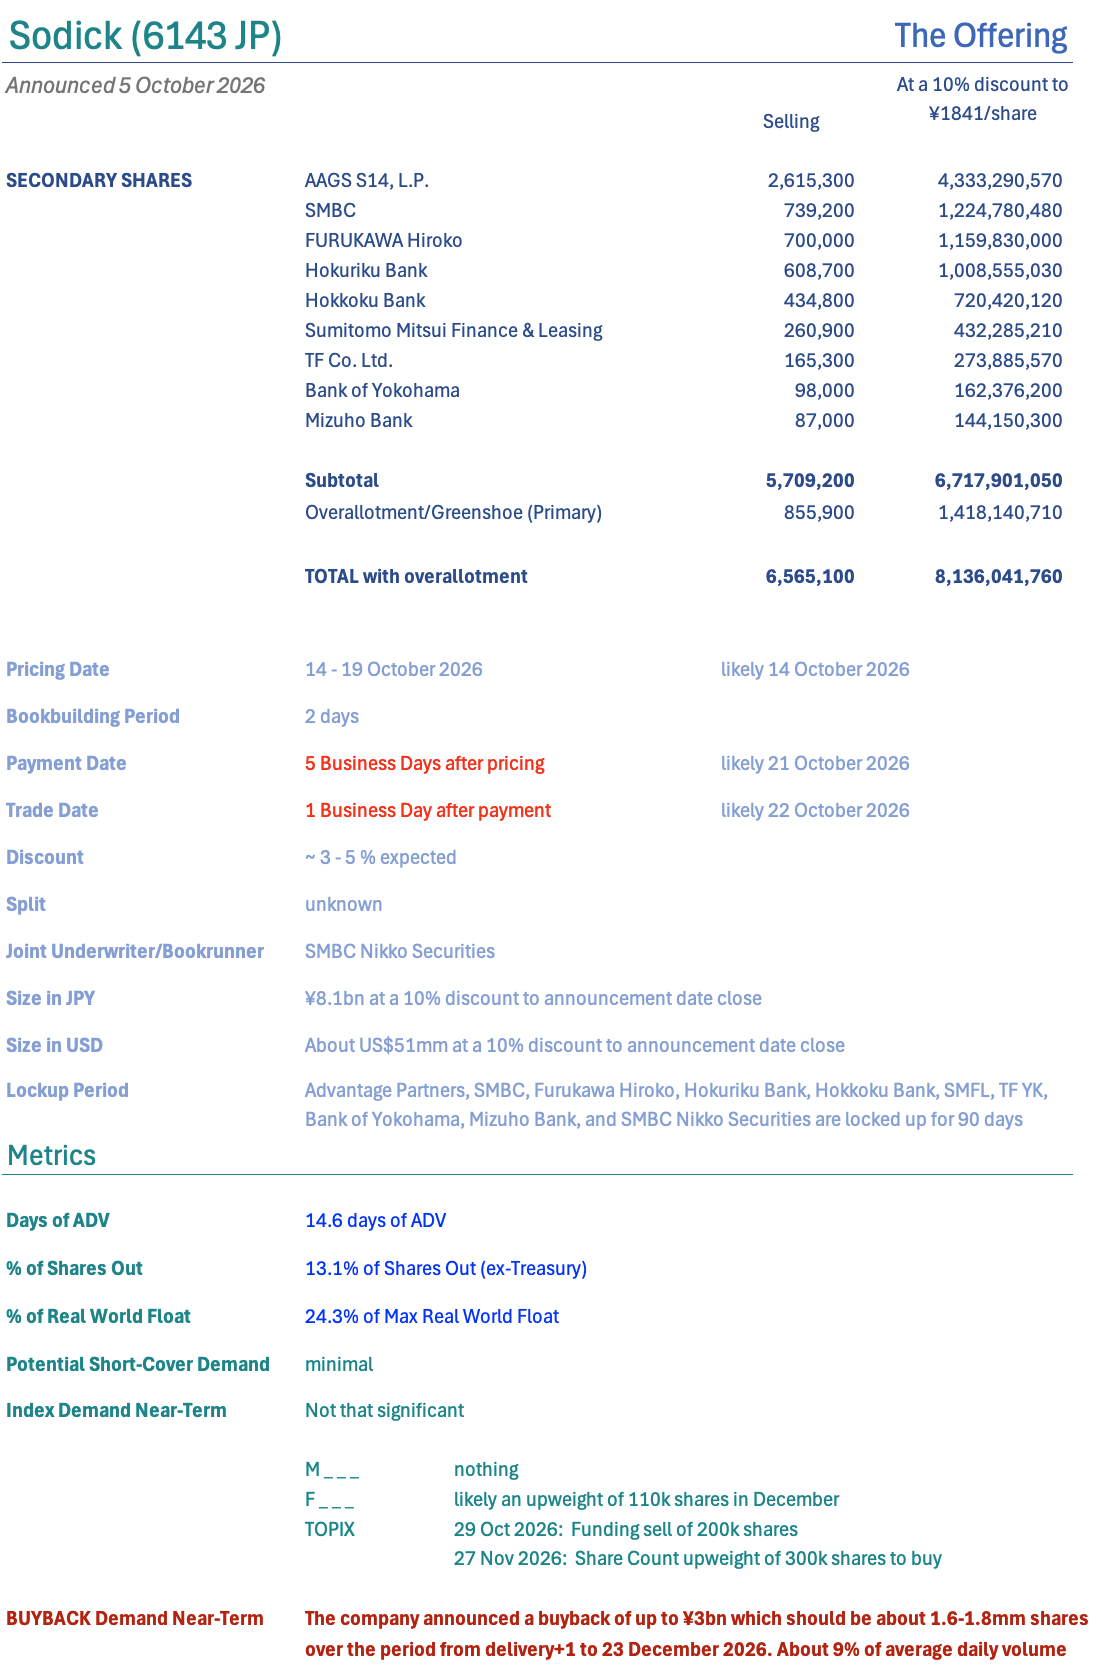
1. [Japan Offering] Sodick (6143 JP) Offering by Crossholders and AP (Ouch); Cheap But A Mgmt Red Flag
- Sodick Co Ltd (6143 JP) announced a secondary equity offering yesterday. The stock is down 6% today because of that but that barely covers the dilution.
- Yes, it is secondary, but nearly 40% of the offering is from secondary shares created from warrant conversion. AP bought dirt cheap warrants and a dirt cheap CB last year.
- The Company benefits from AI Data Centre buildout, and isn’t expensive. There’s a buyback to mitigate supply, but that goes to show the AP deal was structurally a bad idea.
2. MINIMAX-W: Stealth Model, Placement and the Short
- We noted Space Bunny Alpha, a stealth model which is likely MiniMax’s M3.1-Flash, and compared its available benchmarking with Chinese and US models.
- We analysed the sequence of model launches and placements at MiniMax and its competitor Zhipu, and the release cadence of Chinese labs.
- We think the M3.1 launch is imminent and could be followed by a placement, and we review how the stock traded in past launches for MiniMax and its comparable.
3. DayOne Pre-IPO: Tearsheet
- DayOne, a hyperscale data center developer and operator, has filed its registration statement with the SEC for a Nasdaq listing. MS, JPM, BOA, Citi and BNP Paribas are the underwriters.
- We look at the company’s core Singapore/Malaysia/Indonesia markets of Singapore, Johor and Batam, and its newer markets in Asia and Europe.
- We then look at the company’s financial profile, loss-making status, pre-IPO valuation and investor backing.
4. [Japan Offering] CKD (6407 JP) Sees Banks and an Insurer Sell; Buyback but Index Selling Offsets
- Yesterday, Ckd Corp (6407 JP) announced a secondary offering where multiple banks and an insurer will sell shares. Other banks and corporates and various mutual ownership associations will still hold.
- The offering is “small” at 6x ADV and 6% but the stock is well held by actives already. Only 13% of Max Real World Float on offer here but… overhang.
- The company is in the right AI/semicon/machinery space (stock up big last 18mos) but it isn’t dirt cheap and expected growth is slower than you’d like for the multiple.
5. Aequitas: CIG Shanghai Placement – Another Opportunistic Raising, Last One Did OK.. For a While
- CIG Shanghai (6166 HK) is looking to raise around US$250m from a primary share placement, along with US$500m via a CB issuance.
- CIG Shanghai Ltd is a provider of critical infrastructure components for the development of AI. Its portfolio includes high-speed optical transceivers, wireless and broadband access, carrier Ethernet, and edge computing.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
6. Transsion (传音控股) A+H IPO: Analysis of Deal Terms
- Transsion, a mobile phone maker focused on Africa and other emerging markets, launched its IPO to raise USD 428m through an A+H listing. CITIC is the sole sponsor.
- In this note, we look at the deal terms and provide our thoughts on valuation for the company.
- We analyze reference A+H transactions, cornerstone and sponsor performance and assess the risk-reward of the deal.
7. Aequitas: Wuxi Biologics Placement – Recent Streak of Underperforming Deals
- WuXi Biologics Holdings (WBH) is looking to raise US$500m from a partial selldown of its stake in Wuxi Biologics (2269 HK).
- WBH had been continuously selling down its stake over the last few years.
- In this note, we will talk about the placement and run the deal through our ECM framework.
8. Jio Platforms IPO: Valuation First-Look
- Jio Platforms Ltd (1797135D IN), India’s largest digital connectivity player, is set to launch its IPO to raise about US$3.4 billion.
- I previously discussed the IPO in Jio Platforms IPO: The Investment Case.
- My DCF valuation, which leans towards bullish assumptions, is 4.8% below the rumoured US$114 billion valuation. Therefore, Jio is fairly valued at the rumoured IPO valuation.
9. Leaked IPO Prospectus of Anthropic: “Risk to Humanity” + Altruistic Incentives Vs Shareholder Value
- In FY2025, Amazon and Google platforms directly generated 47% ($2.16 billion) of Anthropic’s total sales.
- The founders have also pledged 80% of their personal equity to charitable causes, with chunks directed toward organizations like UNICEF.
- There is a risk of the controlling shareholders potentially not acting in the best interests of all shareholders. Also, its management mentions its technology could be a “risk to humanity.”
10. Jio Platforms Pre IPO: Steadily Broadening Its Band
- Jio Platforms has filed for an India IPO. The company is a technology platform combining mobile, fixed broadband and digital services.
- Jio Platforms intends to use the proceeds for prepayment, in full or in part, of the principal amount outstanding of certain borrowings and for general corporate purpose.
- Jio Platforms’ strong market presence, brand recognition, coupled with consistent subscriber addition does make this issue attractive for investors.