
This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK: The Chancellor’s Empty Hat
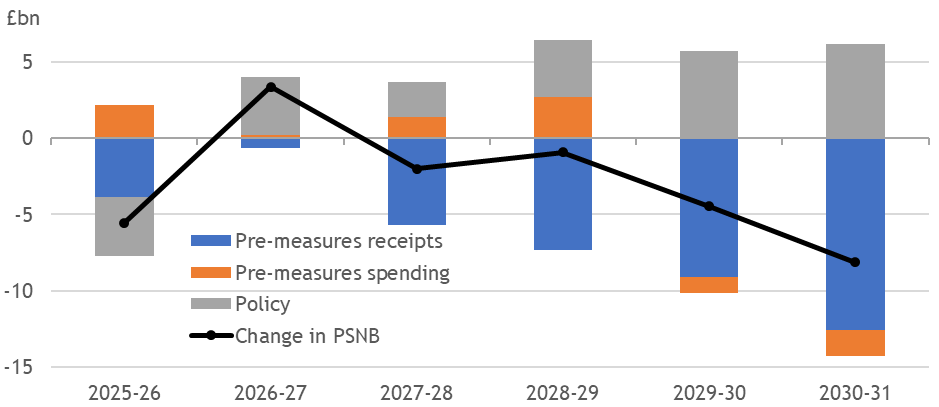
- The UK Chancellor resisted pulling any rabbits out of her hat, which offers welcome economic stability, but leaves her looking like she’s got no ideas left to change things.
- Fiscal projections improved slightly, and earlier announcements only partly spent them, but the Iran war could easily blow up that space, especially if the conflict is sustained.
- Forecasts and Keir Starmer’s position are like Wile E. Coyote floating over the abyss. A more left-wing PM and Chancellor are likely after the local election losses in May.
2. HEM: Mar-26 Views & Challenges
- A dovish repricing during February followed surprisingly broad BoE dissents, even as the Fed signalled stability.
- The BoE’s dovish bias renews the accommodation of excess inflation. Output and credit remain resilient.
- Unemployment’s global stability suggests monetary conditions might be broadly neutral. Cuts could take them loose.
3. HEW: Rates Fly On Magic Carpet
- The explosives flying out of Iran at critical energy infrastructure are causing inflation pressures to soar on a Persian magic carpet, taking the policy rate outlook with it.
- EA inflation was surprisingly strong before this shock hit, and UK CFOs told the BoE that they don’t see slack. Chillingly bad US payrolls don’t break the case for caution.
- Next week’s thin release calendar features UK GDP and US inflation, but their relevance is overtaken by developments in the Middle East and the spillovers from that.
4. EA: Inflation Explodes Before The War
- EA inflation exploded out of its January trough to hit 1.9% in February. The upside news was broad across special aggregates and countries, compounding the hawkish signal.
- Services strengthen the underlying story, with past energy price falls responsible for the ongoing slight target undershoot. War with Iran is flipping that energy price story.
- The ECB can remain in its good place for now. The broad underlying strength renews the likelihood that it heads in a hawkish direction when it leaves the good place.
5. UK: Firms Still Don’t Find Slack
- CFOs are telling the BoE that there has been no change in recruitment difficulties over the past year, staying marginally tight on balance, despite unemployment jumping.
- The divergence is consistent with unemployment’s rise being structural. Adding the NICs threshold change to the basic rate increase raises our NAWRU estimate to 5.3%.
- Dovish MPC hopes that slack will drive headline pay to sustainable levels are likely to be disappointed, with no significant slack and expectations stuck above the target.
6. War, Oil and Asia
- Asia has enough stockpiles to weather at least a month of crude import disruptions.
- It’ll still likely feel the impact of higher oil prices through rising import bills, deteriorating current account balances and weaker currencies.
- Monetary policy will likely prioritise inflation over growth, pushing the bar for rate cuts higher.
7. HONG KONG ALPHA PORTFOLIO: (February 2026)
- Hong Kong Alpha portfolio gained 0.46 % in February resulting in a 2.99% underperformance to its benchmark. The portfolio has outperformed HK indexes by 53% to 75% since inception 10/1/24.
- Hong Kong Alpha has generated 63% of its return from alpha and has a Sharpe ratio of 1.71 since inception. The portfolio’s annualized mean excess return is 24%.
- At the end of February, we reduced positions in the technology sector and added positions in the energy and building materials sectors.
8. Dual Track Anti-Stock Price Suppression Laws in Korea
- In this insight, we discuss the new, dual track anti-stock price suppression laws that the Korean government is trying to pass.
- Two anti-stock price suppression laws include requiring companies with PBR of less than 1x to submit corporate value enhancement plan and amendment to the Inheritance and Gift Tax Act.
- According to KRX, 549 of the 919 KOSPI-listed companies had a PBR of less than 1x (about 60% of total), which is significantly higher than Japan (33%) and US (2%).
9. Activity Robust Before Energy Shock
- The global economic impact of the Iranian conflict is sensitive to initial conditions, where a robust starting point keeps the shock relatively small and linear.
- Slowing in the US services PMI is balanced by a booming ISM and strength elsewhere, including in the manufacturing sector. Employment is also improving outside the UK.
- Resilience to the demand-side of the shock encourages policymakers to lean against the inflation risk, with the possibility of BoE and Fed cuts shrinking in response.
10. Making Sense of the Citrini AI Debate
- Citrini Research recently published a controversial report postulating a scenario where AI wipes out millions of jobs. By contrast, AI boosters assume widespread productivity gains without disruption.
- The history of the adoption of disruptive technology indicates that outcomes are never utopian nor Apocalyptic.
- We prefer to adopt a middle ground. AI is a very real and its adoption will dramatically change society. Expect some degree of disruption in capital markets and return expectations.


