This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Wall Street Vs Silicon Valley: AI Cannot Pay for Itself, so It Will Come for the Businesses that Can
- AI’s Next Battle Is Not Models — It Is the US$4tn+ Fee Pools Around Them, From Financial Services to Advertising and Information
- Silicon Valley Has the Scale and Cost Advantage; Wall Street Has the Licences, Balance Sheets and Relationships to Defend the Fortress
- Our Outcome: A Bifurcated Oligopoly — AI Captures Unlicensed Thinking, While Regulated Incumbents Defend Clients but Surrender Pricing Power
2. India Equities: Stocks to Watch After Deep Underperformance
- India reversed its entire relative gain against EM. The near 50% relative drawdown is the deepest and longest since 2012, so we’re positioning for improvement.
- Bottom-Decile losses in India have historically preceded strong rebounds. Although relative washouts offer no comparable evidence. We can scale up on an absoute basis.
- Opportunity in the middle of the index. We built a tiered watch list from the middle cohort, scaling toward equal weight as confirmation arrives.
3. HEW: Broadening Rate Rises
- Hopeful easing of energy price pressures didn’t disrupt the rising trend in interest rates, aided by PMI data showing sustained resilience and the ongoing fiscal profligacy.
- The Norges Bank delivered a hike, despite dovish hopes to stop it, while the Riksbank signalled it will start hiking before year-end, and even the SNB opened a hawkish door.
- Next week is the RBA’s turn to be hawkish to avoid unwelcome FX pressures. US payrolls and higher EA inflation are the week’s highlights in the macro data.
4. SNB: Franc Shifts the Balance
- The SNB held its policy rate at 0%, as unanimously forecast, judging that higher headline inflation does not yet warrant tightening.
- A weaker franc and elevated energy costs have lifted the inflation path, but forecasts of 0.8% in 2027 and 2028 still support a prolonged hold.
- Rate rises require broader, persistent inflation; renewed franc strength or weaker global demand would instead reinforce the 0% floor.
5. Sentiment Matters: The Biggest Consensus Longs and Shorts
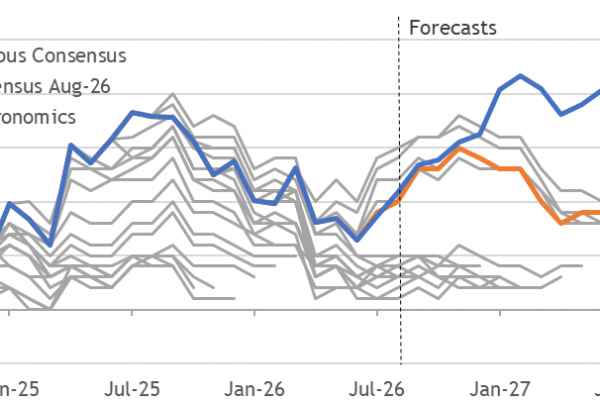
- Where is the market most crowded — and where could the consensus be most vulnerable? This note uses our cross-asset sentiment rankings to find out.
- Technology, Industrial Metals and Energy remain among the strongest consensus longs, with bullish sentiment elevated enough to raise the hurdle for further positive surprises.
- Health Care and High Yield sit near the bearish end of the ranking, but Health Care offers the cleaner contrarian setup given broader and more extreme pessimism.
6. Riksbank Holds Now to Hike Later
- The Riksbank held at 1.75%, as unanimously expected, but its higher rate path confirms a 2026 increase in the base case, with more in 2027.
- Stronger demand, a weaker krona and higher energy costs raise second-round inflation risks, despite underlying inflation remaining near 2%.
- Future hikes hinge on adjusted inflation, demand and labour-market resilience, the krona, energy prices and fiscal policy.
7. Technically Speaking Breakouts & Breakdowns – HONG KONG (September 2026)
- The Hong Kong market continues to drift sideways this month, trading above its long-term support levels but unable to rally past strong resistance at 27100.
- The healthcare and materials sectors have been the only positive performers since August. Large-cap and value factors have consistently outperformed YTD.
- JOINN Laboratories (6127 HK) had an engulfing breakout earlier in the month. The H1 2026 backlog surged 61% to CNY 3.7bn, with newly signed orders nearly doubling.
8. Indonesia: Rupiah Defence Sets the Rate
- Bank Indonesia held its policy rate at 5.75%, as expected, prioritising rupiah stability while macroprudential and fiscal measures support growth.
- Near-Term cuts are unlikely as Fed tightening, a strong dollar, weak portfolio inflows and higher oil prices constrain BI’s policy flexibility.
- A prolonged hold is most likely; renewed rupiah or inflation pressure could trigger a hike, while cuts require sustained external stability.
9. Resilience Survives Renewed Shock
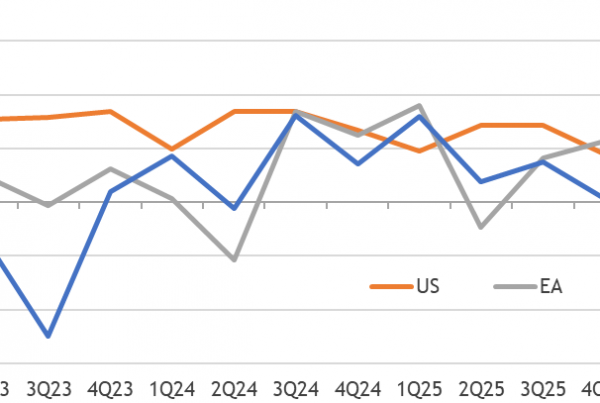
- Flash PMI balances broadly increased in September, despite the intensifying energy supply shock. It has so far been shrugged off, just like the tariffs last year.
- Services balances had fallen in Q1 before the conflict began but have broadly recovered all the lost ground even without the conflict ending.
- National services balances are broadly above their medians of the past year and decade, so demand is not depressed and can’t offset excess inflation in policy trade-offs.
10. BUY/SELL/HOLD: Hong Kong Market Update (September 2026)
- The Hong Kong market continues to consolidate, holding above its long-term support levels but without the momentum to break out to new highs.
- Healthcare is the only sector in positive territory in September. The materials sector benefited from gains in the gold sector.
- ZTE (763 HK) is maintained a BUY at CMB International with a +48% 12-month upside target price. The company is transitioning to international and AI sectors for growth.