
This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
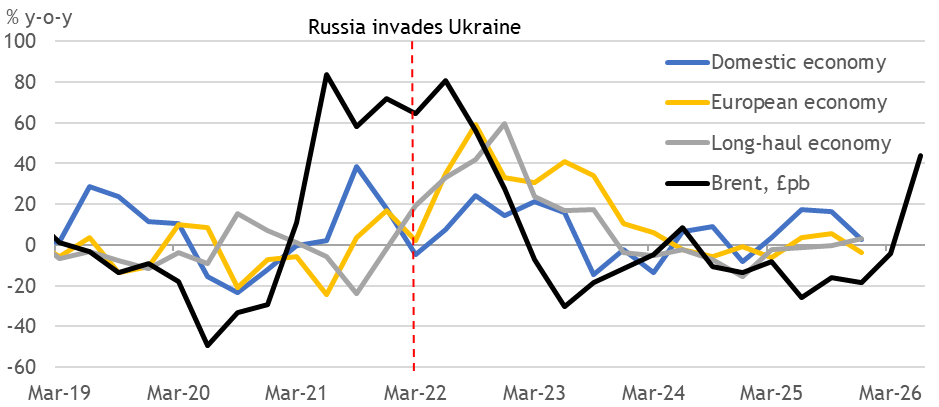
1. UK Airfares Fly Further, Later
- Airfares are energy-intensive, so they will trend higher with oil prices, especially now that domestic flights are almost irrelevant and long-haul’s weight is up 15pp since 2020.
- Prices are being sampled earlier, postponing much of the impact until the summer holidays and beyond, with larger rises and smaller seasonal falls than otherwise.
- Index date quirks will still dominate in a soft April and resurgent December, but we see airfares up 21% by Feb-27, similar to the aftermath of Russia’s invasion of Ukraine.
2. UK: CPI Outlook Embarrasses the BoE
- UK inflation stayed at 3% in February, while the core rate rose to 3.23%, leaving only 30bps of progress over the past year. Underlying pressures keep exceeding BoE hopes.
- Surging energy prices should broadly return the Ofgem cap to Feb-24 levels, but take the CPI above 3.5% after averaging 2.9% in the gap when costs were temporarily low.
- We see inflation peaking around 4% in 2026 and slowing to 3% in 2027. Whatever happens, the BoE’s inflationary bias is set to keep the CPI trending above its target.
3. US BEAR MARKET: Stage Two – ANGER
- The U.S. stock market is entering a new stage of its bear market. It never fully recovered from the Liberation Day drawdown, instead allowing the dollar to absorb the losses.
- The market has entered its 5th month of sub-2% monthly gains, a pattern that has historically preceded bear markets.
- Household dependence on stock market gains for consumption is at historically high levels. Increased inflation resulting from higher oil prices exacerbates a vicious downward spiral in consumption and the market.
4. Activity Resisting Energy Shock
- Flash PMIs for March reveal a broad weakening concentrated in the services sector, but of a similarly benign size to the shock from Trump’s tariff announcement last April.
- The starting point is more robust now, and that momentum should help carry the global economy through the supply shock, although the damage will accelerate with time.
- Monetary policymakers should feel more comfortable focusing on the inflationary risk while the demand side of the stagflationary shock is proving so benign.
5. Asian Equities: Relative Value Trades After This Dislocation
- Sharp dislocations in Asian markets have opened up relative value trade opportunities. Many Asian markets’ valuations are near long-term averages, but some are far more expensive, and some far cheaper.
- Going by likely mean reversion, we conclude that Taiwan should correct more while Korea should rerate. The other markets are close to their long-term means, and hence, difficult to call.
- In ASEAN, going long Indonesia and Philippines and shorting Singapore could be profitable. Shorting Thailand could be an option too, from the perspective of earnings pressure due to tourism slowdown.
6. HEW: War Lays an Egg for Easter
- War with Iran is making little progress between waves of tension, although Trump lost his ladder to climb down as Iran seeks to retain control of the Strait of Hormuz.
- This hurts Europe and Asia the most, and to an increasing extent over time, so their central bankers made screeching hawkish turns. But Latam remains relatively dovish.
- Next weekend is Easter, so this publication will take a customary break, returning on 10 April. EA and US inflation for March, plus nonfarm payrolls, are the main releases.
7. Chile’s Policy Pivot to a Risk‑Management Hold
- The Central Bank of Chile holds rates at 4.5% as expected, shifting from an easing bias to a data‑dependent, risk‑management pause for longer.
- Oil‑driven shock pushes forecast inflation to ~4% near term, so upside inflation risks now outweigh growth in rate decisions.
- Future moves hinge on expectations staying near 3%; anchored views support a hold, de‑anchoring would likely trigger tightening.
8. CHARTING COURSE: U.S. Waves the White Flag, “Lucky Trades”, and the War’s Inflation Tax (3/26/26)
- The war’s unintended consequences are creating global risks in energy and shipping, which may extend beyond the near term. Truce negotiations will be protracted with no quick resolution in sight.
- Prediction markets show that the probability of oil prices remaining high through year-end is increasing, while the probability of a quick war resolution is declining. Iran now controls the Strait.
- Price pressures are mounting as import prices showed the highest monthly increases since 2022.
9. US: Iran War Isn’t About to End Despite the Improved Atmospherics from Trump
- The worst case scenario (of tit-for-tat attacks on energy infrastructure) has abated for the week ahead. Pezeshkian-Trump deal via intermediaries will be fiendishly difficult to implement as IRGC/Basij will resist.
- Despite decapitation of Iran’s leadership, IRGC/Basij’s fight persists, like Iraq’s Ba’athists peopling Iraq’s Sunni militias 2003-13. Israel has forced Iran’s retreat from Syria-Lebanon-Gaza; reformist Azeri-Kurd Pezeshkian could countenance regime change.
- Iran’s intransigent forces won’t capitulate without gaining an end to sanctions. US-Israel will demand a final end to Iran’s nuclear-bomb capability. There’s many a slip ‘twixt cup&lip. Stay cautious.
10. The Heat Is On: News Flow and Sentiment in CHINA / HONG KONG (March 23)
- The Hong Kong market is experiencing its worst February/March period in 10 years. Although the market has corrected amid risk-off sentiment, we expect it to hold long-term support at 24000.
- The energy sector has been the clear beneficiary this year, with coal companies outperforming.
- Semiconductor Manufacturing International Corp (SMIC) (981 HK) share price has tumbled since the start of the war, amid questions about helium supply and prices following the bombing of Qatar facilities.


