This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
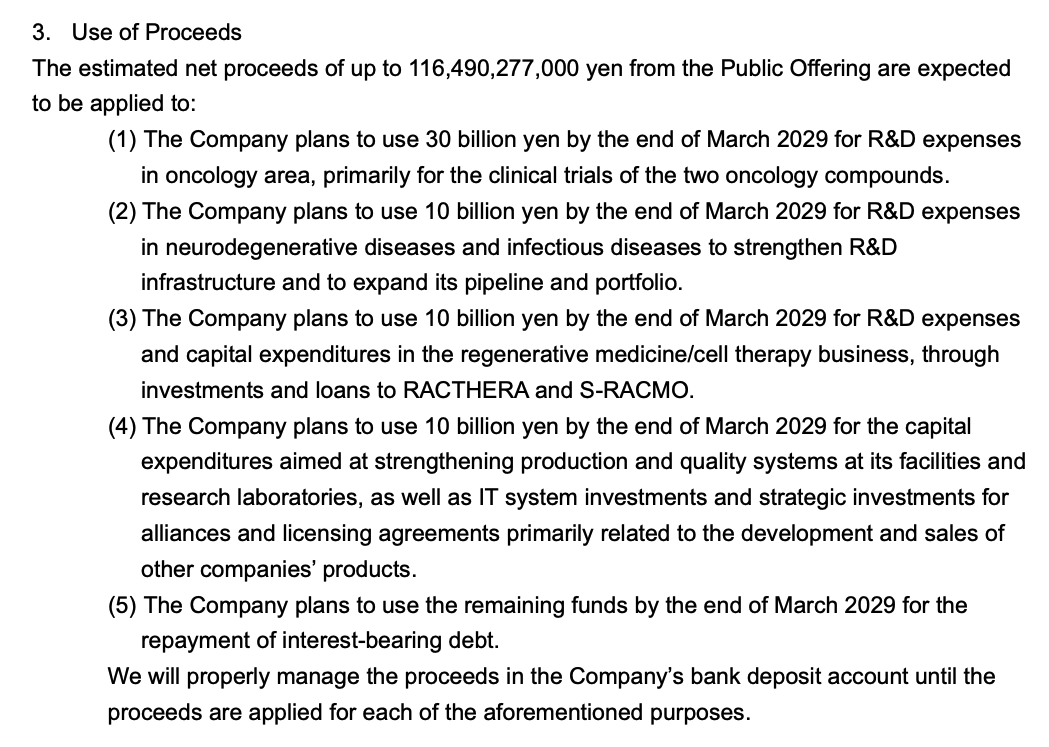
1. [Japan Offering] Sumitomo Pharma (4506) Issuing ¥100bn of New Shares for Investments
- Sumitomo Pharma (4506 JP) is coming out of its earnings funk from 2023-2024. The stock has risen sharply off lows. Now the company has put out its hat.
- They want to sell 59.0mm shares (against 385mm or so now) which is about 15% of shares out, and a whopping 65+% of (active voting rights) Max Real World Float.
- There is index impact near-term and further out, and there are shorts to be covered. But this is heavily dilutive to the active Max Real World Float.
2. [Japan Offering] Union Tool (6278 JP) Issuing ¥30bn of Shares For Investment Purposes
- On Monday 6 April, Union Tool Co (6278 JP) announced they were offering ¥30bn of Treasury shares to fund investment. It is a 28% increase in equity.
- Union Tool is rich in terms of net cash+securities+OPCF, it didn’t need to issue shares to fund the capex, so it feels like a “sell shares at the top” strategy.
- Guidance seems conservative for the market environment but capacity utilisation is high, and they are investing for a higher run-rate going forward. Seems expensive but AI is a new paradigm.
3. Aequitas: Samsung Electronics Placement -Final Inheritance Payment Selldown; 1Q26 Beats Estimates
- Hong Ra-hee, the widow of former Samsung Group chairman Lee Kun-hee, is looking to sell around U$2bn worth of Samsung Electronics (005930 KS) shares via a secondary placement.
- The heirs have been paying inheritance tax since April 2021, and the final payment, due April 2026, is likely to be this sale.
- In this note, we will talk about the placement and run the deal through our ECM framework.
4. Aequitas ECM Weekly (7 April 2026)-Victory Giant, Huaqin, Sigenergy, Manycore, WeWork, MTT, AVATR
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, a number of companies are lininig up in Hong Kong to launch their IPOs soon.
- On the placement front, there weren’t many large deals given the ongoing market volatility.
5. Pre-IPO Sigenergy Technology (PHIP Updates) – The Strength and the Concerns
- The core of Sigenergy’s business model is focusing on segmented tracks, exploring overseas high-end home markets through highly integrated innovative products, and adopting a global distribution model.
- To seize the market and cope with competition, Sigenergy may lower the price of SigenStor.As raw material costs fluctuate, high gross margin is difficult to maintain and would fall back.
- By referring to the valuations of peers during their upwrd phase, considering the high growth/high risk of Sigenergy, and based on our forecast, 12-18x P/E could be a relatively reasonable range.
6. Sigenergy IPO: The Investment Case
- Sigenergy (SIG CH), a global leader in distributed energy storage system (DESS) solutions, is pre-marketing an HKEx IPO to raise around US$500-600 million.
- The flagship product is SigenStor, which is the first ESS solution in the industry to combine five-in-one functionalities and among the first to adopt stacking technologies.
- The investment case rests on the market positioning, rapid growth, margin expansion, declining cash burn and modest leverage.
7. Sigenergy (6656 HK) IPO: Go for It!
- Sigenergy Technology (6656 HK), as a leader in distributed energy storage system solutions, has an impressive profit record and is forecast to sustain.
- Sales of its flagship product, SigenStor, surged 314.3% in 2M26, and confirmed orders reaching Rmb3.8bn at end-Feb. We expect the 3-year EPS CAGR at 41.7%.
- The IPO price (HK$324.2) translates into 12x FY26F PER, cheaper than 20.8x for the HK peers. At a 20-30% discount to peers, its fair value range implies 21-39% upside.
8. Manycore Tech (68 HK) IPO: The Investment Case
- Manycore Tech (68 HK), a leading spatial design software provider, has launched an HKEx IPO to raise US$156 million.
- The software product suite centres on Kujiale, a cloud-native spatial design software targeting the Chinese market. It allows users to create 3D renderings of home interior layouts.
- The investment case is bearish due to the tepid growth, stagnant market share, early indications of customer retention issues and cash burn.
9. Sigenergy (6656 HK) IPO: Valuation Insights
- Sigenergy Technology (6656 HK) is a global leader in distributed energy storage system (DESS) solutions. It has launched an HKEx IPO to raise US$562 million.
- I previously discussed the IPO in Sigenergy IPO: The Investment Case.
- In this note, I present my forecasts and valuation. My analysis suggests that the IPO price is attractive.
10. Aequitas: Sigenergy Pre-IPO – Strong Cornerstone Book; Relatively Cheap
- Sigenergy Technology (6656 HK) is looking to raise up to US$563m in its upcoming Hong Kong IPO.
- It is a market leader in the stackable all-in-one DESS solutions market, a nascent industry.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.