
This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
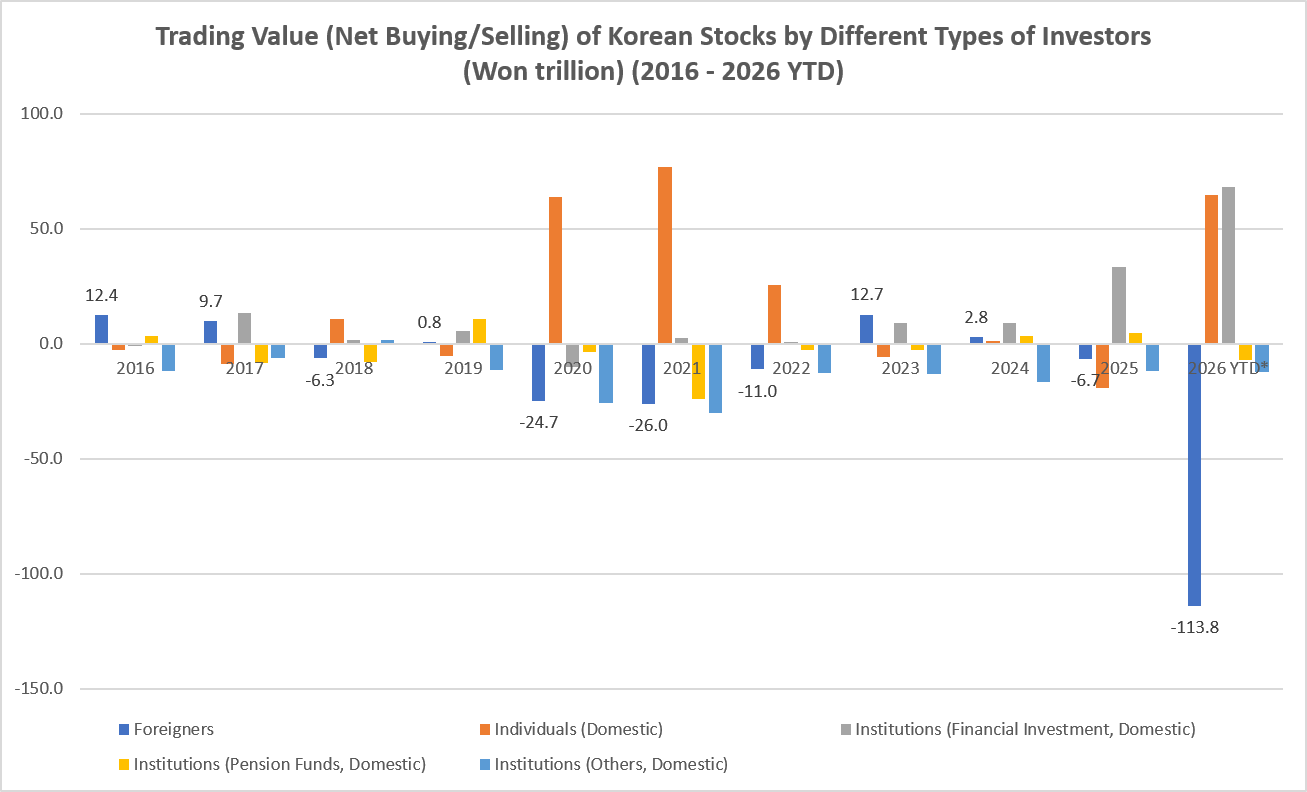
1. Massive Net Selling of Korean Stocks by Foreign Investors in 2026: Having Significant Impact on FX
- Amid record rallies in the Korean stock market and the major semiconductor stocks in particular, there has been a massive net selling of Korean stocks by foreign investors this year.
- In this insight, I discuss the following three major items including net selling/buying of Korean stocks by foreign investors, domestic institutions, and domestic retail in the past 10 years.
- I also discuss percentage change in foreign ownership among the top 20 stocks in Korea and impact of the net selling of Korean stocks by foreigners on the KRW/USD rates.
2. HEM: Jun-26 Views & Challenges
- The Strait of Hormuz remains closed, increasing the supply shock, but markets are functioning, allowing pricing to relax bullishly.
- We still expect only one hike from the ECB and BoE. A reignited conflict would help raise that response to be like 2003, not 2022.
- Dovishly biased assumptions at the BoE leave it accommodating too much excess, delivering persistently above target inflation.
3. Policymakers Tuning Lambda
- Excess inflation risks are more contained by the ceasefire, while demand destruction is becoming clearer, justifying less tightening, although pricing is largely oil-driven.
- Policymakers are increasingly referring to this trade-off, including factors that influence the optimal so-called lambda, like second-round effects and news coverage.
- Megan Greene’s use of the framework is consistent with her voting to hike in June. We still expect a majority to reach a similar conclusion for the 30 July decision.
4. EA Inflation Lifts ECB Rates
- EA inflation rose by 16bp to 3.19% in May, only 2bps above our forecast, but less painful than the consensus expected in recent weeks. National releases may have cut calls.
- Surprises were broadly small, with more downside ones averaging 0.1pp, balanced by bigger country strength. Upside was in services while downside was in energy.
- The ECB is set to demonstrate its commitment to the target with an 11 June hike. This rise provides no excuse not to, but demand destruction urges restraint beyond that.
5. HONG KONG ALPHA PORTFOLIO: (May 2026)
- The Hong Kong Alpha portfolio gained 9.7% in May, outperforming its benchmark by 10.57%. The portfolio has outperformed Hong Kong indexes by 57% to 75% since its inception in 10/2024.
- The portfolio has a Sharpe ratio of 1.37 since its inception, with a mean excess annualized return of 21% and a beta of 1.2.
- At the end of May, we sold our remaining positions in the mining and materials sectors and added positions in the power, consumer and property sectors.
6. HEW: How Soon Is Now?
- Bumper US payrolls data reiterate the burgeoning case to hike, not cut, yet Fed policy is frozen harder than the glacial ceasefire progress towards a mooted deal coming “soon”.
- June is too soon for the BoE, with the DMP revealing no urgency. Still, EA inflation is high enough for the ECB to say now is soon enough to hike.
- We expect the ECB to resist offering explicit support for tightening beyond that, while leaving the door open. US CPI data should ratchet the hawkish pressure by rising again.
7. Asian Equities: Another Month of Huge Foreign Selling; Taiwan and Thailand the Only Exceptions
- In May, foreign investors sold US$24.17bn of Asian equities, US$28.17bn in Korea, US$3.45bn in India and US$151m in Philippines. They bought US$7.5bn in Taiwan and US$104m in Thailand.
- This is the heaviest FII selling episode. In 2026 YTD, FIIs have sold US$102.2bn in Asia-6, after US$45.3bn selling in 2025. In 2022, the worst year recently, FIIs sold US$52.14bn
- Our indicator of cumulative 6-month selling as percentage of market cap indicates that Korea, India and Indonesia are clearly oversold. Taiwan recently bounced back from oversold territory.
8. THE MEGA IPOs: A Rising Tide Lifts A.I. Boats !!
- The three mega IPOs are coming in 2026. SpaceX (SPCX US) is slated to start trading this month with a valuation in the neighborhood of $2 trillion.
- Anthropic and OpenAI are the largest AI-focused firms preparing to go public soon. Anthropic’s valuation reached $965 billion in its last funding round, versus OpenAI’s $850 billion valuation.
- Going forward, AI competition will focus on efficient large-scale deployment and less on peak model intelligence. As compute costs increase, financial strength and access to infrastructure will determine future success.
9. The iEdge Singapore Next 50: From Index Creation to Investability
- The Next 50 is undergoing early-stage re-rating driven by liquidity and visibility, reflecting a market in discovery rather than maturity.
- Liquidity has improved but remains concentrated, highlighting a gap between tradability and true institutional investability across the index.
- The index is evolving into a pipeline for future blue chips, offering exposure to a meaningful slice of Singapore’s mid-cap universe with structural tailwinds from index inclusion, but where stock-specific dynamics still continue to drive returns and dispersion to date.
10. CHARTING COURSE: Japan Takes AI Trade Baton from Korea/Taiwan, and Bye, Bye Bitcoin! (June 4)
- Japan is seeing increased interest from foreign investors as the AI trade matures. Korea and Taiwan have seen investment outflows.
- Japan still faces fiscal challenges as reflected in the precarious simultaneous weakening of the JPY and JGB markets. Investors will turn their attention to those factors as AI speculation corrects.
- Bitcoin declined as Strategy (MSTR US) began selling some of its token holdings. Bitcoin faces headwinds as the cost of capital increases and alternatives gain traction.


