
Receive this weekly newsletter keeping 45k+ investors in the loop
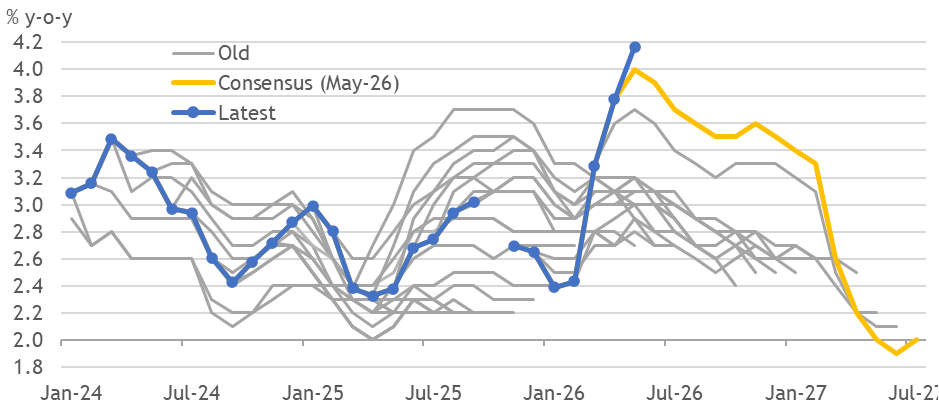
1. US: CPI Builds Bullish Case To Hike
- Another rise in US inflation to 4.2% matched final forecasts, but continued a fierce drift up from earlier expectations as the inflation shock is proving worse than feared.
- The core services impulse also rose again to hit 0.55% m-o-m (6.8% annualised) as the underlying inflation problem stops being remotely consistent with the target.
- We still don’t believe the Fed can ignore the fundamentals. Chair Warsh should talk up the bullish developments that Trump can welcome, creating space to hike if needed.
2. HEW: Long Goodbyes
- Hopes that the war-related disruption might end soon are challenged by the experience of continual delays. Meanwhile, Starmer’s long goodbye got a kick from resignations.
- Thursday’s by-election won’t yield improvement, as Burnham adds his socialist mess to longstanding inconsistencies in the UK political platform and the BoE’s policy failure.
- Nonetheless, we expect another two dissents at next week’s BoE decision to dampen overly dovish pricing. UK inflation’s rise and unemployment data are other highlights.
3. CHINA Vs U.S. TECH IPOs: WHY CHINA IS OUTPERFORMING (June 2026)
- Chinese technology IPOs continue to outperform US tech sector IPOs in 2026. China has instituted supportive policies to help its tech companies list on both the A- and H-share markets.
- The CSI Information and Technology index has outperformed Nasdaq this year, even though China’s largest chip makers have only a small fraction of the market capitalization of their global peers.
- China’s self-reliance policies, AI breakthroughs, USD weakness, and Hong Kong’s international role continue to support the strong performance of China’s tech IPOs this year.
4. ECB: Hiking With Nots
- In an outlook full of uncertainty, the ECB’s unanimous delivery of a June hike was reassuringly unsurprising. Comments primarily focused on what the decision was not.
- President Lagarde didn’t provide explicit guidance on the outlook and pushed back firmly against the notion that this was an insurance or pre-emptive move.
- This open guidance matched our view, so we still see no more ECB hikes. However, a sustained lack of gas inventory could squeeze inflation and rates up again in September.
5. CHARTING COURSE: Trump Begs Iran for Ceasefire, and S&P Needs Leap of Faith (JUNE 9)
- President Trump is struggling to maintain a ceasefire in the Middle East as he mediates between Israel and Iran. Meanwhile, the prospects for lasting peace are declining.
- The US economy is increasingly unbalanced, with government spending and AI infrastructure trying to prop up growth while consumption flatlines.
- The S&P index is increasingly dependent on a small percentage of outperformers. Without these stocks, the equal-weighted index would have declined by 16% over the last 5 years.
6. BoC Holds: Two‑Way Rate Risks
- The BoC held rates at 2.25% as expected, balancing weak growth against energy‑driven inflation and keeping a flexible stance on future rate moves.
- Future hikes hinge on energy costs feeding into core inflation, wages and expectations; otherwise, the Bank can tolerate headline CPI near 3% temporarily.
- Significant US tariffs or deeper domestic slack could trigger cuts, but markets currently price a flat path near 2.25% with only modest hikes after 2026.
7. ADL Breadth Technical Starting to Break Down for KOSPI + RIA Accounts Surpasses 4 Trillion Won
- Concerns about delays in data center construction, lack of profitability at OpenAI, increasing competition, and mega IPOs are all causing concerns about whether KOSPI’s super bull run could continue.
- Important technical (such as KOSPI’s ADL line) is also starting to break down.
- All in all, the overall risk profile of the Korean stock market (especially among the major tech stocks) have risen materially higher now as compared to 6-12 months ago.
8. US MARKET EXHAUSTION (June 26)
- The US market is showing signs of buyer exhaustion. High valuations, declining breadth, single-stock option skew, extreme momentum crowding, and lofty analyst earnings projections present risks to the bull market.
- Wall Street earnings upgrades in April were almost entirely in the tech sector and were heavily dependent on a historically high estimate of S&P operating margins.
- Rushed mega-IPOs and equity placements by hyperscalers pose another risk to the market as liquidity requirements for the tech sector grow rapidly.
9. GOLD: Pulling Back to Reload — Three Headwinds, but Direction Still Points Higher
- Gold has been underperforming the broader market (flat YTD) and plunged last week (-5.2% WoW) on blowout US jobs data, investor liquidity needs, and Iran war stalemate.
- AI equity rotation is the dominant structural headwind: tech ETFs posted their largest monthly inflow since 2024, displacing gold. Fed hike probability now ~60%; two-cut base case is dead.
- Maintain BUY; TP cut to US$4,780/oz (from US$5,400/oz). Central bank buying continues uninterrupted. US $3.4tn CBO deficit, de-dollarisation, and inflation theses narratives are all intact. Accumulate on weakness.
10. Walker’s Weekly: Dr. Jim’s Summary of Key Global Macro Developments – 5 June 2026
-
It’s the first week of the month, all eyes were on the PMIs and everything seemed pretty rosy in the garden, only Malaysia’s PMI reading was below the 50 boom-bust line. However, that could be deceiving. Take the US ISM as an example, one of the components is price paid, the prices paid index in May was 82.1 and it was slightly lower than the April reading of 84, both basically recorded high levels for prices paid in the United States.
-
Korean export numbers came in at 52.3% YoY growth in May and the April figure was up 48% YoY, these are stunning numbers for a mature economy. Nevertheless, the export price number also came in at 41% YoY growth. Export prices, over the course of the last decade, haven’t changed that dramatically from year to year but now they’re totally out of whack.
-
In Vietnam, the latest May CPI number was up 5.6% year on year, and that’s an increase in inflation from around about the 3% mark during 2024 and 2025. Currently, the upper end of the central bank’s inflation target is 4.5%, and there’s only one thing you can do when inflation’s running at 5.6%, raise interest rates.


