
Receive this weekly newsletter keeping 45k+ investors in the loop
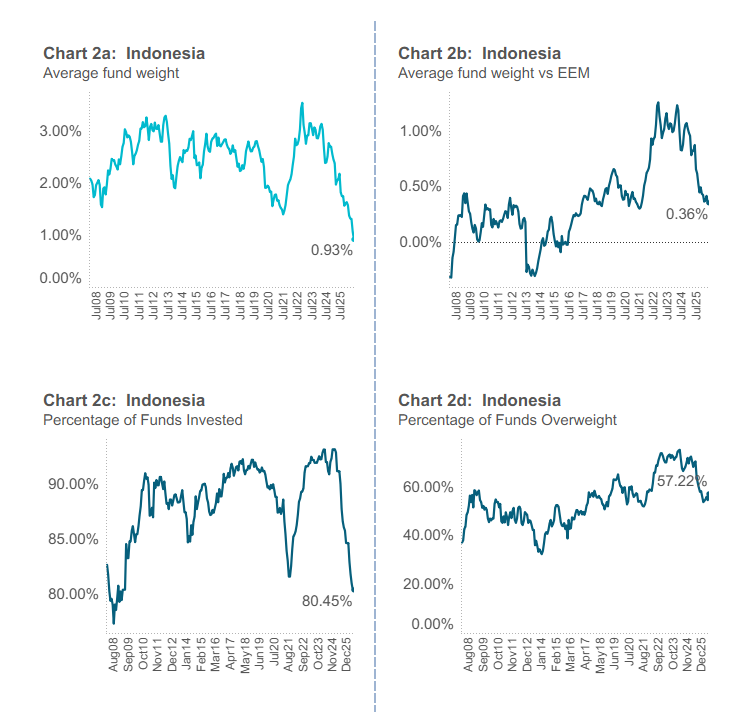
1. Indonesia: Record Lows But Not Abandoned
- Average weights have fallen to an all-time low of 0.93%, with fund participation at a 15-year low of 80.45% — yet the majority of active EM managers remain invested.
- Selling has been concentrated in domestic banks, with Bank Central Asia seeing the largest outright closures, while ASEAN allocations as a whole have dropped to their lowest level on record.
- With MSCI’s verdict on Indonesia’s EM status still pending, the country sits firmly in negative momentum territory, but for many funds, much of the pain may already be behind them.
2. HEW: Cooling Hawkish Heels
- Data releases didn’t deliver the pressure needed to prompt more rate hikes, offering enough softness to cool hawkish heels without wrinkling them into a dovish story.
- US and EA unemployment fell again, but a drop in the US labour force and disappointing payrolls offset that signal. EA inflation matched our 0.2pp below-consensus call at 2.8%.
- Next week’s calendar is thin for releases, with a potential hike from the RBNZ one of the few highlights. We also await the BoE’s FSR and stress test results.
3. Credit Accommodating Strait Shock
- A further strengthening in EA bank lending suggests monetary conditions accommodated the war shock, despite policy rate hikes, reducing concerns for demand destruction.
- UK credit was also resilient, but mortgage approvals took a hit in May despite the first fall in outstanding loan rates in four years, as households refinance at cheaper rates.
- New rates are only up slightly relative to the previous few months. Sentiment ahead of another socialist slide with the PM changing is likely discouraging decisions like moving.
4. EA: Fading Inflation And Hikes
- EA inflation’s 37bp fall to 2.8% in June undershot the consensus by 0.2pp but precisely matched our forecast. Energy prices drove the rise and the fall with their reversal.
- The consensus is embarrassingly slow to update when substantial shocks occur, but it will be forced to close some of the gap to our forecast by cutting after this release.
- With the first-round inflation shock fading and the second-round effects contained by prompt action, our conviction is rising in our call (since March) for only one ECB hike.
5. HONG KONG ALPHA PORTFOLIO: (June 2026)
- The Hong Kong Alpha portfolio beat the Hong Kong indexes in June and was flat to its benchmark with a loss of 6.98%.
- The Hong Kong market experienced heavy selling in the second half of June, as both foreign and mainland investors reduced their exposure.
- At the end of June, we sold positions in the electric utilities, technology, consumer, and property sectors. We added positions in the broker, biotech, telecom, and industrial sectors.
6. Indonesia Economics: Equities Avoid Market Downgrade, Revised Law Creates More Governance Risks
- Indonesia avoided an immediate equity market downgrade but faces a November decision where reclassification to frontier market status remains live. Market indicators suggest investors are unconvinced by the holding pattern.
- The revised financial sector law expands Bank Indonesia’s mandate with growth and employment objectives while making parliamentary oversight and recommendations binding — creating channels for political subordination of monetary policy.
- Patriot bonds” and “red-white bonds” issued by the sovereign fund are shielded from criminal prosecution, civil suits, and tax scrutiny, placing contingent government liabilities beyond any meaningful market accountability.
7. Asian Equities: Nascent Emergence of New Earnings Gainers
- The recent wobble in Asian equities has been driven by a multitude of factors including AI capex uncertainty, USD spike and concerns about US interest rate trajectory.
- Asian earnings estimates continued to rise over the past month. Estimates for Korea and Taiwan continue to increase. India now joins them, marking a departure from last two year’s trend.
- It’s still early days, but particularly encouraging about the Indian earnings revival is the breadth of participating sectors. Five Indian sectors figure in the list of top 20 earnings gainers.
8. The Heat Is On: News Flow and Sentiment in CHINA / HONG KONG (June 2026)
- The HSI broke support at the 24500 level as market breadth and momentum declined. Southbound net buying turned negative in June as the Beijing strengthened enforcement efforts on overseas investments.
- The industrials sector is the top performing sector in Hong Kong YTD, up 16%. Kingboard (148 HK) is the best performing stock in the sector since the Iran war ceasefire.
- WuXi AppTec (2359 HK) rallied along with the entire biotech sector as investors scooped up shares in the IPO of Alebund Pharmaceuticals Jiangsu (APJ HK), which doubled on its debut.
9. Consensus Holdings: The Most Widely Owned Stocks Across Active Equity Funds
- What are the most widely owned companies across active Global, EM, Asia Ex-Japan, MSCI China and China A-Share funds?
- The USA runs the Global fund universe: thirteen of the top twenty most widely held stocks are American, with Europe and EM sharing the remaining seven between them.
- South Korean and Taiwan names drawf key China holdings in terms of weight, despite being held by a similar number of funds.
10. Walker’s Weekly: Dr. Jim’s Summary of Key Global Macro Developments – 26 June 2026
-
Bank of Thailand kept interest rates unchanged at 1%, one of the few Asian central banks that hold interest rates at a very low level.
-
But given how strong the Baht has been over the course of last year, interest rate rises in Thailand would further overvalue the currency and that’s not what BoT wants to see.
-
US Fed kept interest rates steady at the moment but Chairman Warsh was talking about raising interest rates, that is because the inflation has entered the pipeline. In Wednesday’s WeeBits note we looked at import price, producer price and consumer price trends YoY, six month annualised and three month annualised. All are showing inflation is pretty severe and rising in the United States.


