This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Derivatives on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
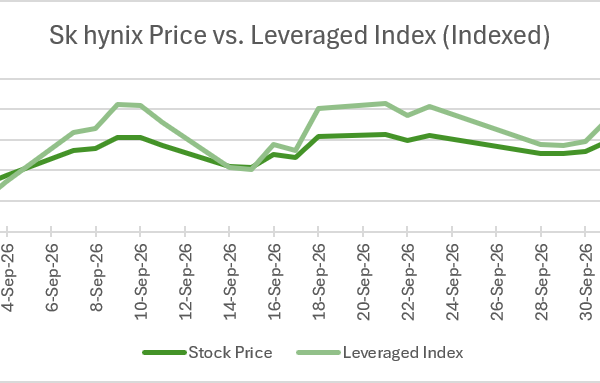
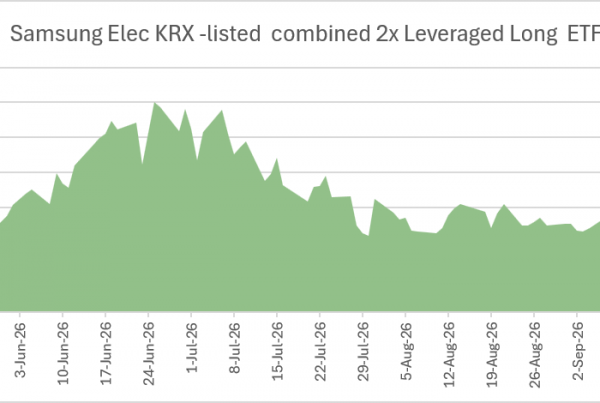
1. SK Hynix (000660 KS): 2x Leveraged ETFs Rebound, but Retail Activity Stays Subdued (9 Sep 2026)
- SK Hynix (000660 KS) gained 6.5% in September MTD, lifting the 2x Leveraged Index 12.3% and combined ETF AUM 14% to KRW 4.36tn.
- The AUM rebound was driven primarily by performance: KODEX units rose just 1%, TIGER was broadly unchanged and the five smaller products recorded reductions.
- Daily creations, redemptions and value traded remain subdued after collapsing at the end of July, coinciding with regulatory measures aimed at curbing retail activity in leveraged ETFs.
2. SK Hynix (000660 KS) Profit Targets – Tactical UPDATE
- Profit targets presented in our previous/latest insight on SK Hynix (000660 KS) were updated last Friday and are presented here, they override any previous profit target presented.
- The stock started a strong rally this week, it may continue for 3 weeks, including this week.
- The rally could reach 2,000,000 on the third week, but there is a barrier after 2,100,000 so we do not expect this rally to go higher.
3. Fast Retailing (9983 JP) Tactical Outlook: Sell Off Is Overdone, Incoming Rally
- Fast Retailing (9983 JP) earnings are one month away. The stock has corrected nearly 22% from its peak in early July. Our model just signaled a high probability LONG entry.
- The broad sentiment on the stock is bullish/outperform, based on upgraded full-year FY2026 guidance, high-margin international expansion and robust domestic same-store sales.
- There is currently no catalyst to suggest an imminent restart of the rally but our model has flagged the stock as excessively oversold: a rally could start this week.
4. WEEKLY Tactical Recap: Samsung Electronics, CATL, Tokyo Electron, Advantest Corp, Bank of China, BYD
- WEEKLY tactical global macro recap/analysis for several markets and stocks we track, grouped by sector.
- We apply our quantitative models to each instrument’s trend, to determine which stocks/markets are just starting a trend, are in the middle of it, or are about to end it.
- Most overbought: META, Bank of China, USO/Oil, China Construction Bank, Mitsubishi UFJ Financial. Most oversold: NeatEase Cloud Music, CATL, Samsung Electronics, Gold, Shin Etsu Chemical
5. China International Capital (601995 CH) Post-Merger Tactical Outlook / Risks
- As reported by Brian Freitas global index trackers will start to buy China International Capital (601995 CH) at the close on Monday September 14th.
- Tri-Party share-swap merger absorbing Dongxing Securities (601198 CH) and Cinda Securities (601059 CH) was approved by CSRC in early September 2026.
- CICC is trading at good discount value, mildly oversold, according to our model, but it could go lower before global index trackers buy and push the price higher.
6. HSI Tactical Outlook: Dive or Rally?
- The Hang Seng Index (HSI INDEX) has been rallying briefly in July, then flat/slightly down in August. September is a question mark, the index direction is unclear at the moment.
- Solid domestic macro fundamentals—notably strong mainland China trade balance data and targeted state liquidity injections— continue to drive institutional Southbound capital flows into Hong Kong-listed equities.
- This insight plots out our model support and profit targets for tactical positioning in case a breakout happens in the next 2-3 weeks.
7. Options Weekly: Put Buying Surges as Stocks Slide Into September
- Defensive options positioning dominated the week of August 31.
- Across five high-severity pulses, traders piled into protective puts on names nursing sharp price declines.
- The put/call ratio (PCR) – which measures put volume relative to call volume – spiked well above seasonal norms on multiple names, with several readings hitting 52-week extremes.