This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Derivatives on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
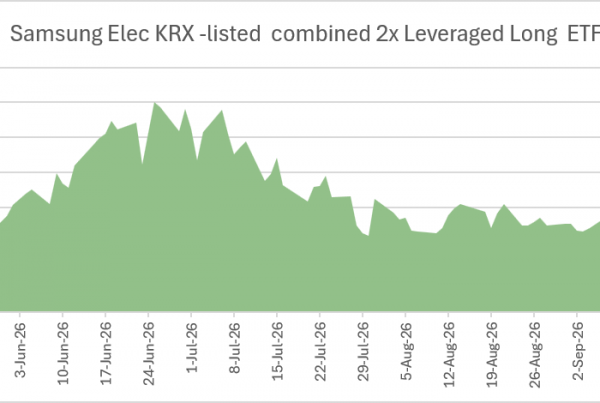
1. SK Hynix (000660 KS): Inverse 2x ETF Units Double as Long 2x ETF Outflows Persist
- SK hynix (000660 KS) gained 6.1% in September and its 2x Leveraged Index rose 9.6%, yet combined long-ETF AUM declined 2.7%.
- All seven long-leveraged ETFs recorded reductions in units outstanding, while September net outflows reached KRW 514bn and daily flow activity remained subdued.
- In contrast, the inverse ETF’s units outstanding more than doubled and its market capitalisation increased 68%, despite the product losing 17.0% during September.
2. Suzuki Motor (7269 JP) Tactical Outlook: A Good Time to Buy (Asymmetric High Prob Entry)
- Suzuki Motor (7269 JP) has been selling off for the past 5 weeks, showing an attractive inexpensive valuation.
- The stock looks reasonably priced on cash flow, displays strong operational cash generation and balance sheet strength (driven by hybrid and small-car dominance in emerging markets).
- Our model analysis shows the stock sell-off right now is probably exhausted, so the timing for positioning is quite good, at the moment.
3. Samsung Electronics (005930 KS) Tactical Outlook Ahead of Q3 Earnings Release
- Most analysts expect Samsung Electronics (005930 KS) to post its fourth consecutive quarter of record operating profit, driven by ongoing AI infrastructure demand and tight memory suppliesA
- The LSEG SmartEstimate points to a massive year-over-year jump in earnings—up from 12.17 trillion won a year earlier—with some brokerage forecasts hovering around 105 trillion won in total operating profit.
- Near-Term flows around the October 8 print should be volatile owing to the convergence of preliminary guidance, semiconductor ETF rebalancing, options expiry, and the conclusion of Samsung’s share buyback program.
4. HKEX (388 HK) Tactical Outlook: Potential Rally
- Hong Kong Exchanges and Clearing (388 HK) has corrected 11% in the last few weeks, but its most significant last peak was in August 2025.
- The main hypothesis of this insight is that the stock may offer a short-term asymmetric LONG opportunity, to profit from a counter rally.
- Analysis conducted with out quantitative model show that last week’s correction was shallow so the stock could go lower, but it should be bottoming soon. Broader consensus: strong buy.
5. WEEKLY Tactical Recap | Asymmetric Setup: CATL, Advantest Corp, Tokyo Electron, Zijin Mining, NIFTY
- WEEKLY tactical global macro recap/analysis for several markets and stocks we track, grouped by sector.
- We apply our quantitative models to each instrument’s trend, to determine which stocks/markets are just starting a trend, are in the middle of it, or are about to end it.
- Most overbought: Nikkei 225, Hanwha Solutions (009830 KS), Tokyo Electron (8035 JP), Advantest Corp (6857 JP) Most oversold: NIFTY, CATL (300750 CH), GLD, Zijin Mining, Nippon Steel Corporation (5401 JP)
6. Samvardhana Motherson: Building a Broader Aerospace and Defence Systems!
- Motherson has agreed to acquire 50.1% of Rotary Connectors. This transaction adds a critical interconnect component to the group’s aerospace and defence Electrical Wiring Interconnect System capability.
- Aerospace revenue has grown from INR 245 crore in FY23 to INR 2,447 crore in FY26, while the order book reached USD 1.6 billion at FY26-end.
- FY26 aerospace EBITDA margin was only about 8.3%, well below the smaller pre-acquisition FY24-base. The next leg depends on mix, utilisation, integration and return on capital, not revenue growth alone.
7. Let’s Make a Case for a BYD (1211 HK) Rally (Tactical View)
- Our quantitative models last week indicated BYD Company (1211 HK) had reached oversold territory. The stock could rally back towards 90 from here, and possibly change long-term trend.
- Valuation multiples have de-rated significantly, pricing in worst-case domestic price-war scenarios while underappreciating higher-margin overseas export growth and AI-driven smart driving adoption.
- A tactical LONG position from current price levels, targeting a mean-reversion move toward 90-100 (near our model + consensus target) could offer more reward potential than downside risk (good asymmetry).