
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Intel CEO Heads To DC To Save His Job As Former CEO Calls His Leading Edge Strategy A Joke
- Intel CEO Lip Bu Tan is reportedly headed to Washington today to meet with the US Administration and clear up any misunderstandings about his past investments in China etc.
- Meanwhile, former CEO Craig Barrett published his third opinion piece about Intel’s future and calls LBT’s strategy of not investing further in 14A without customer support a joke
- It’s challenging to deal with the US Administration from a position of strength. It’s a whole different ball game when both the CEO & the company are in crisis mode…
2. Taiwan Dual-Listings Monitor: TSMC Spread Remains Extreme; UMC ADR Short Interest Falling
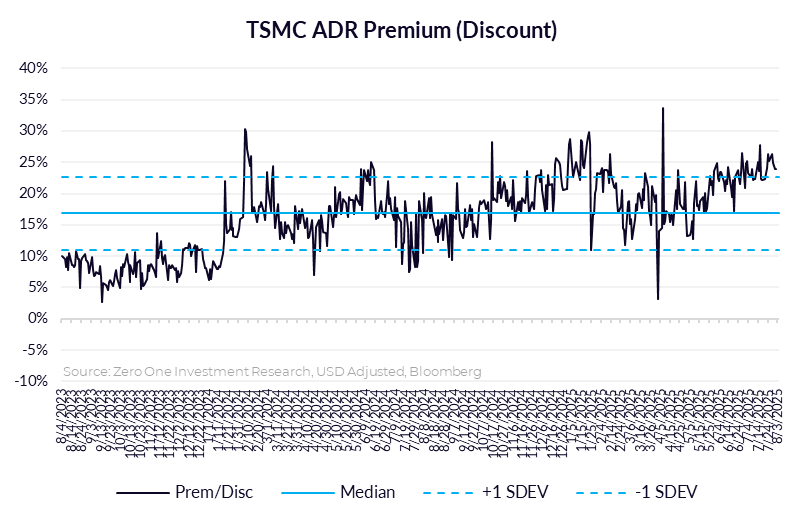
- TSMC: +22.8% Premium; ADR Spread Remains at Historically Extreme Levels
- UMC: -0.8% Discount; Wait for More Extreme Levels; Short Interest in ADRs Falling
- ASE: -0.1% Discount; Continued Opportunity to Go Long the ADR Spread
3. Taiwan Tech Weekly: Foxconn US$1bn USA Robotics Push; Samsung Doubles Down on US Fabs; Intel Crisis
- Foxconn Tech invests US$1bn in U.S. robotics, AI, and smart manufacturing over 10 years, expanding into service robotics via RoboTemi stake.
- Samsung to surpass US$50bn in U.S. chip investments, adding US$7bn for advanced packaging to compete with TSMC and capture AI/HPC integration opportunities.
- Intel faces leadership crisis as CEO Lip Bu Tan’s strategy is criticized; U.S. policy and competitive pressures may accelerate market gains for TSMC and Samsung.
4. TSMC (2330.TT; TSM.US): Board Meeting Resolutions; 2nm Technology Information Leakage Issue.
- Taiwan Semiconductor (TSMC) – ADR (TSM US) disclosed Board of Directors meeting resolutions today.
- Taiwan Semiconductor (TSMC) – ADR (TSM US) 2nm technology manufacturing information leakage issue.
- Currently, only TSMC, Samsung, and Intel have achieved trial production at the 2nm node.
5. Apple. A Master Class On How To Win Friends & Influence People
- Apple CEO Tim Cook visited the White House announcing an additional $100 billion investment in the US over the next four years, on top of the $500 billion already committed.
- He launched the American Manufacturing Program with nine initial members seven of which are already long terms partners and two of which have no direct relationship with Apple at all
- Samsung with its image sensor deal (presumably) and MP Materials with its rare earth magnets deal are two clear winners from the Apple announcement. Overall, successful mission by Mr. Cook.
6. Nanya July Revenue Soars 31% MoM As Micron Revises Current Quarter Guide Up >5%
- Nanya last week announced that revenues for the month of July amounted to NT$5.3 billion, an increase of 31.4% MoM, and an increase of 95% YoY,
- Micron this week revised upwards its guidance for the current quarter with a roughly $500 million increase in revenue, attributable primarily price increases for DDR5
- Customisation of Micron’s HBM4E base logic die is transforming their key customer relationships from commodity vendor to strategic ASIC design-like partner. That’s good for Micron…
7. AMAT Q325. Tanking On Tepid Leading Edge Outlook & China Woes
- AMAT reported FY Q325 revenues of $7.3 billion, up 3% QoQ, up 8% YoY and ~$100 million above the midpoint of the guided range
- Looking ahead, AMAT forecasted current quarter revenues of $6.7 billion at the midpoint, down 8.3% QoQ and down 4.9% YoY
- The China slump was not unexpected, but the leading edge logic drop was definitely a surprise
8. PC Monitor: ASUS’s Gaming & Commercial Strength Signal AI PC Cycle; Positive Read for Dell, HP
- ASUS experienced record 2Q25 revenue driven by 30–40% YoY growth in gaming and commercial PCs, supported by a new GPU sales strength and enterprise market expansion.
- AI servers held mid-teens revenue share for ASUS; margin pressure from tariffs and FX expected to ease after 3Q.
- Strong gaming and commercial PC momentum could signal PC upgrade activity in response to AI PCs, offering positive read-through for Dell and HPQ’s upcoming results end-August.
9. Taiwan Dual-Listings Monitor: TSMC ADR Premium Sees Small Breakdown; ASE Discount Long Opportunity
- TSMC: +21.5% Premium; Historically High Short Interest in the Local Begins to Drop?
- ASE: -0.4% Discount; Opportunity to Go Long the ADR Premium
- UMC: +0.2% Premium; Wait for More Extreme Levels Before Going Long or Short the Spread
10. Himax (HIMX US) – Share Drop: Near-Term Weakness Offset by Structural Automotive & AI Growth Drivers
- 2Q25 beat on margins, in-line on profit; automotive and non-driver ICs resilient despite macro headwinds; guidance points to weaker 3Q25 from seasonal bonus costs and softer demand.
- Automotive, OLED, WiseEye AI, and WLO/CPO remain multi-year growth drivers; CPO mass production targeted for 2026 with early-stage annualized revenue potential above US$100m.
- Shares likely fell on weak near-term outlook, but structural leadership in automotive display ICs, AI sensing, and optical technologies underpins long-term growth runway through 2028.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Spread Short Setup, ASE ADR at Historically Rare Discount
- TSMC: +23.9% Premium; Continued Opportunity to Short the ADR Premium
- UMC: -0.4% Discount; Wait for More Extreme Levels Before Going Long or Short
- ASE: -1.5% Discount; Historically Rare Discount Presents Opportunity to Long the ADR Spread
2. TechChain Insights: Taiwan’s Battery Cell Moment? USA & EU Supply Chain Under Strategic Pressure
- Battery cells are the new chokepoint in the global clean energy supply chain, with China still controlling 75%+ of global capacity and exporting under increasingly restrictive terms.
- Taiwan is emerging as a high-trust, high-precision hub for advanced cell manufacturing, applying its semiconductor model to batteries.
- With pouch cells gaining traction across drones, robotics, and compact mobility, Taiwan’s lab-to-fab advantage positions it as a future anchor of the U.S. and European energy ecosystems.
3. Intel. Was Tesla’s Deal With Samsung The Death Knell For IFS?
- Tesla & Samsung just inked an eight year, $16.5 billion foundry deal set to run from July 24, 2025 through December 31, 2033.
- Had Intel snagged this deal, it would have been a lifesaver for the company. Not getting it likely triggered the updated “Risk Factors” section in their latest 10K.
- This isn’t Intel playing politics, there’s no point. It’s LBT laying it on the line for investors. Continued investment in 14A is no longer a given. It’s that simple…
4. Taiwan Tech Weekly: TSMC’s Arizona Surprise – 2nm by 2026?; Signs of Hyperscaler Growth Acceleration
- U.S. 2nm Production May Begin Sooner Than Expected — Is TSMC Responding to Unprecedented N2 Demand?
- Hyperscalers 2Q25: Revenue Growth Accelerates, Cloud Revenues Accelerate, Capex Higher
- TechChain Insights: Taiwan’s Battery Cell Moment? USA & EU Supply Chain Under Strategic Pressure
5. Intel. Crisis Mode All Over Again
- President Trump wants Intel CEO Lip Bu Tan to resign immediately because he claims that he is “highly CONFLICTED”
- The President’s concerns likely relate to a recent DoJ case against Cadence as well an investigation by the Select Committee on the CCP into Walden International’s Chinese investments
- That both these topics weren’t comprehensively addressed and mitigated prior to Mr. Tan’s appointment beggars belief. Where was the due diligence Mr. Yeary?
6. Intel (INTC.US): Changing the CEO Could Save This Company? Probably the Wrong Direction.
- US President Trump urged Intel Corp (INTC US) yesterday to replace its current CEO, Mr. Lip-Bu Tan.
- We believe Intel Foundry Services (IFS) could be a highly challenging — or even misguided — strategy
- Intel Corp’s share price has declined about 23% since Mr. Lip-Pu Tan took office.
7. SMIC (981.HK): 2Q25 Results in Line; 3Q25 May Offer Mild Upside, but GM Is Expected to Be Flattish.
- Semiconductor Manufacturing International Corp (SMIC) (981 HK) reported in-line 2Q25 results, while its 3Q25 guidance appears somewhat cautious, particularly in terms of gross margin.
- The Americas continued to contribute a low-teens percentage to revenue, accounting for 12.9% in 2Q25, while China and Eurasia comprised the remaining majority.
- Our top questions for the upcoming SMIC’s 3Q25 earnings conference call.
8. Novatek (3034.TT): 3Q25 Outlook Is Expected; Weaker Demand from China Due to Subsidy Tapering.
- 3Q25 Outlook & Guidance- Revenue: NT$23.7–24.7bn( down 9.5~5.7% QoQ); Gross Margin: 34–37%; Operating Margin: 15–18%; USD/TWD Assumption: 29.5
- Weaker demand from China due to subsidy tapering in 3Q25, but seasonal stocking in non-China markets.
- 2025 foldable penetration estimated at ~1.6% (~19mn units); Large foldables: higher internal display resolution and ASP; OLED TDDI advantage: fewer components, more space-efficient, enabling thinner phones.
9. Novatek (3034.TT): FX Impact Persists; 3Q25 May Be a Down Quarter.
- We expect Novatek Microelectronics Corp (3034 TT)‘s 3Q25 might be decline 5-10% QoQ, reflecting 2H25 US tariffs impacts and Chinese opponent’s competition.
- The Foldable handset may be indicated a new era to come, and we believe Novatek Microelectronics Corp (3034 TT) shall be one of the DDIC winners.
- The stock price of Novatek Microelectronics Corp (3034 TT) is long staying with NT$450~650 since the beginning of 2024, and the current price is at the relative low point.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Intel (INTC.US): 18A May Have Been Too Rushed; Now All Hopes Rest on 14A.
- On July 24, chip giant Intel announced that its latest 18A advanced process is progressing smoothly. However, the next-generation 14A process will be developed “based on confirmed customer commitments.”
- Apple (AAPL US) adopt Intel’s 14A process for its future M-series chips, while NVIDIA Corp (NVDA US) is expected to use the same process for its entry-level gaming GPUs.
- U.S. President Trump is imposing tariffs on countries around the world, which is indirectly pressuring some manufacturers to accelerate the establishment of U.S.-based production facilities.
2. Taiwan Dual-Listings Monitor: TSMC ADR Premium Remaining Unusually High; UMC & ASE Headroom Changes
- TSMC: +26.3% Premium; Opportunity to Go Short the ADR Premium
- UMC: -1.2% Discount; ADR Headroom Falls Yet Again by a Significant Amount
- ASE: +0.7% Premium; Opportunity to Go Long the ADR Premium — ADR Headroom Has First Change in a Long Time
3. Microsoft FYQ425. Who Says Elephants Can’t Dance?
- Q425 revenues of $76.4 billion, up 5.5% QoQ, 18% YoY and handily beating guidance of $73.8 billion.
- Azure surpassed $75 billion in revenue in FY25, up 34% YoY, driven by growth across all workloads.
- Contracted backlog grew by $53 billion QoQ to reach $368 billion. Wow!
4. Yageo’s AI-Driven Momentum and Strategic Expansion Through Shibaura Acquisition
- 2Q25 Results Summary: Reports Broad-Based Growth with Specialty Margin Strength
- Yageo Inventory Recovery Marks a Demand-Led Inflection for Hardware Components
- Update on Shibaura Acquisition: Still on Track, Strategic Synergy in Focus
5. Taiwan Tech Weekly: Mediatek Reportedly Bests Broadcom for Meta Custom Chip Win; Semi Key Indicators
- MediaTek Reportedly Wins Meta’s 2nm AI Chip Order Over Broadcom
- Memory Monitor: SK Hynix Vs. Micron — Different Speeds & Focus, Same Structural Shift
- Semi Key Indicators Q2 2025: PC, Smartphone Unit Shipments, Global Semi & WFE Sales All Looking Good
6. Intel Q225. GM Obfuscation, Red Flags & 14A Now Officially A Risk Factor
- Intel reported Q225 revenues of $12.9 billion, up $200 million QoQ, flat YoY but $1.1 billion above the guided midpoint. After that revenue beat, things went downhill from there.
- CEO Lip Bu Tan said he will review and approve all future company product designs prior to tape out. Sounds like a vote of no confidence in the design team.
- Intel’s 10 Q now lists the possibility of pausing or abandoning 14A as a risk factor with doomsday details about the implications for the company
7. ASEH (3711.TT): FX Impact; AI Gains Attention; 3Q25 Grows, but GM and OPM Decline QoQ.
- 3Q25 guidance (Assuming US$1 = NT$29.2.): Consolidated US$ revenue: +12-14% QoQ; NT$ revenue: +6-8% QoQ; Gross margin: -1 to -1.2ppts QoQ; OPM: -0.1 to -0.3ppts QoQ.
- Still keep US$1bn advanced packaging guidance despite AI boom (TSMC revised up).
- Long-Term success definition for ASE: Transition from OSAT model to foundry-aligned scale.
8. Vanguard (5347.TT): FX Impact; Mild Recovery, Slightly Better Than 3Q25 Preview.
- 3Q25 Outlook (based on USD/TWD = 28.7): Wafer Shipments: +7–9% QoQ; ASP: +1–3% QoQ; Gross Margin: 25–27%.
- Revenue Mix (Industrial, Auto, 3C): Industrial + Automotive: 40%+ (majority industrial; automotive in teens) ; Communication & Computing: 20%+ each ; Consumer: 10%+.
- 2025 Dividend Policy : Will maintains NT$4.5 per share dividend.
9. Hon Hai(2317.TT): Form Strategic Alliance Via Share Swap with TECO (1504) For Global AI Data Center
- Hon Hai Precision Industry (2317 TT) and Teco Electric & Machinery (1504 TT) held a joint press conference this afternoon to announce the formation of alliance through a share swap.
- Teco (1504) TT and Hon Hai (2317 TT) stated their target markets extend beyond Taiwan and Asia, to include substantial business opportunities in the U.S. and the Middle East.
- Foxconn Chairman Mr. Young Liu also noted that as AI data centers scale up rapidly and demand surges, modular design is increasingly favored.
10. Tokyo Electron (8035 JP): Why the Big Downward Revision?
- Tokyo Electron’s share price dropped 18% on Friday following the announcement of weak Q1 results and a huge downward revision to H2 FY Mar-26 guidance.
- Push-Outs and/or cancellations of orders due to the uncertainty caused by President Trump apparently caught managment by surprise. Costs also rising as management ramps up capex and R&D.
- Impact of Trump’s yet-to-be-announced tariffs on semiconductors is still unknown, but 15% base rate on Japan already a negative.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Tech Weekly: TSMC Preparing 5x 2nm Ramp into 2027; Altman ‘Jokes’ About Buying 100x More GPUs
- TSMC’s Most Advanced Node — 5x Growth to 200K Wafers a Month? Upcoming 2nm Node Capacity Ramp Could Be Much Bigger Than Many Think
- OpenAI’s Sam Altman ‘Jokes’ About Owning US$3 Trillion Worth of GPUs One Day…
- AI PC Delay — Nvidia-MediaTek Push AI PC Chip Launch to 2026
2. Semi Key Indicators Q2 2025: PC, Smartphone Unit Shipments, Global Semi & WFE Sales All Looking Good
- According to Gartner, PC unit shipments increased 4.1% YoY in Q225 to reach 63.2 million
- According to IDC, smartphone unit shipments grew 1% YoY in the second quarter, reaching 295.2 million units
- Global semi sales were up 20% YoY in May while SEMI now expects YoY growth in WFE spending of 7.5% in 2025 and a further 10% in 2026

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. TSMC Q225. Surfing The AI Tidal Wave With Style
- TSMC reported Q225 revenues of $30.1 billion, up 44% YoY, up 17.8% QoQ and handily beating the high end of the $29.2 billion guidance.
- Full year 2025 guidance raised to 30% YoY growth, and that may still not be enough
- Resumption of H20 sales to China not yet baked into forecast, an army of ex Intel employees coming on the job market & potential Fx reversal are all possible tailwinds
2. TSMC 2Q25 Takeways: Undervalued Op Leverage and Capacity Strain Setting Up 2026 N2 Growth Suprise
- TSMC Beats, Raises, and Confirms AI Ramp Is Real, Despite FX Drag
- Conclusion — Maintain Structural Long View, 2026 Growth Likely Underappreciated
- TSMC ADR Premium Rebounds to 23.6% — US Investor Positioning Skewed Toward TSMC’s Unique AI Exposure
3. TSMC (2330.TT; TSM.US): FX Could Make an Impact; Full Year USD Revenue Raised to ~30% YoY.
- 3Q25 Guidance: Revenue: US$31.8–33.0 billion (approx. 8% QoQ growth); Gross Margin: 55.5–57.5%; Operating Margin: 45.5–47.5%.
- Despite FX headwinds, TSMC aims to maintain gross margin ≥ 53%
- Driven by strong demand in AI (including sovereign AI) and HPC; Full-year USD revenue growth outlook raised to ~30% YoY.
4. Taiwan Dual-Listings Monitor: TSMC Results Ahead; ASE Historically Rare Discount
- TSMC: +20.6% Premium; FY2Q25 Results This Week a Key Catalyst
- UMC: 0.0% Premium (Parity); Wait for More Extreme Levels Before Going Long or Short
- ASE: -0.8% Discount; Historically Rare Discount, Long the ADR Spread
5. ASML Q225 Earnings. Solid Results, Forecasting 15% Growth In 2025, Down 7% In Pre Market. But Why?
- ASML today reported second quarter revenues of €7.7 billion, bang at the top of the guided range, flat QoQ and up 23% YoY
- Guided 2025 at 15% growth (~€35 billion), a big step up in confidence from the €30-€35 billion range given last quarter
- Comments regarding uncertainty about 2026 outlook and tariff impacts likely led to the >7% sell off currently happening in pre-market trading.
6. Taiwan Tech Weekly: Intel Tapes Out New Chips at TSMC – What It Means; PC Demand Growth in Focus
- Intel Tapes Out New PC Chips on TSMC 2nm — Dual-Node Nova Lake Strategy Shows Dependence on TSMC… and Value of UMC for INTC in the Long-Term
- DRAM Memory Outlook — Nanya Results See Non-AI DRAM Demand Rebound; DDR4 Shortage Tightens, Expects Continued Strength in 2H25
- PC 2Q25: 6-7% Unit Growth YoY Is Pretty Good. 2025 Looks like a 5-6% Growth Year
7. Intel Layoffs Finally Kick Off With A Chaotic Start In Oregon
- Despite initially WARNing of 529 job cuts in Oregon, the actual number turned out to be 2,392
- Only 9% of the Oregon cuts are in management positions
- Huge cuts in technical employees across the board with a total of thirty Principal Engineers losing their jobs in Oregon alone.
8. TechChain Insights: Kinik – The Hidden Enabler Behind TSMC’s Sub-2nm Push
- We Engaged with Kinik Recently to Get Insight on Activity Strength for TSMC’s Expansion into Nodes 2nm and Below
- Diamond Tooling: Quietly Powering Advanced Logic; Kinik Recently Running at Max Capacity for Key DBU Business Segment… also at 100% for SBU Segment
- Takeaways — Kinik as a Concentrated Play on Advanced Node Transitions… Also, We Believe Signs Remain Positive for TSMC’s Recent Activity Momentum
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. TSMC (2330.TT; TSM.US): The 3Q25 Outlook Suggests Modest Growth, but FX Could Pose a Headwind.
- Looking ahead to the third quarter, we estimate that TSMC’s revenue in U.S. dollars could grow by approximately 5–10% quarter-over-quarter.
- Buoyed by the AI boom and the recent increase in U.S. semiconductor investment tax credits to 35%, TSMC will achieve its full-year target of 25% growth in U.S. dollar revenue.
- In the second half of the year, as multiple brands launch flagship smartphone chips, TSMC’s N3P process is fully prepared for volume production.
2. Taiwan Dual-Listings Monitor: Spreads Near Record Highs After U.S. Market Holiday
- TSMC: +26.3% Premium; Near Record High After U.S. 4th of July Holiday
- UMC: +4.7% Premium; One of the Highest Levels in History — Short
- ASE: +4.6% Premium; Wait for More Extreme Level Before Going Long or Short
3. TSMC June Revenue Down 17.7% Mom. What Gives?
- TSMC today reported June 2025 revenues of NT$263.71 billion, a decrease of 17.7 % MoM but an increase of 26.9% YoY
- At the guided exchange rate of 32.5, TSMC’s Q225 revenue amounts to $28.7 billion, up 12.2% QoQ and up 37.6% YoY, but roughly $100 million below the guided midpoint
- However, if we take today’s exchange rate of 29.24, Q225 revenue comes in at $31.9 billion, way above the guide. Take your pick & let’s see this day next week
4. Taiwan Tech Weekly: US Targets Malaysia & Thailand; Wind Power Fuels Taiwan’s AI Infrastructure Push
- US Eyes New AI Chip Restrictions on Malaysia and Thailand
- Chip and AI Boom Driving Taiwan’s Offshore Wind Expansion — Local Stocks to Watch
- China Set to Become World’s Largest Semiconductor Foundry Hub by 2030 — But One Needs to Consider Leading Edge Capacity vs. Mature Capacity
5. TechChain Insights: Zhen Ding – How Next Generation PCBs/Substrates Will Be Critical for AI Devices
- Zhen Ding Technology Holding (4958 TT) is leveraging its full-stack PCB and IC substrate portfolio to position itself as a critical enabler of AI hardware across cloud, channel, and edge applications.
- AI-Linked hardware is expected to account for over 70% of Zhen Ding’s revenue in 2025, up sharply from 45% in 2024 and just 8% in 2023.
- Zhen Ding shares remain substantially below their 52-week highs; we see the company well-placed in terms of long-term drivers. Well placed for an upcoming AI robotics boom.
6. Cerabyte. Forever Data Storage At A Fraction Of Current Costs?
- Cerabyte has a stated vision of achieving $1 per petabyte per month, a cost reduction of 1000x within the next two decades. That’s a bold vision.
- Magnetic tape storage continues to play a crucial role in data centers and its technology continues to advance with the latest LTO-10 cassette announced by Fujifilm in June 2025
- Microsoft’s Project Silica, launched in 2019, appears to take a very similar approach albeit there are as yet no stated plans for commercialisation.
7. Nidec (6594 JP): New Factory in China
- Nidec has opened a new motor factory in China to meet an anticipated increase in demand for home appliances.
- Sensing an opportunity for growth, management is already considering the construction of a second factory.
- This fits with the Chinese government’s efforts to promote domestic demand and with Nidec’s need for a new growth driver in China.
8. MediaTek (2454.TT): 3Q25 Outlook Is Expected to Decline by Approximately 0–6%.
- For Mediatek Inc (2454 TT)’s 3Q25 outlook, its revenue is expected to decline by approximately 0–6% quarter-over-quarter, reflecting a relative low seasonal factors and order adjustments.
- Regarding Mediatek Inc (2454 TT)’s partnership with Alphabet (GOOGL US), the TPU v7e is expected to begin tape-out in September 2025.
- Based on current project developments using TSMC’s 2nm process, MediaTek is highly likely to co-develop the next-generation MTIA v4 ASIC with Meta (META US).
This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Intel (INTC.US): Abandon Promoting 18A to Fully Focus on 14A
- Even if Intel Corp (INTC US) ceases marketing 18A to new customers, the company will still fulfill existing foundry commitments.
- In response to the 18A dilemma, Intel’s initial solution is to redirect resources toward the development of 14A, a next-generation process where Intel hopes to gain an edge over TSMC.
- In addition to the strategic realignment of the foundry business, Tan’s broader efforts include refreshing Intel’s leadership team.
2. Taiwan Dual-Listings Monitor: TSMC High Premium Persisting, Record Short Interest in Local
- TSMC: +23.4% Premium; Consider Shorting ADR Spread at Current Level; Record Short Interest in Local
- UMC: +1.1% Premium; Wait for More Extreme Premium to Short
- ASE: +2.9% Premium; Near Level to Go Long the ADR Spread
3. TSMC (2330.TT; TSM.US): Halts GaN Production at Fab 5, Shifting to Advanced Packaging.
- Taiwan Semiconductor (TSMC) – ADR (TSM US) is planning to scale back its presence in the gallium nitride (GaN) market to focus on high-growth areas.
- To meet customer demand, Taiwan Semiconductor (TSMC) – ADR (TSM US) has recently been reallocating resources away from mature process nodes.
- We estimate that Navitas Semiconductor Corp (NVTS US) alone consumes over half of TSMC’s GaN capacity each month, making it TSMC’s largest GaN customer.
4. Kawasaki Heavy Industries (7012 JP): Sell into Strength
- KHI has retreated 12% from its June 30 high, but is still 69% above its April low, despite guiding for a decline in orders and weak profits in FY Mar-26.
- Orders from Japan’s Ministry of Defense are forecast to drop from ¥772.3 billion to ¥400 billion this fiscal year, while the overall profit of the Aerospace division drops 14%.
- The potential impact of U.S. tariffs on Power Sports & Engines is not factored into guidance, offsetting what otherwise seem to be conservative assumptions.
5. Our Thesis: Intel Should Take a Stake in UMC — New Signals Reinforce the Case
- UMC’s renewed push into 6nm, paired with Intel’s strategic overhaul under new CEO Lip-Bu Tan, raises the likelihood of an Intel equity stake in UMC.
- We maintain our Structural Long view on UMC and reiterate our original thesis: a deeper partnership via a stake from Intel would be transformative.
- At 12.5x trailing PER with a net cash position, UMC remains attractively valued as a strategic asset — especially if can essentially have its own ‘Group’ advanced fabs with Intel.
6. Meta Superintelligence Labs. Genius Move Or Desperate Gamble?
- On Monday, June 30, Meta CEO Mark Zuckerberg announced the creation of Meta Superintelligence Labs, staffing it with a host of leading researchers from the likes of OpenAI and Google
- With astronomical hiring bonuses and lucrative compensation packages, this newly assembled team will struggle to gel and likely drive an exodus of existing Meta AI employees elsewhere
- Yann LeCun is sidelined in the MSL memo. He believes LLMs are not the way to achieve human-level AI. It appears that Mark Zuckerberg disagrees. Let’s see…
7. Taiwan Tech Weekly: Has Samsung Given Up Chasing TSMC?; Xiaomi Tesla-Killer EV Using Key TSMC Chips
- Samsung Said to Have Give Up Chasing TSMC at the Leading Edge of Chip Manufacturing
- Xiaomi’s Tesla-Killer YU7 EV Surges in Orders — TSMC Rides the Wave as Core Chip Supplier
- TSMC (2330.TT; TSM.US): Will Rapidus Threaten TSMC’s 2nm Market? We Think It’s Too Early to Say (II)
8. TechChain Insights: Chenbro Micom — How Server Racks Are Evolving With Nvidia’s B-Series & ASICs
- Key Player In Roll-Out of Nvidia’s New Blackwell Solutions. Having followed Chenbro closely over the past year, we’ve seen it steadily increase its exposure to the AI infrastructure cycle.
- Nvidia B200 and B300 Server Builds Are Ramping. Chenbro sees projects based on Nvidia’s B200 and B300 GPUs actively progressing, with B300 projects initiated and shipments starting in 2H25.
- Non-Nvidia ASICs also growing as a contributor. The company also sees AI systems based on custom ASICs as a growing contributor to the business.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Apple Intelligence. What’s Another Year?
- Apple failed to deliver on the highly anticipated Siri makeover, noting that it didn’t meet their quality standards and effectively pushing it out for another full year
- Internal rivalries, divided opinions on the direction AI should take, organizational restructuring, unwillingness to do meaningful acquisitions would all appear to be contributing to Apple’s AI woes
- Apple’s peers are advancing their AI ambitions at warp speed, investing heavily, taking bold risks and mostly delivering on their promises. Apple is the polar opposite. What’s another year? Failure.
2. Micron Q325 Earnings: NAND’s Surprising Rebound While HBM Already @$6 Billion Annual Run Rate.
- Q325 revenues of $9.3 billion, up 15% QoQ and up 37% YoY and $500 million above the guided midpoint. This represented a new quarterly revenue record for the company
- Micron forecasted current quarter revenues of $10.7 billion, up 15% QoQ, with gross margin of 42%, up 300 basis points sequentially
- HBM negotiations for 2026 supply & pricing still ongoing. Could Micron be holding out for a better deal?
3. TSMC (2330.TT; TSM.US): Will Rapidus Threaten TSMC’s 2nm Market? We Think It’s Too Early to Say (II)
- Japan’s Fujitsu Ltd (6702 JP) is currently developing a 2nm CPU named “MONAKA” (link). The CPU is planned to be manufactured by Taiwan Semiconductor (TSMC) – ADR (TSM US).
- Rapidus has to deal with high technical barriers, tight timelines, heavy R&D costs, market and profitability challenges.
- Talent shortage in Japan: A lingering pain for the Semiconductor industry
4. Coatue Doubles Down On An AI Supercycle @ EMW 2025
- Cloud 2025 CapEx consensus increased 70% from January 2024 to the present day $365 billion
- Google page views declined 8% since the launch of ChatGPT
- Apart from the Mag7, Coatue is heavily focusing investment on companies involved in AI-required power delivery, AI software and AI semiconductors
5. Taiwan Dual-Listings Monitor: TSMC Historically High Spread Persisting; UMC High Premium
- TSMC: +22.1% Premium; Consider Shorting ADR Spread at Current Level
- UMC: +3.5% Premium; Extreme vs. History, Consider Shorting ADR Spread
- ASE: +2.4% Premium; Approaching Level to Long the ADR Spread
6. Memory Monitor: Micron Reinforces AI Memory Tailwinds, But Broader Supply Chain Recovery Gradual
- Micron Results Beat Across the Board, AI Product Mix Drives Gross Margin Upside
- No Evidence Yet of Hyperscaler Pullback, But No Significant Increase in Outlook Either
- Conclusion: AI-Driven Strength Continues, But Divergence Across the Memory Supply Chain Persists
7. Taiwan Tech Weekly: 1.4nm Slips from Samsung’s Grip? Why Intel May Be TSMCs Sole Next Gen Competitor
- Samsung’s 1.4nm Technology Delay Highlights Potential That Intel Could End Up the Only Viable Alternative to TSMC — Maintain Structural Long for TSMC
- Micron Results Today Will Provide Insight Into Resilience of AI/HPC Equipment Demand
- TechChain Insights: Himax Threatened by China Auto Chip Push? CPO Tech with TSMC Remains Bright Spot
8. TechChain Insights: Himax Threatened by China Auto Chip Push? CPO Tech with TSMC Remains Bright Spot
- China’s push for 100% auto chip localization by 2027 poses risk to Himax, which derived 75% of 1Q25 revenue from China. We engaged the company for comments./
- Himax may avoid direct targeting due to Taiwanese roots and local production via CN Nexchip, and we believe is less vulnerable than Western firms like NXP, TI, and Wolfspeed.
- Copackaged Optics (CPO) industry momentum continues to build as Himax continues role alongside TSMC and FOCI; industry moves from Nvidia, AMD validate long-term optical interconnect opportunity Himax is positioned for.
9. Mediatek Rising in Smartphones and Beyond – Q1 Market Share, Nvidia Partnership, TSMC Node Advantage
- 1Q25 Smartphone Chipset Market Share Data — Shows Growth Outperformance for Mediatek
- Nvidia Partnership Helping Mediatek Break Into PCs and Handheld Gaming Devices — High End Graphics Performance for Small Form Factors
- Smartphones Expected to Rapidly Switch to Advanced Node Chipsets by 2026 — This Plays to Mediatek’s TSMC Advantage

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Spread Remains at Historically Extreme Level; UMC Breaks Higher
- TSMC: +21.5% Premium; Consider Shorting ADR Spread at Current Level
- UMC: +2.3% Premium; Can Consider Shorting ADR Premium at Current Level
- ASE: +3.8% Premium; Wait for More Extreme Premium Before Going Long or Short the Spread
2. TSMC (2330.TT; TSM.US): Germany Fab Delayed for European Budget Crisis; Fab 21 Project in Arizona.
- Taiwan Semiconductor (TSMC) – ADR (TSM US)’s Plan to Build a Plant in Germany Faces Delays.
- TSMC’s Fab 21 Project in Phoenix, Arizona: Progress, Challenges, and Future Plans.
- There remains uncertainty about whether political factors — such as U.S. President Trump’s tariff threats targeting the semiconductor industry— might impact or even reverse TSMC’s investment decision.
3. Taiwan Tech Weekly: TSMC’s 2nm Node to Generate Largest Revenue Ever; US Bottleneck in Adv Packaging
- TSMC’s Next Generation 2nm Node Gathers Momentum as Intel Lags Behind
- TSMC’s Arizona Plant Ships First AI Chips — But Taiwan Remains Core to Packaging
- MediaTek (2454.TT): Chinese Stimulus Program Might Lose Actively; Google DPU Project Delay to 2026.
4. MHI (7011 JP): Take Profits
- MHI is up nearly 60% year-to-date to 46x management’s EPS guidance for FY Mar-26 and 27x our EPS estimate for FY Mar-30.
- By then, we expect Air, Defense & Space revenues to double and the division’s operating margin to rise from 10% to 15%, which is the likely cap on profitability.
- Given Japan’s uncertain finances and the long time horizon that should already be discounted, we recommend profit taking.
5. Vanguard (5347.TT): The 3Q25 Outlook Is Expected to Improve by Around 5% QoQ.
- Vanguard Intl Semiconductor (5347 TT)’s 3Q25 outlook shows slight improvement over 2Q25, potentially around +5%.
- Vanguard Intl Semiconductor (5347 TT) overall utilization expected to reach around 75–80% in 3Q25, with 0.18µm loading is nearly full.
- Progress on Vanguard’s Singapore 12” fab is still in early stages, with the main constraint being the equipment move-in schedule.
6. AMD Advancing AI 2025: Key Takeaways
- AMD snagged Sam Altman as a guest speaker and advocate for the company’s next generation MI450 accelerator product
- Oracle announced their intention to create a zetascale AI cluster based on AMD’s MI355X GPUs
- Marvell announced its custom Ultra Accelerator Link (UALink) scale-up offering. Astera Labs will be next in line.
7. Towa (6315): Buy for Orders Rebound
- After nearly two years of decline, TOWA’s new orders appear to have hit bottom this quarter and should start to recover in the three months to September.
- Sales and profits should follow a similar trajectory with management expecting nearly 60% of FY Mar-26 sales and more than 80% of operating profit to be recorded in 2H.
- Rising demand for AI-related high-bandwidth memory (HBM) and GPU packaging should drive growth for the next 2-3 years, bringing the projected P/E ratio for FY Mar-28 down to 12X.
8. MediaTek (2454.TT): Chinese Stimulus Program Might Lose Actively; Google DPU Project Delay to 2026.
- We anticipate that 2H26 may not be strong for Mediatek Inc (2454 TT), and a typical peak season demand is unlikely.
- Chinese National Development and Reform Commission (NDRC) and the Ministry of Finance issued an urgent response: the current unified deadline for the 2025 national subsidy policy remains December 31, 2025.
- Mediatek Inc (2454 TT) recently underperforms among large-cap stocks due to delay in Google’s Tensor Processing Unit (TPU) project, affecting next year’s revenue and profit.
9. Defense Tech: Taiwan Advanced Submarine Trial & Global Turmoil Puts CSBC in the Investor Spotlight
- Submarine Milestone Validates CSBC’s Strategic Role: Taiwan’s June 17 maiden sea trial of the Hai Kun-class submarine highlights CSBC as the sole builder of Taiwan’s Indigenous Defense Submarine (IDS) program.
- Scale of Program Is Significant vs. Market Cap: Seven additional submarines are expected to follow, with a reported program budget of NT$284bn (~US$9.5bn), over 12x CSBC’s current US$760m market cap.
- Emerging Naval, Drones, & Energy Platforms Provide Optionality: Beyond submarines, CSBC is expanding into unmanned surface vessels (USVs) and offshore wind engineering, offering long-term exposure to Taiwan’s asymmetric defense.

This weekly newsletter pulls together summaries of the top ten most-read Insights across Tech Hardware and Semiconductor on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Taiwan Dual-Listings Monitor: TSMC Premium Break Out Is at Historically High End of Range
- TSMC: +23.4% Premium; Consider Shorting ADR Spread at Current Level
- UMC: 1.5% Premium; Wait for More Extreme Premium Before Going Short the Spread
- ASE: +4.4% Premium; Wait for Higher Premium Before Going Short
2. AMD Ups The Ante With A Flurry Of Smaller Acquisitions
- AMD recently announced the acquisition of Enosemi, a silicon-valley based startup specialising in chips for Co-Packaged Optics (CPO), and Brium, a previously unknown startup specialising in compiler optimisation
- AMD is also acquiring the engineering team behind Untether, a canadian AI hardware startup similar in many ways to Graphcore
- Wave Computing, Luminos Computing, Graphcore, Untether, the list of failing would-be NVIDIA challengers keeps growing. Who’s next?
3. Taiwan Tech Weekly: 2026 Chip Forecasts Remain Robust; Robots as Taiwan’s Next Driver; Memory 1Q25
- Global Chip Sales Tick Higher in April, 2026 Growth Forecast Robust — WSTS Forecast Signals Sustained Semiconductor Growth Through 2026 Despite Macroeconomic Uncertainty
- National Taiwan University Semiconductor Forum Highlights — Edge AI and Robotics The Next Major Demand Catalyst… AI Still in Its Early Phase
- Semiconductor Memory Q125 Review — Tariff & Tech Transition Impacts, HBM Outlook
4. TSMC (2330.TT; TSM.US): Is the Cost of Advanced Wafers a Concern? We Believe It Isn’t.
- There is speculation that the cost of Taiwan Semiconductor (TSMC) – ADR (TSM US) 1.4nm wafers is more than 30% higher than that of 2nm wafers.
- In semiconductor node migration, newly introduced solutions are generally more advanced and therefore more valuable—which naturally means higher costs.
- Apple (AAPL US)’s iPhone consistently adopts TSMC’s most advanced technology, ensuring its products maintain industry-leading operational efficiency.
5. Alphawave Ditches WiseWave Before Embracing Qualcomm Bid. But Why?
- Qualcomm’s recently rumoured desire to acquire UK-listed Alphawave finally came to fruition on June 9 with a US$2.4 billion offer
- Just two days earlier, on June 7, Alphawave announced that the company had disposed of its interest in China-based JV, WiseWave Technology
- What is WiseWave Technology, why did Alphawave invest in it and why is it now divesting that interest prior to the Qualcomm acquisition?
6. TSMC: Review of Client Roadmaps, Rumored A16 Pricing Underscores Strategic Moat in Advanced Nodes
- TSMC May Sales at Record High; Rumored A16 Pricing Underscores Strategic Moat in Advanced Nodes
- Review of Client Roadmaps Shows TSMC Positioned as Indispensable Enabler of AI and Advanced Compute Products
- We Maintain Our Structural Long Rating on TSMC; Inexpensive Despite Recent Rally
7. Memory Monitor: Soaring DRAM Prices and Enterprise Flash Shifts – The Memory Market Finds a New Gear
- DRAM — Global Memory Market Has Regained Momentum in Mid-2025, Driven by a Sharp Upswing in Spot Prices.
- NAND Flash — Strategic Outsourcing, High ASP Segments Drive Memory Controller Specialist Gains
- Conclusion — Short-Term Gains vs. Long-Term Growth in Memory Markets