This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
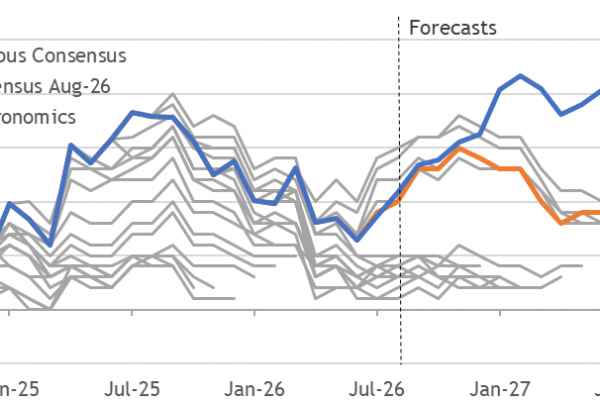
1. HEM: Oct-26 Views & Challenges
- Energy prices are squeezing higher amid low inventories and resilient demand, building more inflation than many forecast.
- Second-Round effects are small, but UK inflation expectations are anchored above the target, and monetary conditions aren’t tight.
- We see hikes from the BoE in Nov-26 and the ECB/Fed in Dec-26. Market pricing looks too stretched given dovish policymaker bias.
2. HEW: Broadly Blowing Tighter
- Energy supply is tightening due to intensified attacks in the Strait of Hormuz and a US hurricane. Fed minutes and ECB meeting accounts also confirm a tightening bias.
- A failure by the UK Green Party leader to significantly increase support for the left in a by-election also reduces the political pressure on PM Burnham to loosen fiscal policy.
- Next week features US inflation data that are set to show another rise with energy prices. UK GDP and the final EA inflation print are other highlights for us.
3. US TREASURIES: Where Bonds Go, Stocks Will Follow!!
- The US bond market is rapidly moving against investors, and, absent a sea-change event, the equity market will eventually follow. The positive bond-stock correlation reinforces equity market risk.
- The 5.25% level on the 10-year has been a turning point for the equity/bond relationship, flipping correlations from negative to positive.
- The MOVE/VIX level of 6.6 is precarious and likely to resolve with a rise in the VIX, leading to a corresponding fall in equity prices.
4. Fed: Hawkish Minutes, Softer Data
- The Fed minutes confirm that the unsurprising 25bp September hike had unanimous backing, including from non-voters, and that most officials favoured another increase by year-end.
- Several saw policy as only mildly restrictive, while a couple explicitly raised their neutral-rate estimates, reinforcing a higher-for-longer stance.
- Softer post-meeting inflation and payroll data favour an October pause, but our call for a December rate hike remains likely.
5. ECB: December Hike Reinforced
- The ECB meeting accounts confirm unanimous support for the unsurprising 25bp hike delivered in September, and provide no basis to treat it as the end of the cycle.
- All members saw upside inflation risks, while one judged the adverse energy scenario likelier than the baseline, reinforcing a December hike.
- A 2.5% rate is still seen within the range of staff neutral estimates. Resilient activity and above-target core inflation leave scope for another 25bp increase.
6. Rare Earth Elements: U.S. SMUGGLING ILLICITS CHINA CRACKDOWN !!
- As with US efforts to thwart Chinese smuggling of chips to meet its AI demand, China cannot fully stop US smuggling of REEs and high-powered permanent magnets.
- Chinese official policy holds that applying export controls to rare earths is consistent with international practice because they can be used for both civilian and military purposes.
- U.S. is 80% import-dependent on REEs, with China supplying 80% of those imports. It is a 100% net importer of REEs produced via China’s magnet rare earth concentrate (mREC) process.
7. Portfolio Update: Broader Commodity Positioning, Narrow Equity Leadership
- U.S. small caps, metals and mining stocks, and gold were key detractors within the portfolio suite, offsetting positive allocation effects in our underweight fixed income exposure.
- Aggressive portfolios maintained their outperformance YTD driven by strong selections within the equity asset class.
- Positioning changes include commodity diversification beyond gold, adding Japanese equities, and maintaining an underweight to bonds.
8. U.S. Midterms Elections: What a Trump Without Congress Means for Markets
- Democrats are favoured to win Congress, but even a sweep cannot remove Trump or overturn his vetoes, tariffs and pardons. Expect investigations and friction, not reversal.
- Losing Congress will not calm Trump’s style; it redirects it. With no re-election to protect, expect him to be contained at home and unleashed abroad, as in 2019.
- Unlike 2019, the Fed is hiking and the 10-year is above 5%. Own cheap index protection, a curve steepener, defence and staples, and Asia hedges to January.
9. The (funding) Wall of Worry
- Will AI kill us, or the companies building it? Or the bond market?
- Will the smartest guys in the room once again blow up markets as their cost of funding rises?
- When will bonds v Equities mean revert? Will Congress take back control of US war(s)?
10. Asian Equities: Valuations in ASEAN Markets Are More Divergent than Rest of Asia
- Malaysia’s PE and P/BV are at significant discounts to their long-term means. Thailand is at a small discount. Indonesia and Philippines are at very large discounts to their long-term averages.
- Singapore’s PE and P/BV are at large premiums to long-term averages. Despite the improvement in governance and high dividend yield, they don’t seem justified by forward EPS growth and ROE.
- In the near term, Indonesia, Philippines, Malaysia could rerate. However, “higher for longer” US yields could prevent significant rerating of the first two. Thai valuations could stay flat for now.