This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Derivatives on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. China Mobile (941 HK) High-Conviction Tactical Entry
- China Mobile (941 HK) has been downtrending since mid-November, this insight assesses the Convexity of a China Mobile Long Position based on our model probabilistic forecast.
- Mean reversion opportunities come in various shape, this one is a short-term trade, where the investor can lock in a quick gain on a 1-2 weeks holding horizon.
- The trade can be executed with stocks or options. Vertical Spread combos, if available are also a good choice, use our model targets to improve your P/L Ratio skew.
2. Pan-Asian Stocks Tactical Outlook (Week Jan 19 – Jan 23)
- Tactical WEEKLY snapshot of the Pan-Asian indices and stocks we cover, the forecasts are based on our proprietary quantitative models.
- Most stocks are overbought or becoming overbought, after the last WEEKLY Close.
- Only 3 stocks are oversold: China Mobile (941 HK) , Softbank Group (9984 JP) , HDFC Bank (HDFCB IN) . Deeper evaluation of these stocks will require dedicated insights.
3. Samsung Electronics (005930 KS) Tactical Outlook: One More Week of Gains?
- Samsung Electronics (005930 KS) rallied much higher since our last insight, another +15% higher, totalling roughly +45% gains from mid-December.
- We already flagged the stock as insanely overbought in our insight in early January, now we are way beyond that.
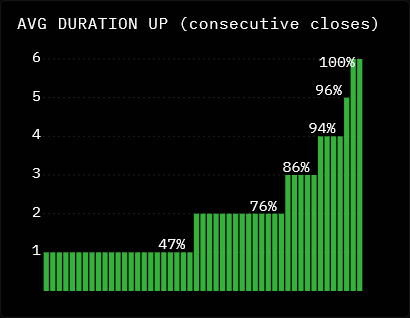
- The PRICE MODEL limit has been trashed, the TIME MODEL says that usually this pattern never rallies for more than 6 weeks. Next week is the 6th week up.
4. Nikkei 225 (NKY INDEX) Outlook Amid Escalating Japanese Government Bond Concerns
- At the end of last week our quant model signaled the Nikkei 225 (NKY INDEX) was overbought (82% prob. of reversal). This week the index started to pullback.
- Escalating Japanese Government Bond concernsare worrying investors. Our model did not know what the catalyst was going to be but signaled the potential for a pullback before the news.
- Now in this insight we will evaluate where could be a good area to buy again the Nikkei 225 (NKY INDEX) .
5. Australia Single Stock Options (Jan 12–16): Materials Dominate Amid Compressed Implied Correlations
- The combination of narrow leadership, low correlation, and elevated single stock volatility defines the current market backdrop.
- Materials Sector in focus with BHP and RIO both reporting this week.
- Sector-Level analysis shows Materials stocks clustered near their highs despite wide dispersion in implied volatility positioning.
6. HDFC Bank (HDFCB IN) Tactical Outlook After Q3 Earnings Call Release
- HDFC Bank (HDFCB IN) ‘s Q3 results met expectations, with encouraging credit growth from easing rates and CRR releases. Deposit mobilization, CASA growth, and lower funding costs remain critical profitability drivers.
- Asset quality remained pristine with low NPA accretion and mid-20 bps slippages excluding agriculture. The bank provisioned INR 5 billion for agricultural inspection; net credit costs were ~37 bps.
- Our model says HDFC Bank is oversold, this could be a good time for a LONG trade. Gaudenz Schneider recently published a statarb trade proposing LONG HDFC vs SHORT Axis Bank.
7. Hong Kong Single Stock Options Weekly (Jan 19 – 23): Tight Index Range Masks Stock-Pickers Market
- Hong Kong equities continue to trade in an unusually subdued environment, with tight index ranges reinforcing the absence of strong directional conviction.
- Correlation measures continue to soften, pointing to a stock picking environment rather than broad index driven moves.
- The current backdrop reflects indecision rather than stress, with volatility easing alongside range bound prices.
8. Australia Single Stock Options (Jan 19–23): Dispersion Intensifies as Momentum Fades
- Australian equities lost momentum over the week, with subdued performance masking growing dispersion beneath the surface.
- Market breadth offered little encouragement, highlighting a lack of broad participation despite pockets of resilience.
- Diverging sector returns underscored a continued decline in cross-market cohesion.