This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK: Turning the Statistical Corner
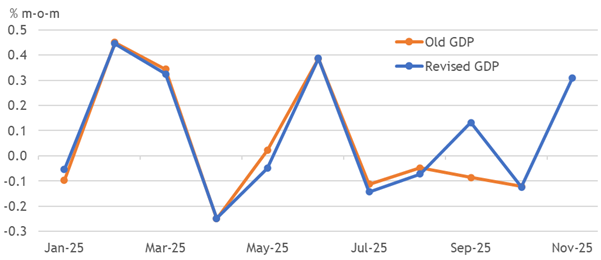
- The UK GDP surprise flipped to exceed expectations with 0.3% m-o-m growth in Nov-25 as residual seasonality turned past its trough. We now track 0.14% q-o-q for Q4.
- Further upside news is likely over the next few months as output surges again in Q1, pushing back dovish hopes for another rate cut. We still see the cutting cycle as over.
- Economists prefer to tell fundamental stories, ignoring statistical ones, but we should not be shocked by the impact of the predictable surprises created by this shortcoming.
2. US Inflation Resumes Without Payback
- US inflation resumed its monthly trend in headline, core, and underlying services after nonsensical methodological noise around the shutdown, including non-collection itself.
- Payback from late sampling in November didn’t have an apparent inflationary effect, perhaps because the gap between collections didn’t leave long for other prices to rise.
- Surprises are skewing lower, but inflation is stuck above the target, so there isn’t a compelling case to cut again. We still expect the Fed to hold rates in January.
3. “DON’T FIGHT THE FED” : It Might Fight Back!
- Federal Reserve Chair Jerome Powell has said the Department of Justice has served the central bank with subpoenas and threatened it with a criminal indictment over his previous testimony.
- Powell said that the DOJ actions were part of a concerted effort by the Administration to undermine and threaten its ability to set interest rates according to its mandate.
- Precious metals moved higher on the news, while the dollar and S&P futures declined. We expect growing anxiety about the Fed’s independence to weigh on U.S. markets this year.
4. The Heat Is On: News Flow and Sentiment in CHINA / HONG KONG (January 14)
- The materials, healthcare, and tech sectors are leading the Hong Kong market out of its consolidation pattern, with January shaping up to be one of the best in years.
- China and Hong Kong ETF flows were the strongest in Asia during 2025 posting significant inflows throughout the year although Korea had the most significant increase at 600%.
- Trip.com Group (9961 HK) share price plunged after it announced an investigation into its monopolistic business practices. Haidilao International Holding (6862 HK) shares jumped after the founder returned as CEO.
5. Tactical Trading – Increasing Hong Kong Exposure
- The time is right to increase exposure to the Hong Kong market
- A confluence of factors and catalysts will drive the index higher
- We suggest a few names that we believe will benefit.
6. Technically Speaking Breakouts & Breakdowns – HONG KONG (January 13)
- Hong Kong market is poised to break out from its consolidation, which began in October of last year. The next resistance level for Hong Kong’s Secular Bull Market is 30,000.
- Increased strength and momentum in the high beta tech and healthcare sector, along with increased mainland buying, confirm the probability of a breakout in the near term.
- Hua Hong Semiconductor (1347 HK) has had a breakout from its continuation wedge formation pattern. As the second largest mature node specialty foundry, the company is benefiting from on-shoring policies.
7. Overview #46 – From GPUs to Geopolitics: Is China Winning the AI Race?
- A review of recent events and data impacting our investment themes and outlook
- China has another breakthrough moment with DeepSeek changing standard AI architecture
- The case for precious metals and commodities continues to build, but short-term caution is warranted.
8. BUY/SELL/HOLD: Hong Kong Market Update (January 10)
- The Hong Kong market has shown increased momentum so far in 2026, testing the top of its trading range at 27000. The materials sector continues to outperform.
- Mainland buying has increased during the first week of 2026, with Momentum, Growth and Liquidity leading factors in stock outperformance.
- Baidu (9888 HK) announced that it will spinning off its AI chip business in a separate Hong Kong listing. The shares have outperformed on the news.
9. CHINA REFLATION: China Gets Invited to the Global Inflation Party!
- After three years of disinflation and continuous price pressures, reflation is reappearing in China. CNY appreciation pressure and rising government bond yields reflect underlying inflation building in the economy.
- Exporters are showing increased preference to repatriate FX earnings as China’s trade surplus reaches record highs in 2025. Foreign investors began to reallocate investments toward the mainland in 2025.
- China’s monetary policy will include “reasonable” price increases as one of its major policy benchmarks. This policy will work in coordination with fiscal policies like “anti-involution” to support prices.
10. A Momentum-Driven Start to 2026
- Evidence of strong price momentum is intermediate-term bullish for equities.
- Our technical outlook is further supported by twin macro tailwinds of easy monetary and fiscal policy.
- However, growth expectations are high and the market is vulnerable to disappointment and the propensity for large drawdowns during mid-term election years.