This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
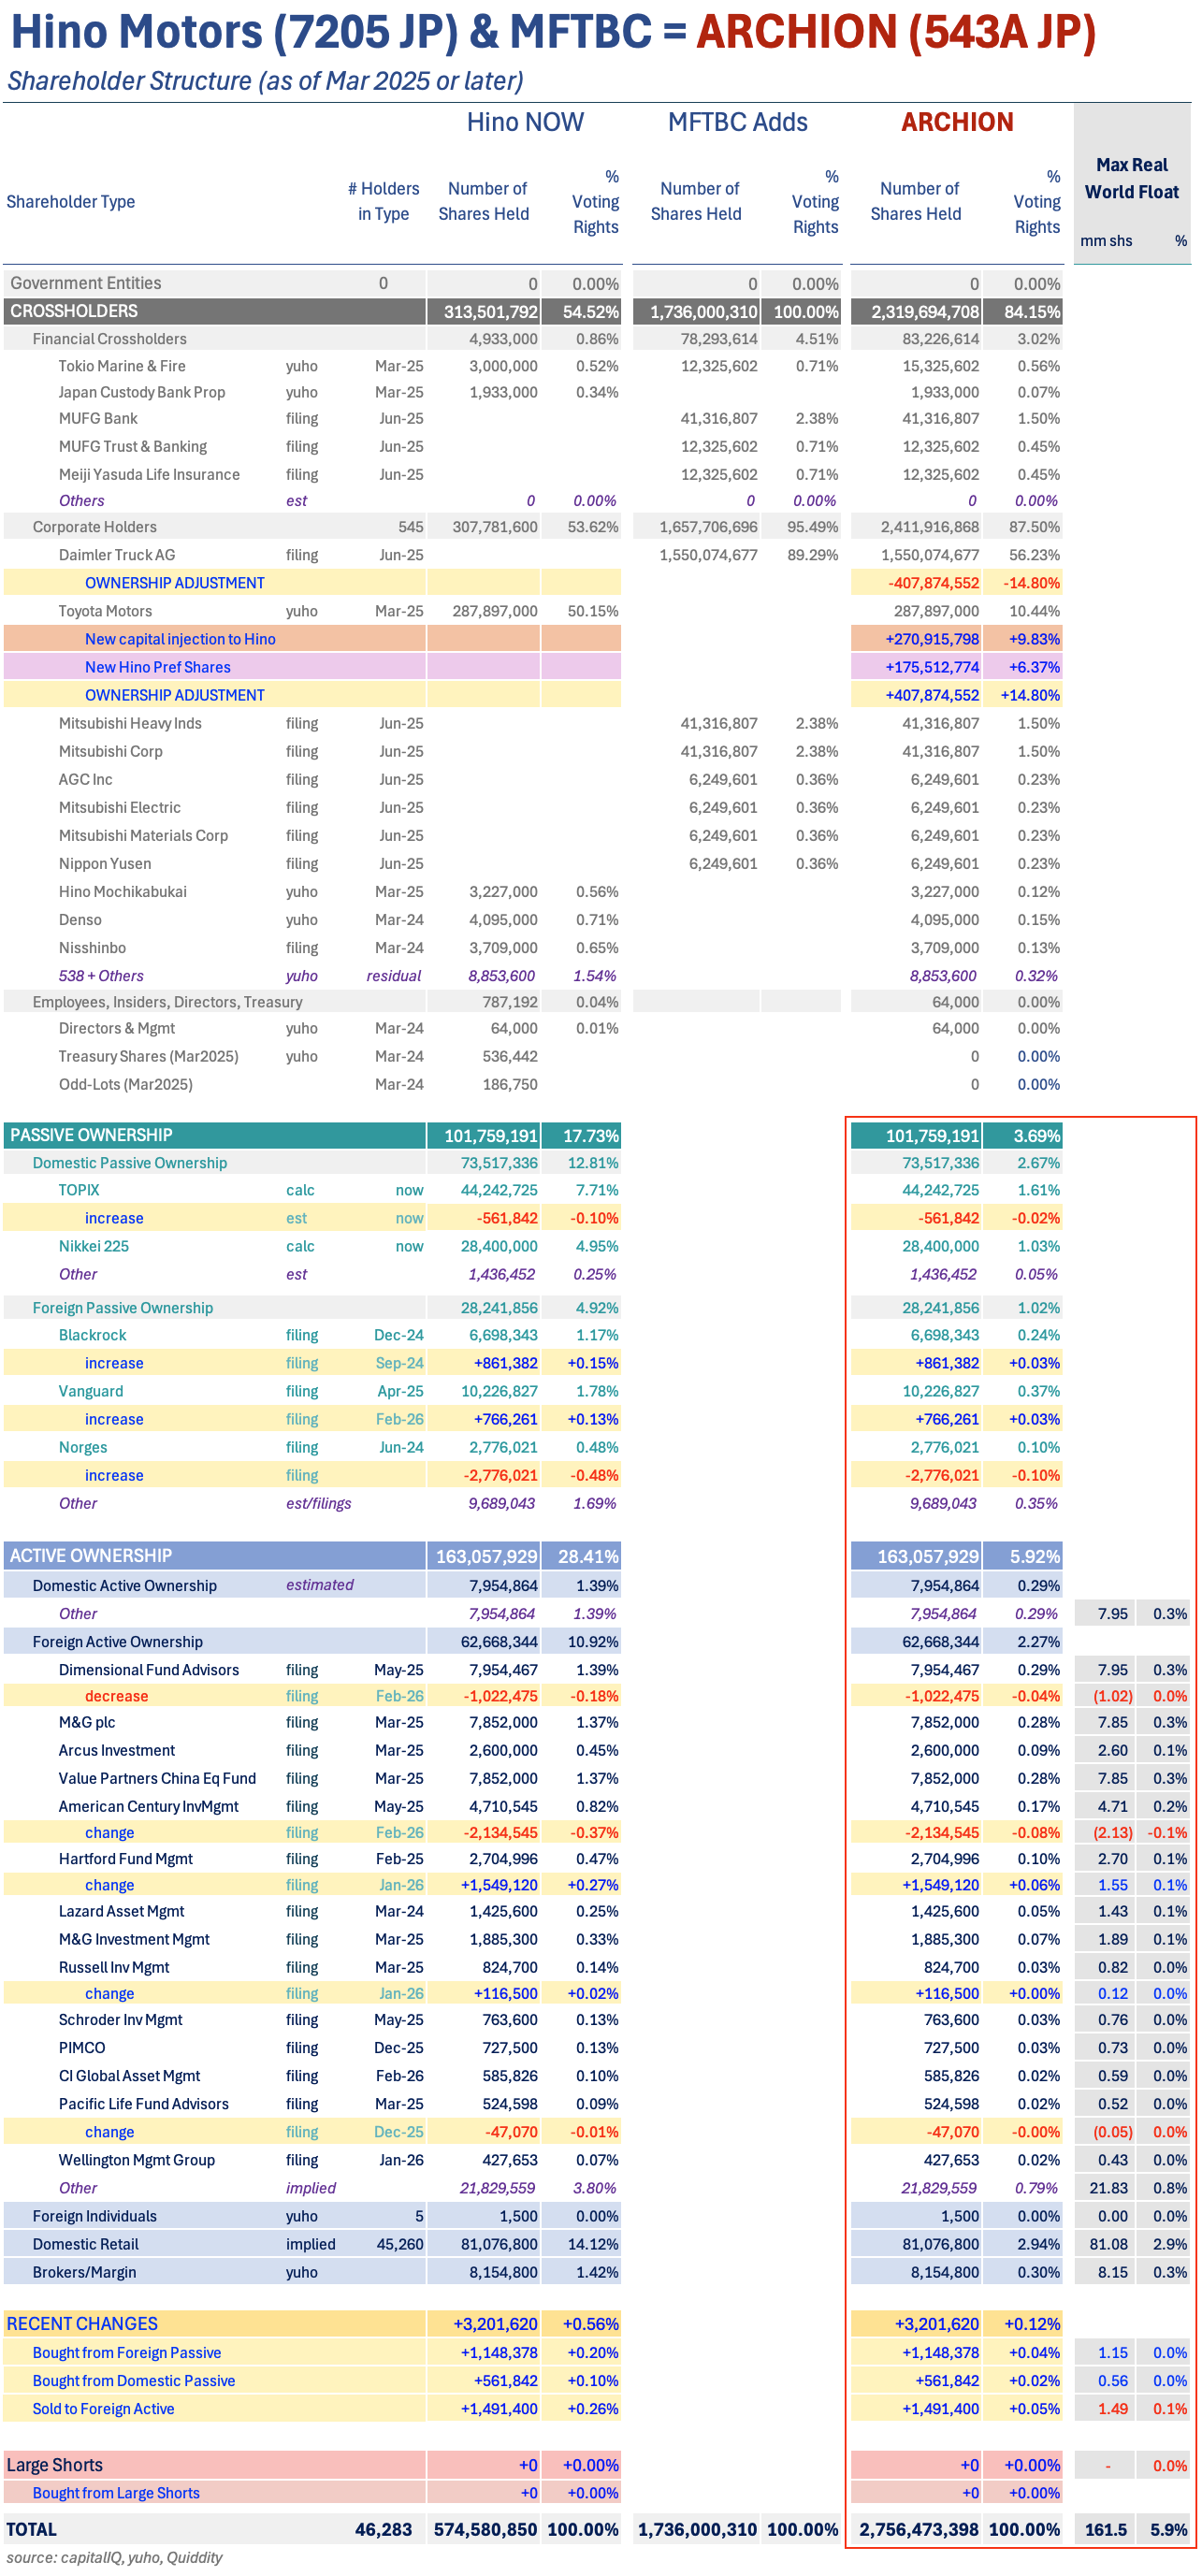
1. [Japan M&A/ECM] ARCHION INCOMING!
- On April 1, the merger of Hino Motors Ltd (7205 JP) and Mitsubishi Fuso Truck & Bus Co (MFTBC) is effective where MFTBC gets injected into a Surviving Entity ARCHION.
- Currently, “minorities” own 49.7% of Hino Motors but that includes cross-holders. Active holders and passive holders will own 5.7% and 3.9%, respectively. Daimler and Toyota 83%, crossholders 7+%.
- Daimler and Toyota need to sell down to 25% each. The cross-holders will want to sell too. This will mean a BIG offering “as soon as is reasonable.” A re-IPO.
2. Aequitas: Victory Giant A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Victory Giant Technology -A (300476 CH) (VG) is now said to be looking at raising up to US$2bn in its H-share listing.
- VG is one of the global leaders in advanced printed circuit boards (PCB) products for AI and high-performance computing.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
3. Victory Giant H Share Listing: The Investment Case
- Victory Giant Technology -A (300476 CH), the world’s leading PCB manufacturer for AI and high-performance computing, is pre-marketing an H-Share listing to raise around US$2 billion.
- Victory Giant is an AI hardware play and a core supplier to NVIDIA Corp (NVDA US), as it is one of the few companies capable of mass-producing high-end HDIs.
- The investment case is bullish due to Victory Giant’s leading market share, rapid growth, rising margins, low leverage and undemanding valuation.
4. Huaqin H Share Listing: The Investment Case
- Huaqin Technology (603296 CH), the world’s largest consumer electronics original design manufacturer, is pre-marketing an H-Share listing to raise around US$1 billion.
- Huaqin ranked as the largest consumer electronics ODM globally in 2024, with 22.5% market share.
- The investment case is bearish as Huaqin’s rapid growth has come at the cost of margins and cash generation. Also, the valuation is unattractive compared to peer multiples.
5. Unitree Robotics Valuation Update: Bull-Case DCF Frames IPO Upside As Onshore Listing Nears
- My bull-case 10-year DCF, based on stronger humanoid commercialization, faster revenue scaling, sustained growth and profitability expansion over time, suggests upside potential ahead of onshore listing.
- While the robotics stock valuations are high, I note the companies with long-term growth opportunities that are investing in growth with higher expenses can still maintain high multiples for years.
- Using my 2026 estimates, Unitree Robotics should trade post-IPO at an EV of ~19x revs, a premium to high-growth HK-listed robotics peers, including Shenzhen Dobot and UBTech Robotics.
6. Pre-IPO Victory Giant Technology (PHIP Updates) – Some Points Worth the Attention
- Victory Giant has delivered an impressive 2025 results. However, the profit in the second half of the year showed a slight downward trend compared with 25Q2.
- AI and high-performance computing business is still expected to maintain a growth rate of 40%-50% in 2026. The growth rate will gradually slow down to 20%-30% from 2027 to 2028.
- An IPO price that is 20% to 30% lower than A-share is a rational range. 25x P/E based on 2026 forecast could be comfortable, which provides certain margin of safety.
7. Aequitas: Tata Capital IPO Lockup Expiry – Will Have to Sell US$1.4bn of Stock but Has More Time Now
- Tata Capital Limited (TATACAP IN) raised around US$1.7bn in its IPO in October 2025. The lockup on its promoter and pre-IPO investors is set to expire soon.
- Tata Capital Limited (TCL) is the flagship financial services company of the Tata group and a subsidiary of Tata Sons Private Limited.
- In this note, we will talk about the lockup dynamics and possible placement.
8. Aequitas ECM Weekly (30 March 2026)-Huayan, Diagens, Tong Ren, Epiworld, Pateo, Capitaland, Seoul Gu
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, three mid-cap companies are set to list later today in Hong Kong.
- On the placement front, there weren’t many large deals given the ongoing market volatility.
9. Pre-IPO Manycore Tech – (PHIP Updates) – The Business Model, the Concerns and the Outlook
- The core business model of Manycore is “cloud-native SaaS subscription + spatial intelligence solutions”, and it is transforming from a simple software fee model to a platform-based capability output model.
- Manycore’s moat is built on the basis of the triad of “technology + data + leading scenarios”, but the core business is strongly correlated with the real estate cycle.
- 8-10x P/S can be regarded as a relatively conservative lower limit for valuation, while 12-15x P/S can be considered as an upper limit for valuation when market sentiment is optimistic.
10. Arxis Inc. (ARXS): Peeking at the IPO Prospectus of a PE Backed Aerospace Components Company
- Arxis Inc designs mission-critical, IP-protected electronic and mechanical components for aerospace, defense, and industrial markets, with highly diversified customers and strong engineering differentiation.
- Backed by Arcline Investment Management since 2019, Arxis has completed 30+ acquisitions and filed for a March 2026 IPO with leading global underwriters.
- Strong revenue growth ($424.5M to $1.59B from 2023–2025) and a profitable 2025 support its platform-driven “layer cake” growth model across defense and aerospace.