This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
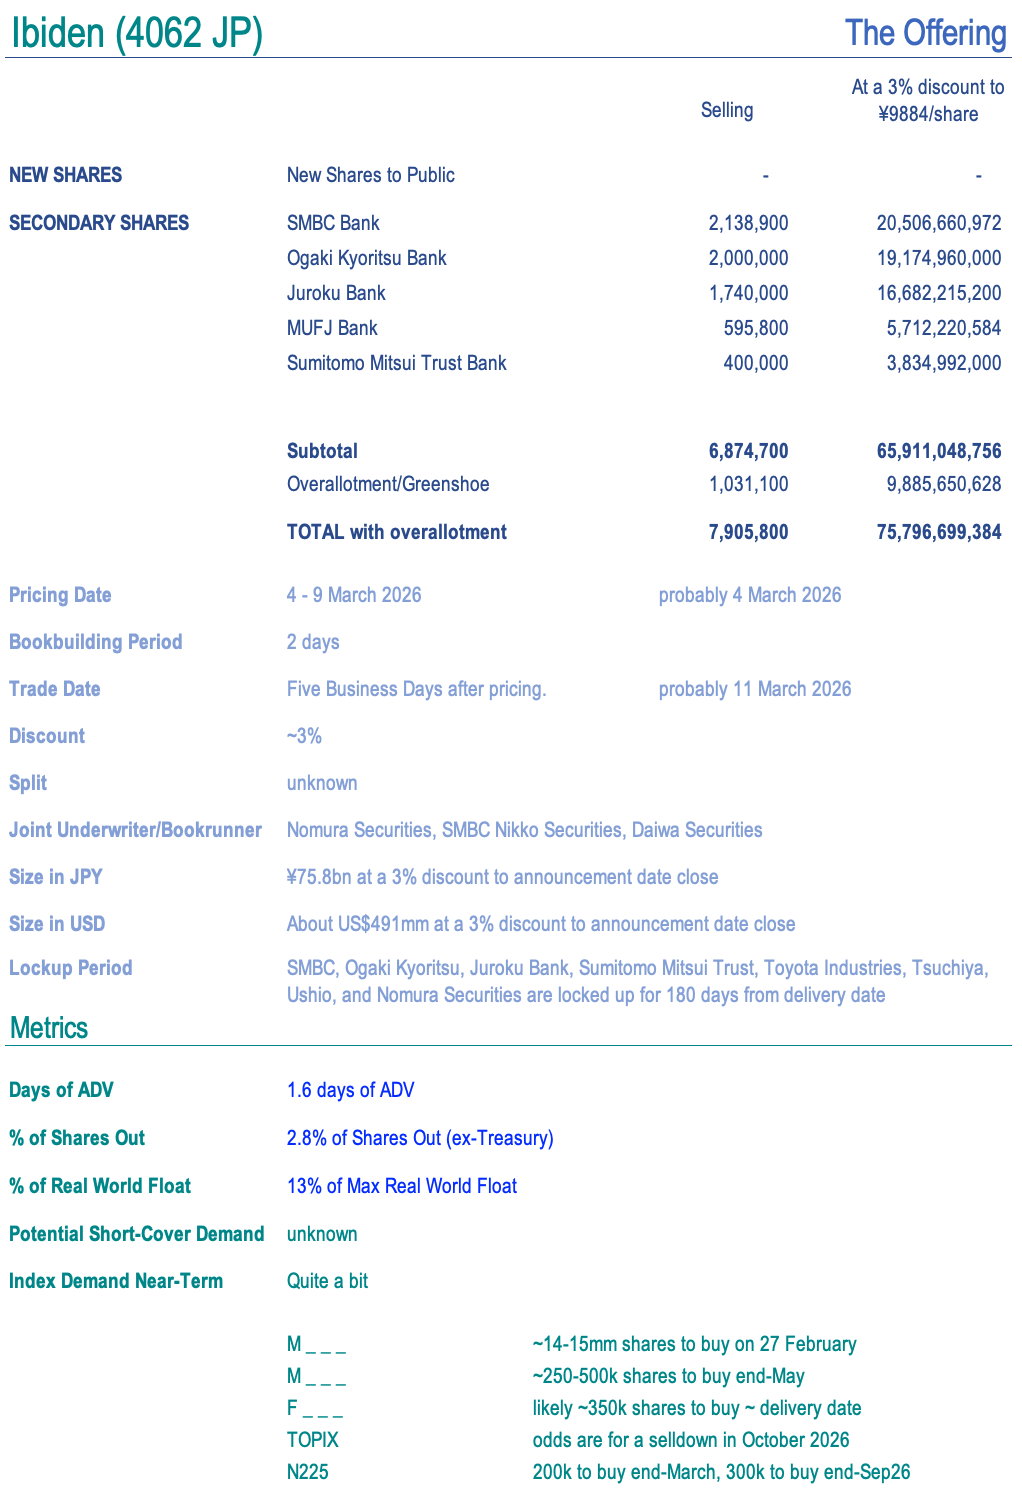
1. [Japan Offering] Five Banks Offer 3% of Ibiden (4062) After 400% 12mo Run into Friday’s Index Buy
- The stock is up 400% in a year. 3yr forward revenue consensus is up 20%, 3yr forward consensus earnings are up 50%. Multiples are therefore WAAAAY up.
- Today, five banks announced a partial selldown. They have more to go after, and there are lots of corporate crossholders not involved here.
- There is a big index upweight Friday after upweights in October and a Nikkei inclusion in November. HALF the September Max Real World Float has moved to Passive in 5mos.
2. PayPay IPO (PAYP US): The Investment Case
- PayPay (PAYP US), Japan’s leading financial technology company, is seeking to raise about US$2 billion through a Nasdaq IPO.
- In 2024, PayPay held an 64% share of Japan’s code-based payment market by transaction volume. It is a subsidiary of Softbank Group (9984 JP).
- The investment case rests on market leadership, the payment business’s robust transaction-driven growth, financial services’ increasing margin contribution, profitability, and a strong credit profile.
3. Nintendo (7974 JP): A US$2.1 Billion Secondary Offering
- Nintendo (7974 JP) has announced a secondary offering of 32.7 million shares (37.6 million including overallotment), worth around US$1.8 billion (US$2.1 billion including overallotment).
- There are four selling shareholders: Nomura Trust and Banking Co, Bank of Kyoto, DeNA (2432 JP), and Resona Bank.
- The offering as a percentage of outstanding shares and ADV is below average compared to recent large placements. A ToSTNeT-3 repurchase (up to JPY100 billion) will mitigate the impact.
4. Aequitas: PayPay Pre-IPO – The Positives – Dominant in the Payment Space
- PayPay (PAYP US) (PP), a Japanese payments and financial services platform, is looking to raise up to US$2bn in its upcoming US IPO.
- PP operates a digital finance platform that serves as a payment solution for users and merchants, along with offering additional services.
- In this note, we talk about the positive aspects of the deal.
5. Aequitas: Toyota Motors Cross-Shareholding – Possible US$19bn Unwind, Might Not Be Soon
- As per media reports Toyota Motor (7203 JP) (TMC) could be planning to unwind some of its US$19bn cross-shareholding by working with financial institutions.
- In our prior series of notes, we had looked at the cross-shareholding across a swathe of companies, the largest of which was Toyota Motors.
- In this note, we take a quick look at the possible shareholding unwind.
6. Aequitas: Capitaland India Trust Placement – Accretive Raising For Asset Construction
- Capitaland India Trust (CLINT SP) is looking to raise US$121m in a primary placement.
- The purpose is for financing of two office buildings in Bangalore, India.
- In this note, we will talk about the placement and run the deal through our ECM framework.
7. Cosmo Robotics IPO Valuation Analysis
- Our base case valuation of Cosmo Robotics is target price of 12,107 won per share (102% higher than the high end of the IPO price range).
- Our base case valuation of Cosmo Robotics is based on a P/S multiple of 45x our estimate sales of 8.8 billion won for the company in 2025.
- The P/S multiple of 45x is based on the average P/S multiple of the comps in 2025.
8. Aequitas: Ibiden Placement – Opportunistic Selldown as Shares Were up 8% Today
- A group of shareholders are looking to raise US$394m from selling their respective stakes in Ibiden Co Ltd (4062 JP).
- The deal is another cross-shareholding unwind, which has been an ongoing narrative in Japan over the past 1-2 years.
- In this note, we will talk about the placement and run the deal through our ECM framework.
9. Wuxi Lead Intelligent Equipment – The Concerns On Fundamentals and the Valuation Outlook
- Investors are concerned about whether this high growth in 2025 represents a temporary rebound in industry or a sustainable trend. The concern on fundamentals directly suppressed the stock price performance.
- The IPO pricing of HK$45.8/share is supported by core strength and business model, but it does not leave sufficient safety margin to hedge against short-term market pessimism towards cyclical stocks.
- Given the current market attitude towards new energy equipment, HK$35-42/share may represent a more solid bottom area.Share price can easily break through IPO pricing when WUXI LEAD fulfill high-growth commitment.
10. HPSP Placement: Yet Another Opportunistic Selldown by Crescendo Equity Partners
- Crescendo Equity Partners is looking to raise ~US$225m via a secondary placement of its shares in HPSP (403870 KS) .
- This comes after a prior selldown last month and before their 90 days lockup.
- In this note, we will talk about the placement and run the deal through our ECM framework.