
This weekly newsletter pulls together summaries of the top ten most-read Insights across Macro and Cross Asset Strategy on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. UK: Unsustainable Wage Growth
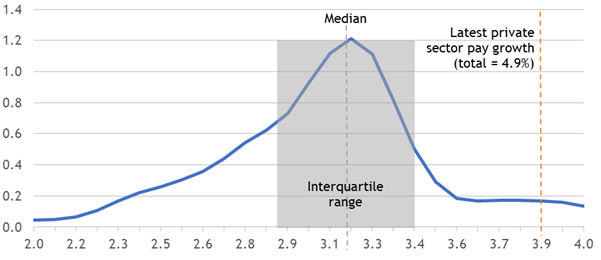
- Wage growth of 3.25% is unlikely to be consistent with achieving the 2% inflation target, contrary to the BoE’s assessment that relied on consistently dovish-biased assumptions.
- Stagnant productivity and a recovery in profit margins are problems that should inform any coincident assessment. But the Bank is relying on the world to bail out UK excesses.
- The Euro area and China are not structurally exporting disinflation anymore, and the latter is not politically tolerable. The biased BoE seems set to keep missing its target.
2. UK Electoral Hopes Rise In Asian Victories
- Landslide victories for recently appointed Prime Ministers calling snap elections in Japan and Thailand offer hope to Labour MPs hoping Keir Starmer stands aside soon.
- Peter Mandelson’s conduct is damned in the Court of Public Opinion, including evidence that he was unfaithful to his political colleagues and husband. Starmer can’t escape it.
- Leadership challengers aren’t ready yet, so Starmer remains likely to limp on longer. But change will bring fiscal easing that the dovish BoE fails to anticipate adequately.
3. UK GDP Softly Turns In Q4
- Half of last month’s upside GDP growth surprise was revised away with the December data, tempering Q4 growth back to our 0.1% q-o-q forecast while disappointing others.
- An encouraging mix skewed to services output meant the underlying performance still trended up during Q4. We now track 0.4% for Q1, aided by residual seasonality.
- Revisions to December, or a belated catch-up to trend, could make this even stronger. It is the flip side of soft H2 performances, and the dovish BoE is focused on other things.
4. CHARTING COURSE: HK Dollar & Bitcoin…. Again(February 2026)
- The HKD is moving to the weak end of its trading band. In order to maintain the current level of the Aggregate Balance, the HKMA will allow HIBOR to rise.
- A stronger CNY/HKD exchange rate will draw more HKD investments to the mainland as stock market valuations converge. There is a strong demand for Chinese bonds in Hong Kong.
- Bitcoin is taking a breather after its rapid decline this year, and before it begins its next leg down. Our long gold / short bitcoin strategy has gained 55% YTD.
5. About 10% of Listed Stocks in KOSDAQ Could Be Delisted by the End of 2026
- There are too many listed stocks in the KOSDAQ exchange. The Korean financial regulators have finally realized this problem and the FSC announced several measures to fix this problem.
- About 10% of the stocks listed on the KOSDAQ exchange could be no mas by the end of 2026.
- The overall impact should be positive on the KOSDAQ index since it helps the investors to focus on the higher quality companies and the zombie companies to be delisted.
6. BUY/SELL/HOLD: Hong Kong Market Update (February 10)
- Hong Kong market continues in an upward trend after breaking resistance at 27100 last month. The next resistance level is 28000. Southbound flows have accelerated over the last week.
- The energy, conglomerates, and property sectors outperformed the materials sector in 2026. Momentum and value have been the top factors for performance YTD.
- Zhejiang Sanhua Intelligent Controls (2050 HK) was initiated with OUTPERFORM at Shenwan Hongyuan Research. The manufacturer of air-conditioning and refrigeration components has expanded into energy storage, automotive thermal management, and robotics.
7. Asian Equities: Foreigners Continue to Sell Asia but Market Rotation Setting In
- In January FIIs sold US$3.5 bn Asia-6 equities and till 10th February they have sold US$5.7bn. February marks the fourth month in succession that the FIIs are selling Asia.
- In February MTD, FIIs have sold US$6.5bn Korean equities and US$888m Taiwanese. They bought US$1.7bn India and US$23m Philippines. Thailand was also bought (US$139m in January), Indonesia sold heavily (US$588m).
- FII buying should restart in Korea, Taiwan soon. Flows into India have bounced back but it’s too early to predict a sustainable reversal. Philippines, Thailand should continue to see inflows.
8. Asian Equities: India – Light at the End of the Tunnel
- After long-drawn-out underperformance, Indian equities are looking interesting again. Cyclically improving growth, stabilizing currency on the back of several trade deals, policy focus on infrastructure and advanced manufacturing are converging.
- High frequency data reveals growth acceleration in consumer discretionary, construction goods, automobiles, electrical goods, base metals. Some of these sectors are reasonably valued in relation to forecast growth and ROE.
- We highlight 17 stocks across a range of sectors that have robustly improving earnings estimates, strong growth forecasts, healthy balance sheets, reasonable growth-adjusted valuations. 8 of them are large caps.
9. Understanding US Debt Dynamics – Dissecting the $38t Debt
- Investors should not focus solely on the $38t in US public debt as it a headline figure over-reported and under- analysed
- Fears of using short-term debt as the main source of financing debt is misplaced. They are rolled over and do not ‘add’ to new debt unless deficits expand
- Teasury auction data does not show any signs of funding stress to date despite the widespread fears fanned by comments on Trump’s fiscal policies
10. HEW: Assuming Success
- Assumptions consistent with our hopes are alluring, but not always realistic. They can lead policymakers to learn the wrong lessons for politics and monetary conditions.
- Recent election victories don’t mean a new soft-left UK leader will achieve the same. Current resilience need not break to target-consistent levels, nor create room for cuts.
- Next week is packed with some of the most important UK releases coming before the BoE’s March decision, including unemployment and inflation’s likely January drop to 3%.


