
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Zhongji InnoLight (3308 HK) IPO: Debut and Trading Strategy
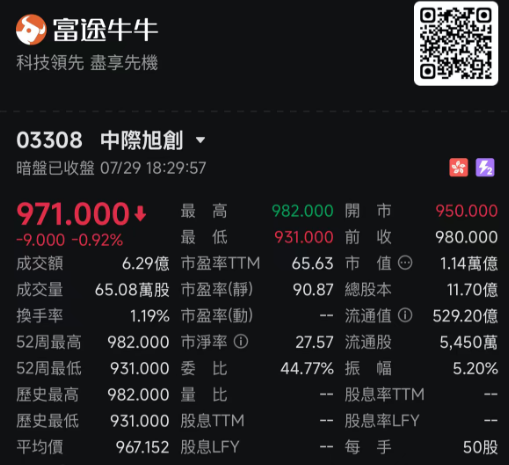
- Zhongji InnoLight (3308 HK) fixed its IPO price at HK$980, 3% below the maximum, due to the recent weakness of AI-related stocks. Its HA discount is now at just 11.1%.
- Its peers have retreated an average of 12.1% in a week, and its A-share was off by 10.4%. Futubull’s grey market price was down 1% from the IPO.
- It may dip below IPO on debut, but anything below 15% HA discount is a bargain (HK$936.8). For initial upside, we look for par with A-share, i.e. HK$1,102.
2. HK IPO WATCH: Zhongji Innolight – Global Dominance for AI Buildout
- Zhongji Innolight has placed its dual-listed H shares at HK$980 per share, approximately a 10% discount to its A shares. The listing will be the largest in HK since Alibaba.
- Zhongji Innolight is the world’s largest manufacturer of optical transceiver modules, holding 21.2–23.1% global market share in datacom optical modules as of 2025.
- The company supports global cloud and AI computing infrastructure with strong hyperscaler qualification relationships with Google, Amazon, Meta, and Nvidia, its largest customers.
3. Initial Thoughts on the Yangtze Memory Technologies Co (YMTC) IPO
- YMTC is getting ready to complete its IPO in China in 2H 2026/1H 2027. Many investors are lining up to subscribe to the YMTC IPO after the huge CXMT IPO.
- Reuters has mentioned that YMTC may be pushing internally for a 1 trillion won yuan ($148 billion) valuation target which is 28% of CXMT’s current market cap.
- Both CXMT and YMTC are quickly emerging as formidable competitors to SK Hynix (000660 KS) and Samsung Electronics (005930 KS).
4. Aequitas ECM Weekly (27 July 2026)- Innolight, SBI, Tier IV, Indo-MIM, Gcash, Archion, SinoTruck
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Zhongji Innolight (300308 CH) launched HK’s largest listing so far this year, while SBI Funds Management reopened the Indian markets.
- There weren’t many placements over the past week but we did look at a few upcoming lockup expiries.
5. Aequitas: Shein – The Negatives – Controversies, Down Rounds, Cash Payouts & Earning as Well.
- SHEIN Global Holdings (SHEIN HK), a global online fashion and lifestyle company, aims to raise up to US$3bn in its Hong Kong listing.
- Shein is a global online fashion and lifestyle company serving approximately 273m active customers in approximately 160 markets in 2025.
- In this note, we talk about the not-so-positive aspects of the deal.
6. Zhongji Innolight (中际旭创) IPO Trading
- Zhongji Innolight raised HKD 52,891m (USD 6,746m) from its global offering and will list on the HKEx on Thursday, July 30, 2026.
- In our previous notes, we looked at the company’s fundamentals and the deal terms.
- In this note, we provide an update for the IPO before its trading debut.
7. IPO Databook: Beijing ESWIN Computing Technology (HK) – Jul 2026
- Beijing ESWIN Computing Technology Co., Ltd. is a RISC-V oriented chip product provider in China, researching and designing chips, chipsets, and circuit boards. It was China’s largest domestic smart device.
- Beijing ESWIN Computing Technology served 220 customers worldwide and was China’s largest domestic smart device human-machine interaction chip product provider in 2025.
- The company reported a loss of RMB(1,515,844) thousand for 2025 and net cash used in operating activities of RMB(1,171,001) thousand.
This content is AI-generated and displayed for general informational purposes only. Please verify independently before use.
8. Nvidia to Acquire a 4.5% Stake in Naver for About $1 Billion
- On 27 July, it was announced that NVIDIA plans to purchase a 4.5% stake (7.24 million shares) in Naver for 1.48 trillion won (approximately $1 billion).
- To mitigate the dilution of shareholder value resulting from the issuance of new shares, Naver plans to cancel 4.9 million treasury shares (3.1% of outstanding shares) on 3 August.
- The capital infusion from Nvidia is likely to put a greater emphasis on additional sales and profit growth from Naver’s AI infrastructure related businesses.
9. SHEIN Global Pre-IPO: Key Positives and Negatives
- SHEIN Global Holdings (SHEIN HK) aims to raise HK$15.7-23.5bn in its upcoming HK IPO and has passed the listing committee hearing. It recorded losses of US$99m in 1Q26.
- Key positives are its leadership position with global presence, excellent brand portfolio with comprehensive offerings, and unique operating model and end-to-end intelligent supply chain.
- Key negatives are its exposure to regulatory and tariff uncertainties, geopolitical and supply chain scrutiny, and challenges from intensifying competition.
10. Aequitas: Manipal Health IPO – RHP Updates and Thoughts on Valuations
- Manipal Health Enterprises (MHEL) is looking to raise up to US$960m in its upcoming India IPO.
- MHEL operates a pan‑India network of multispecialty hospitals delivering a range of care services, from outpatient services to complex tertiary and quaternary interventions.
- We have looked at the past performance in our previous note. In this note, we talk about the RHP updates and valuations.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: Innolight A/H Listing – Updated Peer Comp and Thoughts on Valuations
- Zhongji Innolight (300308 CH) one of the world’s largest optical transceiver manufacturers, now aims to raise around US$7bn in its H-share listing.
- Innolight was the global leader in 2025 in optical modules, with its products being in high demand for data centers.
- In our previous notes, we have looked at the company’s past performance and recent filings updates. In this note, we talk about the likely A/H premium/discount.
2. [Japan Offering] ARCHION (543A) Prices Today (?) – Big Picture Growth Priced Cheaply
- The mega-offering-slash-re-IPO of Archion (543A JP) likely prices today. This is 900mm new shares for ~US$1.6bn of which 40% (US$630mm) goes to internationals, 60% to domestics.
- There’s a bunch of index buying to do between now and end-October. More than I originally thought due to one recent data point.
- The stock has NOT gotten crushed in the last two weeks despite indications the sellers wouldn’t mind. That tells me this is priced except for print risk.
3. Aequitas: Innolight A/H Listing – Decent Pricing, Strong Cornerstone
- Zhongji Innolight (300308 CH) (ZI), one of the world’s largest optical transceiver manufacturers, aims to raise around US$7bn in its H-share listing.
- Innolight was the global leader in 2025 in optical modules, with its products being in high demand for data centers.
- We have looked at the past performance and likely A/H premium in our previous note. In this note, we talk about the IPO pricing.
4. Innolight H Share Listing: The Investment Case
- Zhongji Innolight (300308 CH) is a leading global provider of optical interconnect solutions. It is seeking to raise US$7 to US$8 billion.
- The principal products, optical transceivers, are compact devices that convert electrical signals into optical signals, and vice versa, to enable high-speed, energy-efficient and low-latency data transmission.
- The investment case is based on strong market position, AI infrastructure-fuelled revenue growth, margin expansion, cash generation and a strong balance sheet.
5. Zhongji Innolight (中际旭创) A+H IPO: Analysis of Deal Terms
- Zhongji Innolight, a global supplier of optical transceivers, launched its IPO to raise USD 7,021m through an A+H listing. GS, CICC, MS, and GF are the deal sponsors.
- In this note, we look at the deal terms and provide our thoughts on valuation for the company.
- We analyze reference A+H transactions, cornerstone and sponsor performance and assess the risk-reward of the deal.
6. Archion (543A JP): The Current Playbook
- Since the announcement of the US$1.7 billion secondary offering, Archion (543A JP)’s shares have declined 5.8% to the undisturbed price of JPY313 (3 July).
- It is instructive to look at recent large Japanese placements to understand the potential trading pattern. Archion’s share decline is lower than the median of recent large placements.
- The preliminary pricing range is JPY250 to JPY300 per share. The offering will likely be priced on 22 July. The average large Japanese placement tends to generate positive returns.
7. Innolight H Share Listing (3308 HK): Valuation Insights
- Zhongji InnoLight (3308 HK), a leading global provider of optical interconnect solutions, has launched an H Share listing to raise US$7.0 billion.
- I discussed the H Share listing in Innolight H Share Listing: The Investment Case.
- The proposed AH discount of 23.3% (based on the close on 21 July A Share price) is attractive, and I would participate in the H Share listing.
8. Aequitas: A/H Premiums and Recent 48 Deals Performance – Better Performance, a Look at Correlations
- With over 48 A/H listings since the start of 2025, we look back at some of the trends from the recent listings.
- In this note, we will also talk about the overall performance of the cohort of 48 deals. Overall, A/H listings since 2025 have reversed the trend of past A/H listings.
- We also have a look at some of the factors that might impact the post deal performance.
9. Zhongji InnoLight (3308 HK) IPO: Assessing the Valuation
- The IPO of Zhongji InnoLight (3308 HK), a leading global provider of optical interconnect solutions, which seeks HK$54.5bn, is the largest since 2019.
- Its FY25-28F EPS CAGR will reach 89.8%, underpinned by the jump in revenue and expansion in margin. Its 1Q26 net profit has already surged by 262.3%.
- The IPO is priced at a 17.7% HA discount. At a HK$1.2trn market capitalisation, pegging it to its A-share will give a price of HK$1,227, or a 21.5% upside.
10. Pre-IPO Zhongji InnoLight (PHIP Updates) – Some Points Worth the Attention
- ZHONGJI adopts a “sales-driven” approach. The core is to respond quickly to customer orders rather than stockpiling goods for sale.Supply chain is efficient during prosperous periods but vulnerable during disruptions.
- The uncertainty of the technical route and the development progress of the 3.2T optical transceivers are both turning points. The outcome of the technological competition is far from being settled.
- The recent sharp fluctuations in A-shares may affect the pricing benchmark for H-shares. In our view, a comfortable valuation range could be P/E of 25-35x, based on 2026 forecast.
Receive this weekly newsletter keeping 45k+ investors in the loop
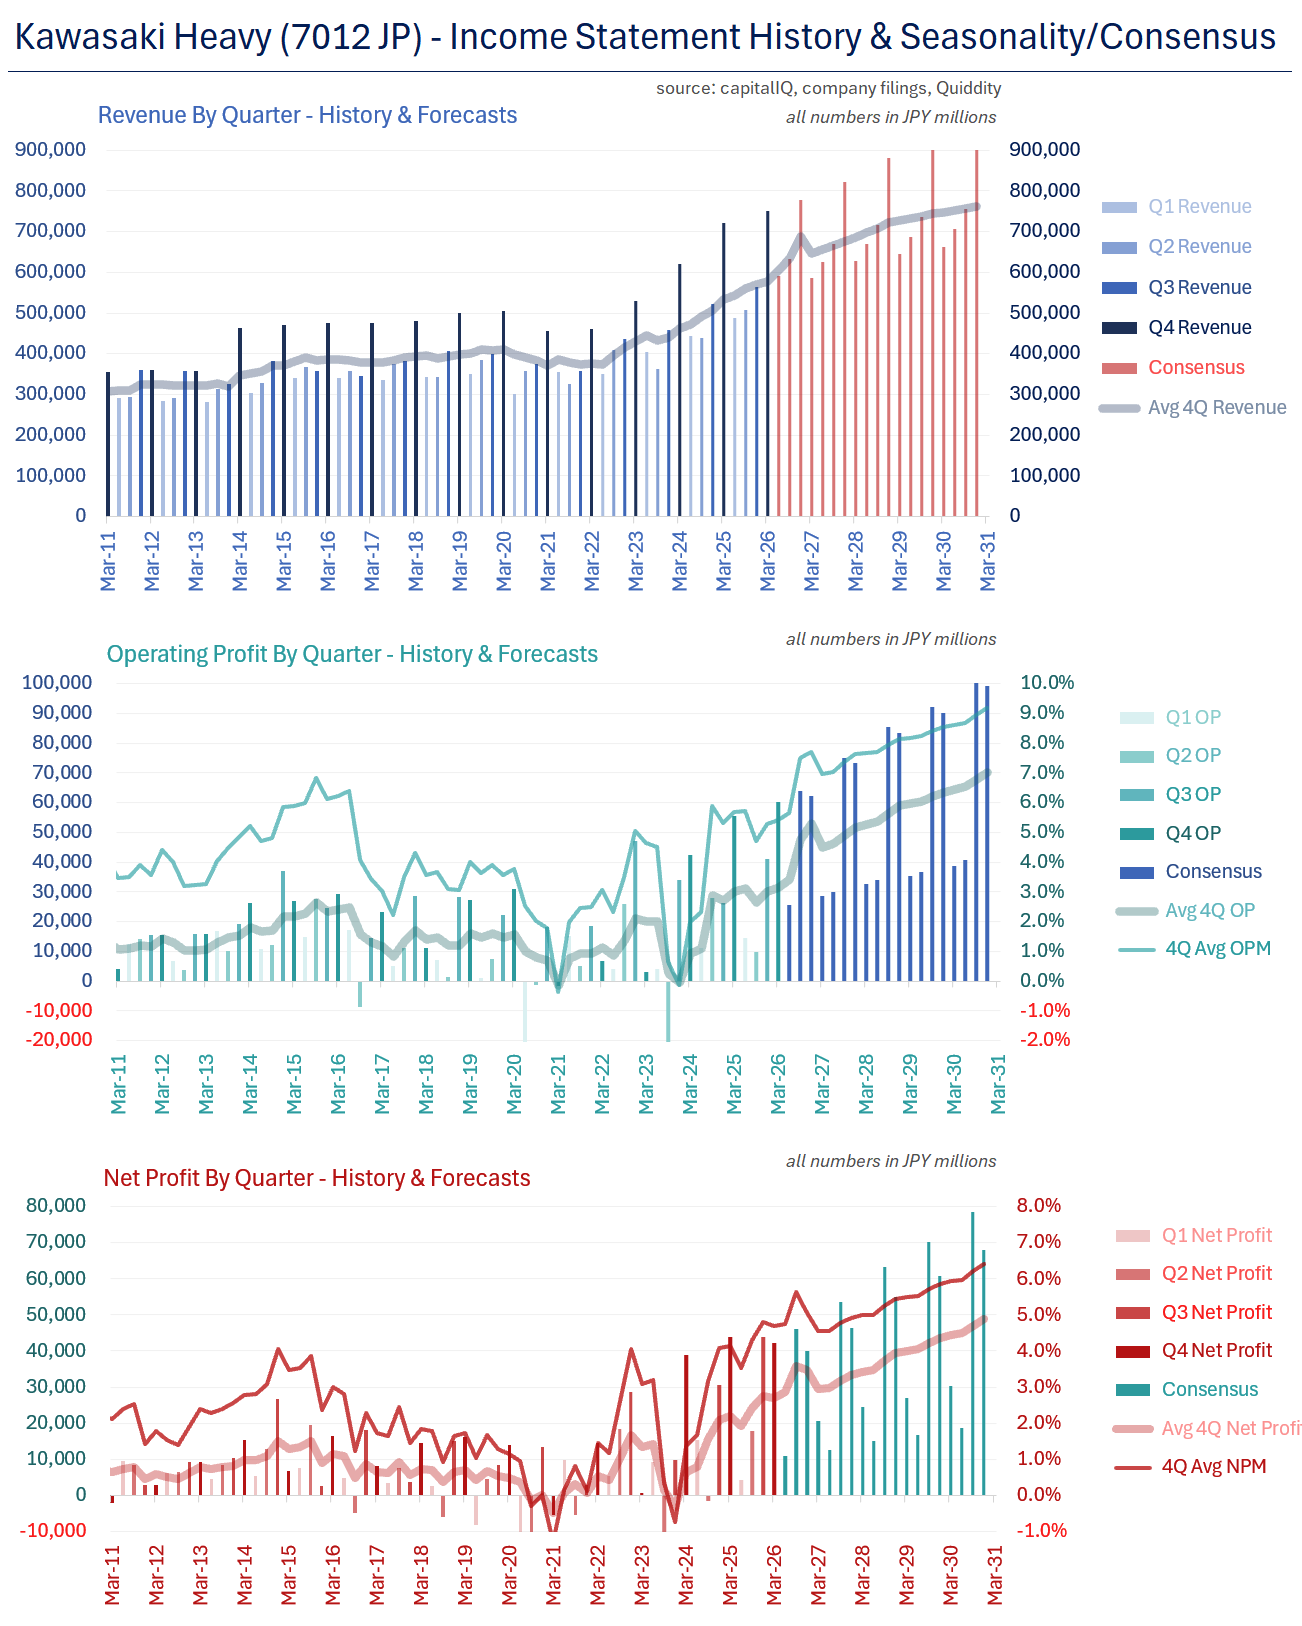
1. [Japan Offering] Kawasaki Heavy (7012) Deal Probably Prices Today
- Kawasaki Heavy Industries (7012 JP) is down about 9% outright since a Reuters article mid-day 1 July suggested they’d be raising equity. TOPIX is up tiny in the same period.
- An equal-weighted basket of Mitsubishi Heavy Industries (7011 JP) and Kawasaki Heavy Industries (7012 JP) is up 2.25%. The KHI/Peers ratio had already come off recent highs too.
- At a discount today’s close, this looks like a good deal relative to peers, but it isn’t a total no-brainer.
2. Top Five Reasons Why Samsung Electronics Should List Its Shares as ADRs in the U.S.
- Bloomberg published an article today that Samsung Electronics is in early discussions of a potential listing of ADRs in the U.S.
- The number one reason why Samsung Electronics should list its shares in the U.S. is that this could reduce the valuation discount on the company relative to its global peers.
- In terms of Samsung Electronics completing an ADR listing, I think the overall process could take about 2-3 years.
3. Aequitas: Archion Placement – Past Large Deals Performance and Thoughts on Valuations
- Toyota Motor (7203 JP) and Daimler Truck Holding (DTG GR) (DT) are looking to raise up to US$1.7bn via selling around 35% of their stake in Archion (543A JP).
- The news of the possible deal had been leaked ahead of the actual launch, although the overall selldown was very well flagged.
- We have looked at most aspects of the deal in our earlier notes. In this note, we talk about the recent share price performance and provide our thoughts on valuations.
4. CXMT Corporation (688825 CH) IPO: Valuation Insight
- CXMT Corporation (688825 CH) concluded its IPO price at Rmb8.66, and we estimate this equals 5x PER for FY26 and 3.4x for FY27.
- It is inexpensive relative to global peers, as they are trading at an average of 8.1x and 6.1x, respectively. Normally, A-shares trade at a higher multiple than global peers.
- Applying the Hang Seng AH premium on the IPO, there is a 74.5% upside. Aggressively, if GPU companies are used as references, it may even provide a 3x upside.
5. SK Hynix (SKHY) Delivers Strong Institutional Debut Following IPO Prophet’s 9.20/10 Pre-IPO Rating
- After awarding SK hynix (Nasdaq: SKHY) — a 9.20/10—the company’s U.S. debut largely validated our pre-offering thesis.
- From the opening print through the closing bell, institutional demand remained firmly in control as the stock generated an immediate Bullish Sentiment signal and never produced a Bearish Sentiment signal despite normal intraday profit-taking.
- SK hynix opened trading at $170.00, a substantial premium to its $149.00 IPO price, immediately confirming strong investor demand for one of the year’s most anticipated semiconductor offerings.
6. Aequitas ECM Weekly (13 July 2026)-SK Hynix, Zhipu, Corex, Biren, Gigadevice, Archion, SBI
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, a lot of the listing last week didn’t end up doing much.
- There are quite a few lockup expiries coming up, while there were a number of placements as well over the past week.
7. SBI Funds – IPO Review – Weak Performance Impacting AUM Momentum
- SBI Funds is India’s largest AMC ($308bn AUM including $132bn MF AUM with 15.3% market share). It is also the largest PMS manager (39.7% share) and SIF platform (28% share)
- The company has been losing market share in recent years due to underperformance in several equity schemes. Starting valuations are down at PE of 38x, while peers trade at 40-50x.
- The issue opens on 14th July @ 575 per share. A secondary with both SBI and Amundi selling 10% stake each to be pared down in the next 3 years.
8. Aequitas: SBI Funds Management IPO – Will Trade Inline with Its Large Peers
- SBI Funds Management is looking to raise about US$1.2bn in its upcoming India IPO.
- SBI Funds Management is an asset management company(AMC) involved in managing mutual funds, providing portfolio management services, managing alternative investment funds and ETFs, and providing advisory services to offshore clients.
- We have looked at the past performance in our previous note. In this note, we talk about the RHP updates and valuations.
9. Head of US$150M Postage Fraud Scheme Tied to Chinese EComm Parcels Sentenced to Prison in California
- More than three years after her arrest, Lijuan Chen was sentenced to 30 months in prison
- The California woman ran a scheme linked to tens of millions of parcels from China
- We believe US Feds may develop case against the companies who benefited from the fraud
10. Aequitas: BizLink Holding GDR Early Look – Proposed GDR and CB Issuance Amid Strategic Expansion
- Bizlink Holding (3665 TT) (BizLink) is looking to raise up to US$350m in its upcoming GDR offering. The firm is also looking to raise another US$500m via convertible bonds.
- In July 2026, Bizlink announced its board’s resolution to issue between 4.5-6m common shares via a GDR offering.As per the firm, proceeds will be used to purchase overseas raw materials.
- Similar to previous GDR listings, the deal is a long drawn out process with the firm required to jump through a number of board/shareholder/regulatory approval loops.
Receive this weekly newsletter keeping 45k+ investors in the loop
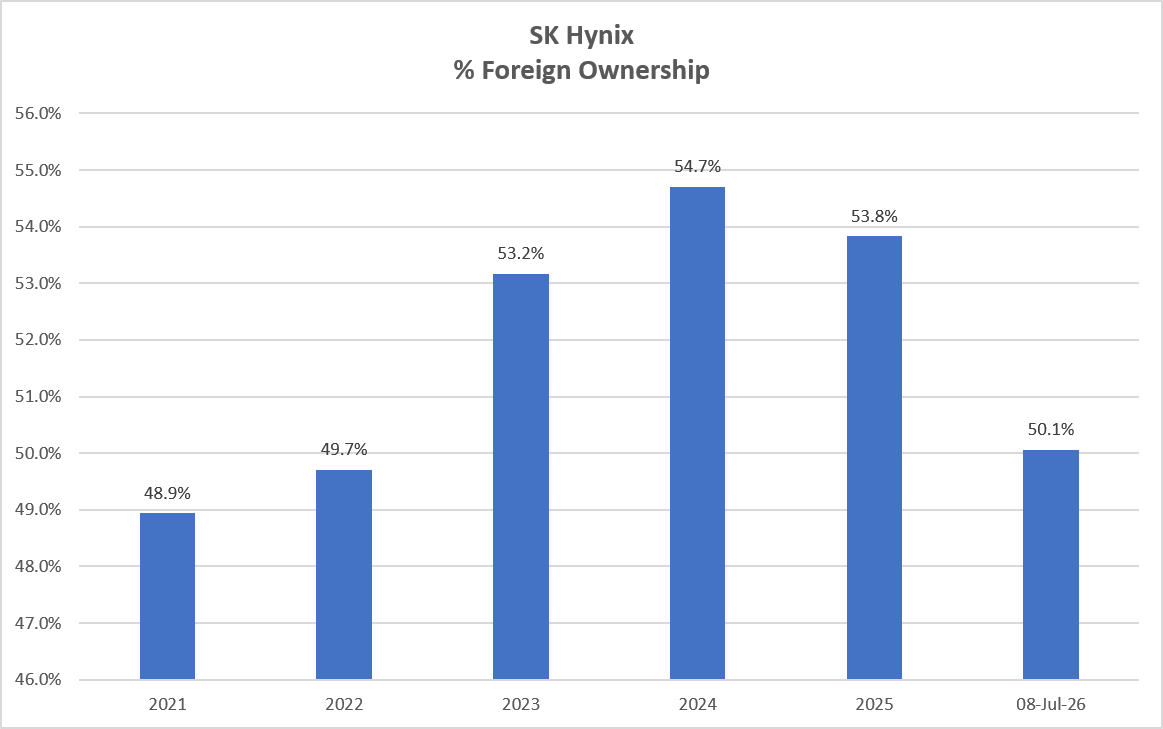
1. SK Hynix: What If Too Many Investors Are Gearing Up for the Buy ADR/Sell Local Shares Trade?
- With the listing of SK Hynix ADR on NASDAQ on 10 July, many investors are considering various trading strategies, including just buying the ADR or putting on a long-short trade.
- In this insight, I highlight how too many investors may be gearing up on the latter trade (buying the ADR and shorting the local shares).
- The premium for SK Hynix ADR versus local shares could potentially be as high as 12-17% initially after the ADR trading but could decline gradually in the months ahead.
2. Mapping Out the Moving Parts Around Hynix ADR Headroom
- Citi ADR headroom timing is not just about premium management. It is equally driven by how quickly Korean regulators get comfortable with impacts on KOSPI liquidity and the FX tape.
- Near term focus is FX over KOSPI turnover. ADR conversion can add repatriation risk, but real money driven flows create USD demand and support KRW, giving regulators a usable lever.
- If post listing pressure hits Hynix local and semis and destabilizes FX, regulators may step in aggressively, flipping positioning fast and driving a sharp bounce. Key setup to watch.
3. Aequitas: SK Hynix US$27bn ADR Listing – Discount Has Already Been Narrowing
- SK Hynix (000660 KS) (SKH), a leading global memory producer, aims to raise up to US$27bn via an ADR listing.
- We have looked at the past performance and other deal dynamics in our previous notes.
- In this note, we talk about the recent updates and deal dynamics.
4. [Japan Offering] ARCHION (543A) Incoming – Big Re-IPO Now Smaller, Better
- Friday after the close the Nikkei reported that Toyota Motor (7203 JP) and Daimler plan on offering ¥200-300bn of shares in Archion (543A JP) within the month, perhaps next week.
- This has been VERY well-flagged. OR should have been. I wrote about it in June 2025, then Jan 2026, then March 2026, then a few days later in April.
- They say 30% of shares out or ~900mm shares which would be the full offering, but the ownership drop looks like 35.2% in their diagram. It is a BIG offering.
5. On the Timing of Hynix’s Underlying Stock Split
- Market consensus is EGM around November to approve split and authorized share increase, timed with post listing 25 percent headroom activation, with split completion likely in early December.
- Post ADR listing, stock split expectations and potential parity change could compress ADR shorts and hedges, increasing squeeze risk and making timing a key post listing setup variable.
- Stock split toward 1 to 1 parity could drive quant inflows, faster trading versus peers, and higher microstructure noise with sharper tails, key for post ADR listing positioning.
6. [Japan Offering] ARCHION (543A JP) Offering Announced – The RE-IPO Is On
- After the Nikkei’s article Friday, at the lunch break today, Archion (543A JP) announced Daimler Truck and Toyota Motor (7203 JP) would each sell 394mm shares in an offering.
- The offering will have a greenshoe of 118.2mm shares so the total comes to 906mm shares, to be priced 22-27 Dec and placed 5 days later.
- The price is lower as the stock is lower. Some index demand now, more later. It is a re-IPO with the offering size at 600% of current MaxRealWorldFloat.
7. Archion (543A JP): A US$1.7 Billion Secondary Offering
- Archion (543A JP) has announced a secondary offering of 787.9 million shares (906.0 million including overallotment), worth around US$1.4 billion (US$1.7 billion including overallotment).
- The offering was expected, as it would enable Toyota Motor and Daimler Truck to reduce their respective shareholdings to 25% of the total shares, thereby increasing the tradable share ratio.
- The offering, as a percentage of outstanding shares, is the fourth-highest, and, in terms of ADV, the highest among large Japanese placements since 2021.
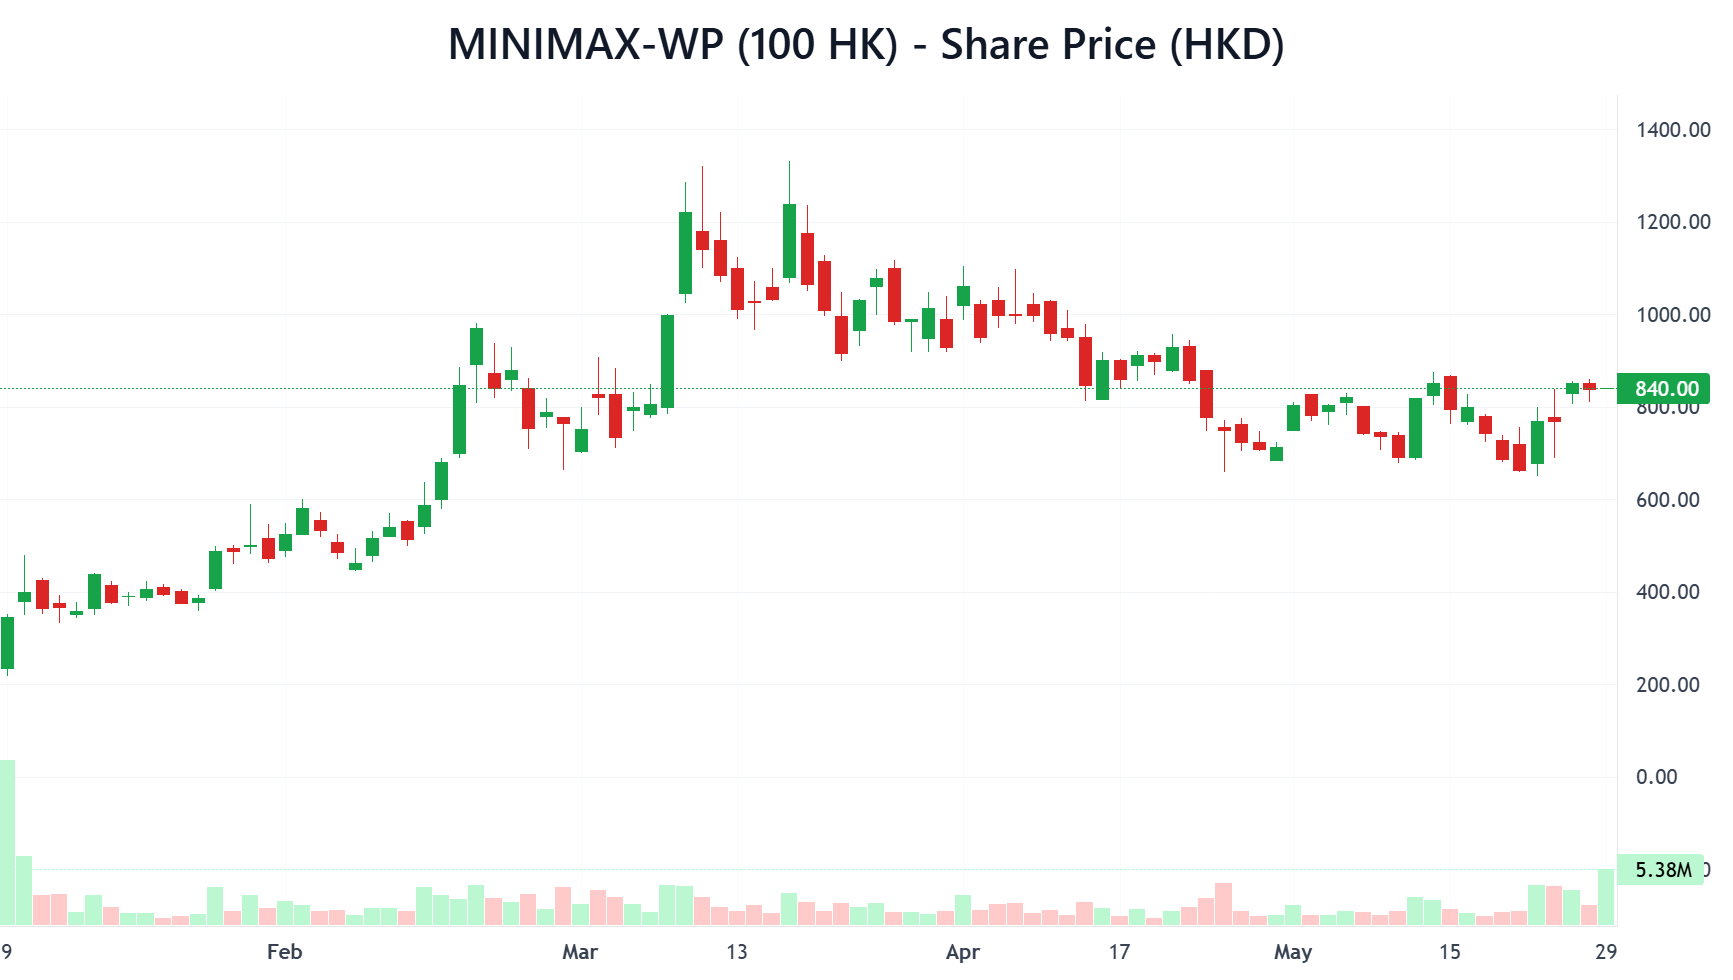
8. MINIMAX-W: Pre-Lock-Up Expiry Update, Positioning Revised
- The 9 July wave. We detail the 153.5m-share six-month unlock, its holder composition, and the full cornerstone book.
- Seller incentive. We assess how the share-price reset from the March peak changes holders’ motivation to exit.
- Positioning signals. We track token usage after the M3 launch, consensus revisions, and short positioning into the event.
9. SK Hynix (SKHY): Demand Continues to Pour In for Mega ADS Offering
- Channel checks indicate SK Hynix’s ADS offering is 5x+ oversubscribed, driven by strong demand from technology specialists, sovereign wealth funds, and global institutions.
- The AI memory leader enters the U.S. market with dominant HBM leadership, broad international investor interest, and books closing ahead of Friday’s debut.
- We believe SK Hynix remains attractively valued versus Micron Technology despite superior HBM leadership and exposure to the accelerating AI infrastructure buildout.
10. SK Hynix (SKHY): Peeking at the Prospectus of a Korean Based Semiconductor Company
- AI memory leader with 56% HBM market share, positioned at the center of accelerating AI infrastructure and data center spending.
- Revenue nearly tripled in Q1 2026 as rising HBM demand and pricing drove exceptional profitability and operating leverage.
- U.S. ADS listing offers investors exposure to a global semiconductor leader benefiting from one of the strongest AI-driven memory cycles in history.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Hynix ADR Listing Timing and Expected Rollout, Plus Likely Conversion Book Open Mechanics
- Assuming NASDAQ listing on July 10, pay in hits July 14, triggering issuance; KSD registration follows, with KOSPI listing July 29, marking first ADR to local conversion window.
- Street view is wide Form F-6 over registration, but Citi may keep conversion shut post July 14 to defend ADR scarcity premium despite volatility risk.
- Watch ADR premium and ADTV; expect ~1% gradual tranche releases. If premium holds 5-10% post July 14, Citi likely steps in, signaling arb into local or GDR versus ADR spreads.
2. Hynix Filed F 6: 25 Percent Headroom, Phased Rollout Expected
- 1.78bn ADS equals about 25 percent float. Syndicate set headroom far above 2.5 percent, fully rolling GDR into ADR with a more aggressive than expected structure.
- Key is Citi book stance. Expected phased rollout: initial GDR to ADR conversion, then capped flow after one month, and full 25 percent open by 3 to 6 months.
- Early 5 to 10 percent ADR premium looks embedded. Trade is to track widening then fade via ADR short versus KOSPI long as window expansion guidance emerges.
3. [Japan Offering] Kawasaki Heavy (7012 JP) Looking at an Offering
- Today Reuters carried an article suggesting Kawasaki Heavy Industries (7012 JP) would soon announce a ¥200bn capital raise – combo equity and convertible bond offering – in an ABO.
- ¥200bn would be a 23% increase in equity but about 6-7% dilution in realtime (equity+CB delta). ¥100bn of each would be 3x ADV, 4.8% of Shs Out, 10.7% of MRWF.
- The shares fell 8% today, putting them 13% off the recent high as a ratio against MitHeavy+IHI. The shares aren’t cheap, but this looks to be “easy.”
4. Aequitas ECM Weekly (29 June 2026) – SK Hynix, Kioxia, Lingyi, SG Micro, Circuit Fab, Merdeka, Anker
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, SK Hynix (000660 KS) announced the timeline for its ADR, and Kioxia Holdings (285A JP) was said to be finalising banks as well for its ADR.
- Over the past week, there were a number of placements in India, along with a few large deals in Hong Kong as well.
5. [Japan Offering] Kawasaki Heavy Offering Details Out
- Kawasaki Heavy Industries (7012 JP) has just announced their capital raising intentions. ¥93.7bn (estimated) of shares (37.35mm shares), and ¥100bn of 2031/2033 convertible bonds.
- The Reuters article presaging this seemed to say this would be aimed at International Investors (i.e. an ABO). The extraordinary filing to EDINET suggests an Open Offering to the same.
- A bookbuilding between 14-16 July, but only for international investors. No greenshoe. Weird. 2.8x ADV, 4.5% of shares out, 10% of Max Real World Float. Should be easy. But weird.
6. Foundation Healthcare Pre-IPO: Leadership Amid Favorable Market Dynamics to Drive Sustainable Growth
- Foundation Healthcare, Singapore’s largest private multi-specialty healthcare network, has filed for Singapore IPO. The IPO will consist of fresh issue as well as OFS from SeaTown (indirectly owned by Temasek).
- The company plans to use IPO proceeds to fund acquisitions in Singapore, investments to support expansion plans in new geographies, and for general corporate and working capital purposes.
- Foundation Healthcare has a proven track record of strong growth in revenue and Adjusted EBITDA. With scalable business model, bottomline outpaced revenue growth.
7. Ecopro BM: Rights Offering of 1.2 Trillion Won
- On 30 June, Ecopro BM (247540 KS) announced that it will conduct a rights offering capital raise worth 1.2 trillion won.
- The planned issue price for the rights offering is 121,200 won, and the final issue price will be determined on October 12.
- Despite its expected better sales and profits in 2027, the company’s valuation multiples are unattractive. It is trading at P/E of 143.6x in 2027 and 75.6x in 2028.
8. Aequitas: Guangdong Dtech Technology A/H Listing – Peak Growth, Margins and Valuations
- Guangdong Dtech Technology aims to raise around US$600m in its H-share listing.
- Dtech is an integrated provider of precision manufacturing solutions for key process segments of the global printed circuit board (PCB) fabrication value chain.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
9. [Japan Offering] Retailer Valor Holdings (9956) Raising New Money for New Stores
- Today after the close, Valor Holdings (9956 JP) announced an equity offering worth ¥20bn at last price, which will probably mean a lower strike.
- The Use of Proceeds is new stores and refurbishment of existing stores in Gifu, Aichi, and Tokyo.
- Valor also announced the terms of its Capital and Business Alliance with Kohnan Shoji (7516 JP) after the basic agreement signed in February and Kohnan’s April Tender for Alleanza HD.
10. Eacon Group IPO: Worth Mining For Value
- Eacon Group launched its Hongkong IPO aiming to raise up to HK$2.3B (~ US$ 293M). They focus on the commercial deployment of autonomous driving solutions in the mining industry.
- Eacon Group intends to use the IPO proceeds for research & development, IT infrastructure development, overseas business expansion, strategic alliance/acquisition and working capital.
- The medium-term outlook for Eacon Group looks bright. We would recommend investors with to consider the name, given its potential.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Hynix ADR: Mid July Listing, 15% Headroom, and 1:1 Conversion
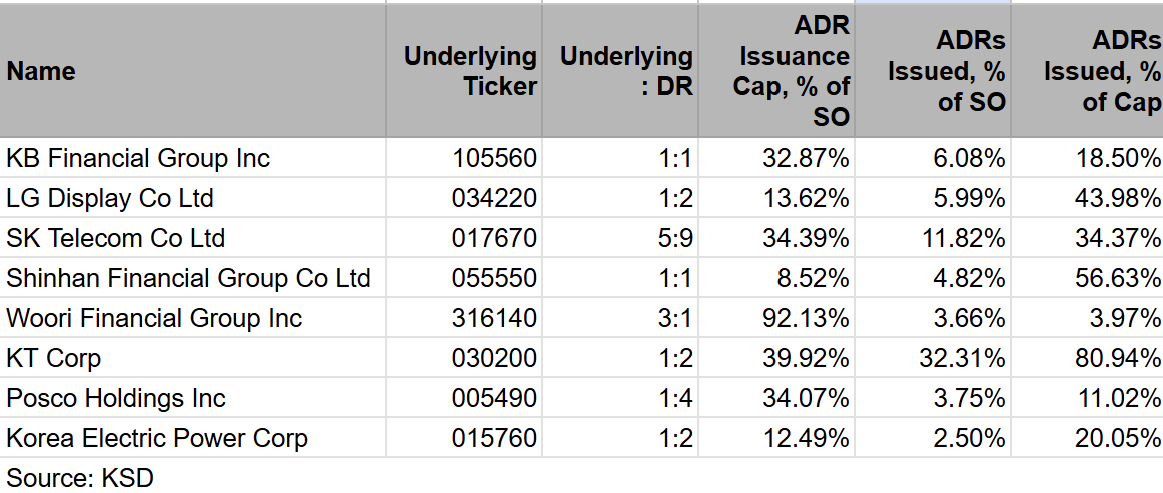
- Street is converging on about 15 percent total headroom, combining 2.5 percent issuance and 12.5 percent conversion, balancing passive inflow demand and Korean regulatory concerns over local market liquidity.
- DR conversion is effectively locked at 1 to 1, with passive flows expected to clear supply, supporting early arbitrage while preserving future stock split optionality.
- Focus on three way dynamics between local upside, ADR subscription demand, and post listing arb, with positioning driven by passive inflow versus headroom supply demand mismatch.
2. SK Hynix – ADR Listing on 10 July
- It has been confirmed that SK Hynix (000660 KS) plans to complete its ADR listing on the NASDAQ exchange on 10 July.
- Estimated issuance price is 2,555,000 won per share and the company projects total proceeds of 45.5 trillion won (US$29.4 billion) (2.5% of outstanding shares).
- The currently stated issuance price is for reference only and does not represent the actual final issuance price.
3. Hynix ADR Filing: Listing July 22 to 29, Headroom TBD, Conversion 1 to 10, Still Clean for Arb Flow
- Street focus is sizing, with 2.5 percent primary ADR print in line. Full convertibility and true ADR float still unclear, with ~15 percent headroom assumed pending Form F-6.
- Pricing likely July 9 flexing to July 16 backstop. Post funding mechanics via local share creation, KSD and SEC timing imply listing window July 22 to July 29.
- Conversion ratio revised to 1 to 10, still clean simple structure, supportive of early stage arb flow and initial secondary liquidity formation.
4. Aequitas: SK Hynix ADR Listing – Now Looking to Raise up to US$30bn – Updates, Valuation, ADR Prem
- SK Hynix (000660 KS) (SKH), a leading global memory producer, aims to raise up to US$30bn via an ADR listing.
- SKH has now announced the details for its raising, which could see the ADR’s being listed next month.
- We have looked at the past performance and other deal dynamics, in our previous note. In this note, we talk about the recent updates.
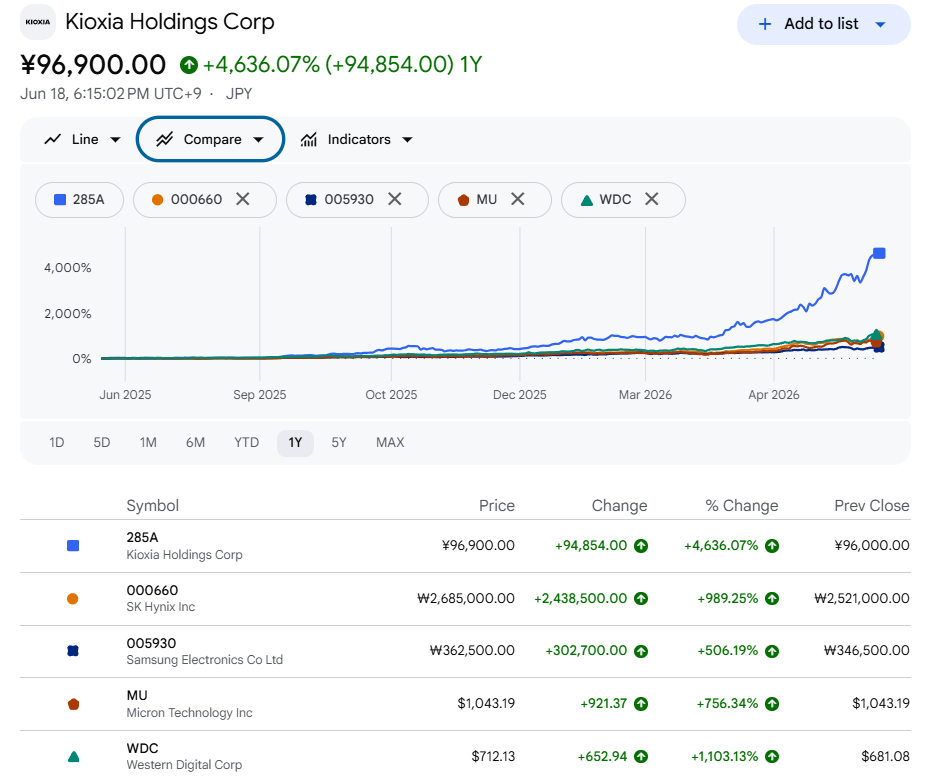
5. Kioxia Targets an ADS Listing in the U.S. In the Spring of 2027 – Implications
- On 25 June, Kioxia Holdings (285A JP) announced that it plans to complete its ADS in the U.S. in the spring (around April to June) of 2027.
- The company is also considering a stock split on the local shares to make them more accessible to retail investors.
- Timing of the ADS offering (spring of 2027) suggests Kioxia is highly confident of its outlook next 9-12 months.
6. Aequitas: Zhipu Lockup Expiry – US$7bn Release After 19x Gains, US$1bn+ H-Share Offering
- Knowledge Atlas Technology (2513 HK) (Zhipu) raised around US$640m in its Hong Kong IPO in January 2026. The lockup on its cornerstone investors is set to expire soon.
- Zhipu is one of the leading players in China’s domestic LLM space. As per media reports, the company could look to undertake an H-share offering as well.
- In this note, we will talk about the lockup dynamics and possible placement.
7. Pre-IPO Anker Innovations Technology (A/H Listing) – The “Shallow-Sea Theory” Does Not Work Well
- Anker’s performance maintained steady growth, but growth rate in 2025 was significantly lower than 2024 and the quality of cash flow deteriorated markedly, due to 2025 rechargeable battery recall incident
- The failure of Shallow-Sea strategy is essentially a mismatch between expansion logic and market reality. Anker attempted to conquer niche category using light-asset logic, but each category has long-standing competitors
- Considering Anker is a benchmark for Chinese consumer electronics industry, with high-quality profit performance (24% ROE)/multi-category matrix to diversify risks, reasonable valuation could be 16-20x P/E based on 2026 forecast.
8. Anker Innovations H Share Listing (668 HK): Valuation Insights
- Anker Innovations Technology (668 HK), a leading global provider of core offshore wind power equipment, has launched an H Share listing to raise US$590 million.
- I discussed the H Share listing in Anker Innovations H Share Listing: The Investment Case.
- The proposed AH discount of 25.6% (based on the close on 22 June A Share price) is attractive, and I would participate in the H Share listing.
9. Crealights Technology (1191 HK) IPO: Lighting Up
- Crealights Technology (1191 HK), an optoelectronic interconnection product provider, targets to raise HK$1.4bn from IPO. Its growth is solid, as revenue surged 6x in FY23-25.
- For the next three years, it will ride on AI spending, with revenue growing by a CAGR of 44.3%. However, heavy investments will sustain its losses.
- At 4.5x FY26 P/S, the IPO is inexpensive relative to peers. It justifies a 20% discount to CIG Shanghai (6166 HK), or 5.1x P/S, implying at least 15% upside.
10. Aequitas: Jio Platforms Ltd Pre-IPO Tearsheet
- Jio Platforms Ltd (1797135D IN) is looking to raise upto US$3.75bn in its India IPO, which will be run by 19 banks including Citi, MS, JPM, HSBC, GS, and others.
- Jio Platforms Ltd (JPL) is a technology and digital services platform company promoted by Reliance Industries, built on a proprietary digital technology stack and pan-India connectivity infrastructure.
- Through subsidiary, Reliance Jio Infocomm, the company provides mobile and fixed broadband connectivity to over 524m customers, making it India’s largest digital connectivity platform, as per the Analysys Mason Report.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Kioxia ADS Listing on NYSE Preview
- Kioxia Holdings (285A JP) is getting ready to complete an ADS listing on the New York Stock Exchange (NYSE) in the next several months.
- Although the details of the ADS offering are not available, I believe the potential size offering could be about US$10 billion to US$20 billion or more.
- Likely sellers are Bain Capital and Toshiba. If ADS offering is US$20 billion, this represents 6% of Kioxia’s market cap and 17% of Bain Capital and Toshiba’s stakes in Kioxia.
2. I JUST SHORTED SPACEX: Should I Worry?
- SpaceX (SPCX US) share price is being driven by a thin float that will grow rapidly before year-end as lockup expirations greatly increase supply.
- The S&P rejected a fast-track for the shares, meaning the largest passive and active index buyers will not provide near-term support.
- The company’s Q2 earnings release in late July/early August will mark the first significant share lockup expiration, followed by a barrage of further share releases through early December.
3. Aequitas: Kingboard Laminates Holdings Placement – Recent Deals Haven’t Done Well, US$1.5bn Raising
- Kingboard (148 HK) is looking to sell around a 4.3% stake in Kingboard Laminates (1888 HK) to raise up to US$1.5bn via a secondary selldown.
- Kingboard Laminates Holdings Limited is a manufacturer of laminates used in printed circuit boards, and is one of the world’s largest suppliers to the electronics industry.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
4. Aequitas: Kioxia ADS Listing – Part 1 – Early Look – At the US$5-10bn+ Raising
- Kioxia Holdings (285A JP), a leading global flash memory producer, aims to undertake an ADS listing.
- In May 2026, Kioxia announced that it was preparing for listing ADS in the US. The timing and size of the deal remain uncertain.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
5. Hankyung Business Daily Mentions SK Hynix ADR Amount Could Be Nearly 40 Trillion Won
- On 16 June, Hankyung Business Daily mentioned that SK Hynix (000660 KS)’s ADR amount could be nearly 40 trillion won ($26.5 billion).
- According to SK Hynix, it refuted Hankyung Business Daily’s comment about shareholder return policy of 100 trillion won.
- SK Hynix’s ADR offering could be completed sooner than anticipated after mid-July.
6. Boston Dynamics – An IPO Likely on NASDAQ in 1H 2027
- In this insight, I discuss the likely IPO of Boston Dynamics in Nasdaq in 1H 2027. Boston Dynamics is the crown jewel robotics company for the Hyundai Motor Group.
- Boston Dynamics’ valuations have recently surpassed $20 billion. In recent weeks, there has been an increased speculation of Samsung Electronics potentially acquiring a 9.9% stake in Boston Dynamics from SoftBank.
- If there are increased news flow about Boston Dynamics’ valuations continuing to rise further, the biggest beneficiary (in terms of impact on share price) could potentially be Hyundai Glovis.
7. Aequitas: Kioxia ADS Listing – Part 2 – Past Deals, Shareholder Overhang, Valuations & Memory Cycle
- Kioxia Holdings (285A JP), a leading global flash memory producer, aims to undertake an ADS listing.
- In May 2026, Kioxia announced that it was preparing for listing ADS in the US. The timing and size of the deal remain uncertain.
- In our previous note, we looked at the company’s past performance, in this note we talk about its past deals, shareholder overhang and valautions.
8. Lingyi ITech (1688 HK) IPO: Deserves a Narrower Discount
- With an aim to raise HK$8.2bn of net proceeds, Lingyi iTech (1688 HK)‘s H-share IPO is a sizeable one and should attract interest.
- Earnings record for this high-precision intelligent manufacturing platform is volatile, but should improve in FY27-28. 1Q26 profit drop is distorted by huge exchange losses.
- Priced at 44.6% discount to its A-share and 27.7x PER, the IPO is inexpensive. Assuming a discount of 26.9%, the fair price (HK$13.43) implies a 32% upside.
9. Aequitas ECM Weekly (15 June 2026) – SpaceX, GO, Lingyi, Nexchip, SG Micro, Semi-Tech, BIWIN, ICICI
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, SpaceX (SPCX US) manage to stay above its IPO price, which should help the overall market
- There were a few lockup expiry linked placements in the past week.
10. WUS Printed Circuit (沪电股份) A+H Pre-IPO: Early Thoughts
- WUS Printed Circuit is seeking an A+H listing. CICC and HSBC are the sponsors.
- We look at the company’s core segments: data communications and smart vehicles.
- We discussed our preliminary thoughts on the company’s fair value based on A-H premium.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SpaceX (SPCX US): Demand Picks Up as Investors Place Disciplined Bets on Musk’s Mega IPO
- SpaceX IPO is fully fixed at $135/share, removing price-range signaling and forcing investors to focus directly on scale, demand, and valuation discipline.
- Channel checks suggest ~2–3x oversubscription reflecting more measured bidding given the deal’s unprecedented $75B+ size.
- Tight ~4–5% free float, expanded retail allocation, and Elon Musk’s 366-day lock-up create a structurally constrained supply setup with heightened post-IPO volatility risk.
2. Aequitas: SpaceX IPO Trading – Updates – Ready for Lift Off
- SpaceX (SPCX US), an Elon Musk led Space to AI company, raised around US$75bn (US$86bn including greenshoe) in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- We have looked at the company’s past performance and valuations in our earlier note. In this note, we talk about the trading dynamics.
3. Lingyi ITech (领益智造) A+H Pre-IPO: Early Thoughts
- Lingyi iTech is seeking an A+H listing and has passed hearing. GTJA is the sole sponsor.
- We look at the company’s core segments: electronic devices and automotive and advanced air mobility.
- We discussed our preliminary thoughts on the company’s fair value based on A-H premium.
4. SpaceX (SPCX US) Goes Public: Unassailable Moat, Unanswerable Valuation
- Largest IPO in financial history — but priced beyond fundamentals. Our EV/Revenue FC range is US$1.16-1.60 trillion, or US88.4-122.3/share
- You are buying Elon Musk, not a diversified conglomerate. Stop here if you don’t like the man!
- Starlink is the cash engine; Starship and AI are the long bets.
5. SK Hynix: To Complete an ADR Listing on NASDAQ in August?
- Reuters reported that SK Hynix is likely to list its ADR shares on NASDAQ as early as August. Passive flows on the SK Hynix ADR listing on NASDAQ are significant.
- If SK Hynix decides to raise $15 billion or more from the ADR listing, it is reasonable to estimate iShares Semiconductor ETF (SOXX) to contribute $1.5 billion or more.
- I think there could be enough demand from the large passive investors in the U.S. to contribute to nearly half or more of the total ADR issuance by SK Hynix.
6. SpaceX Isn’t Just the Biggest IPO Ever — It’s the Biggest Test of the IPO Market Ever
- When most companies go public, investors spend their time evaluating the business.
- They study the financials, compare valuations, and decide whether the opportunity justifies the risk.
- SpaceX is different.
7. IPO Rating: Space Exploration Technologies Corp.
- ✅ IPO PROPHET RATING:9.42/10🏦 Deal Quality & Underwriters: 10/10 Space Exploration Technologies Corp. is expected to come public on Nasdaq under the ticker SPCX, offering approximately 555.55 million shares at $135 per share and targeting roughly $75 billion in proceeds.
- The transaction would immediately rank among the largest IPOs ever completed and would represent the public debut of one of the most influential private companies in the world.
- The company operates across commercial launch services, satellite communications, government and defense programs, advanced aerospace systems, space transportation, and global connectivity infrastructure.
8. Aequitas: Powerchip Semiconductor Manufacturing GDR Offering –
- Powerchip Semiconductor Manufacturing (6770 TT) is looking to raise around US$895m, selling 420m shares (28m GDRs) via a GDR offering.
- Similar to previous GDR listings, the firm has undergone a long drawn out process prior to launching the deal, having to jump through a number of board/shareholder/regulatory approval loops.
- In this note, we run the deal through our ECM framework and comment on deal dynamics.
9. Aequitas: BIWIN Storage Technology A/H Listing – Strong Memory Revenue Growth but Low Market Share
- Biwin Storage Technology (688525 CH) (BST), focuses on the R&D, design, packaging, testing, production, and sales of semiconductor memory, and aims to raise around US$1bn in its H-share listing.
- BST is an independent provider of semiconductor memory solutions with expertise across the full technology stack — from controller chip design, memory solution design to advanced packaging and testing.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
10. Aequitas: Lingyi ITech A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Lingyi iTech Guangdong (002600 CH) (002600 CH, LIT), an intelligent manufacturing platform, aims to raise around US$1bn in its H-share listing.
- LIT offers a full range of development and manufacturing capabilities that cover core materials, high-precision functional components, modules and assembled systems for diverse end products.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. MINIMAX-W: Guide to Lock-Up Expiry Waves
- The first unlock wave should dominate near-term liquidity as supply expands sharply.
- Revenue growth does not offset supply risk while losses remain deep and model read-through is mixed.
- Reported short interest shows investors are already positioning before the event.
2. Initial Thoughts on the Anthropic IPO in 2H26 and Key Beneficiaries in Korea
- In this insight, I discuss my initial thoughts on the mega Anthropic IPO in 2H26 and the key beneficiaries of this IPO in Korea.
- I provide a list of top six Korean companies that could benefit from the upcoming Anthropic IPO in 2H 2026.
- Combined market caps of Anthropic, SpaceX, and OpenAI are likely to be around $4 trillion or more. Once listed, this could negatively impact investors’ capital allocation to other tech stocks.
3. SpaceX (SPCX US): Elon Musk’s SpaceX Sets Terms with Surprising Fixed Price, Set to Raise $75b
- SpaceX prices IPO at $135/share for 555.5M shares, eliminating range uncertainty as market shifts to valuation debate ahead of 6/12 listing.
- Mega-Cap offering expected to raise ~$74.4B–$85.7B in proceeds, funding AI compute, Starship/launch expansion, and global satellite constellation growth initiatives.
- Strong institutional backing, expanded retail allocation (~up to 30%), and staged 91-day lock-up create multiple liquidity events and potential post-IPO volatility catalysts.
4. Aequitas: GO Inc IPO – Final Thoughts on Valuations – Domestically Dominant, but Not at a Discount
- GO (581A JP) a leading taxi app in Japan, aims to raise around US$550m via a secondary selldown in its Japan IPO
- GO combines app-based taxi hailing with in-taxi technology to meet the needs of both users and partner taxi operators through services such as ride matching, payment processing and advertising.
- We have looked at the company’s past performance in our previous note. In this note, we will talk about valuations.
5. Aequitas: SpaceX IPO – Fundamental Thoughts on Valuation
- SpaceX (SPCX US) an Elon Musk led Space to AI company, aims to raise around US$75bn in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- We looked at its past performance in our previous notes. In this note, we talk about the fundmental valuation views.
6. Go Inc. IPO: Peer Comparison and Valuation
- GO (581A JP) has set the IPO pricing at ¥2,350-2,400 per share, the secondary shareholders will raise ¥550m at a market cap and valuation of ¥184.4bn and ¥154bn respectively.
- The company is the dominant player in the Japanese ride-hailing market which is underpenetrated. GO has seen strong revenue growth, improved profitability and strong cash flows.
- We have compared the company against Uber, Lyft, Grab and GoTo and our analysis suggests that the IPO is not very cheap.
7. SpaceX IPO Shares Distribution in Korea & Impact on Aerospace/Other Related Stocks in Korea
- There has been a change in the distribution of SpaceX IPO shares in Korea. SpaceX plans to distribute its IPO shares in Korea through private placement basis in Korea.
- Mirae Asset Securities has applied for a SpaceX public offering volume worth approximately $5 billion (7.5 trillion won).
- The SpaceX IPO could potentially result in some institutional investors reducing their holdings in aerospace related companies in Korea.
8. Aequitas: SpaceX IPO – No Surprises, Watch the Lockup Roll Offs
- SpaceX (SPCX US) an Elon Musk led Space to AI company, aims to raise around US$75bn in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- We looked at its past performance in our previous notes. In this note, we talk about the IPO valautions.
9. Aequitas: Doosan Robotics Placement – Third Block Trade in 2 Months
- Existing shareholders are looking to sell 2.1m shares in a secondary offering of Doosan Robotics (454910 KS).
- This comes on the heels of 2 other block trades done earlier in May this year.
- In this note, we will talk about the placement and run the deal through our ECM framework.
10. Aequitas: SpaceX IPO – Valuations – Now for a Bite of Reality – Retail Euphoria, Index Buying…
- SpaceX (SPCX US) an Elon Musk led Space to AI company, aims to raise around US$75bn in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- We looked at its past performance in our previous notes. In this note, we talk about the additional aspects on valautions.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. SpaceX IPO Valuation Analysis
- SpaceX is preparing to raise at least $75 billion at a valuation of nearly $1.75 trillion to $2.0 trillion.
- My base case valuation of SpaceX is market cap of $1.6 trillion over one year. My valuation sensitivity analysis suggests a valuation range from $1.3 trillion to $1.9 trillion.
- I would not subscribe to SpaceX at a valuation range of $1.75 trillion to $2.0 trillion. Rather, you could purchase Samsung Electronics (005930 KS) at a P/E of 7x, instead.
2. 2025/2026 HK IPO: Cornerstone Investors That Matter
- We study 139 HK listings since 2025 and collected performance data for cornerstone investors, covering both raw cornerstone names and mapped investor entities where available.
- We identify repeat cornerstone investors and sponsors with stronger post-listing track records, focusing on 2W return distribution, dollar-weighted return, deal count, and downside range.
- We further examine investor-sponsor relationships, using both raw co-participation counts and sponsor-adjusted intensity to highlight cornerstone investors and sponsor pairings worth following.
3. [Japan Offering] Rigaku (268A) PE Firm Cleanup Selldown Smaller Than Expected 3mos Ago
- On 21 April, Rigaku Holdings (268A JP) announced a business/capital alliance with larger US SPE metrology firm Onto Innovations. For that, Carlyle sold 27% of their 42% holding to Onto.
- That left 15% to sell to clean up. Shorts are large-ish. The sale price to Onto was well below. An offering should have been imminent. It was.
- On 22 May, they announced a cleanup sale. Rigaku has a big market share in x-ray and growing presence in the booming SPE metrology space. But it’s not cheap.
4. HK IPO Essential Statistics: Quantifying Lock-Up Expiry Overhang
- We studied 43 HK IPO cornerstone deals from the Jan to Nov 2025 listing cohort to measure price action around the IPO+6M lock-up expiry.
- We note that selling pressure from cornerstone selling overhang is deal-size dependent.
- Sponsor mix further refines the screen. Pure international-sponsored deals underperformed other cohorts.
5. Aequitas: SpaceX IPO- A Lighthearted Take on Some of the Claims – Grok Speaks the Truth on Valuation
- SpaceX (SPCX US), an Elon Musk led Space to AI company, aims to raise around US$75bn in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- We will undertake our more serious analysis in the coming days. This note is a lighthearted look at some of the other worldly claims and Grok’s view on SpaceX valuation.
6. Aequitas: GO Inc Pre-IPO – Thoughts on Valuations
- GO (581A JP) a leading taxi app in Japan, aims to raise around US$550m via a secondary selldown in its Japan IPO.
- GO combines app-based taxi hailing with in-taxi technology to meet the needs of both users and partner taxi operators through services such as ride matching, payment processing and advertising.
- We have looked at the company’s past performance in our earlier notes. In this note, we talk about valuations.
7. Aequitas: SpaceX IPO – Space – The Breakthrough Segment but with Low/No Growth
- SpaceX (SPCX US), an Elon Musk led Space to AI company, aims to raise around US$75bn in its US IPO.
- SpaceX is set to be the largest IPO ever. It will also probably end up being one of the most controversial ones given the asking valuations and other worldly promises.
- In this note, we talk about the company background and its ground breaking space segment.
8. Aequitas: GO Inc Pre-IPO – Listed and Unlisted Peer Comparison
- GO (581A JP) a leading taxi app in Japan, aims to raise around US$550m via a secondary selldown in its Japan IPO.
- GO combines app-based taxi hailing with in-taxi technology to meet the needs of both users and partner taxi operators through services such as ride matching, payment processing and advertising.
- We have looked at the company’s past performance in our earlier notes. In this note, we will undertake a peer comparison.
9. Aequitas ECM Weekly (25 May 2026)-SK Hynix, Kokusai, Hulic, GO, Human Made, Powerchip, Quanta, Dajin
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, we had a look at the probable US$10-15bn ADR issuance by SK Hynix (000660 KS)
- There were a number of placements over the past week and we also had a look at some of the planned GDR offerings.
10. Aequitas: CIG Shanghai Placement – Raising Seems Very Opportunistic but Recent Momentum Is Strong
- CIG Shanghai (6166 HK) is looking to raise around US$200m from a primary share placement.
- CIG Shanghai Ltd is a provider of critical infrastructure components for the development of AI. Its portfolio includes high-speed optical transceivers, wireless and broadband access, carrier Ethernet, and edge computing.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.