
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. [Japan Offering] KKR’s Kokusai Cleanup –
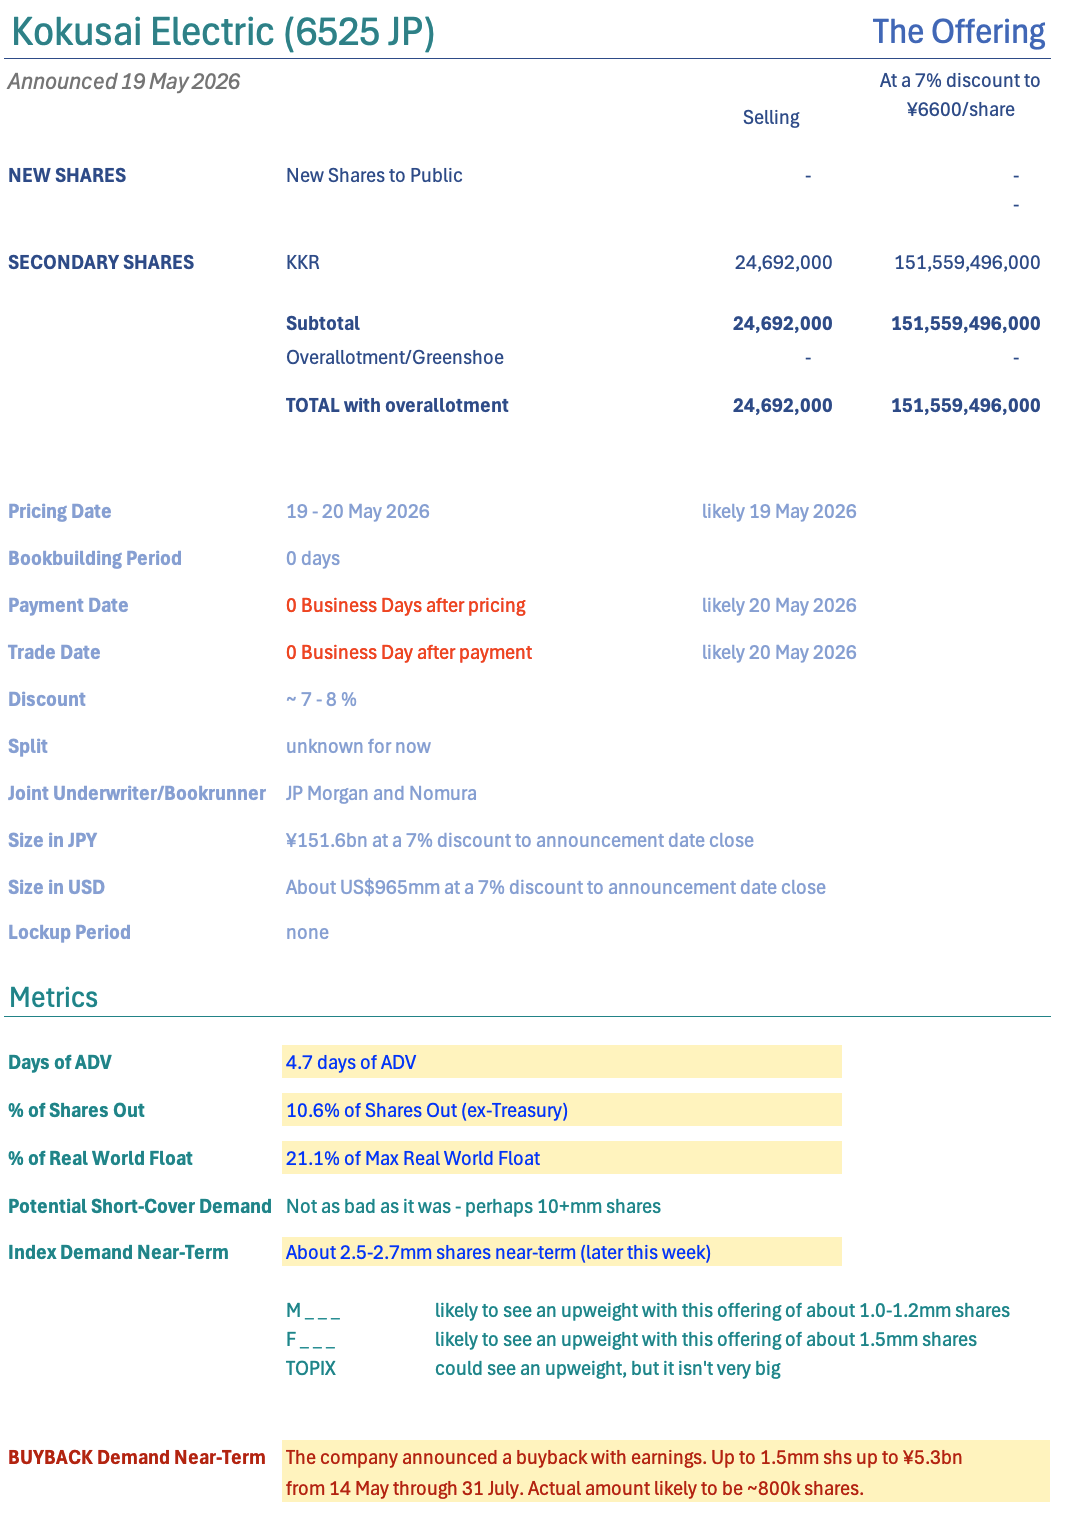
- Today after the close, KKR announced it would be selling its remaining position in Kokusai Electric (6525 JP) of 24.692mm shares or 10.4% of shares out in an overnight offering.
- At the indicated discount, this is a bit under US$1.0bn. No greenshoe. No lockup. They’re done. They did pretty well. AMAT may do a cleanup in the not-distant future.
- This offering is 20% of Max Real World Float. 27+% if Capital isn’t “real world float” today. Index demand is far-dated. Attractive discount for short-term.
2. Initial Thoughts on the SpaceX IPO
- SpaceX now plans to list on the NASDAQ on 12 June. The company is expected to raise $80 billion or more in this capital raise (largest ever in the world).
- After SpaceX, the two other mega IPOs that are expected to be completed in 2H 2026 include Anthropic and OpenAI.
- Although SpaceX’s valuation has not been finalized, it is expected that the SpaceX IPO could fetch about $1.75 trillion to $2.0 trillion, representing P/S (not P/E) of nearly 100x.
3. Aequitas: Kokusai Electric Placement – Past Deals Have Been Mixed but Its a US$1bn Cleanup
- KKR is looking to raise around US$960m through an accelerated secondary offering for around 10% of Kokusai Electric (6525 JP)’s (KE) stock.
- KE had seen a number of selldowns in the past from KKR and Applied Materials, with mixed results.
- In this note, we will talk about the placement and run the deal through our ECM framework.
4. Aequitas: SK Hynix ADR Listing – Part 1 – Early Look at the US$10-15bn Offering
- SK Hynix (000660 KS) (SKH), a leading global memory producer, aims to raise over US$10bn via an ADR listing.
- SKH has confidentially filed for an ADR issuance which could see it potentially launch a raising in July 2026, as per media reports.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
5. Aequitas: SK Hynix ADR Listing – Part 2 – The Quest for a US$1tn+ Valuation
- SK Hynix (000660 KS) (SKH), a leading global memory producer, aims to raise over US$10bn via an ADR listing.
- SKH has confidentially filed for an ADR issuance which could see it potentially launch a raising in July 2026, as per media reports.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
6. GO (581A JP) IPO: The Investment Case
- GO (581A JP) is Japan’s leading ride-hailing platform. It is seeking to raise up to JPY86.7 billion (US$549 million). Pricing is on 1 June, with listing on 16 June.
- It was formed in 2020 through the merger of JapanTaxi, a subsidiary of the major taxi operator Nihon Kotsu Group, and DeNA (2432 JP)‘s mobility division.
- The investment case rests on its leading market position, headroom for growth, strong growth, rising margins, and cash generation.
7. SpaceX (SPCX US): Peeking at the IPO Prospectus of a High Profile Space Infrastructure Company
- SpaceX filed one of the most anticipated IPOs ever, combining dominant space launch, global connectivity, and rapidly scaling AI infrastructure assets.
- Starlink drives profitability and cash flow, while aggressive investments in Starship and AI position SpaceX for massive long-term market expansion.
- SpaceX’s vertically integrated ecosystem spanning rockets, satellites, AI compute, Grok, and X creates a differentiated platform targeting a claimed $28.5 trillion TAM.
8. [Japan Offering] Hulic (3003) Sees Crossholder Selldown in ABO Offering Despite Retail Dominance
- Today after the close, Hulic Co Ltd (3003 JP) announced that several crossholders would sell about ¥30bn of stock in an overnight offering to international investors.
- The Real World Float on this stock is about 27% or so 2.3% is about 8% of Max RWF. Given 75% of MRWF is held by retail, this is surprising.
- The stock is far less volatile than its leverage would suggest but the stock is performing better than a sector suffering from waning investor interest. Could be a good punt.
9. Initial Thoughts on the Changxin Memory Technologies (CXMT) IPO
- Changxin Memory Technologies (CXMT) is getting ready to complete its IPO on China’s Star market in 2H 2026.
- In May 2026, CXMT submitted its updated initial public offering (IPO) prospectus to the Shanghai Stock Exchange’s STAR Market.
- CXMT is seeking to raise 29.5 billion yuan ($4.3 billion) in this IPO in what is poised to be one of the largest IPOs in China in 2026.
10. Aequitas: Rigaku Placement – Cleanup Sale by Carlyle; Jap Leader in Niche Xrays for Semis Inspection
- Carlyle (via Atom Investment) is looking to sell up to ~29m shares in a secondary offering of Rigaku Holdings (268A JP).
- This comes on the heels of Atom doing a block sale to Onto Innovation, whereby Onto acquired 61.1m shares from Atom, on 20th April, 2026.
- In this note, we will talk about the placement and run the deal through our ECM framework.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
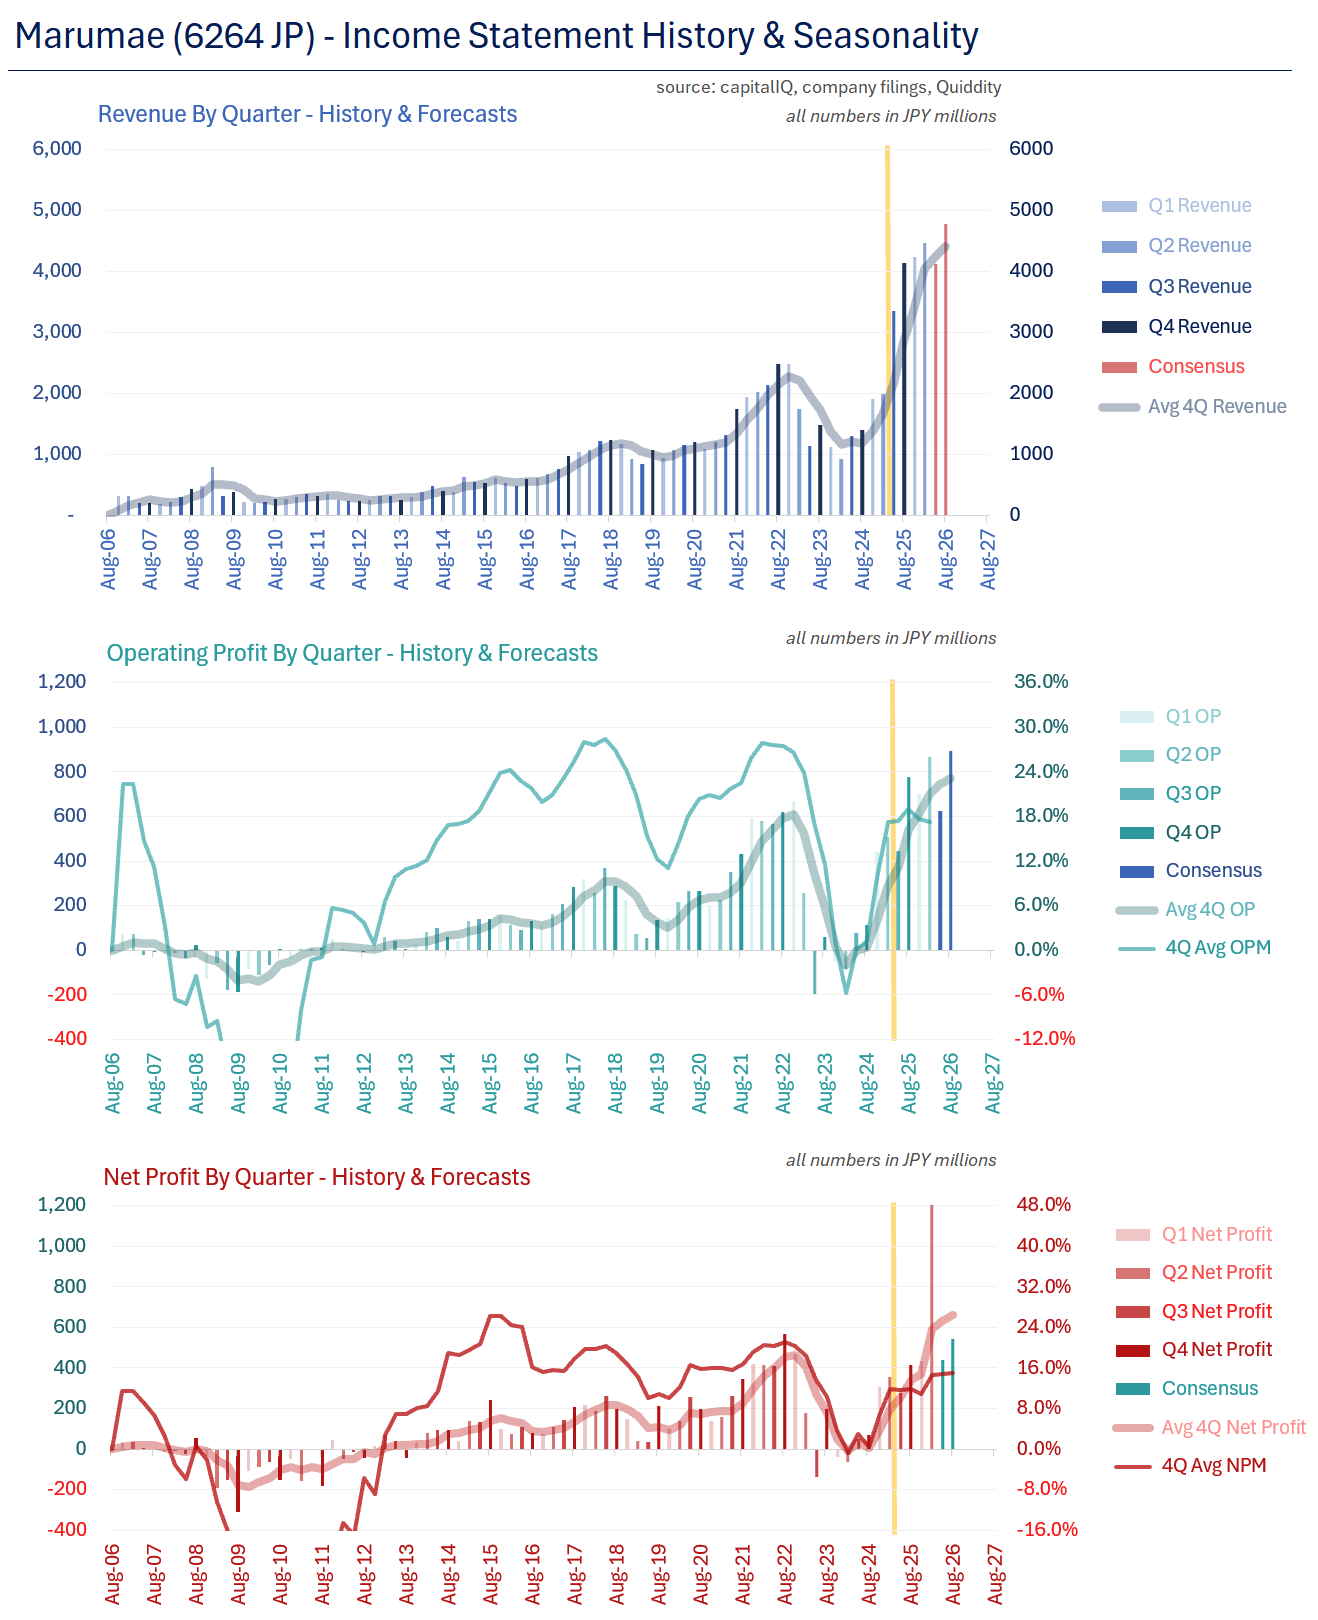
1. [Japan Offering] Marumae (6264 JP) – A Big Opportunistic Offering to Sell Shares at 3+x Revs
- On Friday after the close, after Marumae Co Ltd (6264 JP) shares rose 11% to a record high, the company announced a large primary and secondary offering.
- The company and the CEO will sell up to 4.14mm shares including greenshoe against 25.4mm shares out now and 11+mm shares of Max Real World Float.
- The company is growing this year after last year’s mid-year acquisition of KMAC from JIP. The goal is ¥25bn of sales at 22-23% OPM in Aug28. But it’s big.
2. Robotphoenix (6871) IPO: Worth a Bet
- To raise HK$679.2m of net proceeds, Robotphoenix Intelligent Technology (6871 HK)‘s IPO is small. But this dedicated industrial robotics company is worth a bet.
- Although losses have been increasing for FY23-25, with a 3-year forward revenue CAGR of 35.2%, they should peak in FY27 and start to reduce in FY28.
- We calculate a fair P/S of 13.7-15.5x for FY26, translating into a price of HK$34.3-38.6, or 12.5-26.5% upside from the IPO price.
3. Aequitas: Innolight A/H Listing – Early Look – Peer Comparison and Thoughts on A/H Premium/Discount
- Zhongji Innolight (300308 CH), one of the world’s largest optical transceiver manufacturers, aims to raise around US$5bn in its H-share listing.
- Innolight was the global leader in 2024 in optical modules, with its products being in high demand for data centers.
- In our previous note, we have looked at the company’s past performance. In this note, we will undertake a peer comparison and talk about the likely A/H premium/discount.
4. Big Wave Robotics IPO Valuation Analysis
- My base case valuation of Big Wave Robotics is implied target price of 58,987 won per share, which represents 118% higher than high end of the IPO price range.
- Big Wave Robotics’s sales growth averaged 75.2% per year in 2024 and 2025 versus just 0.1% for the comps in the same period.
- Big Wave Robotics’ operating margin rose from -4.8% in 2024 to 3.2% in 2025. The comps’ average operating margin worsened from -5.4% in 2024 to -21.6% in 2025.
5. Aequitas: Hitachi Construction Machinery Block – Another Selldown by Hitachi Right At Lockup Expiry
- Hitachi Ltd (6501 JP) aims to raise around US$580m via a ~7% stake sale in Hitachi Construction Machinery (6305 JP).
- Hitachi Construction Machinery Co (HCMC) is a Japanese company that designs, manufactures, sells, and services construction and mining equipment.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
6. Aequitas: Shenzhen LDRobot IPO Trading – Strong Retail Appetite, Decent Insti Demand
- Shenzhen LDRobot (1236DES HK) raised around US$112m in its Hong Kong IPO.
- Shenzhen LDRobot (LDR) is a robotics company focused on intelligent robot visual perception technology as well as the development of complete intelligent robots.
- We have looked at the company’s background and pricing in our earlier note, in this note we talk about the trading dynamics.
7. Aequitas:Time Interconnect Placement-Opportunistic Raising but Momentum Is Strong;Last Deal Did Well
- Time Interconnect Technology (1729 HK) is looking to raise around US$300m from a primary share placement.
- TIME Interconnect Technology Limited (TIME) makes cable assembly products, server products, and networking and speciality cables.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
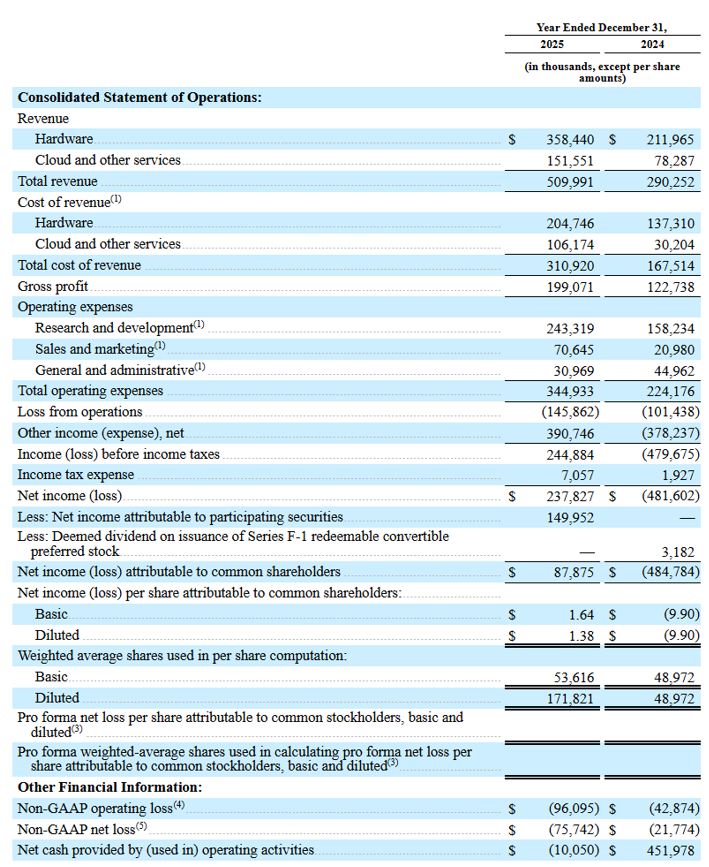
8. Cerebras Systems (CBRS): Upsizes IPO Amid Explosive Institutional Demand, Explosive Debut on Tap
- Cerebras dramatically upsized its IPO after overwhelming institutional and sovereign wealth fund demand drove the deal to become heavily oversubscribed.
- Proprietary wafer-scale AI chips differentiate Cerebras from GPU competitors by improving inference speed and reducing networking bottlenecks.
- Revenue growth, margin expansion, and a $24.6 billion contract backlog support bullish long-term infrastructure scaling expectations.
9. Aequitas ECM Weekly (11 May 2026)- TFC Optical, Tinci, Dajin Heavy, Metis, LDRobot, Lenskart, Pine
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Metis TechBio appears to be ticking the right boxes to be doing well.
- On the placement front, there were selldowns in Doosan Robotics (454910 KS) and Lenskart Solutions (LENSKART IN).
10. Lincoln International (LCLN): Banking Advisory Firm Sets Terms for IPO Seeking up to $2.0b Valuation
- Lincoln International launches IPO on May 20, offering 21.0 million shares at $18–$20, implying ~$1.8–$2.0 billion valuation.
- Expected ~$368 million in net proceeds (up to ~$423 million with greenshoe), primarily used to redeem partner units and repay ~$186 million of term debt.
- Global advisory platform focused on private equity and capital markets, with strong growth, diversified revenues, and leading sponsor advisory rankings.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Cerebras Systems IPO Preview + Impact on Samsung Electronics and SK Hynix
- Cerebras Systems is getting ready to complete its IPO in the U.S. in the coming days. The company is seeking to raise as much as $3.5 billion in this IPO.
- Cerebras is offering 28 million shares at $115 to $125 per share. Main underwriters of this deal have already received indications of interest above $10 billion in potential orders.
- Greater use of Cerebras Systems’ AI chips could negatively impact high-margin HBM business units of SK Hynix and Samsung Electronics.
2. Cerebras Systems Inc. (CBRS): NVIDIA Competitor Sets IPO Terms, Targets Valuation Up to $26 Billion
- Cerebras Systems targets IPO raising up to $3.5 billion, positioning as a high-performance AI infrastructure competitor to NVIDIA.
- Company offers 28 million shares at $115–$125, implying a $24.5–$26.6 billion valuation, debuting Thursday, 5/14.
- Uses proprietary wafer-scale processor delivering up to 15x faster AI inference than GPU-based systems, including NVIDIA benchmarks.
3. Aequitas ECM Weekly (4 May 2026)- CATL, Innolight, Lightelligence, Unimicron, Cofoe, Lenskart, Seres
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Shanghai Xizhi Technology (Lightelligence) (1879 HK) recorded one of the highest demands yet.
- On the placement front, Contemporary Amperex Technology (CATL) (3750 HK) finally got its H-share listing done.
4. Aequitas: Shenzhen LDRobot IPO – Strong Topline Momentum, Still Not Profitable
- Shenzhen LDRobot (1236DES HK) is looking to raise around US$127m in its upcoming Hong Kong IPO.
- Shenzhen LDRobot (LDR) is a robotics company focused on intelligent robot visual perception technology as well as the development of complete intelligent robots.
- In this note, we talk about the company’s past performance and valuations.
5. Pre-IPO Shenzhen LDRobot – The IPO Pricing Is Reasonable
- The competition in the field of visual sensors is particularly fierce. This has led to the dilemma of “price war” for LDROBOT’s robots, which have not yet achieved large-scale profitability.
- The IPO pricing is HK$24-30/share, with market value of HK$8-10 billion, or about RMB7-8.7 billion. If based on 2025 revenue and 2026 revenue forecast, P/S is 9.3-11.6x and 5.23-6.53x, respectively
- Such valuation range based on IPO pricing is also close to peer Robosense and Geekplus. So, we think an overall valuation of about 6-7x P/S is relatively reasonable for LDROBOT.
6. Impact Therapeutics (英派药业) IPO: Mind the Catalysts in 2H2026
- Impact Therapeutics, a China-based biotech, launched its IPO to raise at least USD 116 million via a Hong Kong listing.
- In this note, we look at the deal terms and recap our valuation thoughts for the company.
- We also look at the main reason that caps the return of the deal.
7. Aequitas: Metis Techbio Pre-IPO – Trading at a Fraction of InSilico Despite Twice the Revenue Size
- Metis TechBio (MTB HK) is looking to raise up to US$270m in its upcoming Hong Kong IPO.
- It is a pioneer in AI-empowered nanomaterial innovation, dedicated to the delivery and application of functional payloads across life forms.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
8. Cerebras Systems IPO Valuation Analysis
- My base case valuation of Cerebras Systems is market cap of $41.7 billion or $192 per share, which represents 54% higher than the high end of the IPO price range.
- I estimate Cerebras to generate revenue of $1.1 billion (up 118% YoY) in 2026 and $2.3 billion in 2027 (up 107.9% YoY) in 2027.
- Despite higher losses, I estimate the company’s operating margins to improve from -28.6% in 2025 to -20.8% in 2026, and -13.7% in 2027.
9. Fervo Energy Company (FRVO): Geothermal Energy Meets the IPO Market, Seeking $6.5b Valuation
- Fervo Energy is preparing a major IPO amid rising U.S. power demand, aiming to raise over $1B by offering 55.5 million shares at $21–$24 per share.
- The company plans to use proceeds to fund GeoCluster development, capital expenditures, and operations, supporting expansion of its enhanced geothermal energy platform.
- Strong institutional support includes $350 million in cornerstone investor demand, signaling confidence in Fervo’s EGS technology and long-term scalable clean energy potential.
10. Aequitas: VeriSilicon Microelectronics A/H Listing – Growth Picking up but at the Cost of Margins
- Verisilicon Microelectronics S (688521 CH) (VM), which offers custom silicon solution and semiconductor IP licensing services, aims to raise around US$1bn in its H-share listing.
- According to CIC, VM was the largest IP provider in the Chinese mainland and the eighth-largest globally in terms of IP revenue in 2025.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
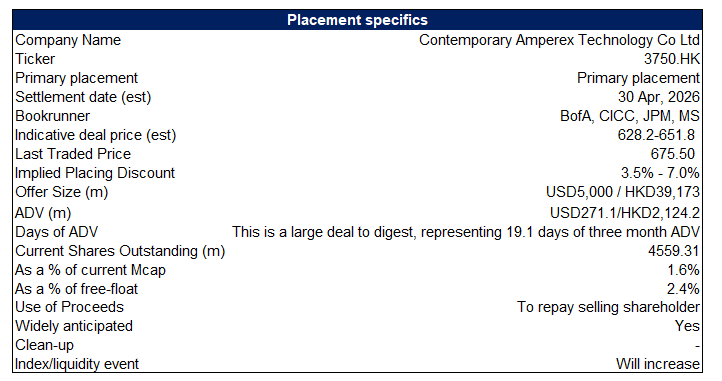
1. Aequitas: CATL H-Share Placement- Will Be Very Well Flagged US$5bn Deal but Last Deal Didn’t Do Well
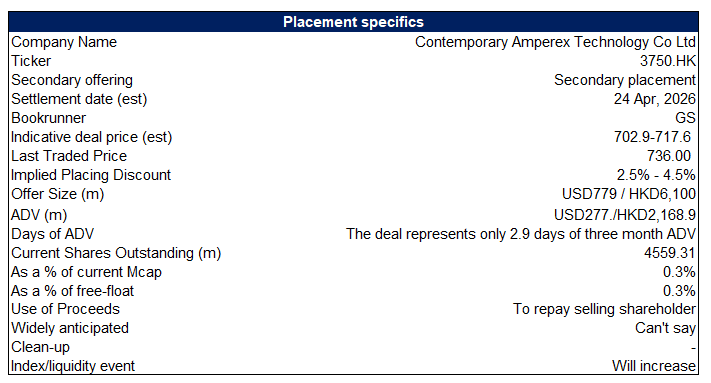
- Contemporary Amperex Technology (CATL) (3750 HK) (CATL) is now looking to raise US$5bn via issuing new shares.
- Two weeks ago we wrote about how CATL could look to raise US$5bn via a primary issuance, since then nearly US$4.5bn worth of secondary deals have taken place.
- In this note, we run the deal through our ECM framework and talk about the deal dynamics.
2. HK A+H IPO 2026 Update: Cornerstone Signal Returns, A-Share Momentum
- We updated our previous HK A+H listing study with deals in March and April.
- International cornerstone participation in the deal is still a strong binary screen.
- A-Share 1-month pre-listing momentum by quartile appears to be a leading indicator.
3. Aequitas: Innolight A/H Listing – Early Look – At US$5bn Could Be Hong Kong’s Largest This Year
- Zhongji Innolight (300308 CH), one of the world’s largest optical transceiver manufacturers, aims to raise around US$5bn in its H-share listing.
- Innolight was the global leader in 2024 in optical modules, with its products being in high demand for data centers.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
4. Mabwell (迈威生物) A+H IPO Trading
- Mabwell raised HKD 1302m (USD 166m) from its global offering and will list on the Hong Kong Stock Exchange on Tuesday April 27th, 2026.
- In our previous note, we looked at the company’s fundamentals and the valuation.
- In this note, we provide an update for the IPO before its trading debut.
5. Aequitas: Cofoe Medical A/H Listing – Discount to HK and International Med-Device Peers
- Cofoe Medical Technology (CFMT HK) is looking to raise up to US$135m in its upcoming Hong Kong IPO.
- It was founded in 2009 (with its brand tracing back to 2007), and as per the prospectus, is a leading provider of home care medical devices in China.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
6. Mobia Medical (MOBI): Peeking at the IPO Prospectus of Med Device Company for Stroke Survivors
- Mobia Medical is a commercial-stage medtech company with FDA-approved Vivistim system, the first therapy targeting chronic ischemic stroke motor recovery via vagus nerve stimulation.
- The company filed for IPO on April 17, backed by major underwriters, and has rapidly scaled revenue from $15.6M (2024) to $32.0M (2025), a 104.8% increase.
- Despite strong growth and over 1,000 implants, Mobia remains loss-making, but targets a large ~$30B U.S. stroke recovery market with limited direct competition.
7. Cosmo Robotics IPO Bookbuilding Results Analysis
- Cosmo Robotics finalized its IPO price at 6,000 won (high end of IPO price range). The IPO offered shares are 4.17 million and the offering amount is 25 billion won.
- A total of 2,257 institutions participated in the bookbuilding process with a competition ratio of 1,140 to 1.
- My base case valuation of Cosmo Robotics is implied market cap of 350 billion won or target price of 10,708 won per share (78% higher than the IPO price).
8. Cofoe Medical Technology (1187 HK) IPO: Priced with Reasonable Potential Gain
- Cofoe Medical Technology (1187 HK) launched its H-share IPO at HK$39.33, valuing the stock at 16.4x PER for FY26, a discount to the global peers.
- Its 3-year EPS CAGR of 18.8% is ahead of the global average, but its market capitalisation of HK$9.3bn is materially smaller.
- Using a 10% PER discount to global peers, it has a fair range of HK$41.8-45.2, which equals a reasonable 27-33% discount to its A-share Cofoe Medical (301087 CH).
9. Aequitas: Hong Leong Asia Placement – Large Deal to Digest but Continues to Ride Tailwinds
- Hong Leong Asia (HLA SP) is looking to raise up to US$114m in a primary offering.
- This is a large deal to digest, representing 28.8 days of ADV and 6.3% of shares outstanding.
- In this note, we will talk about the placement and run the deal through our ECM framework.
10. Aequitas ECM Weekly (27 April 2026)-CATL, Victory Giant, Huaqin, MTT, Lightelligence, CICT, Sany
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, Victory Giant (2476 HK) managed to perform well in HK’s larget listing so far this year.
- On the placement front, Contemporary Amperex Technology (CATL) (3750 HK) witnessed selldowns on its A-share and H-shares line.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: CATL H-Share Placement – Has Seen Nearly US$5bn Worth of Wrong Deals
- Sinopec is looking to raise around US$780m via selling most of its stake in Contemporary Amperex Technology (CATL) (3750 HK)’s H-shares.
- Last week we wrote about how CATL could look to raise US$5bn via a primary issuance, since then nearly US$4.5bn worth of secondary deals have taken place, including this one.
- In this note, we run the deal through our ECM framework and talk about the deal dynamics.
2. Victory Giant H Share Listing (2476 HK): Trading Debut
- Victory Giant (2476 HK) priced its H Share at HK$209.88, raising HK$20,117 million (US$2.6 billion) in gross proceeds. The H Share will be listed tomorrow.
- I discussed the H Share listing in Victory Giant H Share Listing: The Investment Case and Victory Giant H Share Listing (2476 HK): Valuation Insights.
- Victory Giant’s international and retail oversubscription rates were above the median of recent large AH listings. The peers have re-rated, and the AH discount remains attractive.
3. Victory Giant A/H Trading – Set of an AI Pop, Strong Institutional Demand
- Victory Giant Technology -A (300476 CH) (VG) raise around US$2.9bn in its H-share listing.
- VG is one of the global leaders in advanced printed circuit boards (PCB) products for AI and high-performance computing
- We have covered various aspects of the deal in our previous note. In this note, we will talk about the demand and trading dynamics.
4. Aequitas: Lightelligence IPO – Betting On The Next AI Bottleneck
- Shanghai Xizhi Technology (Lightelligence) (LIG HK) is looking to raise around US$330m in its upcoming Hong Kong IPO.
- Lightelligence, otherwise known as Shanghai Xizhi Technology, is a specialist technology company dedicated to the pioneering field of optoelectronic computing, an innovative paradigm that combines photonics (light) and electronics.
- We have looked at the company’s past performance in our previous note. In this note, we talk about valuations.
5. Mabwell (迈威生物) A+H: Moderate Upside but Connect Event Ahead
- Mabwell, a China-based biotech, launched its IPO to raise at least USD 185 million via a Hong Kong listing.
- In this note, we look at the deal terms and provide our thought of valuation for the company.
- We analyzed the reference connect events and assess the risk-reward of the deal.
6. Aequitas ECM Weekly (20 April 2026)-CATL, Victory Giant, Sigenergy, Gpixel, Huaqin, MTT, JST
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, all eyes will on Victory Giant Technology -A (300476 CH) as it completes one of the largest A/H listings.
- On the placement front, there weren’t many large deals given the ongoing market volatility, we did look at the news of a possible raising by CATL(300750 CH).
7. Xizhi Technology (Lightelligence) (1879 HK) IPO: Valuation Insights
- Shanghai Xizhi Technology (Lightelligence) (LIG HK) is a Chinese optical interconnect company. It has launched an HKEx IPO to raise US$319 million.
- I previously discussed the IPO in Xizhi Technology (Lightelligence) IPO: The Investment Case.
- Despite my cautious view of the fundamentals, my DCF sensitivity analysis suggests the IPO price range is reasonable. The presence of blue-chip cornerstones will help sentiment.
8. X-Energy Inc. (XE): Ark Invest Anchoring Nuclear Reactor Tech IPO
- X-Energy IPO shows strong demand with ARK anchor order and oversubscribed books ahead of expected market debut.
- Positioned to benefit from AI-driven power demand using SMR technology and proprietary nuclear fuel solutions.
- Backed by blue-chip investors and DOE funding, but remains pre-commercial with significant and widening net losses.
9. Shanghai Sunmi Technology (6810 HK) IPO: Doesn’t Stand Out
- While Shanghai Sunmi Technology (6810 HK) is a leader in Business Internet of Things (BIoT) solutions, its IPO size is relatively small with net proceeds of HK$908.7m.
- We forecast its 3-year EPS CAGR at 26.4%, driven by its comprehensive customer coverage and geographical presence, and it will continue to see a positive margin trend.
- At HK$24.86, it is priced at 21.4x FY26 PER, vs. 13.2x for the peer average. Its better growth has been discounted, making the IPO’s risk-reward payoff unfavourable.
10. Aequitas: Shanghai Sunmi Tech IPO – Slowing Growth Doesn’t Justify Premium
- Shanghai Sunmi Technology (6810 HK) is looking to raise around US$135m in its upcoming Hong Kong IPO.
- Shanghai Sunmi Technology Co., Ltd. (SSTC) is a global Business Internet of Things (BIoT) solution provider. Its solutions integrate smart hardware, software, and data insights to enable digital transformation.
- In this note, we talk about the company’s past performance and valuations.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
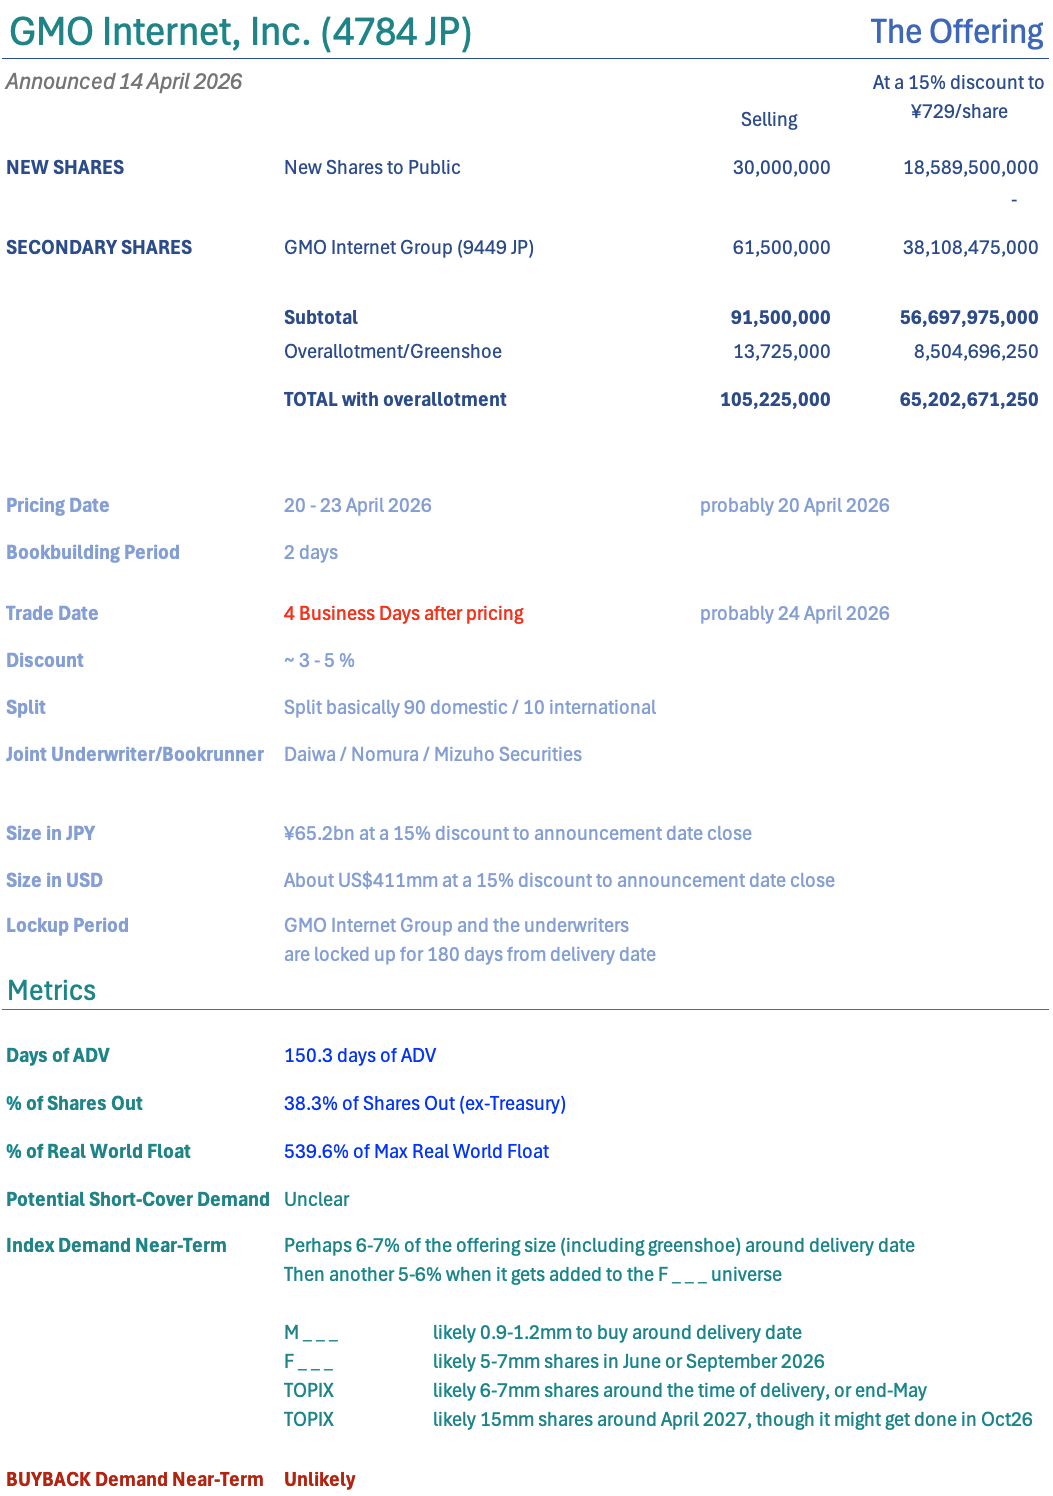
1. [Japan Offering] GMO Internet (4784) – A New Offering at a LOT Lower Price
- On 1-Jan-2025, the new GMO Internet (4784 JP) (formerly GMO Ad Partners) was reborn. It was basically a RTO (of parent GMO’s data centre business) with a new Prime Listing.
- Float was tiny. Maybe 2%. Then there was a TOPIX inclusion. The stock was squeezed from ¥1,200 to ¥3,100 (was ¥350 when the plan was announced in mid-2024).
- An offering was announced last year at ¥3,100. Nobody wanted it. The stock fell 80%, rebounded a bit. Now we have a new offering. But it’s still rich.
2. Hynix ADR Listing Timeline and Size: SK Leadership Pushing Really Aggressive Execution
- Hynix is pushing an accelerated ADR timeline targeting June to July, compressing SEC review and roadshow to pull listing timing forward as much as possible.
- SK leadership pushing larger SK Hynix ADR, open to SK Square’s Hynix stake dilution below 20 percent, likely via secondary ADRs with EB structuring in play.
- Early disclosure on SK Hynix issuance and SK Square monetization keeps overhang, as larger ADR and EB flows may drive volatility and short pressure on Hynix.
3. Aequitas: CATL Possible H-Share Issuance – Could Be an Opportunistic US$5bn Raising in Hong Kong
- Contemporary Amperex Technology (CATL) (3750 HK) could look to raise another US$5bn in Hong Kong via a placement, as per media reports.
- CATL had raised around US$5.2bn in its H-share listing in May 2025 and the stock is up 160% since.
- In this note, we will talk about the possible deal dynamics.
4. Victory Giant Hong Kong Public Offering
- On 13 April, Victory Giant (2476 HK) launched a Hong Kong public offering that seeks to raise up to HK$17.5 billion ($2.2 billion).
- The company is offering 83.35 million shares in Hong Kong at up to HK$209.88 each. The company is expected to start trading in Hong Kong on April 21.
- Victory Giant ranked first globally in terms of sales revenue in the PCB market for AI and high-performance computing in 1H 2025 with a 13.8% market share.
5. Victory Giant Technology Hong Kong IPO Valuation Analysis
- According to my valuation analysis, it suggests base case valuation of HK$378 which is 80% higher than the initial offer price of HK$209.88.
- One could argue that the company deserves to trade at even higher valuation multiples than the comps, given its higher sales growth and operating margins.
- To value Victory Giant (2476 HK), I used three comps including Zhen Ding Technology Holding (4958 TT), Unimicron Technology (3037 TT), and Samsung Electro Mechanics Co, Ltd. (009150 KS).
6. Victory Giant H Share Listing (2476 HK): Valuation Insights
- Victory Giant (2476 HK), the world’s leading PCB manufacturer for AI and high-performance computing, has launched an H Share listing to raise US$2.2 billion.
- I discussed the H Share listing in Victory Giant H Share Listing: The Investment Case.
- The proposed AH discount of 36.8% (based on the 10 April A Share price) is attractive. Overall, I would participate in the listing.
7. Curator’s Cut: Soft Commodities’ Hard Truths, Pricing China’s Hi-Tech & Sumitomo Pharma’s Placement
- Welcome to Curator’s Cut – a fortnightly roundup of standout themes from the 1,400+ insights published on Smartkarma.
- In this cut, we evaluate the supply-side risks to agri-commodities, sift through a flurry of China hard-tech IPOs, and unpack Sumitomo Pharma’s massive share placement.
- Want to dig deeper? Comment or message with the themes you’d like to see highlighted next.
8. Victory Giant Technology (2476 HK) IPO: It Will Be Hot
- Victory Giant (2476 HK)‘s H-share IPO is expected to generate keen interest, given its leadership position in the PCB market in the field of AI and high-performance computing.
- Both its business segment and geographical exposure are diversified. Its 3-year EPS CAGR of 61.5% is the second highest among HA IPOs since 2025.
- The IPO valuation of 18x FY26 PER is at a steep discount to peers. It justifies a 0-10% discount to its A-share, meaning a fair H-share price of HK$305.9-341.6.
9. Aequitas: Victory Giant A/H Listing – Attractive Pricing for AI Play
- Victory Giant Technology -A (300476 CH) (VG) is looking to raise at least US$2.2bn in its H-share listing.
- VG is one of the global leaders in advanced printed circuit boards (PCB) products for AI and high-performance computing.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the IPO pricing.
10. Huaqin H Share Listing (3296 HK): Valuation Insights
- Huaqin (3296 HK), the world’s largest consumer electronics original design manufacturer, has launched an H Share listing to raise US$580 million.
- I discussed the H Share listing in Huaqin H Share Listing: The Investment Case.
- Given my previously discussed bearish investment case and the unattractive AH discount, I would avoid the H Share listing.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
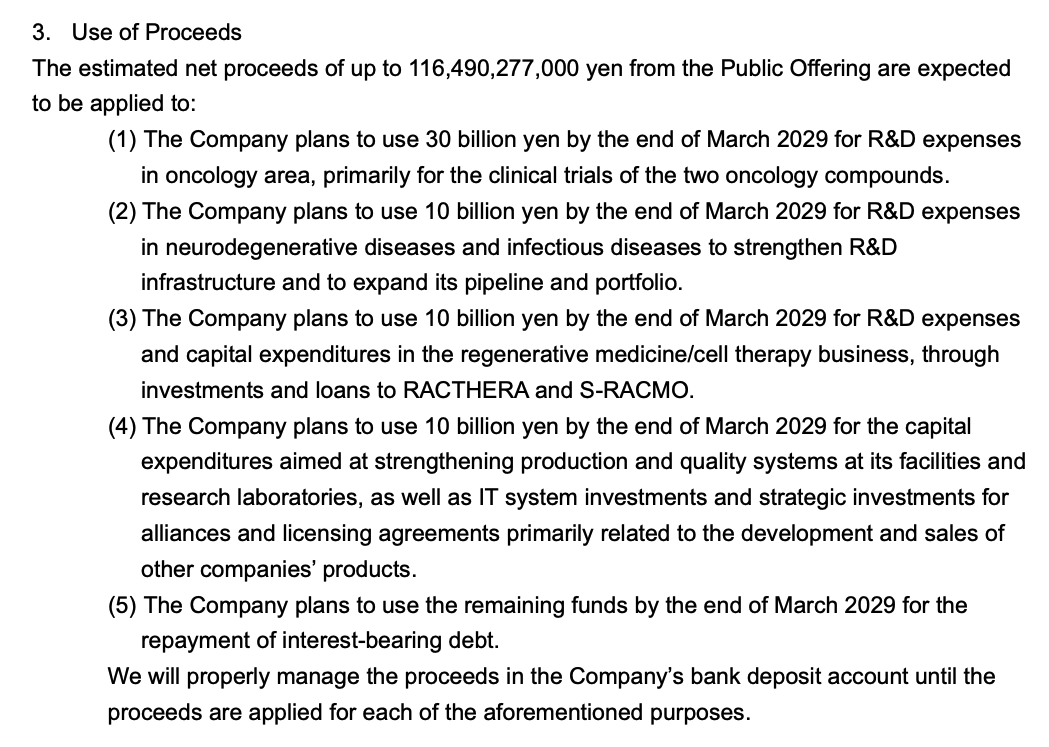
1. [Japan Offering] Sumitomo Pharma (4506) Issuing ¥100bn of New Shares for Investments
- Sumitomo Pharma (4506 JP) is coming out of its earnings funk from 2023-2024. The stock has risen sharply off lows. Now the company has put out its hat.
- They want to sell 59.0mm shares (against 385mm or so now) which is about 15% of shares out, and a whopping 65+% of (active voting rights) Max Real World Float.
- There is index impact near-term and further out, and there are shorts to be covered. But this is heavily dilutive to the active Max Real World Float.
2. [Japan Offering] Union Tool (6278 JP) Issuing ¥30bn of Shares For Investment Purposes
- On Monday 6 April, Union Tool Co (6278 JP) announced they were offering ¥30bn of Treasury shares to fund investment. It is a 28% increase in equity.
- Union Tool is rich in terms of net cash+securities+OPCF, it didn’t need to issue shares to fund the capex, so it feels like a “sell shares at the top” strategy.
- Guidance seems conservative for the market environment but capacity utilisation is high, and they are investing for a higher run-rate going forward. Seems expensive but AI is a new paradigm.
3. Aequitas: Samsung Electronics Placement -Final Inheritance Payment Selldown; 1Q26 Beats Estimates
- Hong Ra-hee, the widow of former Samsung Group chairman Lee Kun-hee, is looking to sell around U$2bn worth of Samsung Electronics (005930 KS) shares via a secondary placement.
- The heirs have been paying inheritance tax since April 2021, and the final payment, due April 2026, is likely to be this sale.
- In this note, we will talk about the placement and run the deal through our ECM framework.
4. Aequitas ECM Weekly (7 April 2026)-Victory Giant, Huaqin, Sigenergy, Manycore, WeWork, MTT, AVATR
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, a number of companies are lininig up in Hong Kong to launch their IPOs soon.
- On the placement front, there weren’t many large deals given the ongoing market volatility.
5. Pre-IPO Sigenergy Technology (PHIP Updates) – The Strength and the Concerns
- The core of Sigenergy’s business model is focusing on segmented tracks, exploring overseas high-end home markets through highly integrated innovative products, and adopting a global distribution model.
- To seize the market and cope with competition, Sigenergy may lower the price of SigenStor.As raw material costs fluctuate, high gross margin is difficult to maintain and would fall back.
- By referring to the valuations of peers during their upwrd phase, considering the high growth/high risk of Sigenergy, and based on our forecast, 12-18x P/E could be a relatively reasonable range.
6. Sigenergy IPO: The Investment Case
- Sigenergy (SIG CH), a global leader in distributed energy storage system (DESS) solutions, is pre-marketing an HKEx IPO to raise around US$500-600 million.
- The flagship product is SigenStor, which is the first ESS solution in the industry to combine five-in-one functionalities and among the first to adopt stacking technologies.
- The investment case rests on the market positioning, rapid growth, margin expansion, declining cash burn and modest leverage.
7. Sigenergy (6656 HK) IPO: Go for It!
- Sigenergy Technology (6656 HK), as a leader in distributed energy storage system solutions, has an impressive profit record and is forecast to sustain.
- Sales of its flagship product, SigenStor, surged 314.3% in 2M26, and confirmed orders reaching Rmb3.8bn at end-Feb. We expect the 3-year EPS CAGR at 41.7%.
- The IPO price (HK$324.2) translates into 12x FY26F PER, cheaper than 20.8x for the HK peers. At a 20-30% discount to peers, its fair value range implies 21-39% upside.
8. Manycore Tech (68 HK) IPO: The Investment Case
- Manycore Tech (68 HK), a leading spatial design software provider, has launched an HKEx IPO to raise US$156 million.
- The software product suite centres on Kujiale, a cloud-native spatial design software targeting the Chinese market. It allows users to create 3D renderings of home interior layouts.
- The investment case is bearish due to the tepid growth, stagnant market share, early indications of customer retention issues and cash burn.
9. Sigenergy (6656 HK) IPO: Valuation Insights
- Sigenergy Technology (6656 HK) is a global leader in distributed energy storage system (DESS) solutions. It has launched an HKEx IPO to raise US$562 million.
- I previously discussed the IPO in Sigenergy IPO: The Investment Case.
- In this note, I present my forecasts and valuation. My analysis suggests that the IPO price is attractive.
10. Aequitas: Sigenergy Pre-IPO – Strong Cornerstone Book; Relatively Cheap
- Sigenergy Technology (6656 HK) is looking to raise up to US$563m in its upcoming Hong Kong IPO.
- It is a market leader in the stackable all-in-one DESS solutions market, a nascent industry.
- In this note, we examine the IPO dynamics, and look at the firm’s valuation.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
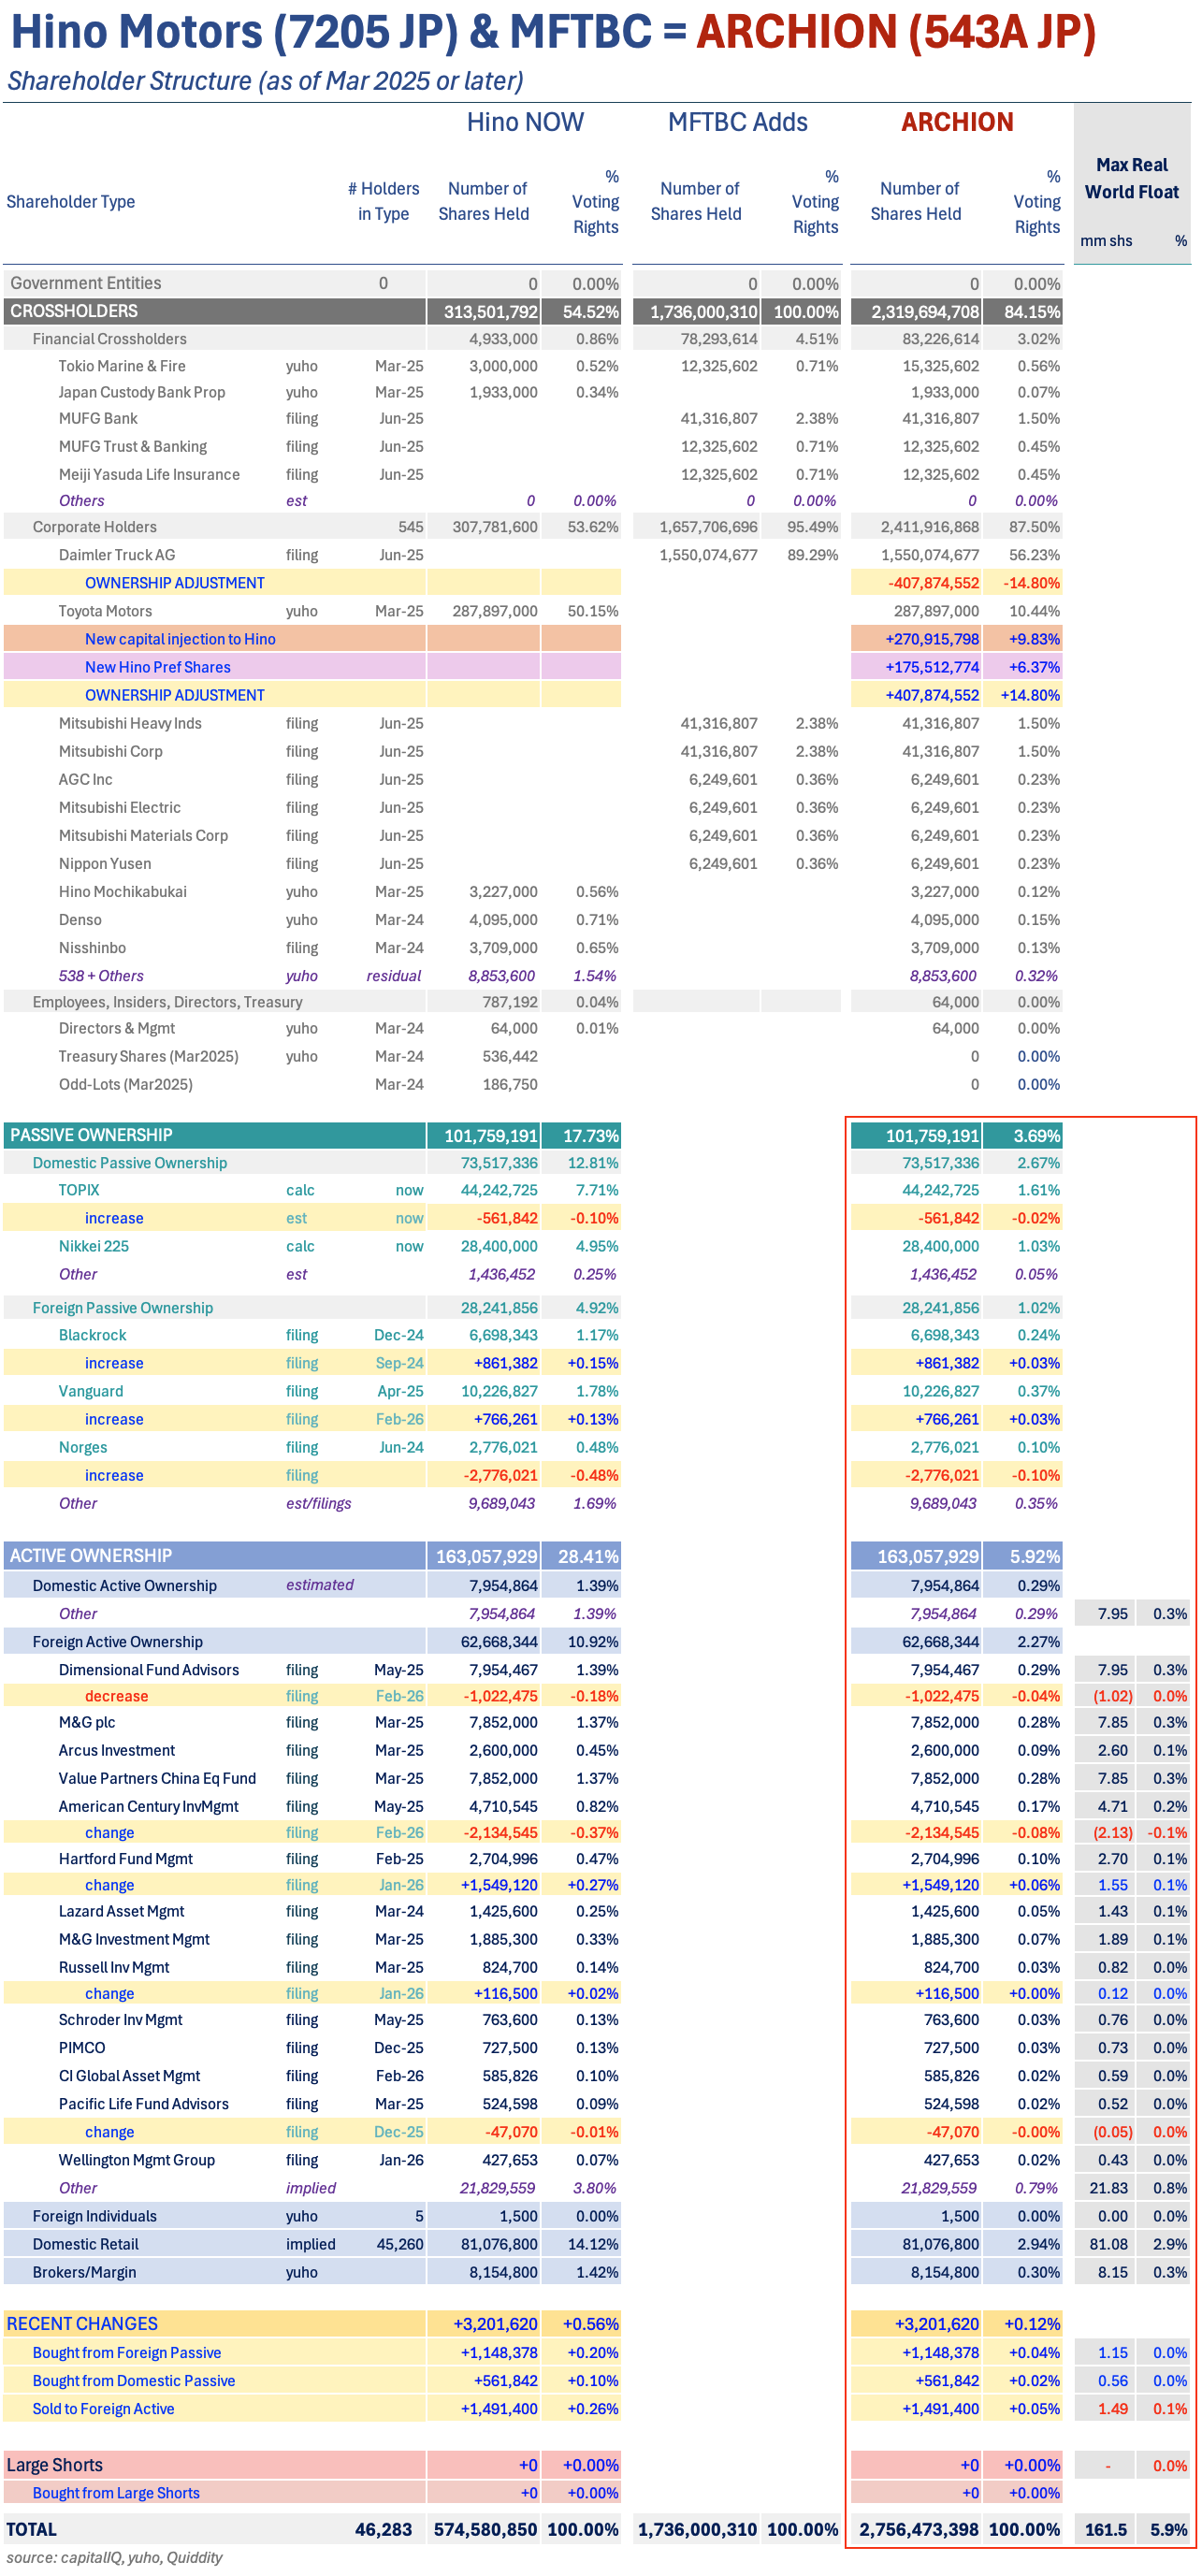
1. [Japan M&A/ECM] ARCHION INCOMING!
- On April 1, the merger of Hino Motors Ltd (7205 JP) and Mitsubishi Fuso Truck & Bus Co (MFTBC) is effective where MFTBC gets injected into a Surviving Entity ARCHION.
- Currently, “minorities” own 49.7% of Hino Motors but that includes cross-holders. Active holders and passive holders will own 5.7% and 3.9%, respectively. Daimler and Toyota 83%, crossholders 7+%.
- Daimler and Toyota need to sell down to 25% each. The cross-holders will want to sell too. This will mean a BIG offering “as soon as is reasonable.” A re-IPO.
2. Aequitas: Victory Giant A/H Listing – PHIP Updates and Thoughts on A/H Premium
- Victory Giant Technology -A (300476 CH) (VG) is now said to be looking at raising up to US$2bn in its H-share listing.
- VG is one of the global leaders in advanced printed circuit boards (PCB) products for AI and high-performance computing.
- We have looked at the company’s past performance in our previous note. In this note, we talk about the recent updates and likely A/H premium.
3. Victory Giant H Share Listing: The Investment Case
- Victory Giant Technology -A (300476 CH), the world’s leading PCB manufacturer for AI and high-performance computing, is pre-marketing an H-Share listing to raise around US$2 billion.
- Victory Giant is an AI hardware play and a core supplier to NVIDIA Corp (NVDA US), as it is one of the few companies capable of mass-producing high-end HDIs.
- The investment case is bullish due to Victory Giant’s leading market share, rapid growth, rising margins, low leverage and undemanding valuation.
4. Huaqin H Share Listing: The Investment Case
- Huaqin Technology (603296 CH), the world’s largest consumer electronics original design manufacturer, is pre-marketing an H-Share listing to raise around US$1 billion.
- Huaqin ranked as the largest consumer electronics ODM globally in 2024, with 22.5% market share.
- The investment case is bearish as Huaqin’s rapid growth has come at the cost of margins and cash generation. Also, the valuation is unattractive compared to peer multiples.
5. Unitree Robotics Valuation Update: Bull-Case DCF Frames IPO Upside As Onshore Listing Nears
- My bull-case 10-year DCF, based on stronger humanoid commercialization, faster revenue scaling, sustained growth and profitability expansion over time, suggests upside potential ahead of onshore listing.
- While the robotics stock valuations are high, I note the companies with long-term growth opportunities that are investing in growth with higher expenses can still maintain high multiples for years.
- Using my 2026 estimates, Unitree Robotics should trade post-IPO at an EV of ~19x revs, a premium to high-growth HK-listed robotics peers, including Shenzhen Dobot and UBTech Robotics.
6. Pre-IPO Victory Giant Technology (PHIP Updates) – Some Points Worth the Attention
- Victory Giant has delivered an impressive 2025 results. However, the profit in the second half of the year showed a slight downward trend compared with 25Q2.
- AI and high-performance computing business is still expected to maintain a growth rate of 40%-50% in 2026. The growth rate will gradually slow down to 20%-30% from 2027 to 2028.
- An IPO price that is 20% to 30% lower than A-share is a rational range. 25x P/E based on 2026 forecast could be comfortable, which provides certain margin of safety.
7. Aequitas: Tata Capital IPO Lockup Expiry – Will Have to Sell US$1.4bn of Stock but Has More Time Now
- Tata Capital Limited (TATACAP IN) raised around US$1.7bn in its IPO in October 2025. The lockup on its promoter and pre-IPO investors is set to expire soon.
- Tata Capital Limited (TCL) is the flagship financial services company of the Tata group and a subsidiary of Tata Sons Private Limited.
- In this note, we will talk about the lockup dynamics and possible placement.
8. Aequitas ECM Weekly (30 March 2026)-Huayan, Diagens, Tong Ren, Epiworld, Pateo, Capitaland, Seoul Gu
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, three mid-cap companies are set to list later today in Hong Kong.
- On the placement front, there weren’t many large deals given the ongoing market volatility.
9. Pre-IPO Manycore Tech – (PHIP Updates) – The Business Model, the Concerns and the Outlook
- The core business model of Manycore is “cloud-native SaaS subscription + spatial intelligence solutions”, and it is transforming from a simple software fee model to a platform-based capability output model.
- Manycore’s moat is built on the basis of the triad of “technology + data + leading scenarios”, but the core business is strongly correlated with the real estate cycle.
- 8-10x P/S can be regarded as a relatively conservative lower limit for valuation, while 12-15x P/S can be considered as an upper limit for valuation when market sentiment is optimistic.
10. Arxis Inc. (ARXS): Peeking at the IPO Prospectus of a PE Backed Aerospace Components Company
- Arxis Inc designs mission-critical, IP-protected electronic and mechanical components for aerospace, defense, and industrial markets, with highly diversified customers and strong engineering differentiation.
- Backed by Arcline Investment Management since 2019, Arxis has completed 30+ acquisitions and filed for a March 2026 IPO with leading global underwriters.
- Strong revenue growth ($424.5M to $1.59B from 2023–2025) and a profitable 2025 support its platform-driven “layer cake” growth model across defense and aerospace.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
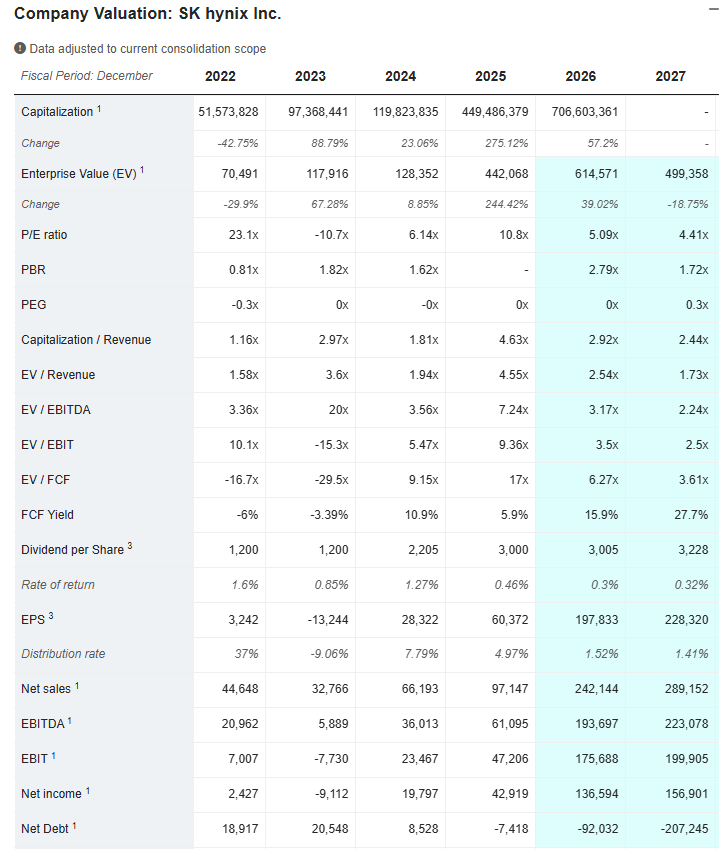
1. SK Hynix To Announce ADR Listing at AGM? (Positives of ADR Listing Vs Negatives of Share Dilution)
- According to numerous local media sources, SK Hynix is pursuing the issue of ADRs. Listing of ADR could get announced at its AGM on 25 March.
- The issuance is expected to represent approximately 2.4% of the total outstanding shares which is now worth 16 trillion won (US$10.7 billion).
- All in all, I think that the positives (reduce valuation gap with global peers and inclusion in major global indices) clearly outweigh the negatives (a small amount of share dilution).
2. Structural Features of Hanwha Solutions Rights Offering
- Deal size is the key swing factor: KRW 2.1tn rights offering, 20% discount, 0.335 allocation ratio. Even with Hanwha Corp 120% take-up, KRW 1.2tn still hits the market.
- Tighter 1st-to-2nd pricing gap reduces discount volatility, setting up a cleaner rights arb, but Hanwha Solutions’ thin SSF liquidity means short hedges will need a creative approach.
- FSS is reviewing the deal over use of proceeds, but with Hanwha Corp pre-signaling full oversub, regulatory risk looks low and unlikely to block the rights offering.
3. Hanwha Solutions: Rights Offering Capital Raise of 2.4 Trillion Won
- On 25 March, Hanwha Solutions (market cap of 6.3 trillion won) announced that it plans to conduct a rights offering capital raise of nearly 2.4 trillion won (US$1.6 billion).
- I have a Negative View of this rights offering capital raise mainly due to excessive dilution concerns of existing shareholders. In addition, the company has poor balance sheet.
- The company’s core solar and chemical businesses are experiencing tough competition and its profitability (operating margin) worsened in 2025. Valuations are also not cheap (EV/EBITDA of 20.1x).
4. Aequitas: Guangdong Huayan Robotics IPO – Some Doubts but Relative Pricing Isn’t Expensive
- Guangdong Huayan Robotics (GHR), a collaborative robotics company, is looking to raise around US$175m in its Hong Kong IPO.
- GHR is a collaborative robotics (cobot) company engaged in the development, manufacturing and sale of cobots and core motion components for industrial automation applications.
- We have looked at the company’s past performance in our previous note. In this note, we talk about valuations.
5. Aequitas: Capitaland Ascendas REIT Placement – Logistics and Data Center Acquisition; DPU Accretive
- CapitaLand Ascendas REIT (CLAR SP) is looking to raise up to US$700m via a share placement and preferential offering, to acquire properties in Singapore, Spain, Japan and the US.
- Shareholders will also be eligible for an additional preferential offering with record date on 1 April
- In this note, we comment on the deal dynamics and run the deal through our ECM framework.
6. Aequitas ECM Weekly (23 March 2026)-Samsung, Kingboard, JRE, Chery, Zijin, Butong, Delton, NSing, FS
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, a wave of smallish HK IPOs was launched late in the week.
- On the placement front, deals have started to flow in across the region after a somewhat quiet war and earnings driven rest.
7. Aequitas: Sieyuan Electric A/H Listing – Power Infrastructure Build-Out Beneficiary
- Sieyuan Electric Co (002028 CH) (SE), a power transmission and distribution equipment manufacturer and integrated power and energy solution provider, aims to raise around US$1bn in its H-share listing.
- SE ranked eighth among international enterprises, fifth among domestic enterprises and third among domestic non-state-owned enterprises, with a market share of 3.5% in 2024.
- In this note, we look at its past performance and other deal dynamics that might impact the listing.
8. Pre-IPO Victory Giant Technology (A/H Listing) – The Business and the Outlook
- Victory Giant’s quarterly growth in 25Q4 witnessed a significant QoQ decline, as the Company’s performance is subject to short-term disturbances caused by product cycles and the bargaining power of customers.
- Although some delayed orders in 25Q4 may be recognized as revenue in 26Q1, leading to a possible sequential improvement, there would be no explosive growth rebound in the short term.
- The market would price in Victory Giant’s “high purity of AI business + steep growth of performance + big profit elasticity”.20-25x P/E based on 2026 forecast could be comfortable range.
9. Unitree Robotics IPO Preview: Path To Market Leadership and The Next Wave of Robotics
- Unitree Robotics, a global leader in high-performance robotics, focusing on humanoid and quadruped robots, is expected to IPO on the Shanghai’s STAR Market in April.
- The founder-led robotics unicorn has established a leading position in quadruped robots and is rapidly transitioning into humanoid robotics, which is expected to be the next major growth vector.
- Unitree Robotics has delivered 3+ years of exceptional revenue growth with a 80%+ CAGR and an elite gross margin profile supporting profitability – something nearly unheard of among robotics peers.
10. Aequitas: Smart More Inc Pre-IPO Tearsheet
- SmartMore Inc (1811514D CH) (SM) plans to raise around US$300m in its upcoming Hong Kong IPO. The deal will be run by CICC, DB and MS.
- SM is an AI company offering robots, edge AI sensors, and agentic software systems.
- It is the largest industrial AI agent provider in China in terms of revenue in 2025, as per CIC.
This weekly newsletter pulls together summaries of the top ten most-read Insights across Equity Capital Markets on Smartkarma.
Receive this weekly newsletter keeping 45k+ investors in the loop
1. Aequitas: Zijin IPO Lockup- Some Cornerstones Could Be Sellers in the US$4bn Lockup Release
- Zijin Gold (2259 HK) raised US$3.2bn from its Hong Kong IPO in September 2025 via a primary offering of HKD71.59/share in its IPO.
- The lockup on its cornerstone investors is set to expire soon.
- In this note, we will talk about the lockup dynamics and possible placement.
2. GenFleet Therapeutics IPO Lockup – A Minor Prelude to a Much Bigger Release
- GenFleet Therapeutics (GFT) raised around US$240m in its Hong Kong IPO in September 2025. The lockup on its cornerstone investors is set to expire soon.
- GFT is a biopharmaceutical company focused on developing novel treatment options in the fields of oncology.
- In this note, we will talk about the lockup dynamics and possible placement.
3. Pre-IPO Delton Technology (1989 HK) – The IPO Pricing Is Attractive
- The core of Delton’s business model lies in JDM that deeply integrates with the computing power trend, which would enable it to achieve highest profit elasticity during industry’s growth period.
- Delton’s weakness include scale and financial stability. Compared with peers, its cash flow and customer structure are relatively fragile. The significant increase in copper prices/commodities may directly erode Delton’s profits.
- We think the IPO pricing is reasonable. For cornerstone investors and long-term value investors, if the final pricing is at HK$71.88 or lower, there would be decent upside potential.
4. Aequitas: Kingboard Laminates Placement – Stock Has Done Exceedingly Well, Last Deal Went Great
- Holdco Kingboard Holdings (148 HK) is looking to sell around a 3.8% stake in Kingboard Laminates Holdings (1888 HK) to raise up to US$357m via a secondary selldown.
- Kingboard Laminates Holdings Limited is a manufacturer of laminates used in printed circuit boards, and is one of the world’s largest suppliers to the electronics industry.
- In this note we talk about the deal dynamics and run the deal through our ECM framework.
5. Aequitas ECM Weekly (16 March 2026)- Past A/H Trends, Delton, Raajmarg, Ringpai, FS.com, Everdisplay
- Aequitas Research’s weekly update on the IPOs, placements, lockup expiry and other ECM linked events that were covered by the team over the past week.
- On the IPO front, most of the listings this week didn’t do much.
- On the placement front, given the market volatility, there weren’t any large deals. We did look at some of the upcoming lockup expiries.
6. Aequitas: Samsung Electronics US$1bn Technical Selldown Likely, past Deals Haven’t Done Much
- Samsung Life Insurance (032830 KS) and Samsung Fire & Marine Insuranc (000815 KS) are likely to sell around U$1bn worth of Samsung Electronics (005930 KS) shares via a block deal.
- The selldown is being undertaken to meet regulatory requirements for shareholding.
- In this note, we will talk about the placement and run the deal through our ECM framework.
7. Aequitas: Guangdong Huayan Robotics Pre-IPO – The Positives – Fast Growth
- Guangdong Huayan Robotics (GHR), a collaborative robotics company, is looking to raise around US$200m in its upcoming Hong Kong IPO.
- GHR is a collaborative robotics (cobot) company engaged in the development, manufacturing and sale of cobots and core motion components for industrial automation applications.
- In this note, we talk about the positive aspects of the deal.
8. Didi Q425 Results | China Biz Hums, International Losses Explode | Before an IPO, Didi Needs a Plan
- Shocking performance from International segment caused large Adj EBITA loss in Q425
- The core Chinese ridehailing business continues to grow and generate improving margins
- Ahead of a potential HK IPO, Didi must offer a pathway towards International recovery
9. Aequitas: Guangdong Huayan Robotics Pre-IPO – The Negatives – Most of the Revenue Comes from Related
- Guangdong Huayan Robotics (GHR), a collaborative robotics company, is looking to raise around US$200m in its upcoming Hong Kong IPO.
- GHR is a collaborative robotics (cobot) company engaged in the development, manufacturing and sale of cobots and core motion components for industrial automation applications.
- In this note, we talk about the not-so-positive aspects of the deal.
10. Chando Global Pre-IPO – The Positives – Well Known Brand
- Chando Global Limited (CG) is looking to raise at least US$500m in its upcoming Hong Kong IPO.
- Chando Global is a multi brand cosmetics company in China. It was China’s third-largest domestic cosmetics group, by retail sales in 2024, according to Frost & Sullivan (F&S).
- In this note, we talk about the positive aspects of the deal.